
 Russia Home Furniture Market | 2026-2036
Russia Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Home Furniture Market Analytics
Urban apartment dwellers is restructuring how Russian consumers furnish compact living spaces, shifting preference toward modular sofas and transformable beds that maximize square meter efficiency. IKEA leverages its flat-pack logistics network to sustain penetration across tier-one and tier-two cities despite operational complexities. BOROVICHI-MEBEL CJSC anchors its position through solid wood dining and bedroom collections that compete on durability perception. Furniture Factory Shatura OJSC differentiates via vertical control over particleboard supply, extending cost stability into mid-market table and storage lines.
Russia home furniture encompasses movable articles designed for residential interior spaces, typically constructed from solid timber, engineered wood panels, metal framing, or upholstered composites with foam and textile layering, and manufactured through CNC routing, veneer pressing, upholstery stapling, and surface finishing processes to provide seating, sleeping, storage, and work surface functionality. Wood material segments occupy the largest value share due to domestic birch and pine availability, though upholstered categories command premium margin pools in metropolitan showrooms. Modern design style leads volume in new-build apartment fittings, while classic styling sustains replacement demand in established owner-occupied housing.
Russia's national standardization body and the Eurasian Economic Commission enforce technical regulations on furniture safety, flammability, and formaldehyde emissions that shape import thresholds and domestic factory upgrade cycles. The country's sanitary-epidemiological framework adds certification layers for upholstered goods containing synthetic foams and adhesives, filtering market access for non-compliant suppliers. Stakeholders must monitor regulatory alignment between Russian GOST standards and evolving EAEU harmonization protocols to anticipate compliance cost shifts and sourcing reconfigurations.
Market Dynamics
Moscow and Saint Petersburg apartment densification is compressing average unit sizes below fifty square meters, forcing manufacturers to reengineer product portfolios around modularity and vertical storage systems that maximize livable floor area.
Growth Catalysts
- EAEU Technical Regulation 037/2016:Harmonized furniture safety standards across the customs union are reducing cross-border certification duplication for compliant Russian manufacturers exporting to Belarus and Kazakhstan.
- Particleboard substitution:Domestic engineered wood panel production is displacing solid timber in mid-market storage furniture, lowering material costs while maintaining structural performance.
- Central Federal District construction:High-density residential development around Moscow is generating concentrated demand for space-efficient furnishings in new-build completions.
Market Restraints
- Birch veneer supply concentration:Kirov and Vologda regions control over seventy percent of domestic rotary-cut veneer output, creating geographic vulnerability to weather-related harvest disruptions.
- Import dependency for hardware:Hinge, slide, and lift mechanisms rely heavily on German and Austrian suppliers, exposing assemblers to euro-denominated cost volatility and extended lead times.
- Formaldehyde emission ceilings:EAEU technical regulations mandate E1-class particleboard minimums, requiring capital-intensive press upgrades at legacy Soviet-era panel plants.
Strategic Opportunities
- Northwestern Federal District underpenetration:Kaliningrad and Pskov regions show furniture spending gaps relative to income levels, creating white space for flat-pack distribution networks.
- Online-to-offline channel fusion:Showroom-light digital platforms with augmented-reality room visualization are capturing younger cohorts before physical store visits.
- Biophilic material convergence:Integration of living moss walls and integrated planters into storage systems is electrifying premium positioning in metropolitan showrooms.
Industry Challenges
- CNC programming talent scarcity:Russian vocational pipelines produce insufficient operators for five-axis routing centers, constraining customization throughput at mid-size factories.
- GOST-EAEU alignment timelines:Overlapping national and customs-union certification requirements extend product approval cycles by four to six months for upholstered goods containing polyurethane foam.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Home Furniture Market |
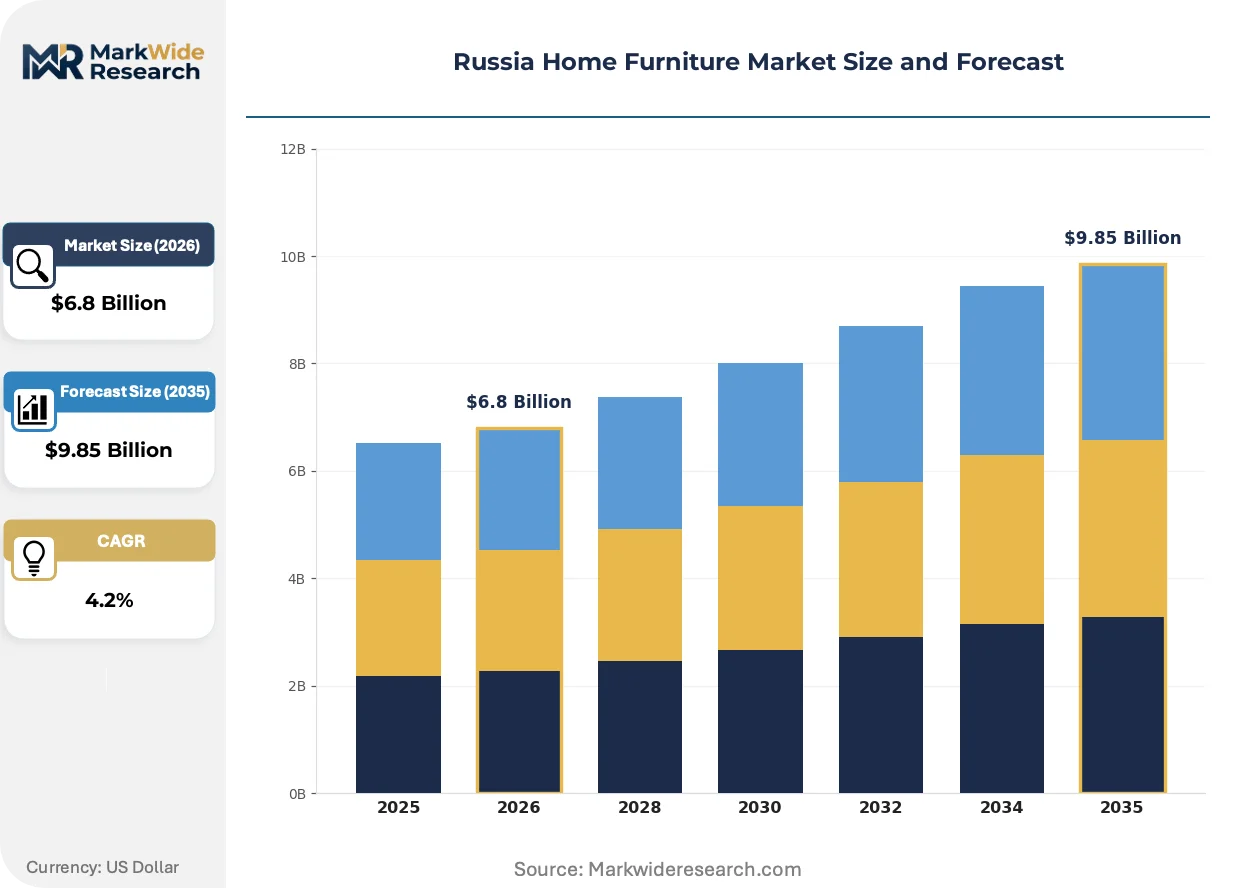
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Tables, Chairs Material: Wood, Metal, Upholstered, Glass Design Style: Modern, Classic, Minimalist, Rustic Distribution Channel: Online, Retail Stores, Wholesale, Showrooms |
| Companies Covered | IKEA, BOROVICHI-MEBEL CJSC, Furniture Factory Shatura OJSC, Lazurit Furniture, Stolplit-Rus OOO, Maria Furniture Factory, Kuchenberg, Angstrem, Ascona-Vek LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Home Furniture Market Evolving Landscape
Digital fabrication and regulatory tightening are compressing traditional manufacturing timelines while elevating material transparency requirements across the Russian furniture supply base.
Electromechanical lift-bed systems with integrated desk surfaces are electrifying space efficiency in sub-forty-square-meter apartments. Young professional households in Moscow's MKAD ring districts are specifying these mechanisms in over one-third of new bedroom purchases. This technology is electrifying demand for reinforced wall-anchoring hardware and load-rated pneumatic struts that domestic metalworkers must now certify to EAEU mechanical safety standards.
Russia's sanitary-epidemiological authority has tightened volatile organic compound testing protocols for synthetic adhesives used in laminated surfaces. Factory laboratories must now maintain gas chromatography capability for batch-level emission verification. Upholstered seating manufacturers in the Vladimir region are absorbing capital costs for in-house testing infrastructure to maintain import-competitive certification speed.
Direct-to-developer procurement is consolidating specification power in Moscow's residential construction sector. Large-scale developers are unbundling furniture from general fit-out contracts, creating dedicated supplier panels for standardized apartment packages. This concentration is most visible in the New Moscow annexation zones where uniform finish specifications across thousand-unit phases favor manufacturers with scalable CNC batch production.
Russia Home Furniture Market Segmentation
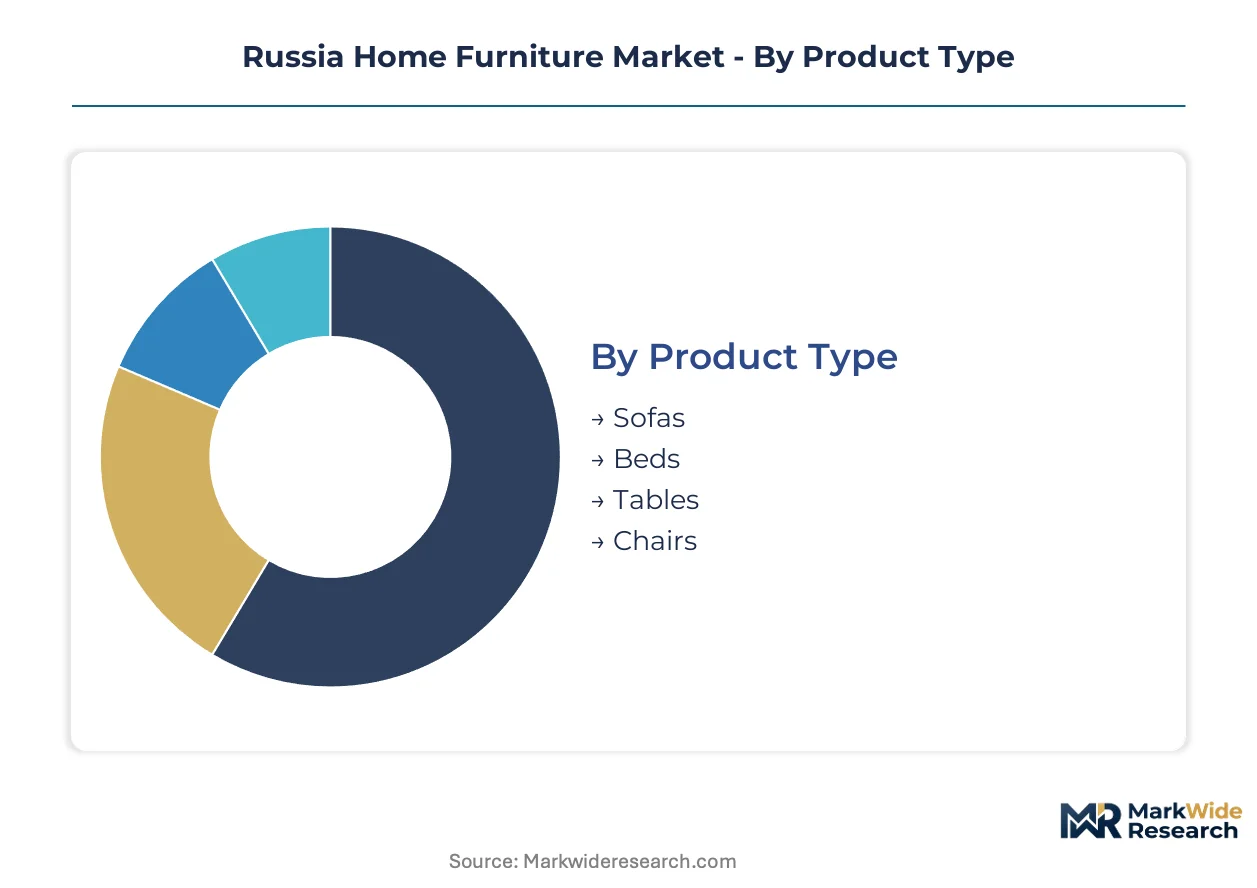
Segmentation in the Russia home furniture market exposes how material sourcing geography, apartment size constraints, and certification complexity create divergent margin structures across product lines. Manufacturers configure production workflows and distribution investments differently depending on which segment combinations they target.
Product Type:
Standalone furniture dominates Moscow and Saint Petersburg apartment installations where occupants purchase pieces sequentially rather than in complete room sets. Sofas and beds function as anchor investments that consumers select first, with tables and chairs following as complementary purchases.
- Sofas:Modular sectional configurations with reversible chaise components and removable upholstery covers accommodate narrow elevator dimensions common in Soviet-era panel buildings. Demand clusters in the Central Federal District where young professional households prioritize transformable seating that converts to guest sleeping surfaces.
- Beds:Platform frames with integrated storage drawers and lift mechanisms capture preference in sub-forty-square-meter apartments. The Vladimir and Ryazan regions manufacture the bulk of domestic bed frames, leveraging local particleboard press capacity and birch veneer finishing infrastructure.
- Tables:Dining surfaces with foldable leaf extensions and nesting designs address space constraints in compact kitchens.
- Chairs:Stackable and cantilever designs concentrate in mass-market channels serving rental apartment turnover.
Volume placements concentrate in beds; the faster expansion belongs to sofas.
Material:
Cost tier positioning separates premium solid timber from engineered panel alternatives, with metal and glass occupying narrower specialty niches. Raw material geography directly shapes factory location decisions and supply radius economics.
- Wood:Birch and pine solids from Kirov and Vologda forests supply high-end dining and bedroom collections, while laminated particleboard from Kostroma and Tver plants feeds mid-market storage lines. EAEU formaldehyde regulations are forcing press upgrades at legacy Soviet-era facilities.
- Upholstered:Foam-core construction with synthetic textile or genuine leather covering commands premium pricing in metropolitan showrooms. Sanitary-epidemiological certification requirements for polyurethane adhesives extend approval timelines for imported foam blocks.
- Metal:Powder-coated steel framing dominates office-adjacent home furniture and industrial-style shelving systems.
- Glass:Tempered tabletops and display cabinet inserts occupy narrow positioning in contemporary design portfolios.
Wood materials anchor current production volumes; upholstered categories are climbing the fastest as metropolitan consumers upgrade seating investments.
Design Style:
Application context distinguishes new-build apartment specifications from replacement purchases in established owner-occupied housing, with aesthetic preference diverging sharply by building vintage and buyer age cohort.
- Modern:Clean-lined surfaces, hidden hardware, and neutral palettes align with developer-standard finish specifications in New Moscow residential towers. This style dominates procurement panels for thousand-unit phases where uniformity reduces construction timeline risk.
- Classic:Carved detailing, dark stains, and symmetrical proportions sustain replacement demand in Stalin-era and Brezhnev-period apartments where occupants seek stylistic continuity with existing architectural elements.
- Minimalist:Extreme reduction in visual mass and multifunctional components appeals to younger cohorts in compact studio layouts.
- Rustic:Distressed finishes and live-edge timber surfaces occupy narrow artisan positioning in dacha and country house segments.
Modern styling captures the largest developer specification volumes; minimalist design is gaining share fastest among digital-native purchasers.
Distribution Channel:
Customer type and purchase urgency separate immediate-need buyers from research-intensive shoppers, with channel selection correlating to product complexity and delivery timeline requirements.
- Retail Stores:Multi-brand furniture malls and manufacturer-owned galleries in Moscow's MKAD ring districts allow tactile material evaluation and same-day takeaway for stock items. These locations absorb the highest rent burdens but capture decisive purchasers unwilling to wait for delivery.
- Online:Digital platforms with augmented-reality room visualization are capturing younger cohorts before physical store visits, particularly for standardized sofa and storage configurations where dimensions are predictable.
- Showrooms:Manufacturer flagship spaces in high-traffic districts concentrate premium upholstery and solid wood collections requiring consultative selling.
- Wholesale:Direct-to-developer procurement panels bypass retail markup for standardized apartment fit-outs in large-scale residential construction.
Retail stores maintain the highest transaction frequency; online channels are expanding most quickly as logistics networks mature for flat-pack delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technopolis Moscow and the Kaluga Special Economic Zone concentrate furniture manufacturing incentives, drawing assembly operations toward the Central Federal District's logistics corridors. Saint Petersburg's port infrastructure anchors northwestern import channels for Baltic hardware suppliers. Regional demand patterns diverge sharply between dense metropolitan cores and underpenetrated peripheries.
Central Federal District
Moscow's MKAD ring districts generate concentrated demand for transformable and space-efficient furnishings in sub-fifty-square-meter apartments. The EAEU Technical Regulation 037/2016 harmonizes safety standards across the customs union, reducing certification burdens for district-based exporters targeting Belarus and Kazakhstan. The Vladimir and Ryazan industrial clusters manufacture bed frames and particleboard components, leveraging captive veneer finishing capacity.
Northwestern Federal District
Saint Petersburg's Baltic port infrastructure processes hinge and lift mechanism imports from German and Austrian suppliers for redistribution across European Russia. The country's sanitary-epidemiological framework mandates gas chromatography testing for synthetic adhesive emissions, extending approval timelines for upholstered goods entering through northwestern customs points. Kaliningrad and Pskov regions exhibit furniture spending gaps relative to income levels, creating distribution white space for flat-pack networks.
Volga Federal District
Kirov and Vologda regions control over seventy percent of domestic rotary-cut birch veneer output, anchoring solid wood furniture supply chains. EAEU formaldehyde emission ceilings mandate E1-class particleboard minimums, forcing capital-intensive press upgrades at legacy Soviet-era panel plants in Kostroma and Tver. Weather-related harvest disruptions in these forest zones transmit price volatility downstream to dining and bedroom collections.
Siberian Federal District
Novosibirsk and Krasnoyarsk metropolitan areas sustain replacement demand for classic-styled furnishings in established owner-occupied housing from the Brezhnev period. The country's national standardization body enforces GOST furniture safety protocols that overlap with EAEU harmonization requirements, extending product approval cycles. Regional assemblers depend on rail freight from Central Federal District particleboard plants, elongating inventory cycles versus western competitors.
Southern Federal District
Rostov-on-Don and Krasnodar Krai residential construction generates demand for developer-standard modern furnishings in new-build completions. Direct-to-developer procurement panels are unbundling furniture from general fit-out contracts, favoring manufacturers with scalable CNC batch production. The district's Black Sea port infrastructure offers alternative import routes for hardware components, though euro-denominated cost volatility persists.
Russia Home Furniture Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail-channel players commanding premium positioning while OEM assemblers serve developer procurement panels. The vendor base organizes around three archetypes: flat-pack logistics specialists with national distribution networks, solid wood fabricators competing on durability perception, and vertically integrated particleboard producers extending cost stability into mid-market lines. Dominant competitive moves include direct-to-developer partnership formation and in-house production of engineered wood panels to insulate against material cost swings.
Among Nordic-origin flat-pack specialists, IKEA leverages its logistics network to sustain penetration across tier-one and tier-two cities. Domestic solid wood fabricators BOROVICHI-MEBEL CJSC and Furniture Factory Shatura OJSC occupy positions within the durability-focused tier, with the latter exemplifying backward integration into particleboard supply. These three entities represent contrasting strategic postures on import dependency, material certification, and channel concentration.
| Leading Market Players |
|---|
| IKEA |
| BOROVICHI-MEBEL CJSC |
| Furniture Factory Shatura OJSC |
| Lazurit Furniture |
| Stolplit-Rus OOO |
| Maria Furniture Factory |
| Kuchenberg |
| Angstrem |
| Ascona-Vek LLC |
| Others |
Value Network & Pricing Analysis
EAEU formaldehyde emission ceilings gate qualified supply for premium-tier furniture lines, forcing manufacturers to absorb capital-intensive press upgrades or surrender pricing power to certified competitors. This regulatory filter concentrates premium positioning among vertically integrated producers while compressing margins at legacy Soviet-era panel plants unable to fund compliance investments.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with metropolitan buyers paying premiums for same-week delivery of certified particleboard storage systems while spot inventory of non-compliant legacy stock trades at discounts. Price differentiation hinges on EAEU certification status and volume scale, with bulk procurement panels for Moscow developers commanding standard-tier rates. Pricing pressure stems from euro-denominated hardware import costs, with hinge and slide mechanism volatility compressing assembler margins. Rental apartment operators exhibit highest price sensitivity, prioritizing economy-tier stackable seating for turnover units.
Supply Chain Analysis
CNC programming talent scarcity in Vladimir and Ryazan manufacturing clusters constrains customization throughput and elongates order fulfillment cycles for mid-size factories. Geographic supply concentration centers on Germany and Austria for lift mechanisms and precision hardware, while domestic birch veneer production draws from Kirov and Vologda forest zones. Raw material dependencies encompass rotary-cut veneer, E1-class particleboard, and polyurethane foam blocks for upholstered construction. Single-source vulnerability in Baltic hardware channels exposes assemblers to extended lead times during euro volatility spikes. Distribution runs through multi-brand furniture malls in Moscow's MKAD ring districts and direct-to-developer procurement panels for standardized apartment fit-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EAEU technical regulations force capital upgrades that weaker players cannot finance, creating acquisition opportunities for well-capitalized manufacturers with captive particleboard supply.
For Market Incumbents: Acquire distressed particleboard press capacity in Kostroma and Tver to secure E1-class certification compliance and deny material access to emerging competitors. Defensive moves require locking direct-to-developer procurement panels through scalable CNC batch production partnerships with New Moscow residential developers, while investing in-house gas chromatography capability to accelerate sanitary-epidemiological approval timelines for upholstered goods. For New Entrants and Emerging Players: Young professional households in Kaliningrad and Pskov represent the most penetrable buyer archetype, with furniture spending gaps relative to income levels creating white space for flat-pack distribution networks. Target showroom-light digital platforms with augmented-reality room visualization to capture research-intensive purchasers before physical store visits, leveraging logistics partnerships for last-mile delivery without capital-intensive retail footprint. For Investors and Strategic Acquirers: Developer unbundling of furniture from general fit-out contracts is the leading indicator that direct-to-procurement-panel manufacturers will consolidate specification power in Moscow residential construction. Long-term viability favors vertically integrated producers with captive veneer finishing and particleboard press capacity. Acquisition targets should demonstrate scalable CNC production and EAEU certification alignment. Watch for distressed asset sales from legacy Soviet-era panel plants unable to fund E1-class press upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Particleboard Supply | In-house E1-class panel production insulates against veneer price volatility and hardware import cost swings. |
| Direct-to-Developer Procurement Panel Formation | Exclusive supplier status for New Moscow thousand-unit phases locks recurring revenue and reduces customer acquisition cost. |
| In-House Gas Chromatography Capability | Batch-level VOC testing accelerates sanitary-epidemiological certification for polyurethane foam upholstery lines. |
| Flat-Pack Distribution Network Expansion | Kaliningrad and Pskov penetration captures underpenetrated Northwestern Federal District demand without flagship retail investment. |
| Augmented-Reality Room Visualization Platform | Digital-first customer capture reduces showroom dependency and shortens consideration-to-purchase cycles for modular seating. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and EAEU technical regulation harmonization protocols underwrites the qualitative findings presented in this study. Primary interviews with furniture factory operations directors, developer procurement managers, retail channel buyers, and sanitary-epidemiological certification specialists combined with secondary validation from GOST standard documentation, EAEU customs union directives, and regional construction permit filings. Bottom-up demand modeling from apartment completion data and top-down supply analysis from particleboard press capacity surveys triangulate volume estimates.
Rate-of-change decomposition across product type, material grade, design style, and distribution channel dimensions structures the analytical framework over the projection horizon. CAGRs derive from segmented demand elasticity analysis and supply capacity expansion schedules, with specific inputs including Moscow MKAD ring district residential densification rates, birch veneer harvest yield variations, and EAEU-E1 particleboard compliance transition timelines.
Revisions become necessary when EAEU regulatory alignment timelines extend beyond modeled assumptions, Baltic hardware import channels face tariff disruption, or Central Federal District construction permits deviate from baseline projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Contract Furniture Market
Furniture
Kids Furniture Market
Furniture
Eco-Friendly Furniture Market
Furniture
Home Furnishings Market
Furniture
Europe Upholstered Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
US Contract Furniture and Furnishing Market
Furniture
United Arab Emirates Furniture Market
Furniture
Rattan Furniture Market
Furniture
Italy Office Furniture Market
Furniture
Study Carrels Market
Furniture
Europe Furniture Market
Furniture
UK Sustainable Office Furniture Market
Furniture
Vietnam Furniture Market
Furniture
School Furniture Market