
 North America School Furniture Market | 2026-2036
North America School Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America School Furniture Market Intelligence
A shortage of certified furniture installers and ergonomic specialists is redrawing how districts evaluate vendor partnerships. Virco Manufacturing Corporation leverages its domestic manufacturing footprint to sustain rapid fulfillment timelines for large district contracts. Steelcase Inc. anchors its position through advanced ergonomic research partnerships with university design programs. Herman Miller Inc. differentiates via modular systems that accommodate flexible classroom layouts.
North America school furniture encompasses desks, chairs, tables, and storage units engineered to institutional durability standards, typically rated for 10-15 year service life under ANSI/BIFMA testing protocols, and serves the core function of supporting varied pedagogical formats from lecture to collaborative learning. Wood and metal materials still occupy the largest volume share, though composite segments are gaining fastest as districts prioritize lighter, more mobile configurations. The distributor channel dominates procurement for public K-12 systems, while direct sales capture premium volumes in private college and university segments where customization requirements run deeper.
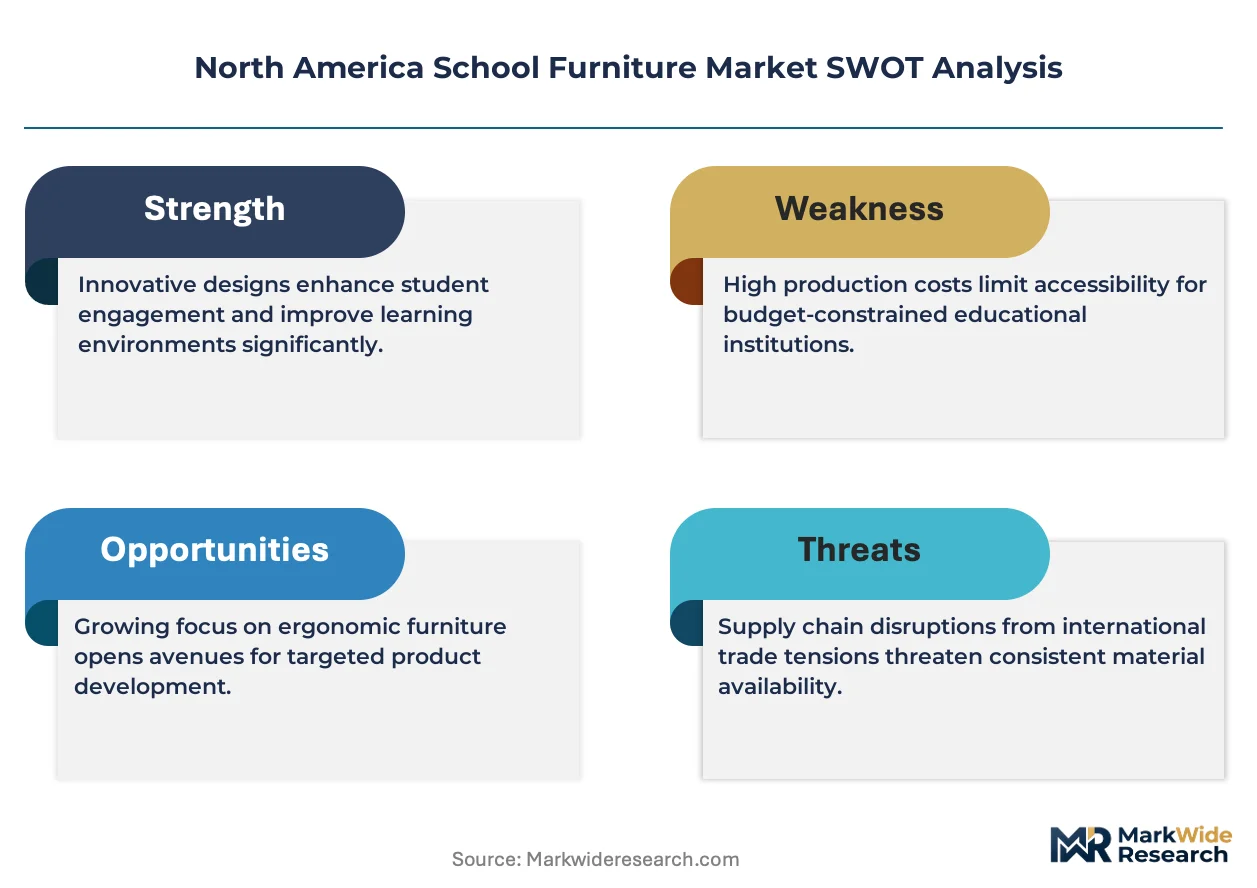
The U.S. Consumer Product Safety Commission and California Air Resources Board set baseline thresholds for structural safety and formaldehyde emissions, with EPA purchasing guidelines pushing broader voluntary compliance across supplier tiers. Health Canada administers parallel surface coating and flammability standards that Canadian provinces incorporate into provincial procurement specifications. Stakeholders must monitor how evolving state-level green building mandates in California, New York, and Texas reshape material specification lists and disqualify non-certified suppliers from bid pools.
Market Dynamics
District procurement cycles now hinge on installer availability rather than product availability alone, compressing vendor evaluation timelines and elevating turnkey service capabilities above standalone manufacturing scale.
Growth Catalysts
- Vocational Training Expansion:Secondary schools across Texas and California are outfitting dedicated STEM labs and career-technical spaces, driving specialized furniture configurations that standard classrooms cannot accommodate.
- EPA Purchasing Guidelines:The U.S. Environmental Protection Agency's low-emitting material standards are filtering into state-level bid specifications, creating compliance-driven replacement demand among districts with aging inventories.
- Composite Material Adoption:Lighter polymer-wood hybrids are enabling mobile classroom layouts without structural floor reinforcement, reducing installation costs for renovation projects.
Market Restraints
- Certified Installer Shortage:The pool of technicians qualified under ANSI/BIFMA installation protocols has not expanded with district replacement volumes, extending project timelines.
- Steel and Aluminum Volatility:Metal frame components remain exposed to commodity price swings that erode fixed-bid margins on multi-year district contracts.
- Canadian Import Friction:Health Canada's surface coating standards create dual-certification burdens for U.S. manufacturers serving cross-border provincial systems.
Strategic Opportunities
- Texas District Consolidation:Rapid enrollment growth in suburban Houston and Dallas-Fort Worth districts is triggering bulk replacement cycles with multi-site coordination needs.
- Furniture-as-a-Service Models:Leasing structures with embedded refresh clauses are penetrating private university segments where capital budget constraints favor operational expenditure treatment.
- Green Building Mandate Convergence:California's CALGreen requirements and New York's state procurement sustainability criteria are creating specification overlap that rewards pre-certified suppliers.
Industry Challenges
- Ergonomic Specialist Scarcity:Districts lack in-house expertise to evaluate adaptive seating claims, forcing reliance on vendor-provided assessments with inherent conflict.
- Legacy Inventory Integration:Modular system upgrades must interface with decade-old fixed-desk installations, complicating phased renovation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America School Furniture Market |
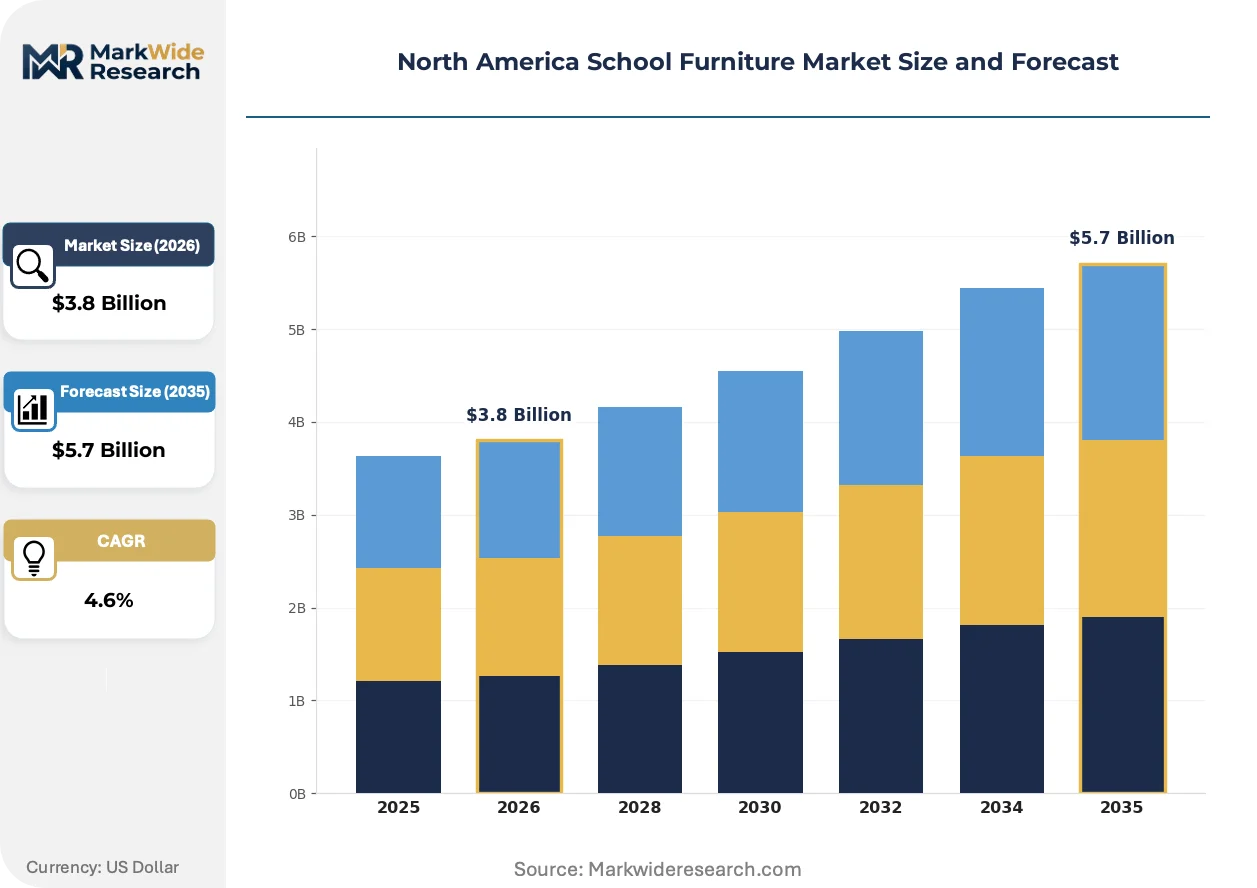
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Units Material: Wood, Metal, Plastic, Composite End User: Elementary Schools, Secondary Schools, Colleges, Universities Distribution Channel: Direct Sales, Online Retail, Distributors, Retail Stores |
| Companies Covered | Knoll Inc., Virco Manufacturing Corporation, Krueger International Inc., VS America Inc., Haworth Inc., Steelcase Inc., HNI Corporation, Smith System Mfg. Co., Herman Miller Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America School Furniture Market Strategic Shifts & Innovations
Classroom configuration flexibility now dominates specification conversations, with mobility and reconfigurability displacing durability as the primary purchasing criterion among district facilities managers.
Modular desk-pod systems with integrated cable management and castor-mounted bases are supplanting traditional fixed-row arrangements. Secondary schools in Florida and Arizona are adopting these configurations fastest, driven by year-round air conditioning costs that favor interior layout changes over building expansion. The shift is compressing demand for heavy laminate tabletops while expanding orders for lightweight composite surfaces with magnetic and writable finishes.
The U.S. Environmental Protection Agency's purchasing guidelines for low-emitting materials are tightening voluntary compliance thresholds across supplier tiers. Manufacturers serving California districts now face de facto mandatory adherence to CARB Phase 2 formaldehyde limits, with testing documentation requirements extending to subcomponent suppliers. Canadian provincial systems are mirroring these specifications, creating North American harmonization pressure on wood-panel sourcing.
District buying committees are unbundling installation and maintenance services from product procurement, issuing separate RFPs for each function. This fragmentation favors specialized service contractors over integrated manufacturers in competitive evaluations. The pattern is most pronounced in Texas, where rapid district growth has outpaced internal facilities staffing and outsourced project management has become standard practice for bond-funded construction cycles.
North America School Furniture Market Segmentation
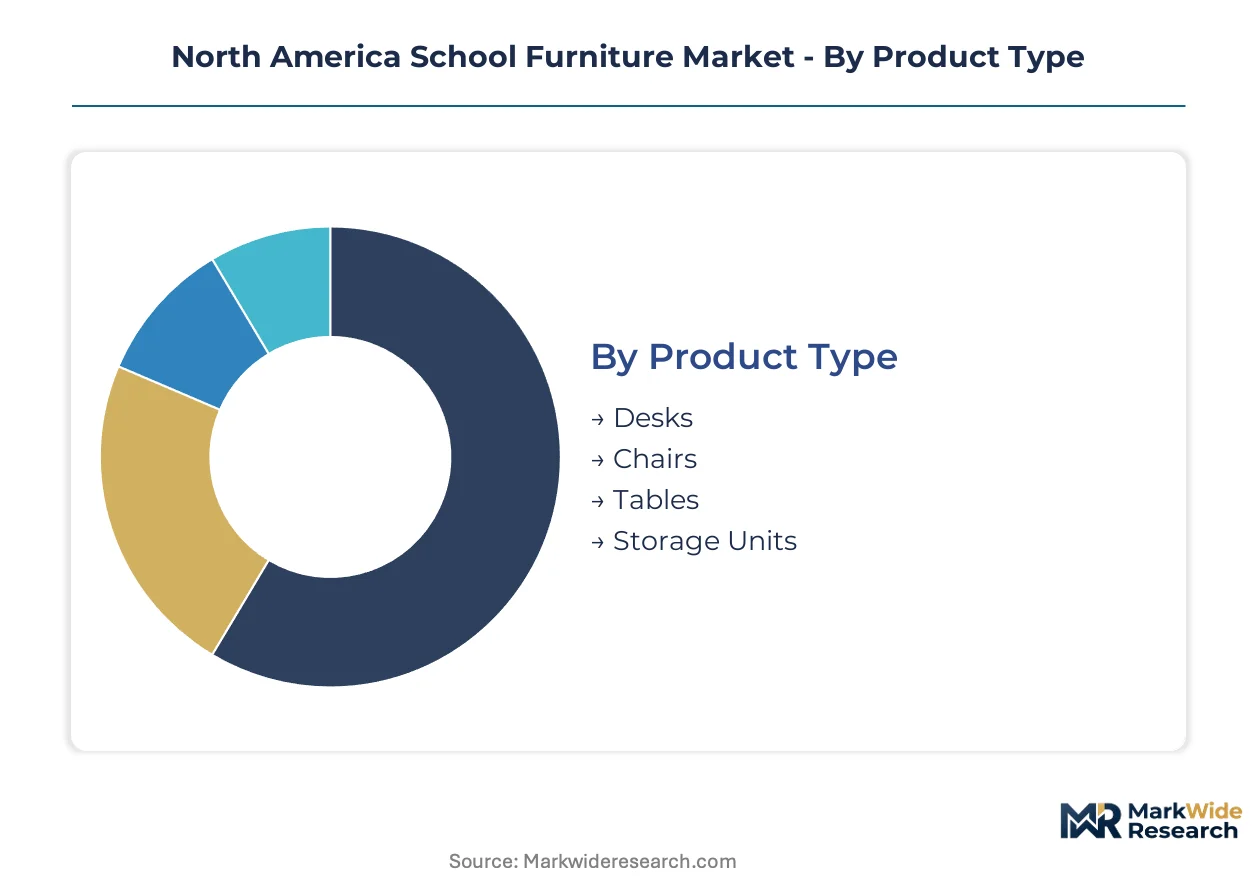
Product, material, and channel configurations in North American school furniture diverge sharply across institutional tiers. Procurement committees weight durability against mobility differently in K-12 bond cycles versus university capital campaigns.
Product Type:
Chairs face the most intense substitution pressure from adaptive seating startups and ergonomic specialists, forcing incumbent manufacturers to defend specification slots with extended warranty terms.
- Desks:Traditional laminate surfaces with steel frames still dominate volume, though fixed-leg units in Texas districts are losing share to height-adjustable alternatives. Houston and Dallas-Fort Worth procurement cycles now require ANSI/BIFMA certification for load-bearing capacity above 300 pounds.
- Chairs:Polypropylene shell designs with cantilever bases have displaced wood-seat models in California secondary schools. CARB Phase 2 compliance documentation now accompanies every bid submission to Los Angeles and San Diego districts.
- Tables:Trapezoidal and hexagonal collaborative surfaces are penetrating STEM lab configurations.
- Storage Units:Mobile cubby systems with locking casters serve vocational training spaces in Florida.
Desks retain volume leadership; chairs hold the steepest expansion curve.
Material:
Cost tier stratification separates premium composite formulations from commodity metal framing, with mid-grade wood laminates squeezed between specification-grade demands and budget constraints.
- Wood:Medium-density fiberboard with thermally fused laminate remains the default for budget-conscious districts, though formaldehyde emission testing now extends to subcomponent suppliers under EPA purchasing guidelines.
- Metal:Steel tube framing with powder-coat finishes anchors institutional durability expectations, particularly in Texas where 10-year service life guarantees are standard bid requirements.
- Plastic:Injection-molded polypropylene shells dominate cafeteria and library seating.
- Composite:Polymer-wood hybrids enable lighter mobile configurations without floor reinforcement.
Metal retains volume leadership; composite holds the steepest expansion curve.
End User:
Application maturity varies dramatically, with elementary procurement locked into standardized bulk contracts while university segments fragment into specialized ergonomic specifications.
- Elementary Schools:Smaller-scale furniture with rounded edges and primary-color finishes dominates procurement, with California districts specifying CARB-compliant materials for indoor air quality.
- Secondary Schools:Vocational training expansion in Texas and California is driving specialized lab configurations that standard classrooms cannot accommodate.
- Colleges:Multi-use lecture hall seating with integrated power outlets is penetrating community college renovation cycles.
- Universities:Research-library carrels and collaborative commons furniture command premium pricing through direct sales channels.
Elementary schools retain volume leadership; secondary schools hold the steepest expansion curve.
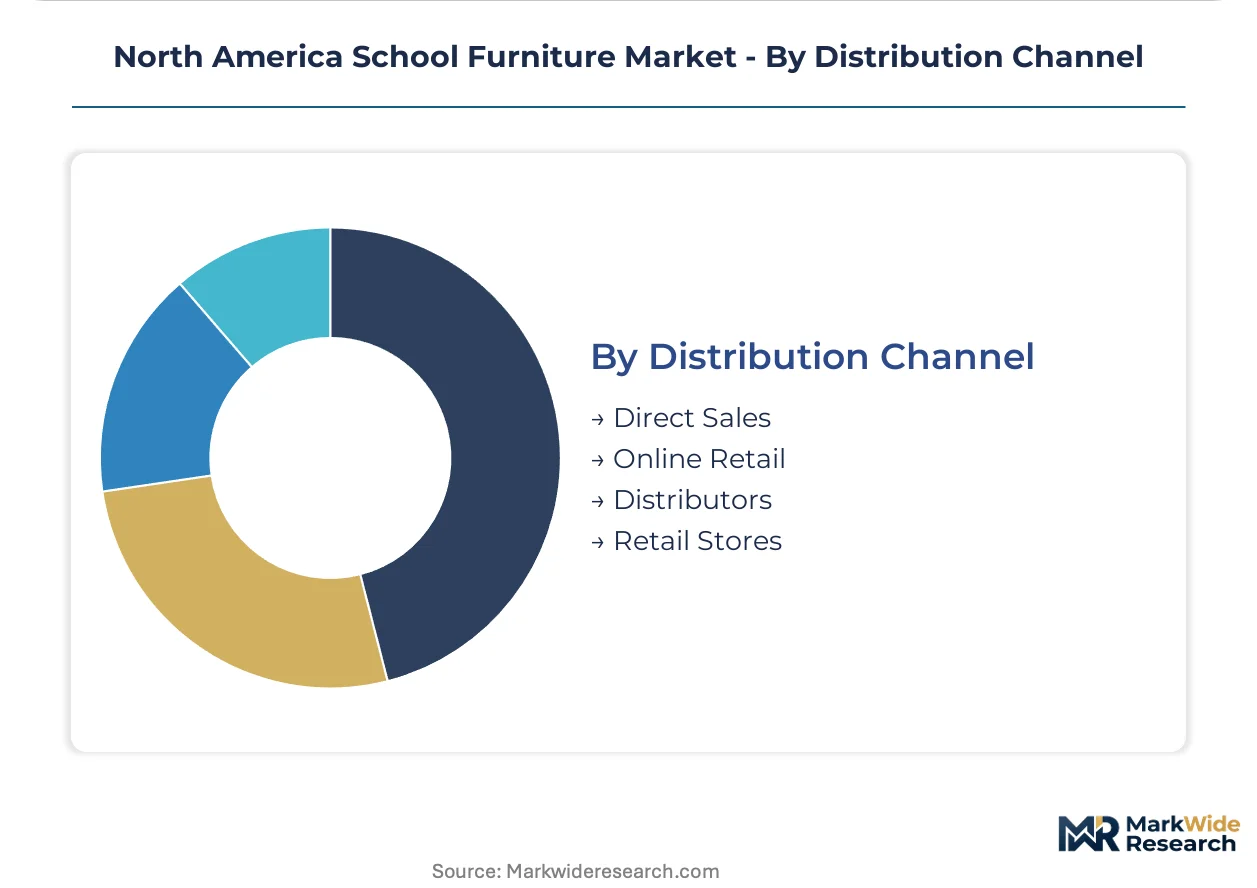
Distribution Channel:
Customer type fragmentation splits procurement between bundled distributor relationships for public systems and unbundled direct negotiations for private institutions.
- Direct Sales:Custom fabrication and embedded installation services capture premium volumes in private university segments where specification requirements run deeper.
- Online Retail:Small-quantity replacement orders and parent-teacher association purchases flow through e-commerce platforms.
- Distributors:Multi-line catalog houses dominate public K-12 procurement, bundling furniture with maintenance contracts and turnkey project management.
- Retail Stores:Independent dealers serve rural districts and charter school startups with limited bond funding.
Distributors retain volume leadership; direct sales hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply, with U.S. districts prioritizing rapid-install mobile configurations while Canadian systems emphasize dual-certification compliance and Mexican procurement concentrates on cost-optimized bulk contracts for expanding basic education coverage.
United States
Texas suburban districts around Houston and Dallas-Fort Worth are driving multi-site replacement cycles through bond-funded construction, while California's CARB Phase 2 formaldehyde limits and EPA purchasing guidelines reshape material specifications statewide. The EPA's low-emitting material standards now filter into state-level bid specifications, creating compliance-driven replacement demand. Florida and Arizona secondary schools are adopting castor-mounted desk-pod configurations fastest, driven by year-round cooling costs that favor interior reconfiguration over building expansion.
Canada
Ontario and Quebec provincial systems are mirroring California emission specifications, creating harmonization pressure on wood-panel sourcing across the Great Lakes supply corridor. Health Canada administers parallel surface coating and flammability standards that provinces incorporate into procurement specifications. Vancouver and Toronto districts are unbundling installation services from product procurement, issuing separate RFPs that favor specialized service contractors over integrated manufacturers.
Mexico
Federal basic education expansion programs in northern border states and the Yucatán Peninsula are generating standardized bulk furniture contracts with 10-year durability requirements. Mexican procurement specifications emphasize cost optimization over ergonomic customization, with distributor channels dominating public system purchases. Monterrey and Mexico City metropolitan areas concentrate demand for vocational training furniture as technical secondary enrollment expands under national education reform mandates.
North America School Furniture Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in North American school furniture supply. The upper tier combines domestic manufacturing footprints with turnkey installation capabilities to capture large district contracts. Below them, ergonomic specialists and composite material innovators compete on specification differentiation rather than scale. Strategic moves concentrate on geographic consolidation through distributor acquisitions and vertical control over certified installer networks to compress project timelines.
Among U.S.-based integrated manufacturers, Virco Manufacturing Corporation exemplifies the rapid-fulfillment archetype through its domestic production positioning. Steelcase Inc. and Herman Miller Inc. occupy positions within the premium-systems tier, representing advanced ergonomic research and modular flexibility specializations respectively. These three anchors illustrate how competitive positioning stratifies between scale-driven fulfillment and specification-driven premium capture.
| Leading Market Players |
|---|
| Knoll Inc. |
| Virco Manufacturing Corporation |
| Krueger International Inc. |
| VS America Inc. |
| Haworth Inc. |
| Steelcase Inc. |
| HNI Corporation |
| Smith System Mfg. Co. |
| Herman Miller Inc. |
| Others |
Cost & Logistics Intelligence
CARB Phase 2 formaldehyde emission standards gate both supplier qualification and price tiering across California and Texas procurement systems, compressing margins for uncertified manufacturers while rewarding documented compliance with specification access. Districts now unbundle installation from product awards, fragmenting pricing power across service and manufacturing layers.
Pricing Analysis
Multi-year district offtake contracts dominate K-12 procurement, with spot purchasing limited to emergency replacement volumes. Price differentiation rests on ANSI/BIFMA certification tier and turnkey installation bundling, with certified turnkey providers commanding 15-20% premiums over product-only bids. Cost compression in metal-framed desk segments is intensifying because steel and aluminum commodity volatility erodes fixed-bid margins. Rural districts and charter school startups exhibit highest price sensitivity, while suburban Houston and Dallas-Fort Worth systems prioritize rapid fulfillment over unit cost.
Supply Chain Analysis
Inbound logistics costs from Asian wood-panel suppliers through Los Angeles and Long Beach port complexes shape total landed cost structures for California distributors. Manufacturing concentration rests on domestic U.S. producers in California and Texas plus Mexican assembly operations serving border-state districts. Raw material dependencies include medium-density fiberboard, steel tube framing, and injection-molded polypropylene. Single-source vulnerability runs through certified installer networks, where technician scarcity extends project timelines. Distribution runs through multi-line catalog houses bundling furniture with maintenance contracts for public systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in certified installation services, where technician scarcity outpaces district replacement volumes and creates niches for specialized service contractors.
For Market Incumbents: Secure captive control over certified installer networks to compress project timelines and defend large-district contract positions against turnkey competitors. Invest in CARB Phase 2 and EPA purchasing guideline documentation systems to maintain specification access as California and New York tighten emission thresholds. Capacity addition in Texas manufacturing corridors captures suburban Houston and Dallas-Fort Worth bond-funded construction cycles. For New Entrants and Emerging Players: Anchor in furniture-as-a-service leasing structures for private university segments, where capital budget constraints favor operational expenditure treatment over ownership. Target secondary school vocational training configurations in Texas and California, where STEM lab specialization outstrips standard classroom supplier capabilities. Pursue direct sales channels with embedded refresh clauses to bypass distributor-dominated K-12 procurement. For Investors and Strategic Acquirers: EPA purchasing guideline expansion reshapes the acquisition landscape by elevating compliance documentation capabilities above manufacturing scale in valuation metrics. Long-term viability centers on suppliers with pre-certified material sourcing and installer network control across the 5-10 year window. Monitor Texas district consolidation patterns as inflection indicator for multi-site coordination demand and bulk replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Acquisition | Captures scarce ANSI/BIFMA-qualified technicians to compress Texas district project timelines. |
| Composite Material Formulation Investment | Enables lighter mobile configurations without floor reinforcement, reducing California renovation costs. |
| Direct Sales Channel Expansion | Penetrates private university segments where customization requirements exceed distributor catalog capabilities. |
| Leasing Structure Development | Converts capital expenditure constraints into recurring revenue streams across community college systems. |
| Cross-Border Certification Harmonization | Aligns CARB Phase 2 documentation with Health Canada standards to unlock Ontario and Quebec procurement. |
Research Approach
Operator-level perspectives from district facilities managers, certified furniture installers, ergonomic specialists, and distributor procurement leads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against EPA purchasing guidelines, CARB Phase 2 documentation requirements, ANSI/BIFMA testing protocols, and district bond-funded construction disclosures. Bottom-up district-level demand aggregation triangulated against top-down manufacturer shipment data.
Sensitivity analysis across enrollment growth scenarios, commodity price bands, and certification timeline variations framed the analytical approach throughout the projection horizon. Segmentation dimensions modeled include product type, material grade, end-user tier, and distribution channel structure. CAGRs derived from fitted trend extrapolation anchored in documented replacement cycles and vocational training expansion mandates.
Material uncertainties — steel and aluminum commodity volatility, certified installer supply elasticity, state-level green building mandate adoption rates — sit outside the modeled envelope. Forecasts reflect assumptions about procurement cycle continuity and bond funding availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
India Home Furniture Market
Furniture
UAE Home Furniture Market
Furniture
Global Home Furniture Market
Furniture
Sanded Plywood Market
Furniture
Fireplace Mantels Market
Furniture
Plastic Furniture Market
Furniture
GCC Multifunctional Furniture Market
Furniture
North America Smart Furniture Market
Furniture
Kids Furniture Market
Furniture
Russia Home Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Study Carrels Market
Furniture
RTA Furniture Market
Furniture
Global Organic Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
Europe High-End Furniture Market