
 US Secondary Wood Products Market | 2026-2036
US Secondary Wood Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Secondary Wood Products Market Intelligence
Asset-light leasing models for CNC routing and finishing equipment are rewriting capital requirements for mid-scale secondary wood processors. Universal Forest Products leverages its distributed mill network to sustain rapid turnaround on custom architectural millwork orders. Georgia-Pacific anchors large-volume OSB and plywood supply through integrated fiber sourcing from its timberland base. Weyerhaeuser Company dominates structural panel distribution by controlling rail and truck logistics into major construction markets.
Secondary wood products encompass engineered and remanufactured wood materials—plywood, particle board, oriented strand board, and veneer—typically manufactured from veneers, strands, particles, or fibers bonded under heat and pressure with formaldehyde-based or phenolic resins, serving as dimensionally stable alternatives to solid lumber in load-bearing and finish applications. The product type dimension shows plywood and OSB commanding the largest volume positions while veneer segments retain premium margin pools in specialty architectural and furniture-grade applications; by end user, construction absorbs the majority of tonnage though cabinetry and furniture channels extract higher per-unit value through specification-grade finishing requirements.
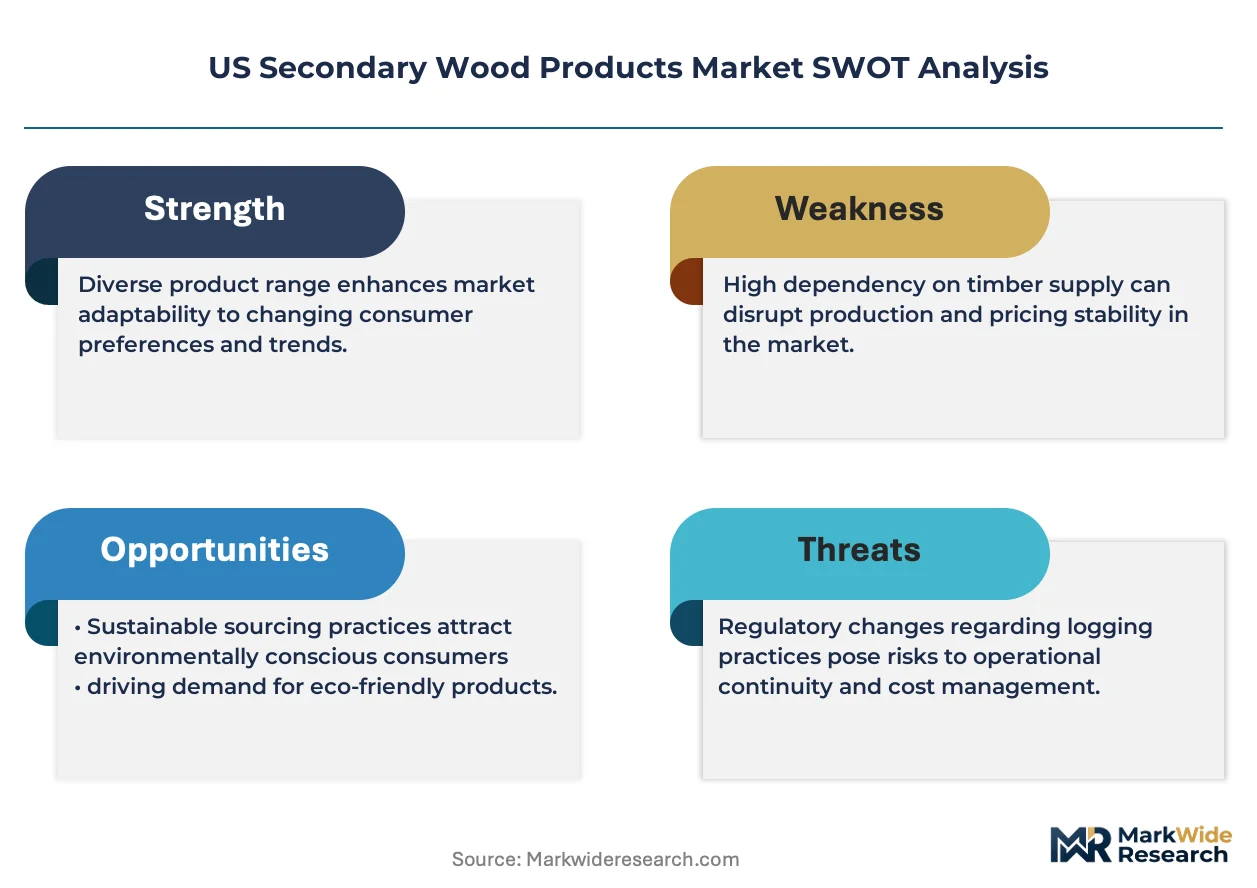
EPA Title VI formaldehyde emission standards, California Air Resources Board ATCM Phase 2 benchmarks, and OSHA wood dust exposure limits collectively shape product certification requirements and factory ventilation investments across US manufacturing facilities. USDA Biopreferred and Forest Stewardship Chain-of-Custody labeling programs increasingly filter into federal and commercial procurement specifications, tilting contract awards toward certified producers. Stakeholders must monitor how pending revisions to TSCA Section 6 risk evaluations for formaldehyde resins could trigger reformulation costs or supply qualification disruptions without warning.
Market Dynamics
EPA Title VI formaldehyde emission standards are compressing bonded wood product specifications while Southeast timber supply concentration creates procurement bottlenecks for non-integrated processors.
Growth Catalysts
- Residential construction recovery:Housing starts in the Southeast manufacturing corridor are pulling engineered wood panel orders from Georgia-Pacific and Weyerhaeuser distribution networks.
- USDA Biopreferred procurement mandates:Federal and commercial contract specifications now filter toward Chain-of-Custody certified producers, tilting awards toward qualified secondary wood manufacturers.
- Asset-light equipment leasing:CNC routing and finishing equipment leasing models are lowering capital barriers for mid-scale secondary wood processors entering custom architectural millwork.
Market Restraints
- Formaldehyde resin input volatility:Phenolic and urea-formaldehyde resin costs fluctuate with petrochemical feedstock pricing, squeezing margins on particle board and OSB production.
- Southeast supply concentration risk:Timber supply and mill capacity clustering in Georgia, Alabama, and North Carolina creates single-point vulnerability for national distribution.
- OSB substitution ceiling:Structural OSB faces technical limitations in high-moisture exterior applications where plywood retains specification lock-in.
Strategic Opportunities
- Underpenetrated Pacific Northwest cabinetry:Washington and Oregon housing markets show gap density for specification-grade veneer products serving furniture-grade channels.
- OSB emerging applications:Manufactured housing and modular construction segments are expanding engineered panel specifications beyond traditional stick-frame residential.
- Biobased adhesive technology convergence:Soy-based and lignin-bonded resin systems are converging with heat-press optimization to reduce formaldehyde dependency.
Industry Challenges
- CNC programming skill scarcity:Custom millwork shops face talent gaps in CAD-CAM integration for complex architectural routing operations.
- EPA certification timeline compression:Third-party testing and TSCA Section 6 compliance documentation create 90-120 day qualification delays for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Secondary Wood Products Market |
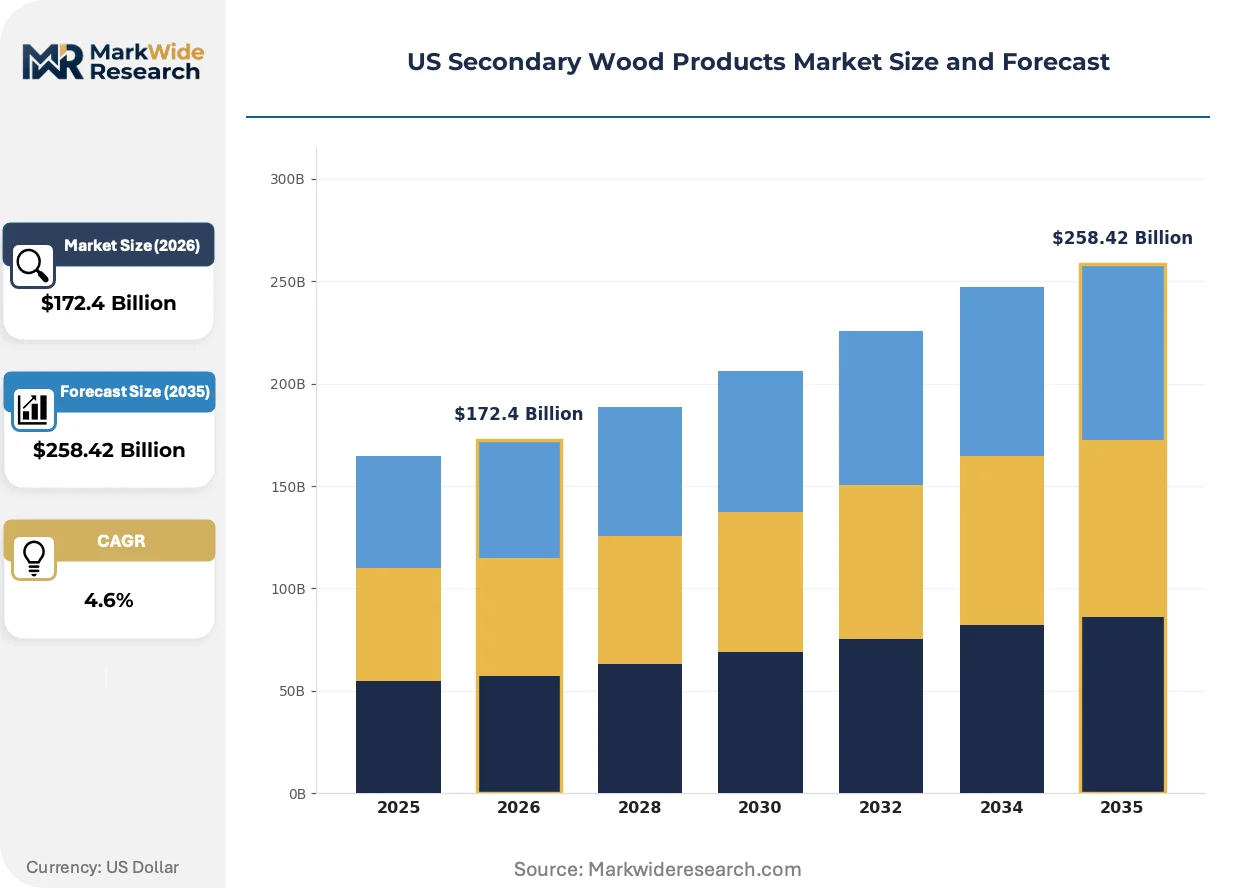
| Market Size in 2026 | $172.4 Billion |
| Market Size in 2035 | $258.42 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Particle Board, OSB, Veneer End User: Construction, Furniture, Cabinetry, Flooring Distribution Channel: Wholesalers, Retailers, Direct Sales, Online Application: Residential, Commercial, Industrial, Recreational |
| Companies Covered | Herman Miller, Universal Forest Products, Ashley Furniture Industries, West Fraser Timber, Georgia-Pacific, Steelcase, Weyerhaeuser Company, Kronospan, HNI Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Secondary Wood Products Market Strategic Shifts & Innovations
Digital fabrication systems and biobased bonding chemistry are displacing conventional manufacturing workflows while procurement specifications harden around emissions certification and chain-of-custody documentation.
Automated optical scanning and AI-driven defect detection is digitizing veneer grading and panel sorting operations. Large secondary wood processors in the Southeast are adopting these systems at scale to reduce manual inspection labor. The technology is digitizing quality control throughput while compressing rejection rates on furniture-grade plywood shipments.
EPA formaldehyde emission standards under TSCA Title VI are tightening bonded wood product specifications nationwide. Manufacturers must reformulate resin systems or absorb third-party certification costs to maintain market access. The regulation most affects particle board and medium-density fiberboard producers serving cabinetry channels, forcing capital allocation toward low-emitting adhesive alternatives.
Specification-grade buyers are consolidating vendor relationships around certified producers with documented Chain-of-Custody and Biopreferred labeling. Distributors serving federal and commercial construction channels are narrowing supplier panels to pre-qualified mills. This consolidation is most visible in Georgia and North Carolina markets where procurement teams prioritize emission-compliant OSB and plywood for institutional builds.
US Secondary Wood Products Market Segmentation
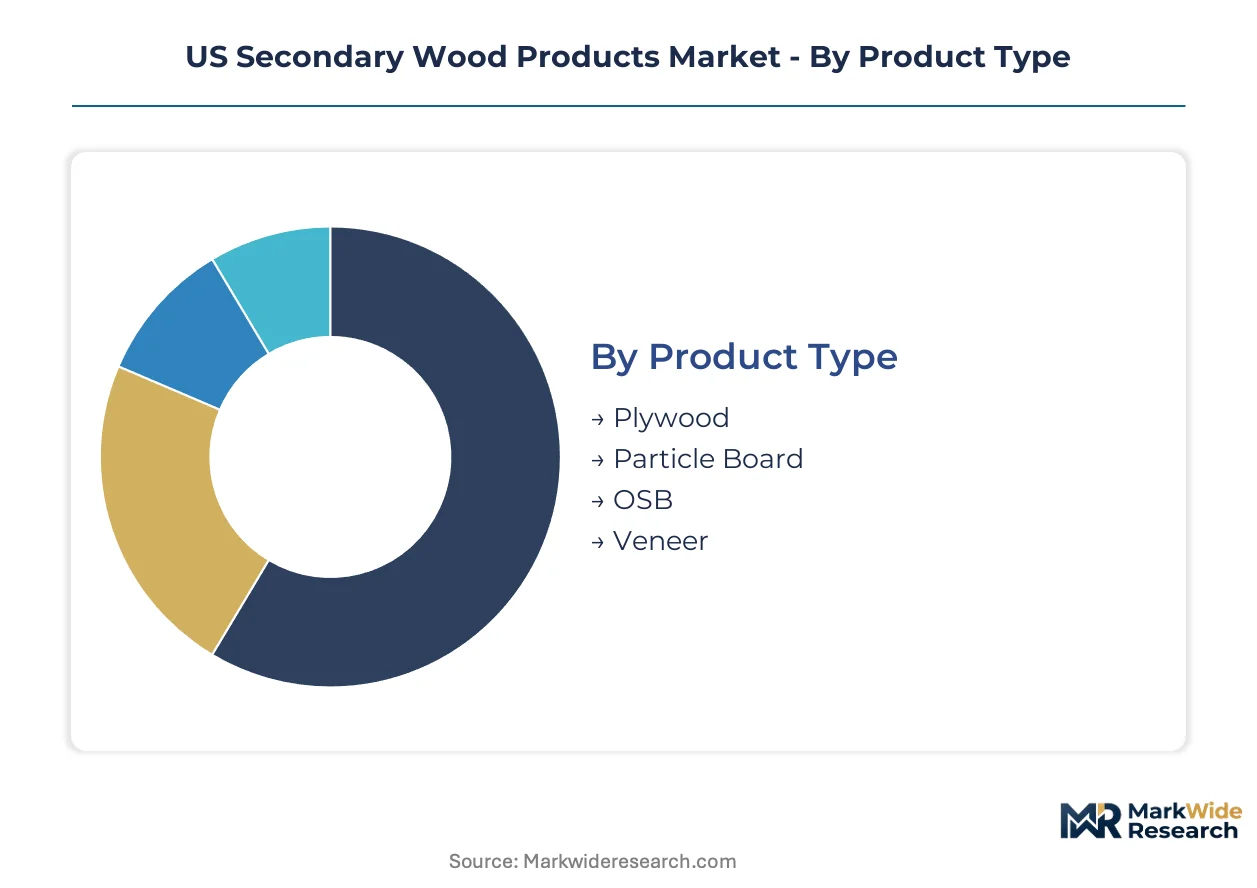
Secondary wood products fragment across four distinct classification axes that determine specification requirements, margin profiles, and channel access. Product type and end-user dimensions command the most strategic attention as they directly govern resin formulation investments and certification burdens under EPA Title VI.
Product Type:
Volume concentration across engineered panel categories dictates capital allocation priorities for mill operators and resin suppliers alike.
- Plywood:Cross-laminated veneer construction bonded with phenolic or urea-formaldehyde resins delivers dimensional stability superior to solid lumber in load-bearing applications. Demand concentrates in Southeast residential construction corridors where Georgia-Pacific and Weyerhaeuser distribution networks service recovering housing starts with structural sheathing and subfloor specifications.
- OSB:Oriented strand board compresses wood flakes in cross-directional layers with waterproof phenolic resins, achieving cost parity below plywood in wall and roof sheathing. Technical limitations in high-moisture exterior applications preserve plywood's specification lock-in for coastal and institutional builds across Florida and Gulf Coast markets.
- Particle Board:Resin-bonded wood particles serve as substrate cores for furniture and cabinetry laminates, facing intense EPA Title VI compliance pressure on formaldehyde emissions. Medium-density fiberboard variants extract premium pricing through uniform density profiles suited to precision machining.
- Veneer:Thin decorative wood sheets overlay lower-grade substrates in architectural millwork and premium furniture channels, retaining margin pools through specialty grade distinctions and Chain-of-Custody certification requirements.
Plywood holds installed capacity. OSB is rotating up the share rankings.
End User:
Application-driven specification tiers separate commodity volume plays from value-capture opportunities in finish-grade channels.
- Construction:Structural panel demand absorbs majority tonnage through single-family residential, multi-family, and light commercial builds. Southeast manufacturing corridor clustering—Georgia, Alabama, North Carolina—positions integrated producers to capture housing start recovery momentum with rapid-turn engineered wood shipments.
- Furniture:Specification-grade veneer and MDF substrates serve case goods and upholstery frame manufacturing, extracting per-unit value premiums through finishing requirements and Biopreferred procurement mandates filtering into federal contract awards.
- Cabinetry:Kitchen and bath cabinet manufacturers drive particle board and MDF consumption for box construction and door panels, facing compressed margins from resin input volatility and third-party certification costs.
- Flooring:Engineered hardwood and laminate underlayment applications utilize plywood and high-density fiberboard cores, with moisture-resistant specifications gaining traction in basement and commercial installations.
Construction dominates absolute volume. Furniture and cabinetry channels are climbing fastest on value per ton metrics.
Distribution Channel:
Channel structure determines working capital intensity and customer relationship depth for secondary wood processors.
- Wholesalers:Regional lumber distributors consolidate truckload volumes from Southeast mills for redistribution to contractor yards and retail locations, controlling inventory risk and logistics coordination.
- Retailers:Home center chains and independent lumberyards serve DIY and small contractor segments with broken-case availability and specification guidance on sheathing and finish panel selection.
- Direct Sales:Large millwork shops and manufactured housing producers source full truckloads or railcar quantities directly from OSB and plywood mills, bypassing distributor margins on high-volume, repetitive specifications.
- Online:Emerging digital procurement platforms connect architectural millwork buyers with custom veneer and specialty plywood suppliers, though structural panel commoditization limits e-commerce penetration.
Wholesalers retain channel control in structural panels. Direct sales are expanding most quickly in manufactured housing and modular construction verticals.
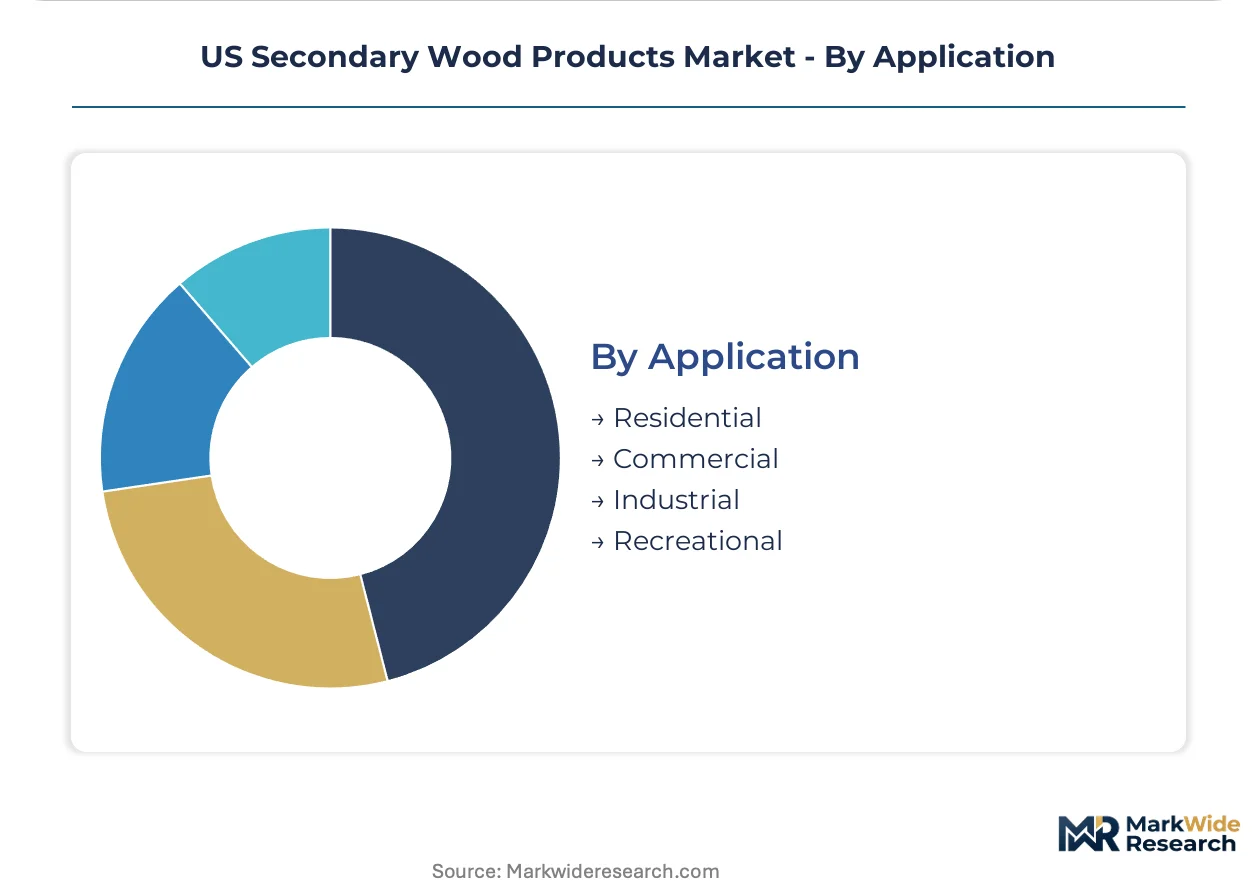
Application:
End-use environment governs moisture resistance specifications and code compliance burdens across engineered wood product selections.
- Residential:Single-family and multi-family housing construction consumes majority structural panel volume through wall sheathing, roof decking, and subfloor applications, with Southeast permit activity driving regional production scheduling.
- Commercial:Institutional and retail builds specify fire-rated and moisture-resistant panels with documented Chain-of-Custody for LEED and Biopreferred compliance, narrowing supplier qualification pools.
- Industrial:Manufacturing facility construction and material handling applications utilize industrial-grade plywood for concrete forming and equipment mounting substrates.
- Recreational:RV, boat, and specialty vehicle manufacturing demand lightweight, moisture-resistant panel cores with formaldehyde emission profiles meeting confined-space air quality standards.
Residential anchors demand volume. Commercial applications are gaining specification intensity through green building procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential construction buyers concentrate in the Southeast manufacturing corridor, where timber supply and mill capacity cluster across Georgia, Alabama, and North Carolina. Specification-grade procurement teams in commercial and federal channels filter vendor selection toward EPA Title VI certified producers with documented Chain-of-Custody credentials.
Southeast Manufacturing Corridor
Georgia, Alabama, and North Carolina anchor national engineered wood panel production through integrated timberland-to-mill operations. EPA Title VI formaldehyde emission standards under TSCA compress bonded wood product specifications, forcing reformulation investments. The Atlanta-Greenville corridor hosts Georgia-Pacific and Weyerhaeuser distribution networks servicing recovering housing starts with rapid-turn structural panel shipments.
Pacific Northwest
Washington and Oregon housing markets show gap density for specification-grade veneer products serving furniture-grade channels. USDA Biopreferred procurement mandates filter federal contract awards toward Chain-of-Custody certified producers. The Portland-Seattle corridor concentrates custom millwork shops facing CNC programming skill scarcity in CAD-CAM integration for complex architectural routing.
Southwest
Texas and Arizona residential construction pulls engineered wood panel orders through distributor networks serving multi-family and light commercial builds. OSHA wood dust exposure limits shape factory ventilation investments across manufacturing facilities. The Dallas-Houston corridor attracts asset-light leasing models for CNC routing equipment lowering capital barriers for mid-scale secondary wood processors.
Midwest
Illinois, Michigan, and Ohio absorb structural panel volume through manufactured housing and modular construction segments expanding engineered panel specifications. Pending TSCA Section 6 risk evaluations for formaldehyde resins threaten reformulation costs without warning. The Chicago-Detroit corridor concentrates industrial-grade plywood demand for concrete forming and equipment mounting substrates in manufacturing facility construction.
Northeast Corridor
New York, Pennsylvania, and New England commercial builds specify fire-rated and moisture-resistant panels with documented Chain-of-Custody for LEED compliance. California Air Resources Board ATCM Phase 2 benchmarks influence specification standards beyond state borders. The Boston-New York corridor narrows supplier qualification pools to pre-qualified mills with emission-compliant OSB and plywood for institutional builds.
US Secondary Wood Products Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven integrated producers anchor volume positions while custom millwork specialists capture premium margin pools. The vendor base separates into three strategic archetypes: timberland-integrated manufacturers controlling fiber sourcing, distributed mill networks sustaining rapid turnaround on architectural orders, and specification-grade finishers targeting federal procurement channels. Dominant competitive moves include backward integration into captive timberland supply and portfolio diversification toward low-emitting adhesive alternatives.
Among US-based integrated producers, Georgia-Pacific, Weyerhaeuser Company, and Universal Forest Products exemplify distinct positioning archetypes. Georgia-Pacific anchors large-volume OSB and plywood supply through upstream control over timberland fiber sourcing. Weyerhaeuser Company occupies a position in structural panel distribution by controlling rail and truck logistics into major construction markets. Universal Forest Products represents the distributed mill network model, sustaining rapid turnaround capabilities on custom architectural millwork orders through geographic dispersion.
| Leading Market Players |
|---|
| Herman Miller |
| Universal Forest Products |
| Ashley Furniture Industries |
| West Fraser Timber |
| Georgia-Pacific |
| Steelcase |
| Weyerhaeuser Company |
| Kronospan |
| HNI Corporation |
| Others |
Cost & Logistics Intelligence
Formaldehyde resin input volatility determines both pricing tier spreads and supply chain shape across the US secondary wood products market. Petrochemical feedstock fluctuations compress margins on particle board and OSB production while forcing reformulation investments toward low-emitting adhesive alternatives.
Pricing Analysis
Cost-plus contracts indexed to methanol and urea spot markets dominate structural panel transactions between Southeast mills and national distributors. Three-tier pricing structure across premium, standard, and economy levels separates Chain-of-Custody certified veneer from commodity OSB and particle board substrates. Pricing pressure stems from phenolic resin cost volatility squeezing margins on medium-density fiberboard production. Manufactured housing producers exhibit highest price sensitivity due to repetitive high-volume specifications, while federal procurement channels absorb premium pricing for Biopreferred-certified architectural millwork.
Supply Chain Analysis
Tariff exposure on Canadian softwood lumber imports dominates supply chain risk calculations for US plywood manufacturers dependent on cross-border veneer supply. Fiber sourcing concentrates in Georgia, Alabama, and North Carolina timberland bases controlled by integrated producers. Raw material dependencies include phenolic resins, urea-formaldehyde adhesives, and wax emulsions for moisture resistance. Distribution runs through regional lumber wholesalers consolidating truckload volumes from Southeast mills for redistribution to contractor yards and retail locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment leasing and aftermarket technical services represent faster-expanding revenue layers than commodity panel production, creating service-attach opportunities for capital-light market participants.
For Market Incumbents: Insulate margin positions by deepening upstream control over timberland fiber supply in the Southeast manufacturing corridor while accelerating low-emitting adhesive R&D ahead of pending TSCA Section 6 formaldehyde risk evaluations. Prioritize Chain-of-Custody certification investments to defend federal procurement channel access against emerging biobased resin competitors.
For New Entrants and Emerging Players: Underpenetrated specification-grade veneer markets in Washington and Oregon represent the most penetrable entry point for furniture-grade channel penetration. Asset-light CNC routing equipment leasing models lower capital barriers for custom architectural millwork shops serving Pacific Northwest housing markets. Target direct sales relationships with manufactured housing producers expanding engineered panel specifications beyond traditional stick-frame residential construction.
For Investors and Strategic Acquirers: EPA Title VI compliance timeline compression reshapes the acquisition landscape toward certified producers with pre-qualified third-party testing documentation. Long-term viability centers on integrated timberland-to-mill operations with demonstrated low-emitting resin formulation capabilities. Monitor USDA Biopreferred procurement mandate expansion as the primary inflection signal for contract award concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberland Supply | Georgia-Pacific and Weyerhaeuser anchor fiber cost control through captive timberland bases. |
| Low-Emitting Adhesive Reformulation | Soy-based and lignin-bonded resin systems reduce formaldehyde dependency under EPA Title VI pressure. |
| Chain-of-Custody Certification Investment | Forest Stewardship labeling filters federal and commercial procurement specifications toward qualified mills. |
| CNC Equipment Leasing Expansion | Asset-light models lower capital barriers for mid-scale processors entering custom architectural millwork. |
| Direct Sales Channel Development | Manufactured housing producers source full truckloads directly from OSB mills, bypassing distributor margins. |
Research Approach
Initial hypotheses were tested against primary input from mill operations managers, resin supplier technical directors, lumber distributor procurement leads, and architectural millwork shop owners and refined through secondary validation against EPA TSCA filing databases, USDA Biopreferred product registry data, Forest Stewardship Council chain-of-custody audit records, and SEC 10-K disclosures from integrated timberland operators. Bottom-up production capacity modeling and top-down construction spending triangulation anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window. Segmentation dimensions modeled include product type, end-user application, distribution channel, and regional manufacturing corridor concentration. CAGRs were derived from housing start recovery trajectories, resin cost pass-through elasticity, and certification adoption curves. Industry-specific forecast inputs incorporated Southeast timber supply availability and modular construction penetration rates.
Practitioners should monitor EPA formaldehyde risk evaluation revisions, Canadian softwood lumber tariff adjustments, and biobased adhesive technology convergence for early signals requiring forecast recalibration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Italy Home Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
North America Slide Rails Market
Furniture
Kids Storage Furniture Market
Furniture
Lecterns Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
Vietnam Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Indonesia Home Furniture Market
Furniture
Europe Sustainable Mattress Market
Furniture
Japan Furniture Market
Furniture
Netherlands Home Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Rattan Furniture Market