
 Asia-Pacific Luxury Furniture Market | 2026-2036
Asia-Pacific Luxury Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Luxury Furniture Market Outlook
Digital twin prototyping is rewriting how luxury furniture moves from concept to finished piece, compressing design cycles and reducing material waste before any timber is cut. Shanghai JL&C Furniture Co., Ltd. leverages this workflow to anchor its position in high-commission residential projects across the Yangtze Delta. Wegmans Furniture Industries Sdn Bhd sustains its competitiveness through captive supply of tropical hardwoods, controlling raw material quality from Malaysian forest concessions to finished showroom floors.
Asia-Pacific luxury furniture comprises handcrafted and precision-manufactured interior furnishings built from premium-grade timber, full-grain leather, and engineered metal alloys, typically specifying joinery tolerances below 0.5 millimetres and finishing with multi-layer lacquer or oil systems. These pieces serve residential estates, hospitality suites, and corporate reception environments where spatial identity carries commercial or social signalling value. Sofas and chairs dominate current revenue pools, reflecting sustained investment from hospitality developers refurbishing boutique properties across Southeast Asia. Leather and solid wood materials command premium positioning, though upholstery variants are gaining traction among younger affluent buyers seeking modular flexibility in urban apartments.
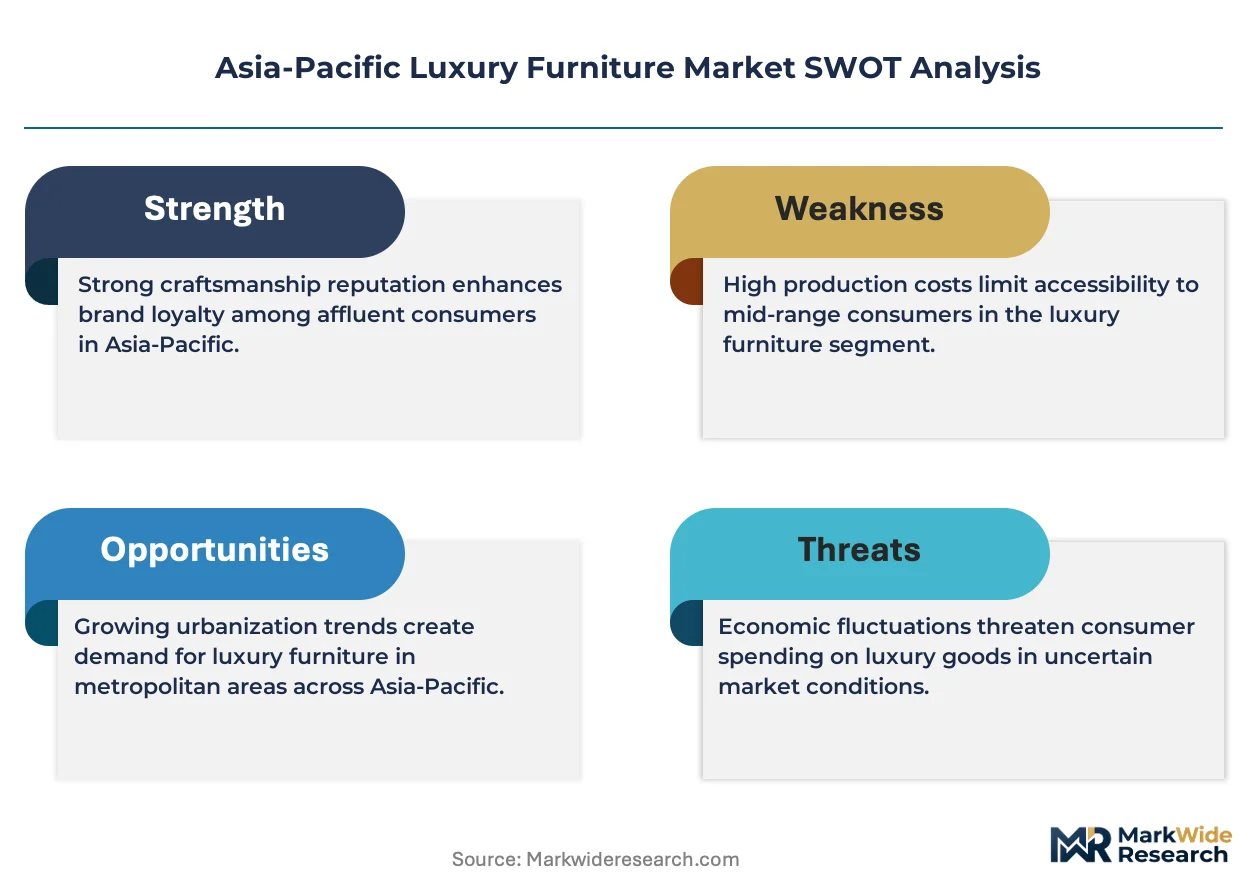
China's SAMR enforces GB standards for formaldehyde emissions in wood products, effectively screening lower-grade imports from regional competitors while elevating compliance costs for domestic workshops. Japan's METI building energy codes indirectly shape furniture specification by mandating thermal performance that dictates interior spatial planning and fixture sizing. India's BIS certification requirements for imported timber species create procedural friction that favours established distributors with established customs relationships. Stakeholders must monitor how evolving dual carbon goals across Beijing, Tokyo, and New Delhi recalibrate material sourcing protocols and transport mode selection for finished goods.
Market Dynamics
Digital twin prototyping is compressing design-to-delivery cycles across the Asia-Pacific luxury furniture sector, forcing workshops to retool for simulation-first workflows or cede high-commission residential projects to digitally native competitors.
Growth Catalysts
- India's PLI scheme:Wood-based manufacturing clusters are redirecting artisanal capacity toward export-grade production, expanding factory-scale output from traditional craft centers.
- Second-home ownership in China's tier-one cities:Affluent professionals sustain consistent commissioning of custom interiors, creating recurring demand for bespoke residential furnishings.
- Tropical hardwood captive supply:Malaysian forest concessions provide controlled raw material quality from stump to showroom, insulating vertically integrated producers from spot-market volatility.
Market Restraints
- GB formaldehyde standards:China's SAMR emission rules elevate compliance costs for domestic workshops while screening lower-grade regional imports from competing suppliers.
- BIS timber certification friction:India's species-specific import requirements create procedural delays that favor established distributors with hardened customs relationships over new entrants.
- Joinery tolerance ceilings:Sub-0.5 millimetre precision specifications for premium-grade pieces limit viable supplier pools to capital-intensive workshops with CNC capability.
Strategic Opportunities
- Modular upholstery systems:Younger affluent buyers in urban apartments are displacing fixed-frame pieces with reconfigurable seating, opening white space for flexible interior solutions.
- Dual carbon protocol alignment:Beijing's transport mode recalibration creates first-mover advantage for manufacturers optimizing finished-goods logistics around rail and short-sea shipping.
- Boutique hospitality refurbishment:Southeast Asian property developers are accelerating upholstery replacement cycles, expanding addressable demand beyond residential estates.
Industry Challenges
- Artisan-to-digital workflow migration:Traditional joiners face capability gaps in CAD-to-CAM translation, slowing adoption of digital twin pipelines in established workshops.
- Multi-layer finishing system capex:Oil and lacquer application lines require substantial equipment investment, fragmenting quality tiers between capitalized factories and craft ateliers.
- Cross-border timber traceability:Chain-of-custody documentation for Malaysian hardwoods demands dedicated compliance personnel, raising fixed costs for mid-scale exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Luxury Furniture Market |
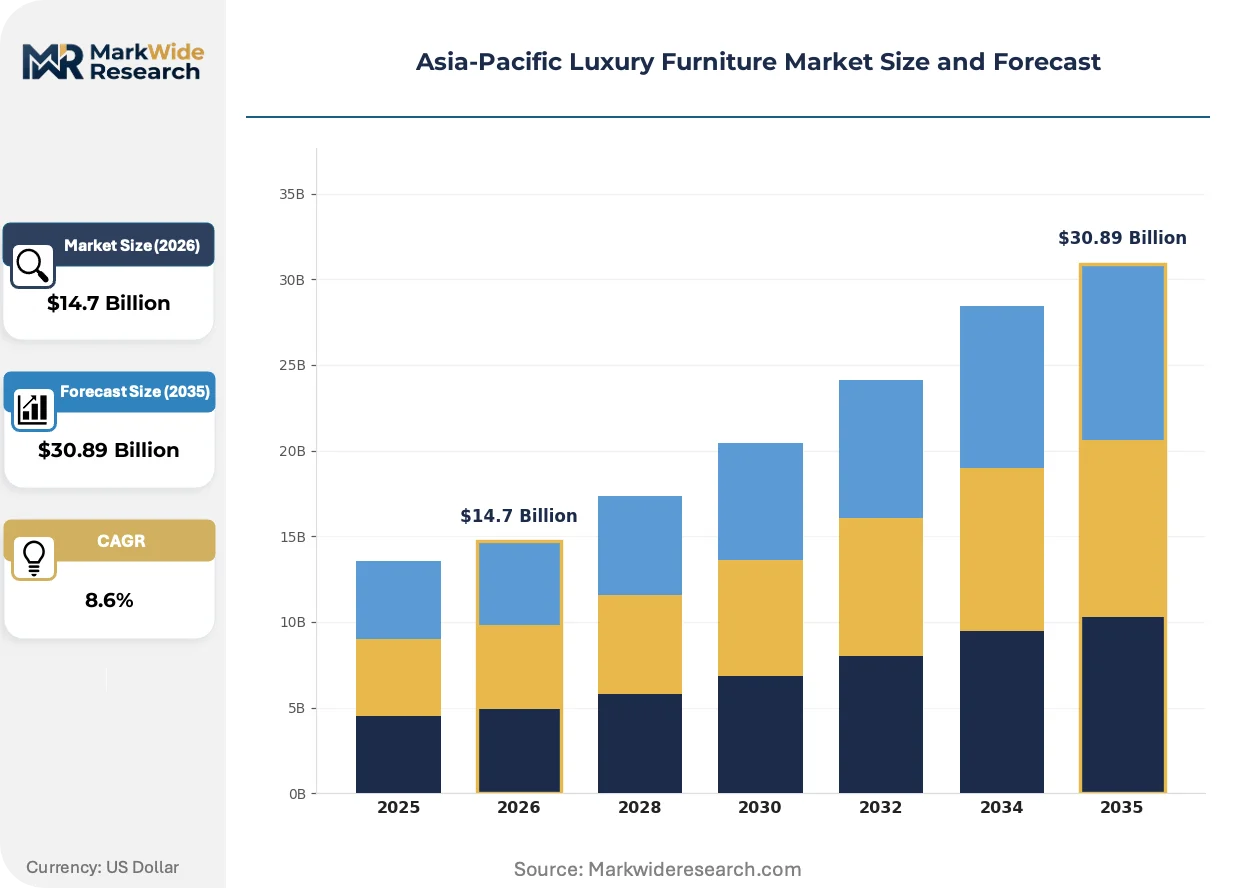
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Leather, Upholstery Style: Modern, Traditional, Contemporary, Rustic Distribution Channel: Online Retail, Showrooms, Specialty Stores, Auctions |
| Companies Covered | Falcon Incorporation PTE Ltd., Kovacs Design Furniture, Shanghai JL&C Furniture Co., Ltd., Wegmans Furniture Industries Sdn Bhd, Far East Furniture, PT. Wirasindo Santakarya, Dynamic Furniture Industries (M) Sdn Bhd, Shanghai Casagi Furniture Ltd., McMichael Furniture, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Luxury Furniture Market Strategic Shifts
Computational design tools and sustainability mandates are converging to reshape how premium furniture is specified, produced, and delivered across Asia-Pacific residential and hospitality verticals.
Parametric modeling software is digitizing the conceptual phase of bespoke furniture development, enabling Shanghai-based residential designers to iterate joinery configurations without physical prototyping. Ultra-high-net-worth households in Singapore and Sydney now expect photorealistic renderings before commissioning six-figure pieces. This capability compression is collapsing traditional design cycles from months to weeks.
China's SAMR enforcement of GB formaldehyde emission standards is restructuring competitive access to the mainland market, disqualifying uncertified regional suppliers while forcing domestic workshops into costly lab-testing protocols. Solid wood and engineered panel producers face divergent compliance burdens depending on adhesive chemistry. Japanese hospitality specifiers are now requiring GB-equivalent documentation for imported fixtures.
Direct-to-designer platforms are displacing traditional gallery-and-showroom distribution for high-commission residential projects across the Yangtze Delta. Affluent buyers in tier-one cities now source bespoke pieces through architect-curated digital portals rather than brick-and-mortar flagships. This channel migration concentrates margin capture with digitally fluent workshops capable of virtual presentation and remote specification.
Asia-Pacific Luxury Furniture Market Segmentation
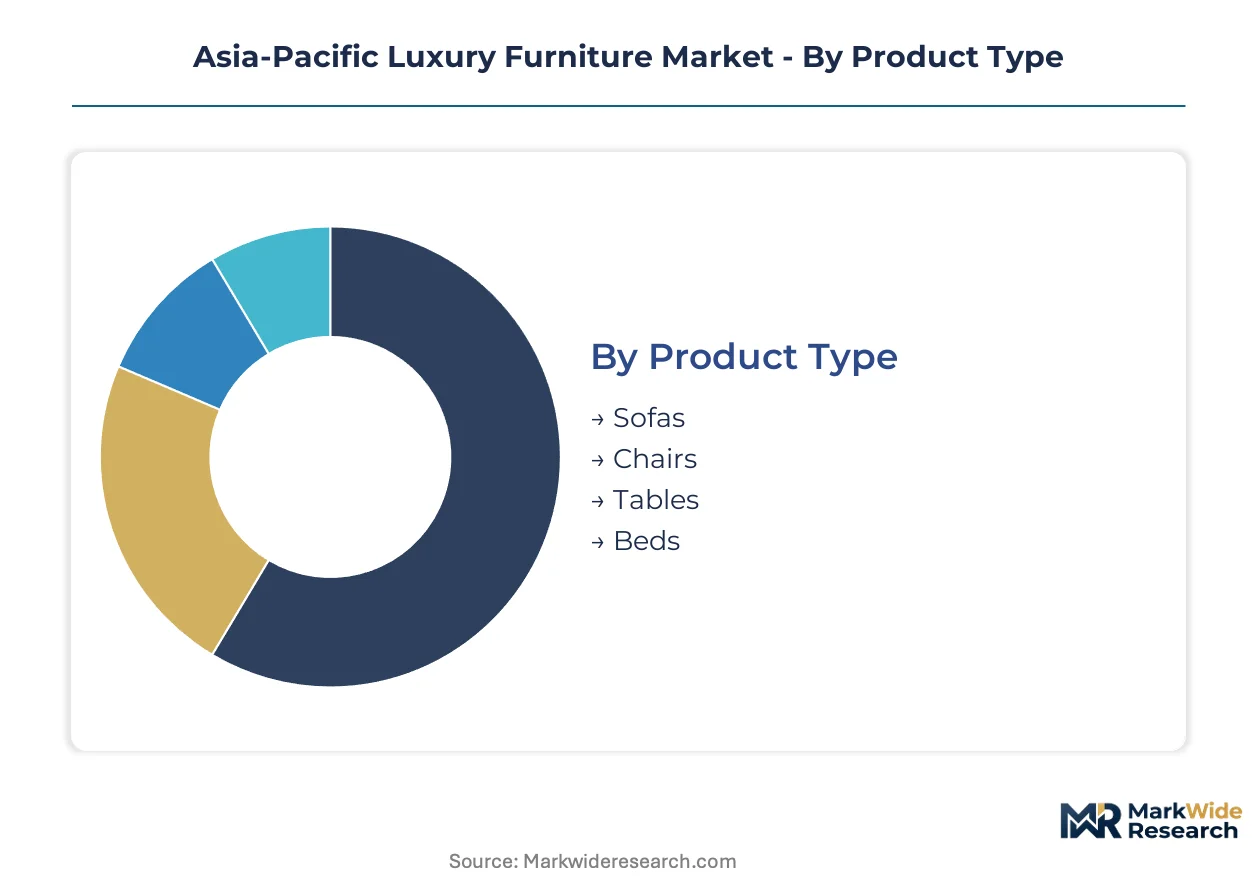
Luxury furniture procurement patterns diverge sharply across product categories, material specifications, and purchase channels. Understanding these fault lines reveals where margin pools concentrate and which segments warrant capacity investment versus selective participation.
Product Type:
Application context determines specification intensity and replacement frequency across residential and hospitality verticals.
- Sofas:Multi-layer upholstery systems with engineered spring cores and full-grain leather or performance fabric covers dominate hospitality refurbishment cycles across Southeast Asian boutique properties. Developers in Bangkok and Jakarta commission these pieces in volume for lobby and suite renovations.
- Chairs:Dining and accent categories specify joinery tolerances below 0.5 millimetres, with solid wood frames and hand-finished surfaces commanding premium positioning in Singapore and Sydney residential estates. Ultra-high-net-worth households commission these as signature pieces for entertaining spaces.
- Tables:Dining and conference surfaces emphasize timber slab construction with live-edge or book-matched veneer aesthetics.
- Beds:Platform and four-poster configurations integrate upholstered headboards with precision-milled hardwood frames.
Sofas command the established base. The steepest expansion runs through chairs as affluent professionals prioritize statement seating for compact urban residences.
Material:
Cost tier and compliance burden stratify competitive positioning from artisanal ateliers to capitalized factory operations.
- Wood:Tropical hardwoods from Malaysian forest concessions supply the premium tier, with chain-of-custody documentation demanded by Japanese hospitality specifiers. China's SAMR enforces GB formaldehyde emission standards that screen uncertified regional imports and elevate lab-testing costs for domestic workshops.
- Leather:Full-grain hides with vegetable-tanned finishes specify thickness above 1.4 millimetres for residential commissioning in Shanghai and Beijing tier-one markets. Affluent buyers accept six-month lead times for bespoke upholstery matched to interior palettes.
- Metal:Engineered alloys in brass and bronze deliver structural elements and accent detailing for contemporary collections.
- Upholstery:Performance fabrics and modular textile systems address younger buyers seeking reconfigurable flexibility in urban apartments.
Wood commands the established base. The steepest expansion runs through upholstery as modular systems displace fixed-frame pieces among demographic cohorts prioritizing adaptability.
Style:
Customer type and spatial signalling intent shape specification preferences across generational and geographic divides.
- Modern:Clean lines and minimal ornamentation specify engineered materials and precision manufacturing, aligning with architect-curated digital portals in the Yangtze Delta. Direct-to-designer platforms concentrate margin capture with workshops fluent in parametric modeling and photorealistic rendering.
- Traditional:Hand-carved detailing and period-appropriate joinery sustain artisanal capacity in Indian wood-based manufacturing clusters supported by PLI scheme incentives. Export-grade production redirects craft heritage toward standardized output for Middle Eastern and European markets.
- Contemporary:Hybrid aesthetics blend modern silhouettes with traditional materiality for transitional interiors.
- Rustic:Reclaimed timber and distressed finishes target secondary residences and hospitality concepts emphasizing authenticity narratives.
Traditional commands the established base. Contemporary gains share fastest as designers bridge generational preferences in multi-generational households.
Distribution Channel:
Margin capture and customer acquisition economics diverge across physical and digital touchpoints.
- Showrooms:Flagship galleries in Shanghai, Singapore, and Sydney sustain high-commission residential projects where tactile material evaluation precedes six-figure commitments. Vertically integrated producers control presentation quality from Malaysian forest concessions to finished floors.
- Online Retail:Architect-curated digital portals displace brick-and-mortar flagships for affluent tier-one city buyers comfortable with virtual specification and remote commissioning. Workshops investing in digital twin prototyping compress design cycles and reduce material waste before timber cutting.
- Specialty Stores:Boutique retailers with hardened customs relationships navigate India's BIS timber certification requirements.
- Auctions:Secondary market channels liquidate estate collections and limited editions for collector audiences.
Showrooms command the established base. Online retail climbs the fastest as digitally native competitors capture design-to-delivery workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth households concentrate commissioning power across five Asia-Pacific markets, with second-home ownership and hospitality refurbishment driving divergent demand patterns. Each national market operates under distinct regulatory frameworks that reshape competitive access and supplier economics.
China
Affluent professionals in Shanghai and Beijing sustain recurring demand for bespoke residential interiors through tier-one city second-home ownership. SAMR enforcement of GB formaldehyde emission standards elevates compliance costs for domestic workshops while screening uncertified regional imports. The Yangtze Delta industrial cluster anchors high-commission residential project execution for digitally fluent workshops.
India
Export-grade production capacity is expanding from traditional craft centers under PLI scheme incentives for wood-based manufacturing clusters. BIS certification requirements for imported timber species create procedural friction favoring established distributors with hardened customs relationships. Maharashtra and Gujarat factory-scale operations redirect artisanal heritage toward standardized output for Middle Eastern markets.
Japan
METI building energy codes indirectly reshape furniture specification through thermal performance mandates that dictate interior spatial planning and fixture sizing. Hospitality specifiers now require GB-equivalent documentation for imported fixtures, extending Chinese regulatory influence. Tokyo and Osaka metropolitan demand concentrates in compact urban residences requiring precision-manufactured pieces.
Australia
Sydney ultra-high-net-worth households are expanding residential footprints, driving demand for bespoke statement pieces with extended lead-time tolerance. Import regulations align with chain-of-custody documentation requirements for tropical hardwoods, privileging suppliers with Malaysian concession relationships. Melbourne and Brisbane secondary markets follow with lagged adoption patterns.
Singapore
Ultra-high-net-worth household residential expansion drives premium commissioning for entertaining spaces and multi-generational living configurations. Strict import documentation requirements for engineered wood products filter supplier pools to established regional distributors. The city-state functions as a specification hub influencing adjacent Southeast Asian hospitality refurbishment standards.
Asia-Pacific Luxury Furniture Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated structure where digitally fluent workshops capture design-to-delivery workflows while vertically integrated producers defend raw material quality positions. The market stratifies into three archetypes: simulation-first residential specialists, captive-supply tropical hardwood controllers, and architect-curated platform intermediaries. Dominant competitive moves center on digital twin prototyping adoption and backward integration into Malaysian forest concessions.
Among China-based fabricators, Shanghai JL&C Furniture Co., Ltd. and Shanghai Casagi Furniture Ltd. exemplify the digitally native archetype compressing design cycles through parametric modeling workflows. Malaysian producers Wegmans Furniture Industries Sdn Bhd and Dynamic Furniture Industries (M) Sdn Bhd anchor the captive-supply tier controlling tropical hardwood quality from stump to showroom. Singapore-based Falcon Incorporation PTE Ltd. occupies a distribution-intermediary position linking regional production capacity with ultra-high-net-worth residential commissioning.
| Leading Market Players |
|---|
| Falcon Incorporation PTE Ltd. |
| Kovacs Design Furniture |
| Shanghai JL&C Furniture Co., Ltd. |
| Wegmans Furniture Industries Sdn Bhd |
| Far East Furniture |
| PT. Wirasindo Santakarya |
| Dynamic Furniture Industries (M) Sdn Bhd |
| Shanghai Casagi Furniture Ltd. |
| McMichael Furniture |
| Others |
Value Chain & Pricing Dynamics
Malaysian forest concessions controlling tropical hardwood supply anchor margin capture at the premium tier, with vertically integrated producers commanding price premiums through stump-to-showroom quality control that spot-market dependent competitors cannot replicate.
Pricing Analysis
Cost-plus contracts with tropical hardwood indexation dominate high-commission residential projects, with pricing stratifying across premium, standard, and economy tiers based on joinery tolerance precision and GB formaldehyde certification status. Cost compression in the standard tier intensifies as digitally native workshops automate CAD-to-CAM workflows. Hospitality developers exhibit highest price sensitivity due to volume procurement, while ultra-high-net-worth households in Singapore and Sydney demonstrate lowest sensitivity for bespoke statement pieces.
Supply Chain Analysis
Tariff exposure between Malaysia and India dominates supply chain risk planning for regional exporters navigating divergent customs protocols. Raw material flows draw from Malaysian hardwood concessions, Indian PLI-supported manufacturing clusters, and Chinese Yangtze Delta precision workshops. Single-source vulnerability concentrates in tropical hardwood species with restricted chain-of-custody documentation. Distribution runs through architect-curated digital portals and flagship galleries in Shanghai, Singapore, and Sydney.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through GB formaldehyde certification and BIS timber import requirements creates durable barriers against unqualified competitors.
For Market Incumbents: Entrench position through backward integration into Malaysian forest concessions and captive supply chains that insulate against spot-market volatility. Invest in multi-layer finishing system capacity to maintain quality tier separation from craft ateliers. Counter the threat from digitally native competitors by embedding parametric modeling capabilities into established workshops.
For New Entrants and Emerging Players: India's secondary cities present underpenetrated white space where PLI scheme incentives reduce capital barriers for export-grade production. Modular upholstery systems targeting younger affluent buyers in urban apartments offer the most penetrable entry vector. Pursue direct-to-designer platform partnerships rather than brick-and-mortar flagship investments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital twin prototyping infrastructure, favoring scaled players with existing CNC capability. Long-term viability over a multi-year horizon rests on identifying workshops with hardened customs relationships and established BIS certification pathways. Monitor dual carbon protocol alignment as the signal to watch for logistics optimization advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Concessions | Malaysian stump-to-showroom control eliminates spot-market volatility for premium hardwood supply. |
| Digital Twin Prototyping Adoption | Parametric modeling compresses design cycles for Yangtze Delta high-commission residential projects. |
| GB Formaldehyde Certification Investment | SAMR compliance opens mainland China access while screening uncertified regional competitors. |
| Modular Upholstery System Development | Reconfigurable seating captures younger affluent buyers prioritizing urban apartment flexibility. |
| Direct-to-Designer Platform Launch | Architect-curated digital portals displace traditional gallery distribution in tier-one cities. |
Study Parameters
Initial hypotheses were tested against primary input from furniture manufacturing executives, hospitality procurement directors, residential interior designers, and timber supply specialists and refined through secondary validation. Primary fieldwork combined structured interviews across Malaysia, China, India, and Singapore with trade data from customs records and industry association filings. Bottom-up capacity assessments and top-down demand modeling were triangulated to converge on segment-level estimates.
Demand-supply-balance dynamics across the analysis window were modeled through interaction between second-home ownership patterns, hospitality refurbishment cycles, and manufacturing capacity expansion under PLI incentives. Segmentation dimensions included product type, material specification, style category, and distribution channel complexity. CAGRs were derived from fitted growth curves incorporating regulatory enforcement timelines and technology adoption S-curves.
Macroeconomic conditions sit as an overlay; deviation in affluent household wealth effects, hospitality investment cycles, or carbon policy implementation would shift the trajectory. Forecasts reflect documented assumptions on certification timeline compliance and digital workflow adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Saudi Arabia Home Furniture Market
Furniture
Vietnam Furniture Market
Furniture
Armchairs with Footrest Market
Furniture
Portering Chair Market
Furniture
Massive Wood Slabs Market
Furniture
Global Furniture Market
Furniture
Europe School Furniture Market
Furniture
Cabinet Market
Furniture
China Home Furniture Market
Furniture
Mexico Home Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
North America Furniture Market
Furniture
Pedicure Chair Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Entryway Furniture Market