
 US Multifunctional Furniture Market | 2026-2036
US Multifunctional Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
US Multifunctional Furniture Market Analytics
Buyer concentration among urban apartment developers is consolidating around mixed-use projects with sub-500-square-foot units. Resource Furniture anchors the premium Murphy bed segment through Italian manufacturing partnerships. Ashley Furniture Industries leverages its North American distribution network to compete on delivery speed for sofa-bed combinations. Sauder Woodworking Company sustains mid-market positioning through flat-pack logistics and mass retail channel control.
Multifunctional furniture denotes engineered domestic and commercial fixtures designed to perform two or more discrete functions through reconfigurable mechanisms, typically incorporating steel pivot hardware, engineered wood substrates, and high-cycle fabric rated for daily transformation. The category serves spatial constraints in dense housing markets and flexible workspace programming. Sofas with integrated storage and sleeper mechanisms dominate unit volume, while wall-bed systems command the highest margin pools due to installation complexity and customization requirements. Tables with fold, nest, or extend features lead commercial adoption in offices and hotels seeking reconfigurable meeting environments.
The Consumer Product Safety Commission governs tip-over and stability standards for freestanding convertible units, while California Air Resources Board limits formaldehyde emissions from composite wood components used in built-in systems. The EPA's formaldehyde emissions standards under TSCA Title VI shape material sourcing decisions for domestic manufacturers. Stakeholders must monitor evolving municipal density bonuses and accessory dwelling unit ordinances across US metro areas, as these zoning shifts directly determine the addressable footprint for space-optimized furniture specifications.
Market Dynamics
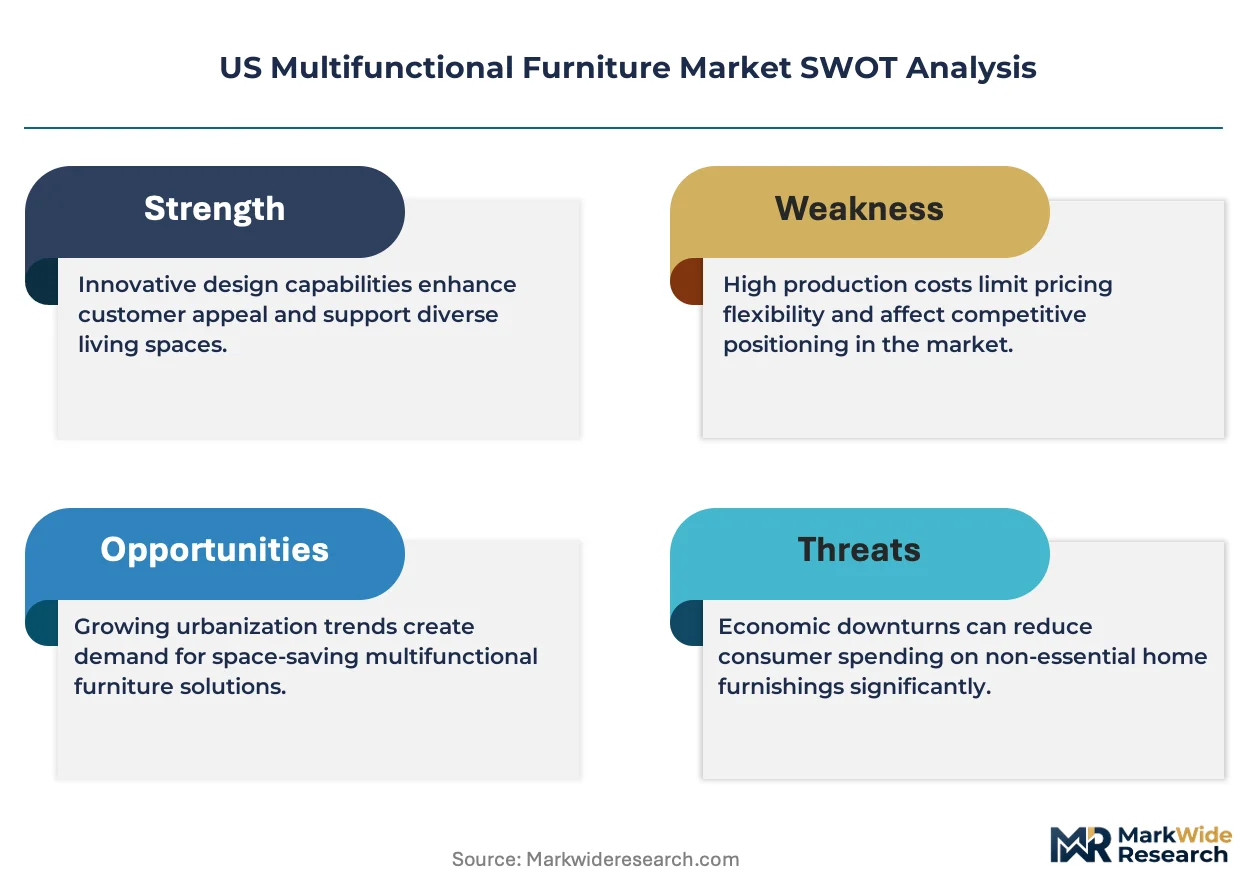
Municipal density bonuses and accessory dwelling unit ordinances across US metro areas are compressing residential square footage, forcing furniture specifications toward convertible mechanisms and vertical storage integration.
Growth Catalysts
- California's Title 24 energy efficiency standards:These codes indirectly shape material specifications for built-in storage units, pushing manufacturers toward lighter engineered substrates that reduce HVAC loads in compact dwellings.
- Seattle and Portland housing stock characteristics:Pacific Northwest urban cores favor convertible living spaces, creating concentrated demand for wall-bed systems and nested table configurations.
- Steel pivot hardware advances:Improved fatigue-rated mechanisms now support daily transformation cycles exceeding 10,000 uses, enabling reliable commercial deployment in hotel and co-working environments.
Market Restraints
- Engineered wood substrate cost volatility:Formaldehyde-compliant composite panels face input price pressure from resin chemistry feedstocks, squeezing mid-market flat-pack producers.
- Installation labor concentration:Wall-bed systems require certified mounting technicians, with qualified installer pools concentrated in coastal metro corridors.
- Tip-over stability compliance:CPSC anchoring mandates for freestanding convertible units add material cost and design constraint without corresponding price elasticity.
Strategic Opportunities
- Texas Sun Belt metro expansion:Dallas and Austin accessory dwelling unit ordinances are creating new addressable footprints for space-optimized furniture specifications in previously underpenetrated markets.
- EPA TSCA Title VI alignment:Domestic manufacturers sourcing certified low-emission substrates can capture preference share from imports facing border compliance friction.
- Direct-to-developer specification channels:Bypassing retail markup by contracting with multifamily project architects during schematic design phases captures margin pool currently absorbed by distribution intermediaries.
Industry Challenges
- Mechatronics integration skill gaps:Furniture engineering talent with combined expertise in timber structures and motorized actuation commands premium compensation in tight labor markets.
- High-cycle fabric certification timelines:Third-party testing for daily-transformation upholstery durability extends product development schedules by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Multifunctional Furniture Market |
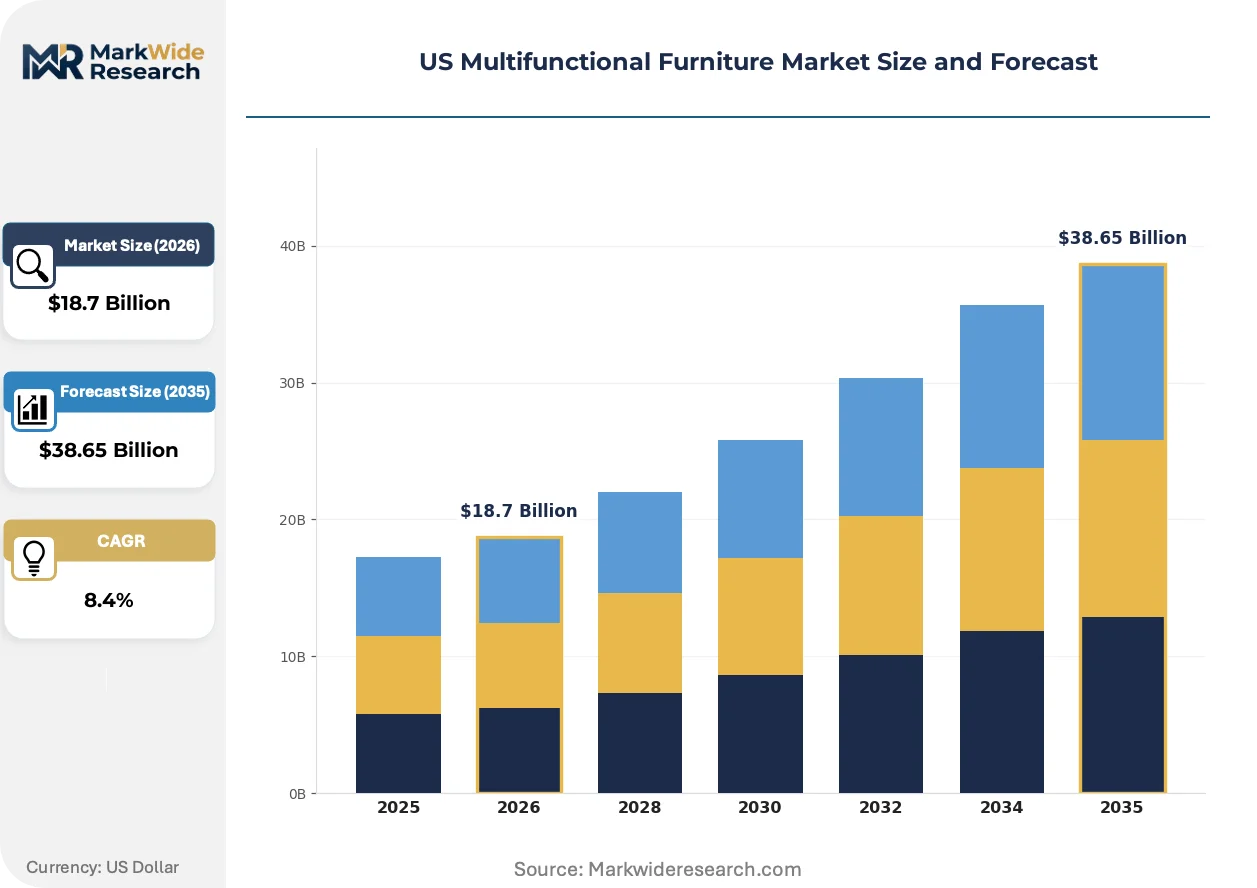
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Tables, Chairs Material: Wood, Metal, Plastic, Fabric End User: Residential, Offices, Hotels, Cafes Design Style: Modern, Minimalist, Traditional, Rustic |
| Companies Covered | Murphy Wall Beds Hardware Inc., Resource Furniture, Ashley Furniture Industries, Sauder Woodworking Company, Expand Furniture, IKEA, Milano Smart Living, Comfold, Meco Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Multifunctional Furniture Market Evolving Landscape
Electromechanical actuation and sensor-embedded surfaces are transforming static furniture into responsive environmental infrastructure, collapsing the distinction between fixture and building system.
Pneumatic-assisted lift mechanisms paired with occupancy sensors are rewriting how wall-bed systems deploy in micro-unit residential towers. New York and San Francisco developers specify these configurations for sub-400-square-foot units where manual operation would strain resident ergonomics. The technology is compressing installation timelines and reducing on-site skilled labor dependency.
California Air Resources Board composite wood emissions limits are tightening material sourcing constraints for domestic manufacturers. Producers must maintain chain-of-custody documentation from panel supplier through finished goods, favoring vertically integrated operations with captive substrate production. Built-in storage system categories face the steepest compliance cost escalation due to their higher surface-area-to-volume ratios.
Multifamily developer procurement teams now specify furniture-as-fixed-asset rather than FF&E, extending depreciation horizons and prioritizing 15-year lifecycle durability over 5-year replacement cycles. This shift favors steel-frame convertible mechanisms over wood-pivot alternatives in Texas and Florida rental portfolios. The behavior is most visible in institutional investor-owned apartment REITs with centralized capital planning functions.
US Multifunctional Furniture Market Segmentation
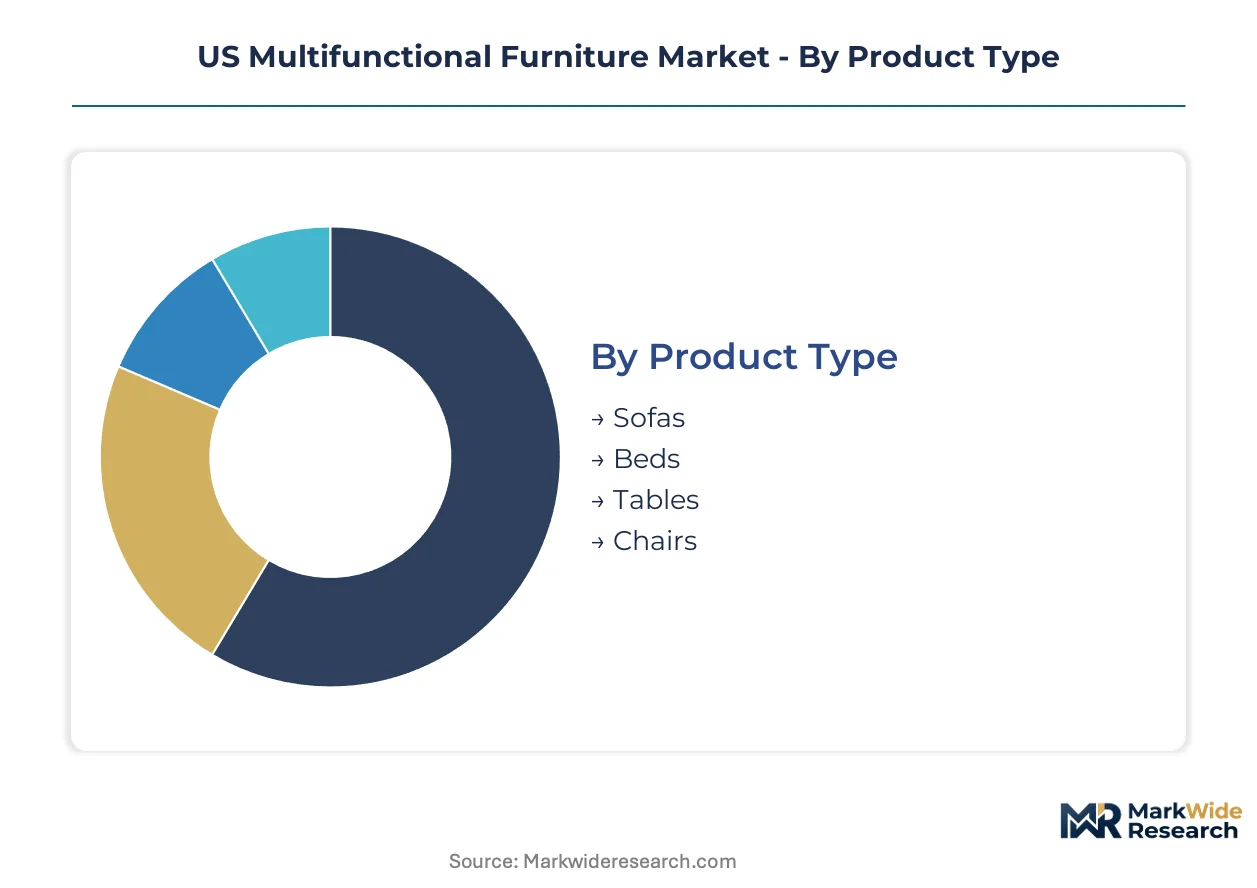
Segmentation in the US multifunctional furniture market reveals how conversion mechanisms and material specifications map to distinct use cases across housing density gradients. Product architecture choices determine whether units ship flat-pack for consumer assembly or require certified installation as fixed building elements.
Product Type:
Integration depth varies sharply: standalone convertible pieces dominate residential channels, while built-in systems anchor commercial specifications requiring architectural coordination.
- Sofas:Engineered frames incorporate steel sleeper mechanisms and under-seat storage compartments rated for daily cycling. Demand concentrates in New York and San Francisco sub-500-square-foot apartments where seating-to-sleeping conversion replaces dedicated guest rooms. Ashley Furniture Industries competes on delivery velocity through North American distribution nodes.
- Beds:Wall-bed systems with pneumatic-assisted lift mechanisms require structural wall anchoring and occupancy sensor integration. Seattle and Portland multifamily developers specify these for micro-units under 400 square feet. Resource Furniture anchors the premium segment through Italian manufacturing partnerships for hardware.
- Tables:Fold, nest, and extend configurations serve reconfigurable meeting environments in offices and hotels. Commercial procurement favors steel-frame mechanisms over wood-pivot alternatives for 15-year depreciation cycles.
- Chairs:Compact folding and stacking designs address auxiliary seating needs in accessory dwelling units and co-working lounges. Sauder Woodworking Company sustains mid-market positioning through flat-pack logistics.
Sofas lead volumes today; beds are gaining share fastest through developer specification channels.
Material:
Cost tier stratification separates premium steel-and-fabric combinations from economy flat-pack alternatives, with compliance burdens falling heaviest on composite wood substrates.
- Wood:Engineered panels dominate built-in storage systems, with CARB Phase 2 and EPA TSCA Title VI compliance documentation required for formaldehyde emissions. California's Title 24 energy efficiency standards indirectly push specifications toward lighter substrates that reduce HVAC loads in compact dwellings.
- Metal:Steel pivot hardware with 10,000-plus cycle ratings enables reliable commercial deployment in hotel and co-working environments. Texas and Florida rental portfolios increasingly specify steel-frame mechanisms for institutional investor depreciation schedules.
- Plastic:Polymer components reduce weight in portable nesting and folding configurations for temporary event use. Limited penetration in permanent residential fixtures due to durability perception gaps.
- Fabric:High-cycle upholstery rated for daily transformation requires third-party certification extending product development timelines. CPSC tip-over stability mandates add material cost without corresponding price elasticity in freestanding convertible units.
Wood leads volumes today; metal is climbing the fastest through commercial specification shifts.
End User:
Application context determines whether furniture ships as FF&E or capitalizes as fixed asset, with depreciation horizon driving mechanism selection.
- Residential:Urban apartment dwellers in dense coastal metros drive adoption of space-saving solutions. Municipal density bonuses and ADU ordinances compress square footage, forcing specifications toward vertical storage integration.
- Offices:Reconfigurable meeting environments demand tables with rapid deployment features. Steel pivot hardware advances support daily transformation cycles exceeding 10,000 uses in co-working environments.
- Hotels:Extended-stay and micro-unit properties specify wall-bed systems with electromechanical actuation. Pneumatic-assisted mechanisms reduce on-site skilled labor dependency during installation.
- Cafes:Limited commercial penetration due to static seating preferences; occasional nesting table deployment for event reconfiguration.
Residential leads volumes today; offices are expanding most quickly through flexible workspace programming.
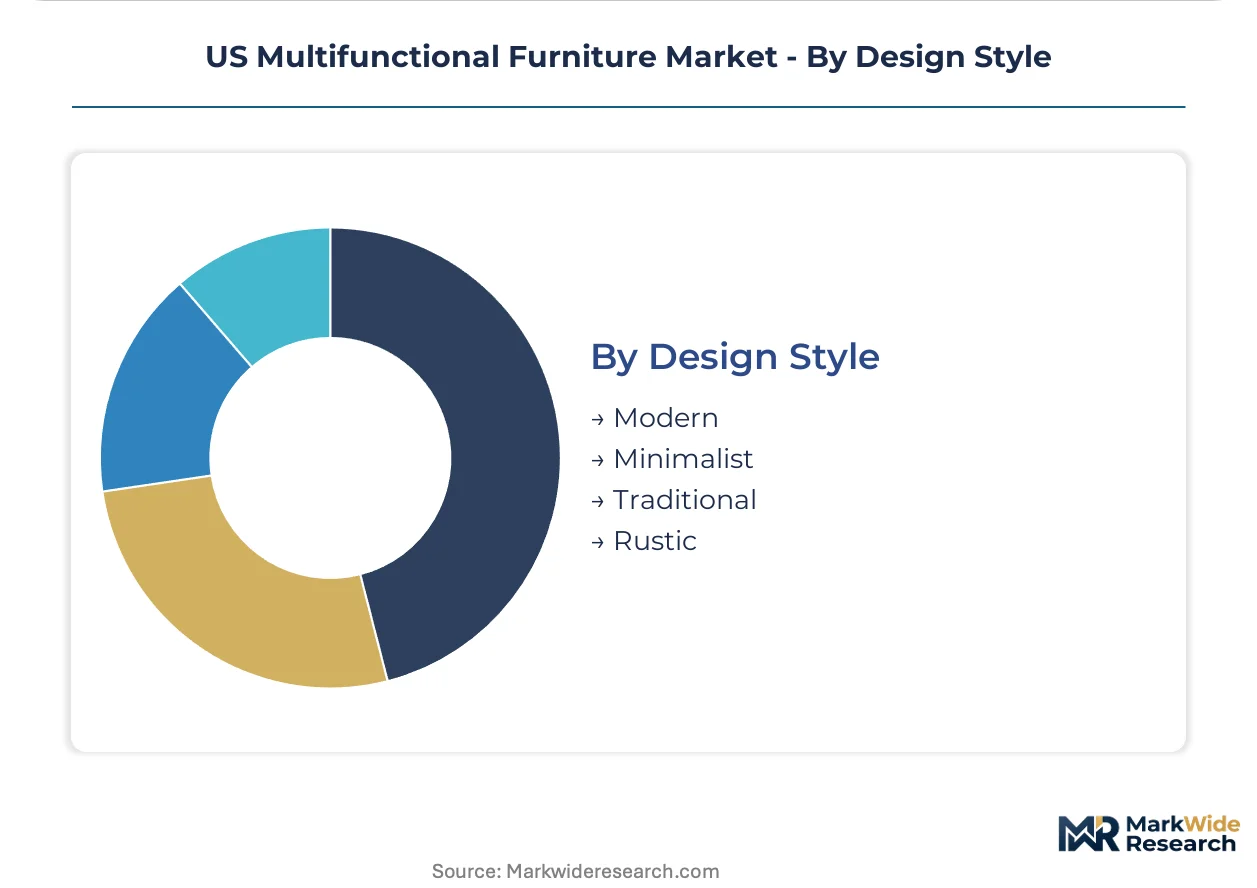
Design Style:
Maturity gradients separate established aesthetic categories from emerging minimalist specifications favored by institutional developers.
- Modern:Clean lines and concealed hardware dominate Pacific Northwest demand in Seattle and Portland housing stock. Built-in storage integration favors this aesthetic for architectural cohesion.
- Minimalist:Reduced visual mass through wall-bed and hidden storage configurations aligns with sub-400-square-foot unit economics. Fastest-growing specification among New York and San Francisco developers.
- Traditional:Ornate detailing in wood-pivot mechanisms retains share in secondary markets with less density pressure. Higher maintenance requirements limit commercial adoption.
- Rustic:Reclaimed wood aesthetics face CARB compliance friction for formaldehyde emissions documentation. Niche positioning in boutique hospitality rather than scaled residential deployment.
Modern leads volumes today; minimalist is gaining share fastest through institutional developer procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Title 24 energy codes and Texas ADU ordinances pull demand in divergent directions, with coastal metros prioritizing lightweight engineered substrates while Sun Belt cities emphasize steel-frame durability for rental depreciation schedules.
California
Los Angeles and San Francisco micro-unit developers specify pneumatic-assisted wall-bed systems for sub-400-square-foot inventory. The California Air Resources Board enforces CARB Phase 2 formaldehyde limits on composite wood substrates, forcing documentation through finished goods. Sacramento's ADU incentive programs are compressing residential square footage and accelerating vertical storage integration specifications.
Texas
Dallas and Austin multifamily REITs favor steel-frame convertible mechanisms to satisfy institutional investor 15-year depreciation horizons. Municipal density bonuses in Houston are expanding the addressable footprint for space-optimized furniture in previously underpenetrated corridors. San Antonio accessory dwelling unit ordinances are creating concentrated demand clusters for sofa-bed combinations in rental portfolios.
New York Metro
Manhattan and Brooklyn developers specify Murphy bed systems with occupancy sensor integration for sub-500-square-foot luxury units. The Consumer Product Safety Commission tip-over stability mandates add material cost to freestanding convertible units without corresponding price elasticity. Queens and the Bronx are seeing procurement teams specify furniture-as-fixed-asset rather than FF&E to extend depreciation schedules.
Pacific Northwest
Seattle and Portland housing stock characteristics favor convertible living spaces with nested table configurations. Washington State energy codes indirectly shape material specifications toward lighter substrates that reduce HVAC loads in compact dwellings. Portland's micro-unit tower pipeline is concentrating demand for electromechanical actuation systems that reduce on-site skilled labor dependency.
Florida
Miami and Tampa extended-stay hotel developers specify wall-bed systems with rapid deployment features for flexible inventory management. The EPA's TSCA Title VI formaldehyde standards shape material sourcing decisions for domestic manufacturers supplying the region. Orlando's co-working space expansion is driving commercial procurement of tables with fold and extend mechanisms rated for 10,000-plus transformation cycles.
US Multifunctional Furniture Market Competitive Landscape
Italian hardware specialists anchor the premium tier; North American mass-market fabricators hold volume positions through distribution density. The vendor base stratifies across three tiers: electromechanical system integrators at the top, steel-pivot mechanism assemblers in the mid-market, and flat-pack logistics operators at the economy level. Two dominant competitive moves are reshaping positioning: direct-to-developer specification channel development bypassing retail markup, and backward integration into certified low-emission substrate production to capture compliance preference share.
Within the premium-tier vector, Resource Furniture occupies a position exemplifying Italian manufacturing partnerships for fatigue-rated hardware. Ashley Furniture Industries and Sauder Woodworking Company represent contrasting scale archetypes—one leveraging North American distribution velocity for sofa-bed combinations, the other sustaining mid-market positioning through flat-pack logistics and mass retail channel control. Murphy Wall Beds Hardware Inc. anchors the specialized wall-bed installation segment where certified mounting technician networks concentrate in coastal metro corridors.
| Leading Market Players |
|---|
| Murphy Wall Beds Hardware Inc. |
| Resource Furniture |
| Ashley Furniture Industries |
| Sauder Woodworking Company |
| Expand Furniture |
| IKEA |
| Milano Smart Living |
| Comfold |
| Meco Corporation |
| Others |
Value Network & Pricing Analysis
Multifamily developer procurement teams concentrated in coastal metros anchor pricing power through direct-to-architect specification channels, compressing retail markups and favoring contract-based project pricing over unit transactional models. This buyer concentration forces manufacturers to absorb compliance cost escalations from CARB Phase 2 and EPA TSCA Title VI substrate certification without full pass-through elasticity.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for steel-frame convertible mechanisms as regional fabrication scales to serve Sun Belt REIT depreciation schedules. Three-tier pricing structure across premium electromechanical systems, standard steel-pivot assemblies, and economy flat-pack alternatives stratifies the market, with differentiation driven by cycle-rating certification and installation service bundling. Cost compression in the mid-market flat-pack tier intensifies because engineered wood substrate resin chemistry feedstocks face volatility, while premium wall-bed systems with Italian hardware partnerships maintain price inelasticity. Price sensitivity concentrates among mass-market retail consumers; institutional developers with 15-year depreciation horizons prioritize lifecycle durability over unit cost.
Supply Chain Analysis
Freight cost differentials between Italian hardware imports and domestic steel fabrication shape regional competitive positioning, with Pacific Northwest and Northeast corridors absorbing higher landed costs for fatigue-rated pivot mechanisms. Manufacturing draws from Italy for premium electromechanical hardware, China for engineered wood substrate feedstocks, and domestic US fabrication for steel-frame assemblies serving Texas and Florida rental portfolios. Raw material dependencies rest on cold-rolled steel coil, formaldehyde-compliant composite panels, and high-cycle upholstery textiles. Single-source vulnerability concentrates in Italian hardware partnerships for pneumatic-assisted lift systems. Distribution runs through direct-to-developer specification channels bypassing traditional retail intermediaries, with certified installer networks concentrated in coastal metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as multifamily developer procurement shifts toward 15-year lifecycle specifications and electromechanical actuation systems displace manual mechanisms in micro-unit towers.
For Market Incumbents: To counter margin compression from engineered wood substrate cost volatility, secure backward integration into CARB-certified panel production or captive resin chemistry supply. Prioritize direct-to-architect specification channel control in Texas Sun Belt metros where ADU ordinances are expanding addressable footprints, using certified installer network density as a defensive moat against flat-pack competitors. For New Entrants and Emerging Players: Enter via San Antonio and Houston accessory dwelling unit corridors where municipal density bonuses have created concentrated demand clusters previously underpenetrated by established coastal players. Target sofa-bed combinations for rental portfolios with flat-pack logistics and rapid delivery velocity as the primary go-to-market angle, bypassing the certified installation barrier that protects wall-bed incumbents. For Investors and Strategic Acquirers: Multifamily REITs with centralized capital planning functions are the most active acquirer in this space, seeking captive furniture specification capabilities to control project-level costs. Long-term viability hinges on electromechanical integration expertise spanning timber structures and motorized actuation. Target acquisition candidates with certified low-emission substrate production and established developer specification relationships. Watch for inflection when steel pivot hardware cycle ratings become standardized procurement criteria across institutional investor portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Substrate Production | Captures compliance preference share from imports facing EPA TSCA Title VI border friction. |
| Direct-to-Developer Specification Channel Development | Bypasses retail markup and captures margin pool absorbed by distribution intermediaries. |
| Electromechanical Actuation System Integration | Collapses installation timelines and reduces coastal metro skilled labor dependency. |
| Certified Installer Network Expansion | Builds defensive moat in wall-bed segments requiring structural anchoring expertise. |
| High-Cycle Fabric Certification Investment | Accelerates product development timelines compressed by third-party testing delays. |
Research Methodology
Bottom-up multifamily developer and commercial procurement modeling reconciled against top-down steel hardware and engineered wood substrate production tracking forms the analytical core of this study. Primary interviews with furniture specification architects, multifamily REIT procurement directors, certified wall-bed installers, flat-pack logistics operators, and CARB compliance officers combined with secondary validation from EPA TSCA Title VI certification databases, SEC 10-K filings of publicly traded furniture manufacturers, municipal ADU ordinance records, and CPSC tip-over stability enforcement actions. Triangulation across these sources ensures demand-side and supply-side estimates converge without material variance.
Historical trendline analysis of wall-bed system deployments, sofa-bed unit shipments, and convertible mechanism cycle-rating certifications established baseline growth patterns across the projection horizon. The analytical framework models segmentation dimensions including product architecture depth (standalone versus built-in), material specification tier (steel-frame versus wood-pivot versus electromechanical), end-use depreciation horizon (FF&E versus fixed-asset), and regional regulatory cluster (CARB-compliant Pacific corridor versus Texas Sun Belt expansion). CAGRs derive from installed base replacement cycles, micro-unit tower pipeline data, and steel hardware fatigue-rating adoption curves.
Inputs from EPA certification databases and municipal zoning records were available through the study window; gaps in real-time multifamily developer procurement decision data introduce uncertainty bands around specification timing assumptions. Forecasts reflect modeled assumptions about ADU ordinance adoption velocity and electromechanical hardware cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Contract Furniture Market
Furniture
Furniture Laminate Market
Furniture
Fireplace Mantels Market
Furniture
Recliner Chair Market
Furniture
Indonesia Home Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Europe School Furniture Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
GCC Luxury Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Armchair on Casters Market
Furniture
Laminated Door Market
Furniture
United States Upholstered Furniture Market
Furniture
RTA Furniture Market
Furniture
Global Furniture Market
Furniture
United Kingdom Kitchen Furniture Market