
 Outdoor Furniture and Grills Market | 2026-2036
Outdoor Furniture and Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Furniture and Grills Market Analysis
EPA regulations on treated lumber emissions is shifting the material cost structure for domestic manufacturers. Char-Broil leverages its vertical integration in burner assembly to sustain margin control across gas grill lines. Ashley Furniture Industries anchors its outdoor portfolio through mass-market distribution density in big-box retail channels. Gloster differentiates through premium teak sourcing and European design positioning in the contract hospitality segment.
Outdoor furniture and grills encompass weather-resistant seating, dining, shade structures, and fuel-based or electric cooking appliances engineered for exterior residential and commercial environments, typically constructed with moisture-barrier finishes, UV-stabilized fabrics, and corrosion-resistant hardware rated for sustained outdoor exposure. The category serves leisure, entertainment, and foodservice functions in exterior spaces. Metal frames and aluminum substrates dominate volume manufacturing due to recyclability and lower transport weight, while pellet grills represent the fastest-expanding grill type as consumers seek precision temperature control and hardwood flavor profiles. Wicker and resin wicker categories carry premium positioning in residential replacement cycles, whereas charcoal retains share in price-sensitive and traditionalist buyer segments.
FDA oversight of food-contact surfaces on grill grates and preparation accessories shapes material selection and coating standards for manufacturers selling into the US market. The EU F-Gas Regulation constrains refrigerant and propellant options in outdoor cooling accessories tied to kitchen islands and beverage systems. California Air Resources Board rules on combustion emissions affect gas grill certification requirements for sale in that state. Stakeholders must monitor evolving state-level fire codes and municipal open-flame ordinances as outdoor kitchen permanence rises and insurance underwriters tighten liability assessments.
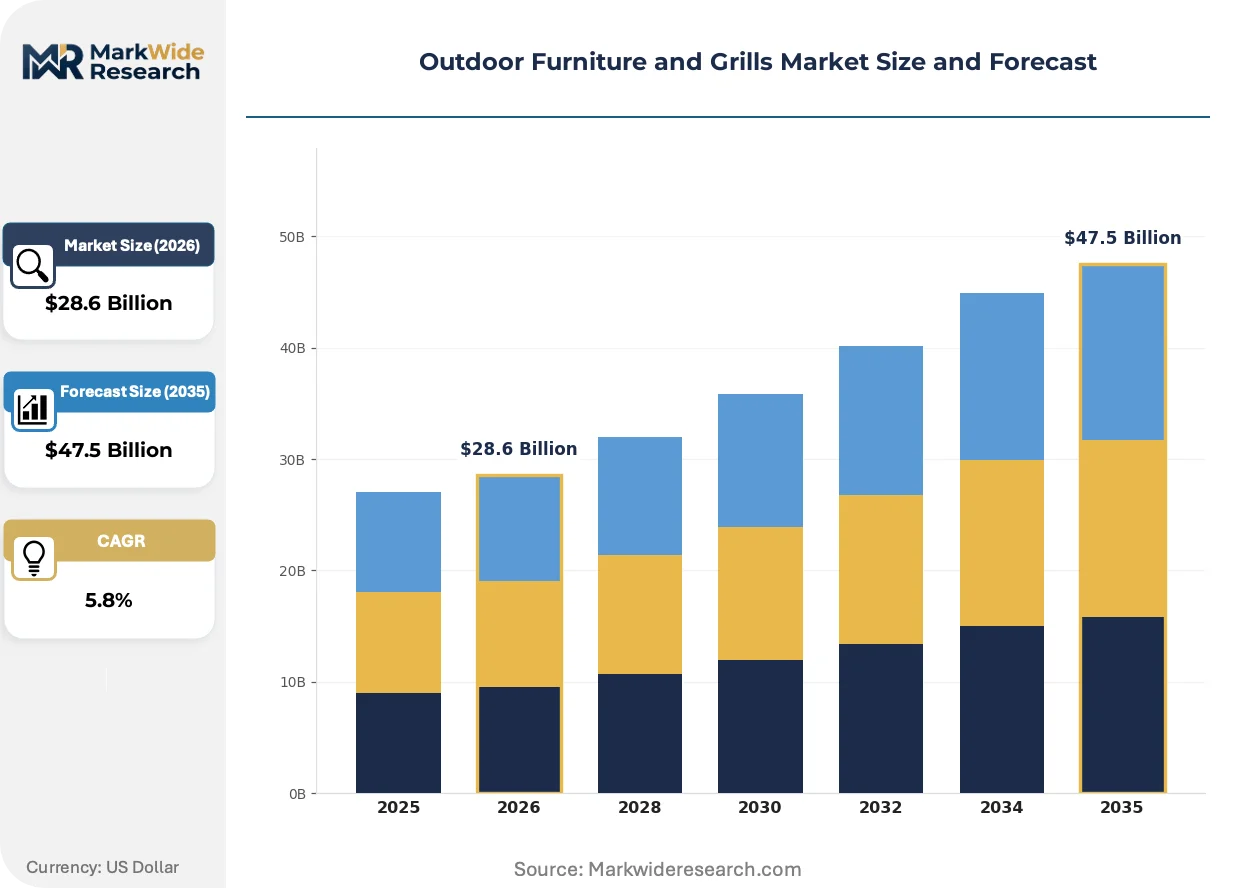
Market Dynamics
Permanent outdoor kitchen installations are compressing replacement cycles for grills while hospitality operators expand exterior dining footprints, creating dual demand velocity that strains powder-coated metal and certified teak supply channels.
Growth Catalysts
- Suburban Homeowner Investment:United States residential buyers are installing covered patio environments with built-in appliances, sustaining demand for weather-resistant cabinetry and fuel-based cooking systems rated for exterior permanence.
- REACH Chemical Restrictions:European ECHA compliance mandates are redirecting treated wood and metal finishing streams toward certified sustainable alternatives, opening material substitution premiums for compliant suppliers.
- Pellet Grill Technology:Hardwood-fueled precision temperature control systems are capturing enthusiast segments seeking smoke-flavor replication previously requiring charcoal expertise.
Market Restraints
- Aluminum Input Volatility:Transport-weight-optimized metal frame production faces margin pressure from energy-intensive primary aluminum smelting cost swings concentrated in Chinese and Gulf state supply basins.
- EPA Treated Lumber Emissions:Domestic United States manufacturers confront reformulation expenses as environmental rules tighten copper-azole and micronized copper quaternary discharge thresholds.
- Resin Wicker UV Degradation:Premium-positioned synthetic weave categories carry warranty exposure from photostabilizer performance variance across subtropical and high-altitude exposure zones.
Strategic Opportunities
- Modular Outdoor Kitchen Systems:Pre-configured appliance islands with utility hookup standardization are penetrating United States Sun Belt metro markets where permitting simplicity accelerates contractor adoption.
- EU F-Gas Refrigerant Transition:Outdoor beverage cooling accessories face redesign windows as hydrofluorocarbon phase-down rules create first-mover advantage for hydrocarbon and CO2-based systems.
- Hospitality Contract Specification:Resort and hotel chain procurement consolidation favors suppliers with European design positioning and certified teak traceability for exterior lounge and dining footprints.
Industry Challenges
- Multi-Jurisdiction Fire Code Alignment:Municipal open-flame ordinances and state-level combustion emissions rules fragment gas grill certification requirements, complicating United States national distribution strategies.
- Corrosion-Resistant Hardware Sourcing:Marine-grade stainless fastener and hinge procurement requires qualification against salt-spray testing protocols that extend supplier onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Furniture and Grills Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Umbrellas, Loungers Material: Wood, Metal, Plastic, Wicker Grill Type: Charcoal, Gas, Electric, Pellet Customer Type: Residential, Commercial, Online Shoppers, Retail |
| Companies Covered | Brown Jordan, Agio International Company, Ashley Furniture Industries, Gloster, Char-Broil, Barbeques Galore, Homecrest Outdoor Living, Lloyd Flanders, Century Furniture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Furniture and Grills Market Emerging Trajectories
Smart connectivity and precision thermal management are redefining grill functionality expectations while regulatory chemistry constraints and hospitality procurement consolidation reshape material selection and channel access.
WiFi-enabled pellet grill controllers are consolidating enthusiast and competition-barbecue segments around hardwood-fueled systems with smartphone-monitored temperature profiles. Residential buyers seeking set-and-forget operation are migrating from charcoal and basic gas units, compressing mid-tier grill price positioning and forcing legacy burner-assembly manufacturers toward control-system partnerships or in-house development.
California Air Resources Board combustion emissions rules are tightening certification thresholds for gas grill sale in that state, forcing national manufacturers to engineer low-NOx burner configurations or accept market exclusion. The regulatory friction is elevating electric and pellet alternatives in United States western states while accelerating catalytic converter and secondary-air-injection technology adoption across gas product lines.
Hospitality procurement teams are consolidating vendor relationships around full-exterior-system suppliers capable of delivering coordinated seating, shade, and cooking appliance packages with unified warranty coverage. United States resort and hotel chains are reducing specialty contractor counts, favoring turnkey outdoor environment providers who assume design liability and installation sequencing risk across permanent exterior kitchen and lounge installations.
Outdoor Furniture and Grills Market Segmentation
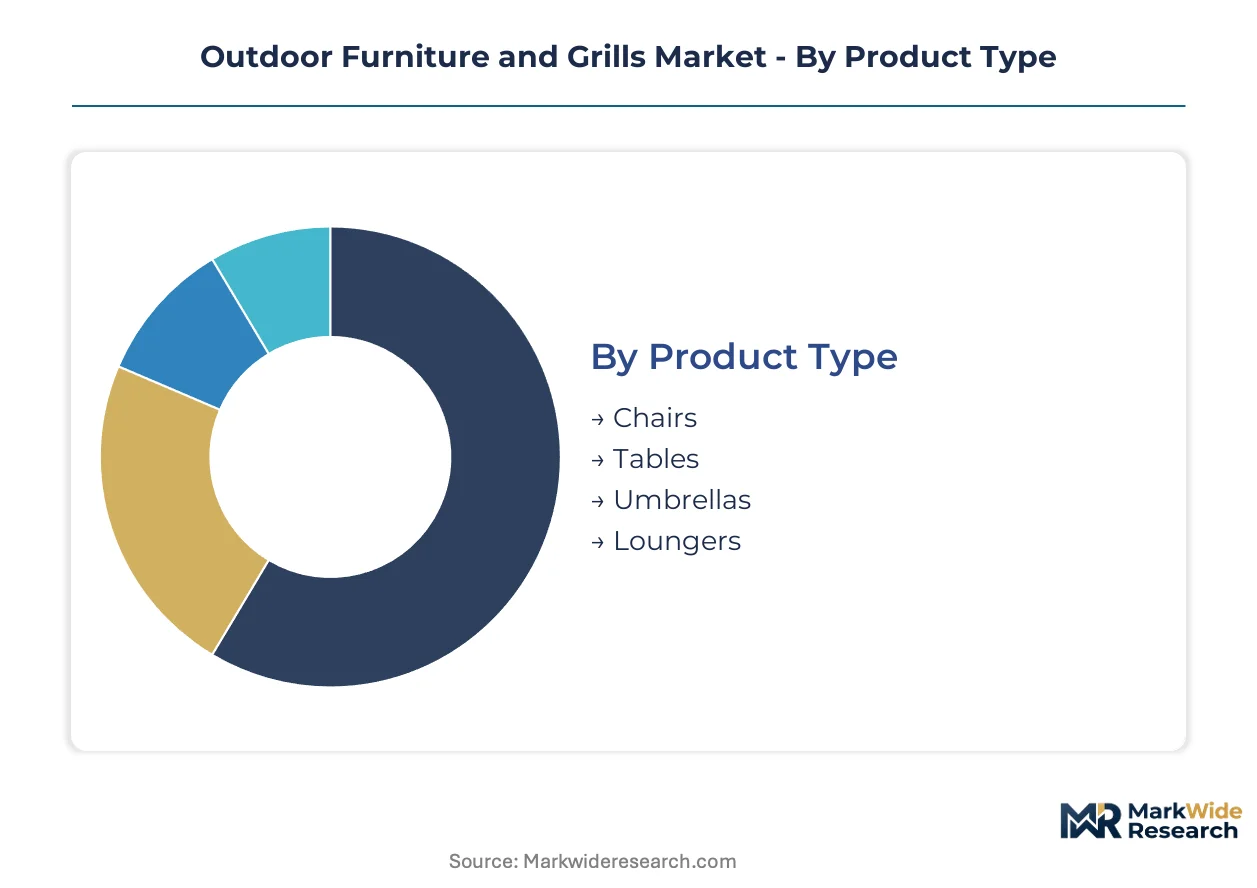
Outdoor furniture and grills segmentation reveals distinct replacement-cycle dynamics across residential and commercial buyer bases. Material durability thresholds and fuel-system permanence drive upgrade timing, creating tiered demand patterns that manufacturers must align with warranty positioning and distribution channel access.
Product Type:
Replacement cycles vary sharply across seating, surface, and shade categories, with weather exposure severity dictating upgrade frequency in coastal and high-UV zones.
- Chairs:Stackable aluminum and resin-wicker seating units face compressed replacement timelines in hospitality settings where fabric fatigue and frame corrosion accelerate turnover. United States suburban homeowners prioritize ergonomic cushioning and powder-coated frame durability for covered patio permanence.
- Tables:Dining and occasional tables engineered with moisture-barrier substrates and UV-stabilized surfaces anchor permanent outdoor kitchen installations. Demand concentrates in Sun Belt metros where utility integration and surface heat resistance drive specification.
- Umbrellas:Cantilever and center-pole shade structures with marine-grade hardware and solution-dyed acrylic canopies serve residential and contract segments requiring wind-load certification.
- Loungers:Adjustable recline mechanisms with quick-dry mesh or teak slat construction target poolside and resort deck environments.
Chairs sit at the top of the volume ranking, with loungers climbing the fastest as resort operators expand exterior wellness footprints.
Material:
Cost-tier positioning separates certified sustainable streams from commodity alternatives, with regulatory chemistry constraints reshaping supplier qualification requirements.
- Wood:Teak and acacia species with FSC chain-of-custody documentation command premium positioning in European contract hospitality procurement. REACH compliance mandates on copper-azole treatments are redirecting domestic United States manufacturers toward thermally modified alternatives.
- Metal:Aluminum and powder-coated steel frames dominate transport-optimized manufacturing due to recyclability and lower logistics cost. Input volatility from energy-intensive primary smelting concentrates margin pressure on mid-tier producers.
- Plastic:High-density polyethylene and resin compounds with UV stabilizers serve price-sensitive replacement cycles in mass retail channels.
- Wicker:Synthetic weave constructions with photostabilizer packages carry warranty exposure variance across subtropical and high-altitude exposure zones.
Metal frames anchor volume production, with certified wood gaining share fastest as hospitality procurement tightens traceability requirements.
Grill Type:
Fuel-system technology differentiation is concentrating enthusiast demand around precision thermal control, compressing mid-tier positioning for legacy burner configurations.
- Pellet:Hardwood-fueled systems with WiFi-enabled controllers and smartphone-monitored temperature profiles are capturing competition-barbecue and residential set-and-forget segments. California Air Resources Board emissions rules are elevating pellet alternatives in western United States states as gas certification tightens.
- Gas:Propane and natural gas units with low-NOx burner configurations face fragmented certification requirements across municipal open-flame ordinances and state combustion rules. National distribution strategies require multi-jurisdiction engineering compliance.
- Charcoal:Traditionalist and price-sensitive buyer segments sustain demand for kettle and kamado configurations despite longer ignition and temperature management learning curves.
- Electric:Apartment and condominium dwellers in jurisdictions with strict open-flame restrictions drive compact, balcony-rated unit specification.
Gas grills retain volume leadership, with pellet systems expanding most quickly as precision control technology penetrates residential enthusiast segments.
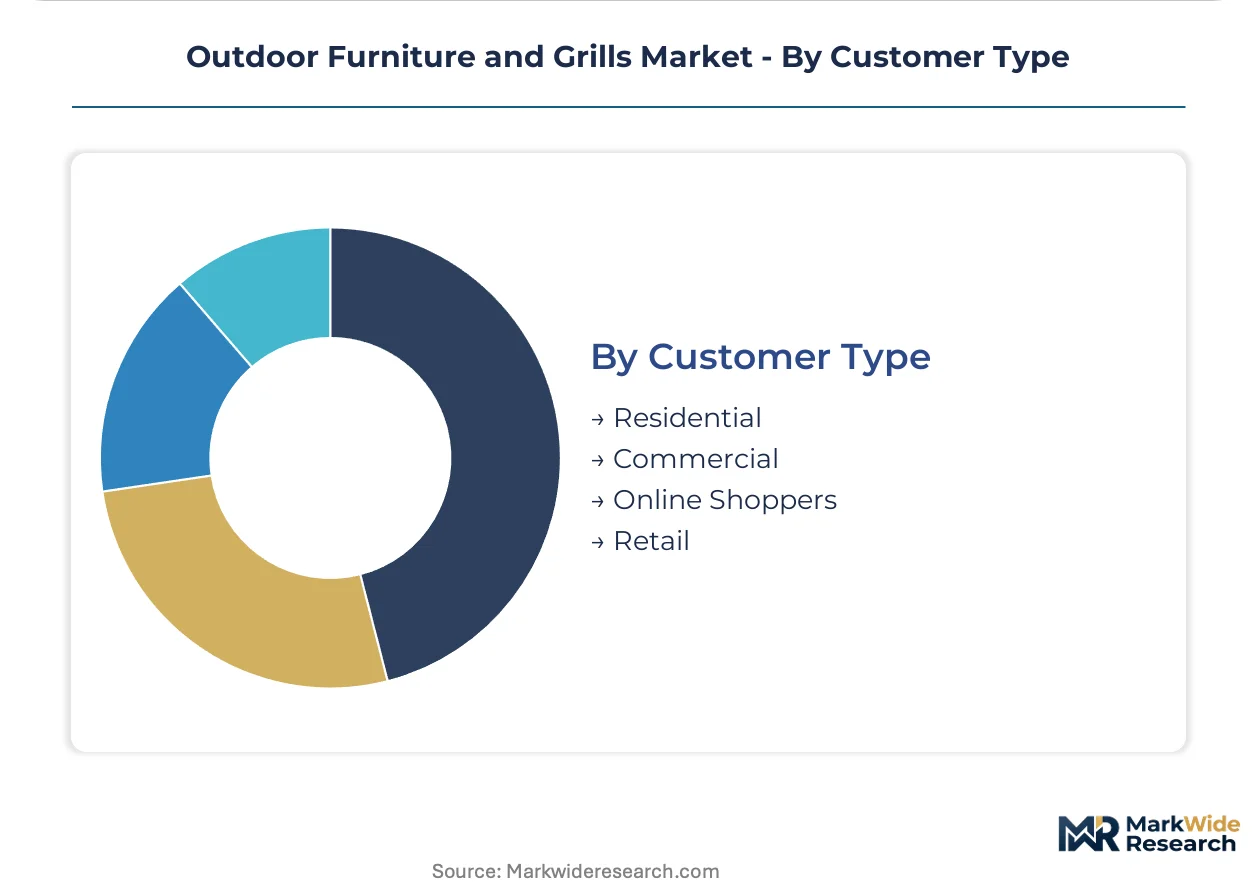
Customer Type:
Channel access and procurement consolidation patterns separate direct-to-consumer velocity from contract specification complexity.
- Residential:Suburban United States homeowners installing permanent outdoor kitchen environments drive weather-resistant cabinetry and built-in appliance demand through big-box and specialty retail channels.
- Commercial:Resort and hotel chain procurement teams are consolidating vendor relationships around full-exterior-system suppliers capable of unified warranty coverage across seating, shade, and cooking packages.
- Online Shoppers:Direct-to-consumer platforms with augmented-reality visualization and modular configuration tools capture replacement-cycle demand from convenience-oriented buyers.
- Retail:Mass-market and specialty storefronts with seasonal inventory cycles and assembly-service offerings serve immediate-need and gift-purchase occasions.
Residential buyers dominate transaction volume, with commercial procurement climbing fastest as hospitality exterior footprints expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled metalworking and furniture craftsmanship clusters anchor production capacity across distinct manufacturing basins, with regulatory chemistry constraints and hospitality procurement consolidation reshaping material sourcing geography.
United States
Suburban homeowners in Texas and Florida metros are installing permanent outdoor kitchen environments with built-in appliances and weather-resistant cabinetry. EPA regulations on treated lumber emissions are forcing domestic manufacturers toward thermally modified wood alternatives and certified metal finishing streams. The Sun Belt corridor from Phoenix to Atlanta concentrates demand velocity for modular outdoor kitchen systems.
Germany
REACH compliance mandates from ECHA are redirecting treated wood and powder-coated metal supply chains toward certified sustainable alternatives with full chain-of-custody documentation. The EU F-Gas Regulation constrains refrigerant options for outdoor beverage cooling accessories integrated into kitchen islands. Industrial clusters in North Rhine-Westphalia and Bavaria host precision metal fabrication capacity serving contract hospitality procurement.
China
Energy-intensive primary aluminum smelting concentrates in Shandong and Xinjiang provinces, creating input cost volatility for transport-weight-optimized metal frame production. Export-oriented manufacturers in the Pearl River Delta face margin pressure from electricity pricing reforms and carbon intensity targets under dual carbon goals. Zhejiang and Jiangsu provinces maintain synthetic weave and resin compound production for price-sensitive retail channels.
Italy
Design-forward seating and shade manufacturers in Lombardy and Veneto command premium positioning in European contract hospitality procurement. FSC-certified teak traceability requirements from resort and hotel chains favor suppliers with documented sustainable material streams. The Brianza furniture district anchors high-end outdoor seating production with integrated metal and upholstery craftsmanship.
United Kingdom
Big-box retail distribution density in the Southeast and Midlands sustains mass-market transaction volume for replacement-cycle seating and grill purchases. ECHA chemical restrictions on copper-azole treatments are accelerating substitution toward thermally modified timber and aluminum alternatives. Greater Manchester and West Yorkshire host powder-coating and metal fabrication capacity serving domestic and export demand.
Outdoor Furniture and Grills Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive burner assembly and metal finishing capabilities. Tiered concentration separates mass-market distribution players from premium design houses and hospitality-focused contract suppliers. Three archetypes dominate: big-box retail anchors with national distribution density, European design houses with certified sustainable material positioning, and vertically integrated grill manufacturers with in-house control over combustion technology. Consolidation pressures are accelerating through hospitality procurement vendor reduction and cross-category warranty bundling.
Among North American mass-market anchors, Ashley Furniture Industries and Char-Broil occupy positions representing distribution scale and captive manufacturing integration respectively. Gloster exemplifies the European premium archetype with hospitality contract specification focus. Brown Jordan anchors the design-forward contract segment. These three named entities represent distinct competitive vectors rather than exhaustive market coverage, with each archetype facing pressure to expand material certification depth and multi-jurisdiction regulatory compliance breadth.
| Leading Market Players |
|---|
| Brown Jordan |
| Agio International Company |
| Ashley Furniture Industries |
| Gloster |
| Char-Broil |
| Barbeques Galore |
| Homecrest Outdoor Living |
| Lloyd Flanders |
| Century Furniture |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum price volatility cascades through powder-coated frame manufacturing into three distinct pricing tiers for outdoor furniture and grills, compressing margins for transport-optimized producers while elevating premiums for certified sustainable material streams.
Pricing Analysis
Bundled installation and warranty services separate premium outdoor kitchen system pricing from unbundled grill and seating transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FSC certification status and burner technology sophistication. Cost compression in mid-tier gas grill segments is intensifying because California Air Resources Board compliance adds engineering overhead without commensurate price recovery. Mass-market retail buyers exhibit highest price sensitivity, while hospitality procurement teams prioritize unified warranty coverage over unit cost.
Supply Chain Analysis
Primary aluminum smelting draws from Chinese Shandong and Xinjiang provinces, Indonesian bauxite, and Gulf state energy subsidies. Powder-coated steel substrates and marine-grade stainless hardware feed from German North Rhine-Westphalia and Italian Lombardy fabrication clusters. Single-source vulnerability concentrates in Shandong smelter capacity subject to electricity pricing reforms under dual carbon goals. Distribution runs through big-box retail seasonal cycles, direct-to-consumer platforms with augmented-reality tools, and consolidated hospitality contract specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as permanent outdoor kitchen installations compress replacement cycles and expand average transaction values across residential and commercial buyer bases.
For Market Incumbents: Cement hospitality contract relationships through unified warranty bundling across seating, shade, and cooking appliance packages. Deepen backward integration into certified teak sourcing with FSC chain-of-custody documentation to defend against European REACH compliance substitution threats. Expand low-NOx burner engineering capacity to preempt California Air Resources Board certification exclusion risks. For New Entrants and Emerging Players: Launch via direct-to-consumer platforms with modular outdoor kitchen configuration tools targeting United States Sun Belt metro markets. Penetrate the electric grill segment serving apartment and condominium dwellers in jurisdictions with strict open-flame ordinances. Anchor initial positioning through WiFi-enabled pellet controller partnerships rather than captive combustion technology development. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated grill manufacturers with captive burner assembly and European design houses with certified sustainable material positioning. Long-term viability favors suppliers with multi-jurisdiction regulatory compliance breadth and hospitality procurement consolidation access. Watch pellet grill WiFi controller adoption rates as inflection indicator for technology-driven share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FSC-Certified Teak Backward Integration | Secures hospitality contract access under tightening ECHA traceability mandates. |
| Low-NOx Burner Platform Standardization | Enables California Air Resources Board compliance without state-specific SKU fragmentation. |
| Modular Outdoor Kitchen System Launch | Captures Sun Belt permitting simplicity and contractor adoption velocity. |
| Direct-to-Consumer Platform Expansion | Bypasses seasonal retail inventory cycles with augmented-reality configuration tools. |
| Hospitality Contract Warranty Bundling | Aligns with resort procurement consolidation around turnkey exterior environment providers. |
Methodological Framework
Bottom-up residential and commercial demand modeling reconciled against top-down aluminum smelter and treated wood supply tracking forms the analytical core of this study. Primary interviews with resort procurement directors, big-box category buyers, powder-coating plant managers, and outdoor kitchen contractors combined with secondary validation from EPA emission filings, ECHA restriction updates, customs trade data, and hospitality development pipeline databases. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of replacement cycle timing and material substitution patterns informed projection framework construction across the analysis window. Segmentation dimensions modeled include product type, material certification tier, grill fuel technology, and customer channel. CAGRs derived from regression against macroeconomic indicators and regulatory implementation schedules. Pellet grill WiFi penetration rates and hospitality exterior footprint expansion served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price spike conditions and municipal fire code fragmentation scenarios. Forecasts reflect assumptions around REACH compliance timelines and Sun Belt permitting velocity. A small set of named triggers—California Air Resources Board rule expansion, ECHA copper-azole restriction tightening, and Chinese smelter electricity pricing reforms—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global Multifunctional Home Furniture Market
Furniture
Salon Chairs Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Europe School Furniture Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
Global Organic Furniture Market
Furniture
Europe Smart Furniture Market
Furniture
UK Multifunctional Furniture Market
Furniture
Unfinished Wood Furniture Market
Furniture
GCC Multifunctional Furniture Market
Furniture
Kids Storage Furniture Market
Furniture
Bean Bag Chairs Market
Furniture
Upholstered Furniture Market
Furniture
Indonesia Home Furniture Market