
 Global Passive Fire Protection Coatings Market | 2026-2036
Global Passive Fire Protection Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Passive Fire Protection Coatings Market Foresight
A capital-intensity divergence between integrated resin producers and regional applicators is reorganizing competitive tiers in passive fire protection coatings. PPG Industries leverages captive epoxy chemistry to secure specification locks on offshore platform projects. Akzo Nobel N.V. anchors its position through marine certification density across North Sea and Southeast Asian shipyards. Hempel A/S specializes in solvent-free intumescent formulations that reduce application labor costs for industrial plant contractors.
Passive fire protection coatings are reactive barrier systems—typically intumescent char-forming layers or cementitious sprays—that insulate structural substrates from thermal load during combustion, with film thickness specifications ranging from one millimeter for thin-film intumescents to fifty millimeters for dense cementitious sprays. Their primary industrial purpose is to preserve load-bearing capacity of steel frameworks long enough for evacuation and emergency response during cellulosic or hydrocarbon fire events. Intumescent coatings now command the fastest-expanding margin pool as architects specify aesthetic-exposed steel in commercial atriums, while cementitious coatings retain volume dominance in petrochemical and tunnel infrastructure where thick-film durability outweighs visual finish requirements. Water-based technology is displacing solvent systems in European and North American construction channels as volatile organic compound thresholds tighten.
The EU Construction Products Regulation and EN 13381 fire resistance testing framework mandate third-party verification of coating performance on structural steel sections, creating compliance barriers for uncertified suppliers. China's Ministry of Emergency Management enforces GB 14907 standards for steel structure fireproofing in high-rise and industrial builds, driving reformulation toward low-smoke, halogen-free chemistries. India's Bureau of Indian Standards has notified revised IS 15103 protocols for passive fire protection materials, tightening char integrity benchmarks for cable coating applications. Stakeholders must monitor divergence between regional test protocols and pre-certify formulations for multi-jurisdiction project bids before specification cycles lock.
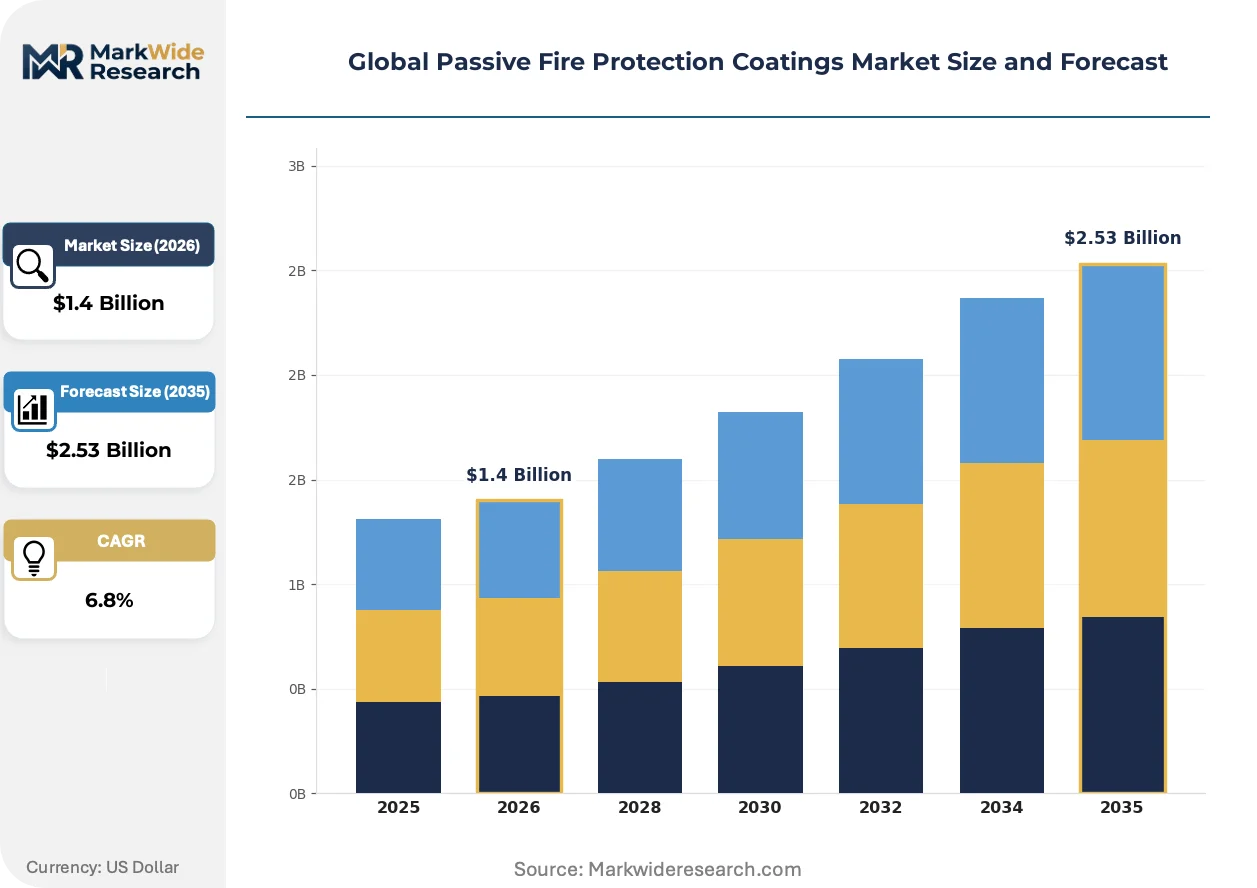
Market Dynamics
Certification-driven specification locks are restructuring competitive access in passive fire protection coatings, as EN 13381 and GB 14907 compliance costs filter out regional formulators and concentrate procurement authority with resin-integrated multinationals.
Growth Catalysts
- Offshore platform construction:Deepwater energy projects in Brazil and West Africa are mandating marine-grade intumescent systems for topside steel protection.
- EU Green Deal VOC thresholds:Tightening solvent emission limits under REACH annex revisions are accelerating water-based coating conversions in German and French industrial construction.
- China's dual carbon goals:MEE enforcement of low-smoke halogen-free standards in petrochemical facility builds is expanding addressable demand for cementitious spray applications.
Market Restraints
- Epoxy resin supply concentration:Captive production by integrated coating majors limits feedstock access for independent formulators in Southeast Asia.
- EN 13381 test duration:Extended fire resistance certification cycles create 18-24 month specification barriers for new market entrants.
- Cementitious durability limitations:Thick-film cracking in high-humidity tunnel environments restricts application windows in tropical geographies.
Strategic Opportunities
- India's infrastructure buildout:Revised IS 15103 cable coating protocols are opening specification windows for char-integrity-tested formulations in metro rail projects.
- Solvent-free intumescent convergence:Combination of UV-cure base coats with reactive char layers is reducing labor hours for industrial plant contractors.
- Direct applicator channel:Bypassing traditional distributor networks through certified installer partnerships is capturing margin in Australian commercial construction.
Industry Challenges
- Fire testing engineer scarcity:Shortage of EN 13381-qualified technicians extends certification timelines for reformulated products.
- Multi-jurisdiction pre-qualification burden:Divergence between EU, Chinese, and Indian test protocols forces redundant testing spend for global project bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Passive Fire Protection Coatings Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Coatings, Cementitious Coatings, Epoxy Coatings, Cement-Based Fireproofing Application: Structural Steel, Electrical Cable, Marine Vessels, Aerospace Components End User: Construction Companies, Shipbuilding Yards, Aerospace Manufacturers, Industrial Plants Technology: Water-Based, Solvent-Based, Hybrid, Acrylic Polymer |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Akzo Nobel N.V., Jotun, Hempel A/S, 3M, Carboline, Promat International, Kansai Paint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Passive Fire Protection Coatings Market Shifts & Advancements
Reactive barrier chemistry is splitting into two performance tracks as aesthetic-exposed steel applications demand thinner films while hydrocarbon fire scenarios require denser char structures.
Thin-film intumescent technology is bifurcating specification standards across commercial and industrial segments. Water-based acrylic-epoxy hybrids now achieve 60-minute cellulosic ratings at sub-3mm dry film thickness, enabling exposed steel aesthetics in German and Japanese atrium architecture. This performance compression is collapsing the traditional premium gap between decorative fire protection and structural cementitious systems.
REACH annex XVII VOC amendments are forcing solvent system phaseouts across EU construction channels. German industrial applicators face mandatory conversion to water-borne or 100% solid formulations by tightened emission deadlines. Nordic shipyards are responding fastest, locking in solvent-free marine certifications ahead of enforcement windows to secure yard capacity.
Specification authority is migrating from general contractors to certified fire protection engineers. Large-scale infrastructure projects in Saudi Arabia and Australia now require independent third-party coating approval before bid submission. This verification shift is compressing distributor influence and rewarding manufacturers with pre-certified formulation libraries.
Global Passive Fire Protection Coatings Market Segmentation
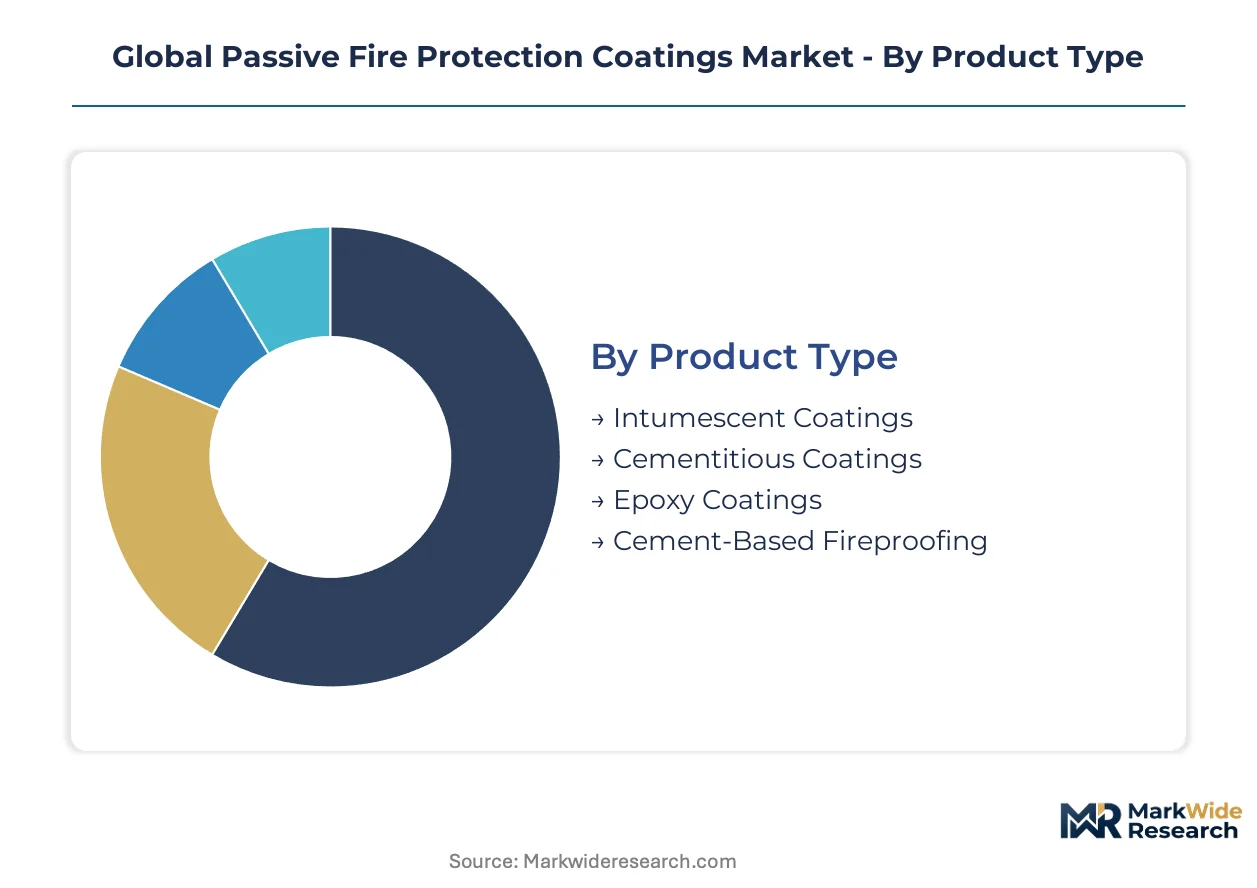
Passive fire protection coatings segment across multiple technical and commercial dimensions that dictate specification authority and margin capture. Product chemistry, substrate application, and regulatory compliance requirements create distinct competitive battlegrounds with divergent growth trajectories.
Product Type:
Intumescent coatings dominate export-led demand from European and East Asian manufacturing bases, while cementitious systems serve predominantly domestic construction markets in China and India.
- Intumescent Coatings:These char-forming acrylic-epoxy hybrids expand 50-100x under thermal load to insulate structural steel. German atrium architects specify sub-3mm films for aesthetic-exposed frameworks, while Brazilian deepwater platforms drive marine-grade procurement from South Korean yards.
- Cementitious Coatings:Dense mineral sprays deliver 2-4 hour fire ratings at 25-50mm thickness for hydrocarbon fire scenarios. Chinese petrochemical facility construction in coastal manufacturing clusters absorbs volume, though tropical humidity cracking constrains Southeast Asian tunnel applications.
- Epoxy Coatings:Captive production by integrated resin majors limits independent formulator access in offshore platform specifications.
- Cement-Based Fireproofing:Pre-mixed dry sprays reduce on-site labor for Indian metro rail infrastructure contractors facing IS 15103 certification deadlines.
Cementitious coatings hold the largest share; momentum sits with intumescent formulations.
Application:
Cost tier stratification separates premium-certified marine systems from commoditized cable coatings, with structural steel commanding specification premiums due to load-bearing safety criticality.
- Structural Steel:EN 13381 and GB 14907 compliance mandates create 18-24 month certification barriers. Third-party verification concentrates procurement with resin-integrated multinationals for German industrial builds and Chinese high-rise construction.
- Marine Vessels:Solvent-free intumescent systems from Nordic shipyards achieve 120-minute hydrocarbon ratings. South Korean and Japanese yards expanding topside steel protection for West African deepwater projects.
- Electrical Cable:Revised IS 15103 protocols in India tighten char integrity benchmarks for metro rail applications.
- Aerospace Components:Lightweight intumescent films meet FAA fireworthiness standards for cabin interior substrates.
Structural steel absorbs the highest certification investment; marine vessels are climbing the fastest.
End User:
Customer type determines channel configuration, with shipbuilding yards consolidating procurement through direct manufacturer partnerships while construction companies rely on certified applicator networks.
- Construction Companies:German and French contractors face mandatory REACH Annex XVII VOC conversions, accelerating water-based system adoption ahead of emission deadlines.
- Shipbuilding Yards:South Korean yards leverage marine certification density to secure capacity commitments from coating majors. Direct partnerships bypass traditional distributor margins.
- Industrial Plants:Australian commercial contractors capture margin through certified installer channel bypasses.
- Aerospace Manufacturers:Fire testing engineer scarcity extends qualification timelines for reformulated lightweight systems.
Construction companies represent the volume anchor; shipbuilding yards show the steepest expansion trajectory.
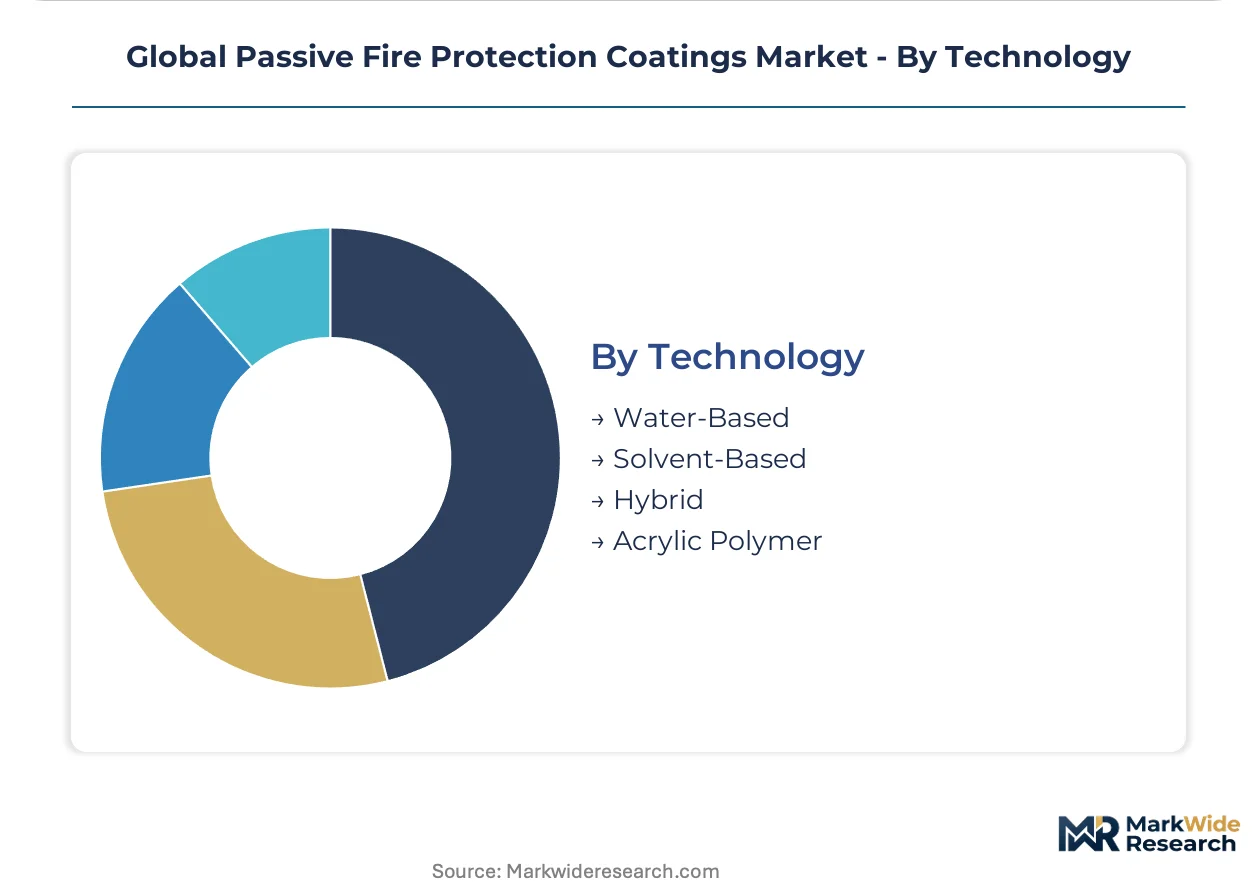
Technology:
Supply concentration in water-borne resin production is reorganizing competitive tiers as EU emission thresholds force solvent system phaseouts.
- Water-Based:Acrylic-epoxy hybrids achieve 60-minute cellulosic ratings with sub-3mm film builds. German industrial applicators convert ahead of tightened enforcement windows.
- Solvent-Based:Declining share in European construction channels persists in tropical geographies where humidity resistance requirements favor solvent-borne durability.
- Hybrid:UV-cure base coats combined with reactive char layers reduce labor hours for industrial plant contractors.
- Acrylic Polymer:Low-smoke halogen-free formulations align with China's MEE enforcement in petrochemical facility builds.
Water-based technology holds the largest share; hybrid systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial corridors where REACH Annex XVII enforcement accelerates water-based conversions, while Chinese coastal clusters absorb volume through state-mandated low-smoke halogen-free procurement for petrochemical builds.
Germany
Industrial construction in the Ruhr and Bavaria drives specification premiums for EN 13381-certified thin-film intumescents. ECHA REACH amendments enforce solvent emission phaseouts by tightened deadlines. Applicator networks in North Rhine-Westphalia convert facilities ahead of enforcement windows to secure specification locks.
China
Petrochemical facility construction in Ningbo and Dalian manufacturing clusters absorbs cementitious spray volumes. MEE enforces GB 14907 standards for steel structure fireproofing in high-rise and industrial applications. Coastal provinces accelerate procurement of marine-grade systems for shipyard expansion.
United States
Offshore platform projects in the Gulf of Mexico mandate hydrocarbon-rated intumescent systems for topside steel protection. OSHA maintains structural fire safety standards for industrial construction. Houston-area engineering firms consolidate procurement authority through third-party coating approval requirements.
South Korea
Shipbuilding yards in Ulsan and Geoje expand marine-grade intumescent procurement for West African deepwater contracts. The national shipyard certification regime aligns with international maritime fire safety protocols. Direct manufacturer partnerships bypass traditional distributor networks to secure yard capacity.
India
Metro rail infrastructure in Mumbai and Delhi drives cable coating demand under revised IS 15103 protocols. BIS tightens char integrity benchmarks for passive fire protection materials. National infrastructure buildout opens specification windows for certified formulations in transit projects.
Global Passive Fire Protection Coatings Market Competitive Landscape
Concentration sits with integrated resin producers who control captive epoxy chemistry and specification authority on offshore platform projects. Three archetypes dominate: multinational coating majors with backward integration into resin production, regional formulators dependent on merchant feedstock supply, and certified applicator networks capturing margin through direct installer partnerships. Competitive moves center on EN 13381 pre-certification investments to compress specification cycles, and solvent-free formulation launches to capture EU Green Deal conversion demand.
Among integrated multinationals, PPG Industries, Akzo Nobel N.V., and Hempel A/S exemplify the resin-integrated archetype that secures specification locks through captive chemistry control. PPG Industries represents the scale-driven position in offshore platform procurement. Akzo Nobel N.V. anchors marine certification density across North Sea and Southeast Asian shipyards. Hempel A/S occupies the solvent-free specialization tier, reducing application labor costs for industrial plant contractors through reactive char layer formulations.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries |
| Akzo Nobel N.V. |
| Jotun |
| Hempel A/S |
| 3M |
| Carboline |
| Promat International |
| Kansai Paint |
| Others |
Supply & Pricing Matrix
Capacity utilization at integrated epoxy resin facilities in Germany and South Korea establishes price floors that regional formulators cannot match without captive feedstock supply. This scale concentration compresses margins for merchant-dependent applicators while concentrating specification authority with backward-integrated multinationals bidding on offshore platform and shipyard contracts.
Pricing Analysis
The customization-premium spread between configured-to-order marine-grade intumescents and standard cementitious sprays runs wide. Project-based contract pricing dominates, with differentiation driven by EN 13381 certification tier and volume scale for multi-site industrial builds. Pricing pressure stems from epoxy resin supply concentration limiting independent formulator access in Southeast Asia. Construction companies show highest price sensitivity on commoditized cable coatings, while shipbuilding yards absorb premiums for solvent-free marine certifications.
Supply Chain Analysis
Inventory lead times for specialty epoxy resins stretch procurement cycles for non-integrated formulators bidding on certified steel protection projects. Supply concentrates in Germany, South Korea, and China, with raw material dependencies on bisphenol-A epoxies, intumescent char-forming additives, and titanium dioxide pigments. Single-source vulnerability runs through South Korean marine-grade resin supply to West African deepwater contracts. Distribution runs through certified applicator networks in European construction channels and direct manufacturer partnerships at Asian shipyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Passive fire protection coatings function as a service-attach business where certified installation and inspection contracts expand faster than material volumes. Recurring certification maintenance and re-inspection services now capture margin pools exceeding initial coating application.
For Market Incumbents: Consolidate specification authority through EN 13381 pre-certification investments that compress 18-24 month approval cycles for reformulated products. Deepen captive epoxy production in South Korea and Germany to defend against merchant resin supply disruptions. Channel control through certified installer partnerships in Australian commercial construction locks out distributor-dependent competitors. For New Entrants and Emerging Players: Differentiate on solvent-free formulation specialization for EU Green Deal conversion demand in German and French industrial corridors. Target India's metro rail infrastructure buildout under revised IS 15103 cable coating protocols where certification windows remain open. Pursue direct applicator channel bypasses to capture margin in Australian certified installer networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors resin-integrated specialists with captive chemistry control over merchant-dependent regional formulators. Long-term viability rests on EN 13381 and GB 14907 certification library depth rather than geographic coverage alone. Watch for divergence between EU and Chinese test protocols as the inflection signal for redundant testing spend burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive feedstock supply secures specification locks on Brazilian deepwater platform contracts. |
| EN 13381 Pre-Certification Investment | Third-party verification libraries compress bid cycles for German industrial steel protection projects. |
| Solvent-Free Formulation Launch | Zero-VOC systems capture EU Green Deal conversion demand ahead of REACH Annex XVII deadlines. |
| Certified Installer Partnership Network | Direct channel bypasses capture margin in Australian commercial construction vertical. |
| Multi-Jurisdiction Test Protocol Harmonization | Pre-qualified formulations reduce redundant testing spend for global infrastructure bids. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and national fire safety regulator certification databases. Primary interviews engaged coating formulators, certified fire protection engineers, shipyard procurement managers, and industrial plant maintenance directors. Bottom-up volume triangulation across product chemistry segments and top-down value validation against disclosed revenue streams ensured cross-verification.
Segmentation dimensions modeled include intumescent versus cementitious chemistry, structural steel versus marine vessel versus cable coating application, water-based versus solvent-based versus hybrid technology, and construction company versus shipyard versus industrial plant end-user archetypes. CAGRs were derived from fitted growth curves across the projection horizon, with inputs from petrochemical facility construction pipelines, shipyard capacity expansion schedules, and regulatory enforcement timelines for VOC and halogen-free standards.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of REACH Annex XVII, GB 14907, and IS 15103 protocols would require recalibration. Forecasts reflect assumptions about certification timeline stability and resin supply concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Carbon Fiber Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
United States Floor Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
Urethane Surface Coatings Market
Coatings
Global Photocatalytic Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Asia-Pacific Protective Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
High Performance Epoxy Coating Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Stealth Coating Material Market
Coatings
Coatings and Fillings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market