
 Global Tools Storage Products Market | 2026-2036
Global Tools Storage Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tools Storage Products Market Intelligence
A growing shortage of skilled professional mechanics is reorganizing procurement priorities toward systems that enhance individual technician efficiency. Stanley Black & Decker leverages its extensive brand portfolio, including DeWalt, to serve diverse professional and DIY end-user needs. Milwaukee Tool differentiates with its focus on integrated, battery-powered tool and storage ecosystems for job sites. Snap-on Incorporated sustains its premium position through direct sales channels to automotive workshops.
Tools storage products encompass containers and furniture designed for organizing, securing, and transporting hand and power tools. These items are fabricated from materials like steel or high-impact plastic, engineered for durability and specific load-bearing capacities. The market shows a clear shift toward modular systems, which represent the fastest-growing category, allowing for customized configurations across different end-users. While steel chests dominate the professional mechanic segment, plastic organizers are prevalent among DIY enthusiasts due to cost and portability.
Product safety and workplace organization are influenced by multiple regulatory frameworks. In the United States, OSHA standards guide workshop safety layouts, while in Europe, CE marking and RoHS directives govern material composition and electrical safety for powered units. The key decision for manufacturers will be balancing investments in material science for durability against the integration of digital tracking technologies into their product lines.
Market Dynamics
The central force shaping the tools storage market is the acute shortage of skilled technicians, which elevates the value of organizational systems that maximize individual productivity and reduce non-value-added time searching for tools and equipment.
Growth Catalysts
- Modular System Adoption:The shift toward customizable, interlocking storage units allows diverse end-users, from automotive mechanics to DIY enthusiasts, to create tailored solutions for specific workflows, enhancing organization and efficiency.
- Workplace Safety Mandates:Regulations like OSHA standards in the United States drive investment in proper storage to reduce trip hazards and improve workshop organization, directly linking safety compliance to market demand.
- Construction Sector Expansion:Sustained activity in residential and commercial construction, particularly in North America, fuels demand for durable, portable, and secure job site storage boxes to protect valuable power tools.
Market Restraints
- Raw Material Volatility:Price fluctuations in industrial-grade steel, a primary material for professional-grade chests and cabinets, directly impact manufacturer margins and create pricing instability for end-users.
- Plastic Durability Limitations:While cost-effective, high-impact plastics have inherent load-bearing and impact-resistance limits compared to steel, restricting their use in heavy-duty professional applications.
- Substitution from General-Purpose Containers:Low-cost, non-specialized bins and containers sold through mass-market retail channels present a constant substitution threat, especially within the price-sensitive DIY segment.
Strategic Opportunities
- Smart Storage Integration:Incorporating RFID or Bluetooth tracking technology into storage units offers a significant value-add for asset management, creating a new premium product tier for commercial fleets and large workshops.
- Emerging Market Workshops:The formalization of automotive repair and skilled trade sectors in developing economies presents a large, underpenetrated market for professional-grade organizational systems.
- Direct-to-Professional Channels:Expanding direct sales models allows manufacturers to build brand loyalty and capture higher margins by bypassing traditional wholesale distribution networks for specialized equipment.
Industry Challenges
- Software Interoperability:Ensuring that new smart storage products seamlessly integrate with the diverse and often proprietary workshop management software used by automotive dealerships and industrial facilities is a major technical hurdle.
- Balancing R&D Priorities:Manufacturers face difficult capital allocation decisions between investing in advanced material science for greater durability and funding software development for digital features and connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tools Storage Products Market |
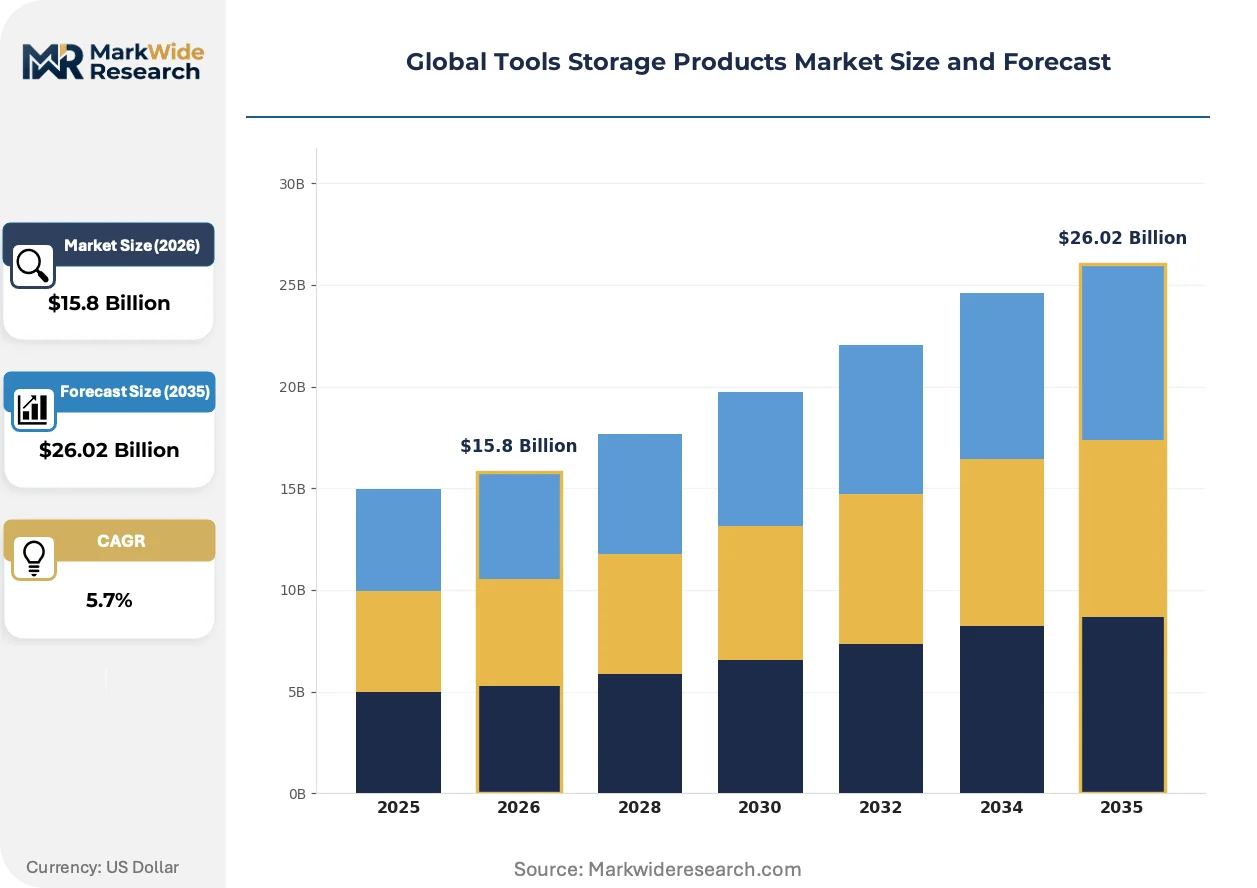
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $26.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toolboxes, Cabinets, Chests, Organizers, Racks, Workbenches Storage Capacity: Small, Medium, Large, Extra Large, Modular Material: Steel, Plastic, Aluminum, Wood, Composite End User: Professional Mechanics, DIY Enthusiasts, Construction Workers, Workshop Owners, Manufacturing Facilities |
| Companies Covered | Stanley Black & Decker, Milwaukee Tool, Snap-on Incorporated, Apex Tool Group, DeWalt, Bosch, Husky, Techtronic Industries, Kennedy Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tools Storage Products Market Strategic Shifts & Innovations
The market's evolution is defined by the transition of storage products from passive containers into active components of a connected worksite. This shift emphasizes integration with power sources and digital asset management tools to improve workflow efficiency.
Integrated battery charging technology is being built directly into tool chests and mobile storage units. Professional tradespeople on construction sites and in maintenance fleets are the primary adopters, seeking to eliminate downtime. This trend is decomposing the traditional, separate tasks of tool storage and battery management into a single, unified job site operation.
European Union directives, particularly RoHS, govern the material composition of electronic components within tool storage products. This regulation forces manufacturers to eliminate specific hazardous substances from powered units that feature integrated lighting, charging ports, or digital displays. Consequently, supply chains for these advanced products must be rigorously vetted for compliance to access the significant EU market.
A significant behavioral shift sees users committing to a single brand's interoperable product ecosystem rather than buying standalone items. This loyalty to integrated platforms of tools, batteries, and storage disrupts the traditional, best-in-class purchasing model for individual components. The pattern is most visible in professional trades where the efficiency gains from a unified system outweigh the benefits of multi-brand tool selection.
Global Tools Storage Products Market Segmentation
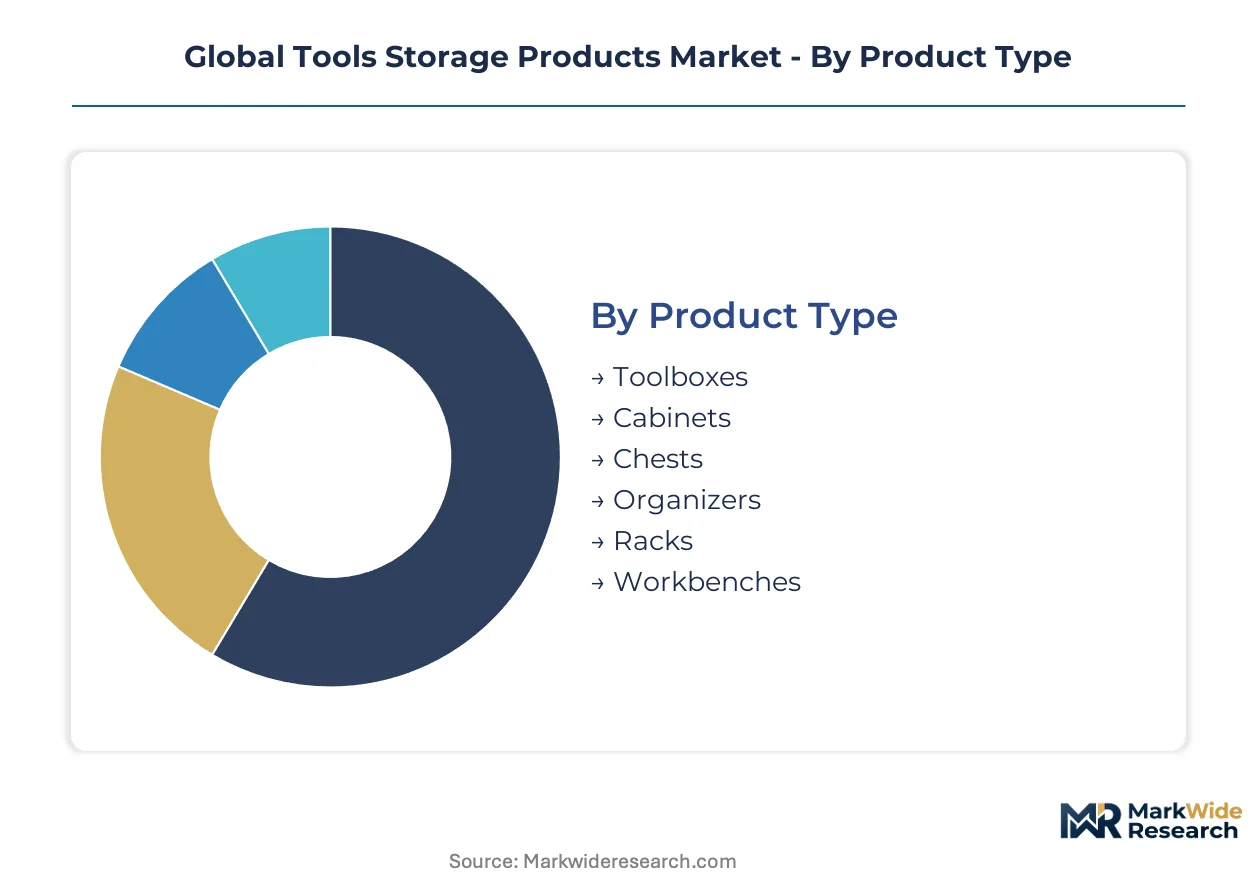
The tools storage market segments delineate varying product functionalities and end-user requirements, guiding manufacturers in product development and market penetration strategies. Understanding these distinctions helps in tailoring solutions for diverse applications, from industrial facilities to individual workshops.
Product Type:
The geographic spread of product types illustrates specialized demand, with certain designs more prevalent in specific regions for their utility.
- Toolboxes:These portable containers are designed for easy transport of hand tools, often featuring a single large compartment or a few trays. Demand is widespread, particularly among mobile technicians in the United States and independent contractors.
- Cabinets:Stationary, multi-drawer units offer secure and organized storage for a wide array of tools and equipment in fixed locations. Manufacturing facilities in Europe prioritize these for workflow efficiency and organization.
- Chests:Heavy-duty, often stackable units provide robust storage and security, suitable for both stationary and mobile applications. Professional mechanics in Germany's automotive workshops rely on chests for durability and capacity.
- Organizers:Smaller, compartmentalized containers keep fasteners, small parts, and specialized tools sorted.
- Racks:Open shelving systems hold larger items or frequently accessed tools, common in garage and workshop settings.
- Workbenches:Integrated workstations with storage drawers and a durable work surface provide a central hub for tasks.
Cabinets holds the largest share; momentum sits with Organizers.
Storage Capacity:
Application dictates the preferred storage capacity, aligning solutions with operational scale and specific user needs.
- Modular:These interlocking and customizable systems allow users to expand or reconfigure storage as needs evolve, offering significant workflow flexibility. Diverse end-users, from automotive mechanics to DIY enthusiasts, create tailored solutions for specific workflows.
- Large:Units designed for high volume and heavy-duty tool storage, often found in industrial settings or construction sites. Construction sites in North America prioritize large capacity for valuable power tools.
- Small:Compact storage solutions for minimal tools or specialized kits, often valued for portability.
- Medium:Balanced capacity for a general assortment of tools, suitable for many home and light professional uses.
- Extra Large:Maximum capacity storage, typically for extensive tool collections or bulky equipment in large workshops.
The market prioritizes Modular for efficiency, while Small addresses basic needs.
Material:
Customer type influences material choice, balancing durability, cost, and specific environmental factors.
- Steel:Known for its exceptional durability, load-bearing capacity, and security features, steel is the material of choice for professional-grade storage. Professional mechanics and industrial users in high-demand environments, like automotive workshops, require steel for its robust performance.
- Plastic:Lightweight, cost-effective, and resistant to rust and chemicals, high-impact plastic offers portability and versatility. DIY enthusiasts and users requiring portable, weather-resistant options, such as those in outdoor construction, favor plastic.
- Aluminum:Offers a balance of strength and lightness, often used for mobile cases and specialized applications.
- Wood:Utilized for aesthetic appeal or custom built-ins, primarily in home workshops or niche applications.
- Composite:Blended materials provide specific performance characteristics, such as enhanced impact resistance or reduced weight.
Longevity and strength define Steel, whereas Plastic offers flexibility and cost advantages.
End User:
The maturity of the end-user segment determines the sophistication and integration level of required storage solutions.
- Professional Mechanics:This segment requires highly durable, secure, and organized storage systems to maximize efficiency and protect valuable tools. The acute shortage of skilled technicians elevates the value of organizational systems that maximize individual productivity.
- Manufacturing Facilities:Large-scale operations demand integrated, often automated, storage solutions for inventory management and asset tracking across complex workflows. These facilities seek efficiency gains through better organization and smart technology integration.
- DIY Enthusiasts:Individuals pursuing home improvement or hobby projects seek cost-effective, user-friendly, and often portable storage solutions.
- Construction Workers:This segment needs rugged, portable, and secure storage for job site conditions, protecting tools from theft and damage.
- Workshop Owners:Businesses requiring comprehensive storage for multiple users and diverse tools prioritize durability, security, and modularity.
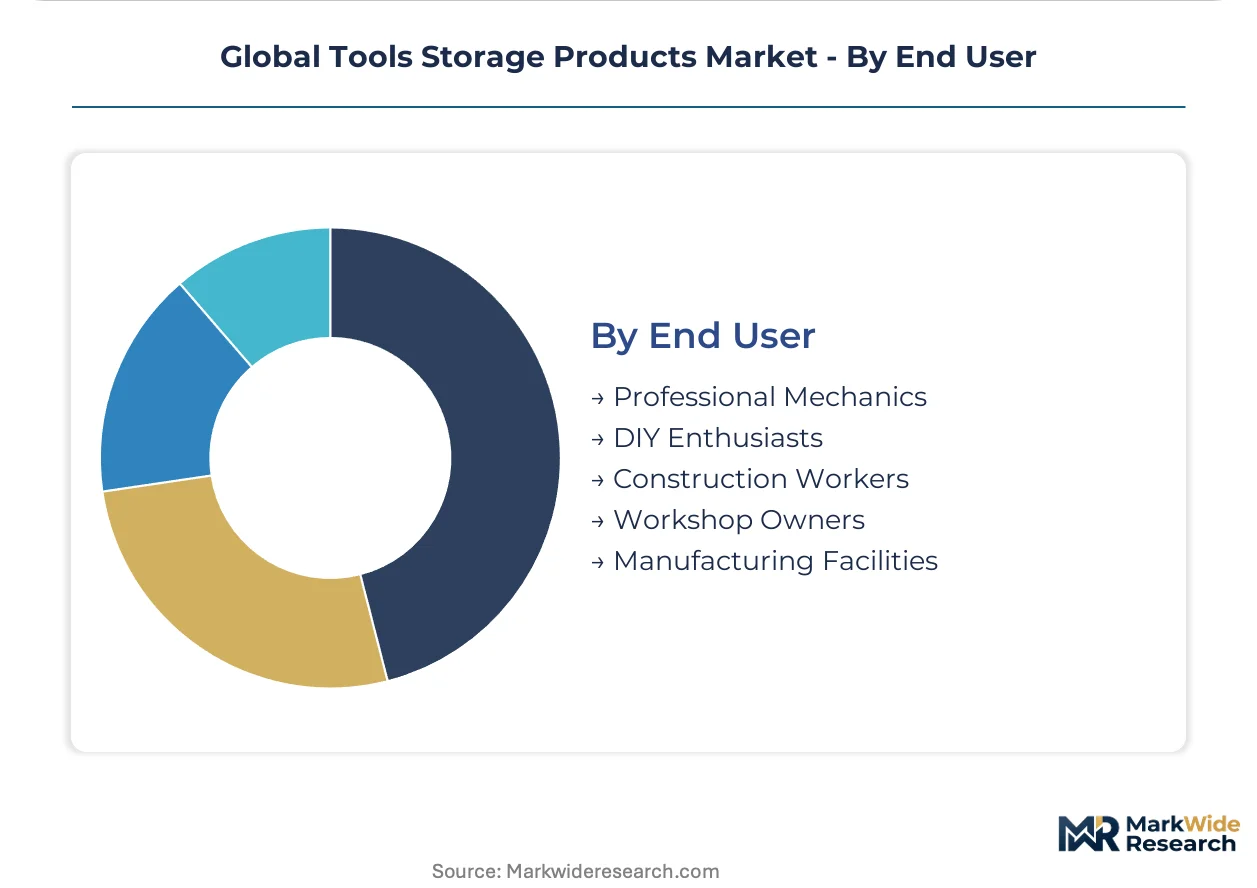
Demand from Professional Mechanics drives premium product innovation, while DIY Enthusiasts represent a high-volume segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry defines regional market dynamics, with premium professional-grade solutions commanding higher value in established industrial economies. Conversely, cost-effective and versatile storage options drive volume in developing construction sectors. This divergence influences product development and distribution strategies across key geographies.
United States
Sustained activity in residential and commercial construction fuels demand for durable, portable job site storage in the United States. OSHA standards guide workshop safety layouts, promoting investment in proper storage. Manufacturing facilities across the Midwest, particularly around Chicago, prioritize efficiency gains through advanced organizational systems.
Germany
Germany's automotive workshops drive demand for robust, high-capacity steel chests for specialized tools. CE marking and RoHS directives govern material composition for powered storage units. Bavarian engineering firms and automotive clusters around Stuttgart heavily invest in integrated tool management solutions.
China
Manufacturing facilities and the formalization of automotive repair sectors in China propel demand for scalable, organized storage systems. GB standards ensure product quality and safety for tools storage products. Industrial zones in the Yangtze River Delta, including Shanghai, are centers for advanced storage solution adoption.
United Kingdom
The United Kingdom's diverse professional trades and active DIY segment create consistent demand for modular and portable tool storage. While no longer an EU member, many products still adhere to CE marking for broader market access. Industrial estates and urban centers like Birmingham show strong uptake of efficient workshop organization systems.
India
India's expanding construction sector and formalization of automotive repair shops increase the need for durable, secure tool storage. BIS standards increasingly influence product specifications for quality and reliability. Major metropolitan areas such as Mumbai and Delhi drive significant adoption of professional-grade organizational systems.
Global Tools Storage Products Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the tools storage products market. The market structure exhibits a tiered consolidation, with premium brands focusing on integrated solutions and other players competing on value. Strategic archetypes include diversified industrial conglomerates, specialized professional-grade manufacturers, and mass-market providers. Dominant competitive moves involve portfolio diversification and the integration of smart technology features.
Integrated ecosystem providers like Milwaukee Tool exemplify a strategy focused on unified, battery-powered tool and storage systems for job sites, enhancing workflow efficiency. Diversified industrial conglomerates such as Stanley Black & Decker occupy a position leveraging extensive brand portfolios, including DeWalt, to serve various professional and DIY end-user needs. Meanwhile, Snap-on Incorporated anchors the premium professional segment through direct sales channels to automotive workshops, emphasizing durability, security, and specialized functionality for mechanics.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Milwaukee Tool |
| Snap-on Incorporated |
| Apex Tool Group |
| DeWalt |
| Bosch |
| Husky |
| Techtronic Industries |
| Kennedy Manufacturing |
| Others |
Cost & Logistics Intelligence
Economies of scale in manufacturing influence the global tools storage market, shaping both supply concentration and underlying price floors for high-volume products. This dynamic impacts how manufacturers balance cost efficiency with product differentiation across diverse end-user segments.
Pricing Analysis
The customization-premium spread defines pricing, with modular systems commanding higher value compared to standard, off-the-shelf units. Pricing structures often stratify across premium, standard, and economy tiers, driven by material quality (steel versus plastic) and brand reputation like Snap-on. Pricing softness runs through the DIY segment due to low-cost general-purpose container substitution. Professional mechanics exhibit lower price sensitivity, prioritizing durability and specialized functionality for their workshops.
Supply Chain Analysis
Inbound logistics costs, particularly global shipping rates and port congestion in Asia, significantly impact the tools storage supply chain. Supply concentration centers on manufacturing hubs in China for high-volume plastic components and Germany for precision steel fabrication. Raw material dependencies include industrial-grade steel and high-impact plastics, with commodity price volatility presenting a structural risk. Distribution channels run through mass-market retail, wholesale networks, and direct-to-professional sales models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global tools storage market presents a defensive moat story, primarily due to the high switching costs associated with integrated tool and storage ecosystems. Once invested in a brand's platform, users face significant hurdles to change.
For Market Incumbents:
Secure existing market share by investing in advanced material science for enhanced durability and integrating sophisticated digital tracking technologies. This strategy counters the threat of low-cost general-purpose alternatives and addresses software interoperability hurdles. Incumbents should leverage their established direct sales channels to reinforce brand loyalty and capture higher margins from professional mechanics.
For New Entrants and Emerging Players:
Lead with specialized, modular system configurations targeting underserved niches within developing economies like India and China. Focus on cost-effective, high-impact plastic solutions for DIY enthusiasts and small workshops, leveraging online direct-to-consumer channels. This approach capitalizes on the underpenetrated demand for basic, customizable storage solutions in these regions.
For Investors and Strategic Acquirers:
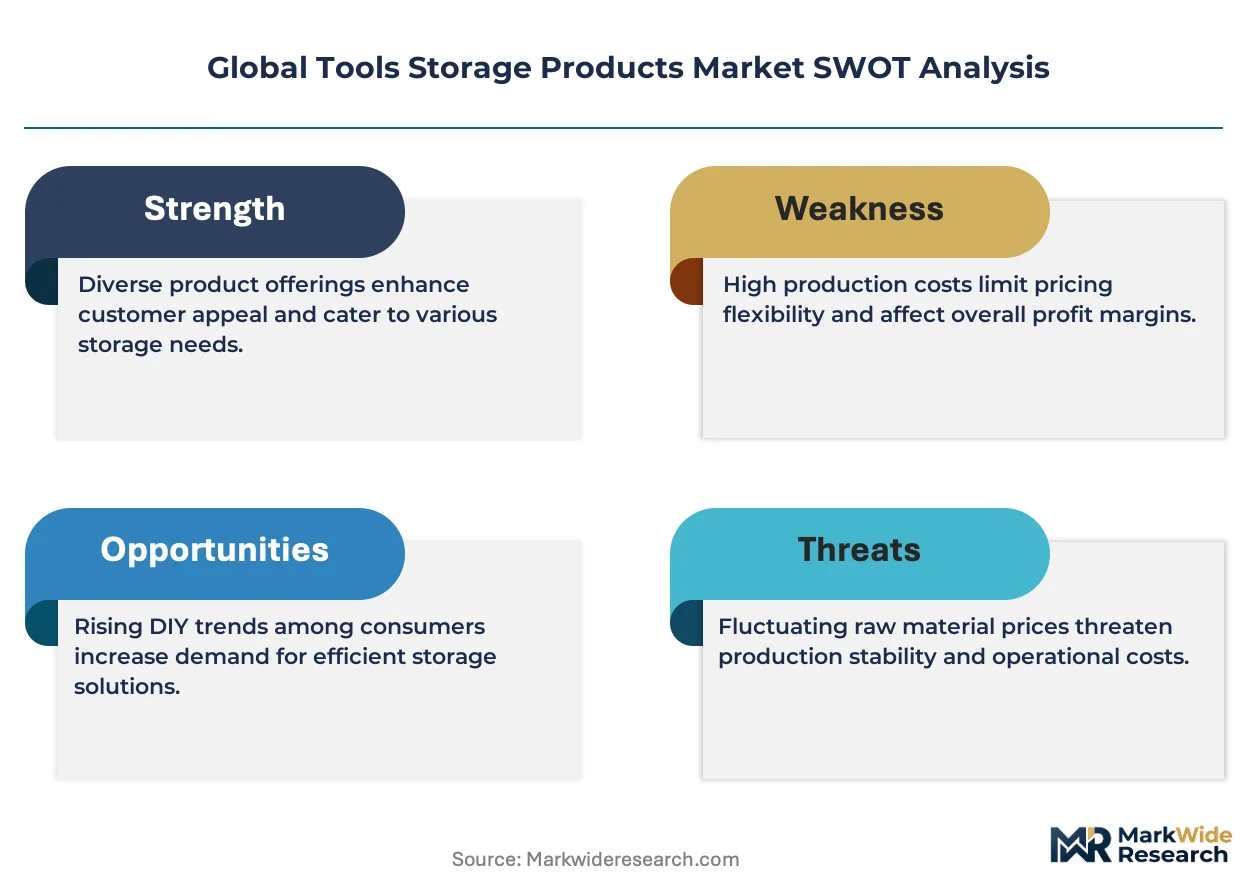
Mid-cycle technology positioning favors specialized manufacturers with strong intellectual property in smart storage and integrated ecosystems. The market's long-term viability remains strong, anchored by the essential nature of tools for skilled trades across construction and automotive sectors. Investors should watch for increasing adoption rates of integrated battery charging technology as a key inflection indicator for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Storage Ecosystem Development | Milwaukee Tool's integrated platforms enhance workflow efficiency for professional tradespeople on job sites. |
| Direct-to-Professional Channel Expansion | Snap-on Incorporated builds brand loyalty and captures higher margins from automotive workshop clients. |
| Advanced Material Science R&D | Stanley Black & Decker differentiates products like DeWalt by improving durability and load-bearing capacities. |
| Modular System IP Acquisition | Enhances customization capabilities, allowing diverse end-users to create tailored storage solutions. |
| Emerging Market Entry (India/China) | Expands market reach into rapidly formalizing automotive repair and construction sectors. |
Research Approach
A standing panel of professional mechanics, manufacturing facility managers, construction site supervisors, and procurement officers provided ongoing calibration for this analysis. This primary input was cross-referenced with extensive secondary validation from sources like OSHA reports, CE marking documentation, national trade statistics from the United States and Germany, and company financial filings. Both bottom-up and top-down triangulation methods were employed.
Outputs were validated against external benchmarks to ensure consistency across the analysis window, utilizing a robust analytical framework. Segmentation dimensions modeled included product type, storage capacity, material, end user, and regional demand patterns. Compound annual growth rates were derived from historical data and projected growth drivers, with construction sector activity and skilled labor availability as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant raw material price volatility, shifts in regulatory frameworks like RoHS, or unforeseen technological disruptions would require recalibration. Forecasts reflect assumptions regarding market dynamics and technological adoption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hacksaw Blades Market
Tools
Portable Tools Market
Tools
Horizontal Milling Machine Market
Tools
Telescopic Tool Boxes Market
Tools
Woodworking CNC Tools Market
Tools
Pneumatic Marking Machines Market
Tools
Europe Power Tools Market
Tools
Foam Cutting Machine Market
Tools
Floor Scraper Market
Tools
Surface Levelling Equipment Market
Tools
Vertical Milling Machine Market
Tools
Woodworking Tools Market
Tools
Crimping Tool Market
Tools
Paint Spray Guns Market
Tools
DIY Ball Mill Market
Tools
Global Staple Gun Market