
 Hungary Warehousing Sector Market | 2026-2036
Hungary Warehousing Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary Warehousing Sector Market Insights
Budapest industrial zone developers is realigning warehouse construction toward automated fulfillment campuses. CEVA Logistics leverages its intermodal hub network to anchor cross-border distribution across Central Europe. DB Schenker sustains competitive density through specialized pharmaceutical cold-chain infrastructure. Waberer's Group dominates domestic road-linked warehousing with integrated fleet-to-shed operations.
The Hungary warehousing sector encompasses facilities designed for goods storage, inventory management, and distribution logistics, typically featuring minimum 10-meter clear heights, ESFR sprinkler systems, and floor load capacities exceeding 5 tons per square meter to accommodate palletized and racked inventory. These structures serve manufacturers, retailers, and logistics operators requiring temporal buffer between production cycles and final delivery. Automated warehouse types capture premium lease rates as labor scarcity intensifies across Greater Budapest. Climate-controlled segments within the warehouse type category specialize in pharmaceutical and food-grade compliance, commanding differentiated pricing through validated temperature mapping. Robotics deployments under the technology dimension concentrate in e-commerce fulfillment centers where SKU fragmentation demands piece-picking automation.
Hungary's warehousing sector operates under EU REACH chemical storage protocols, national building authority fire safety certifications, and BREEAM sustainability benchmarks that increasingly determine facility financing eligibility. The country's national construction regulator enforces seismic and energy efficiency standards that extend development timelines but reduce long-term operational compliance risk. Stakeholders must monitor automation technology refresh cycles and regulatory alignment costs as decisive variables in facility investment returns.
Market Dynamics
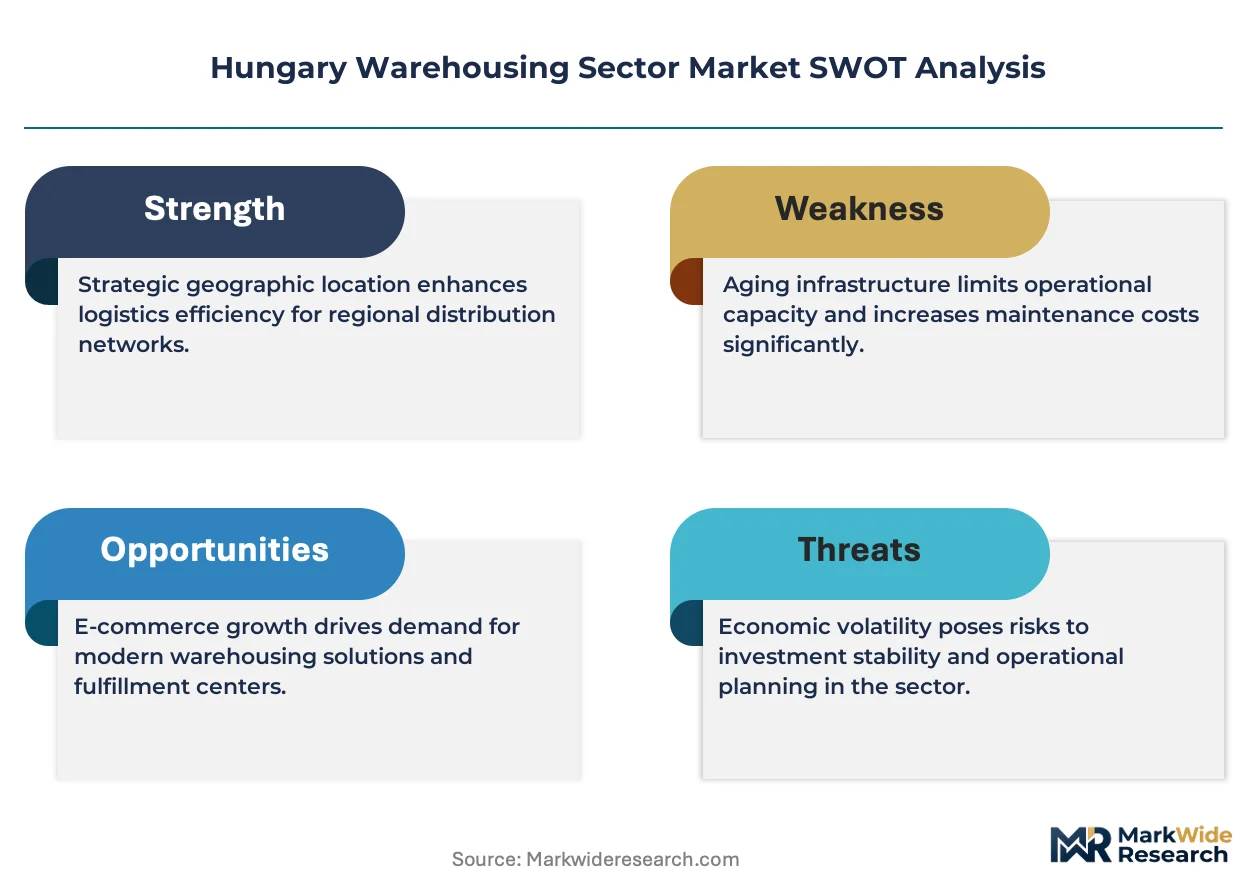
EU Green Deal compliance mandates are compressing facility energy retrofit timelines across Hungary's warehousing stock, forcing capital allocation toward automated fulfillment infrastructure that reduces per-unit carbon intensity while addressing acute labor scarcity in Greater Budapest.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics providers are expanding automated sortation capacity to handle SKU fragmentation from cross-border retail platforms serving Central European consumer bases.
- EU Green Deal energy standards:Facility financing eligibility increasingly ties to BREEAM certification thresholds, accelerating LED lighting and solar rooftop deployment across Budapest metropolitan corridors.
- Pharmaceutical cold-chain validation:Temperature-mapped warehouse segments command lease premiums as regional drug distribution hubs consolidate compliance-heavy inventory storage.
Market Restraints
- Construction input cost volatility:Steel and concrete price fluctuations extend development timelines for speculative warehouse builds in Pest County logistics zones.
- Seismic certification friction:Hungary's national building authority enforces structural standards that add 8-12 months to permit approval for automated high-bay facilities.
- Intermodal terminal congestion:Rail-linked warehousing capacity concentrates around Csepel and Ferencváros terminals, creating bottleneck risk for just-in-time inventory flows.
Strategic Opportunities
- Debrecen logistics corridor expansion:Eastern Hungary's underdeveloped industrial land offers first-mover positioning for e-commerce fulfillment campuses serving Romanian and Ukrainian transit routes.
- Robotics-as-a-service convergence:Piece-picking automation vendors are bundling hardware with predictive maintenance software, lowering capex barriers for mid-size 3PL operators.
- CSRD-aligned facility retrofits:EU corporate sustainability reporting requirements create tenant pull for warehouses with validated carbon accounting and renewable energy certificates.
Industry Challenges
- Automation technician scarcity:PLC programming and AGV maintenance skills command 40% wage premiums, constraining warehouse technology deployment velocity.
- Legacy WMS integration complexity:Brownfield facilities struggle to synchronize SAP or Oracle ERP systems with modern robotic orchestration platforms without operational downtime.
- Fire safety recertification timelines:ESFR sprinkler upgrades for automated high-bay configurations require extended facility shutdowns, disrupting tenant occupancy schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary Warehousing Sector Market |
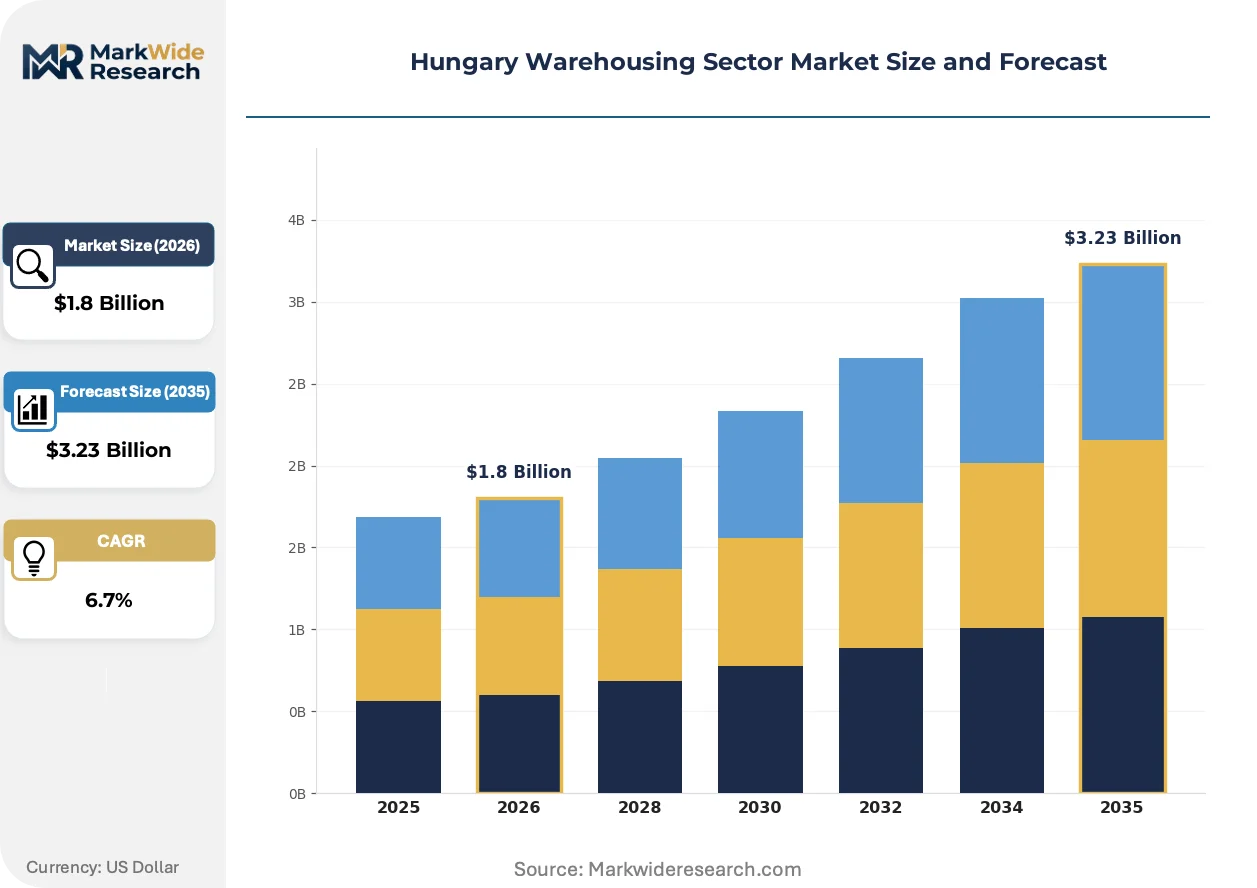
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Warehouse Type: Public, Private, Automated, Climate-Controlled Technology: WMS, RFID, IoT, Robotics Service Type: Storage, Distribution, Cross-Docking, Fulfillment Industry Vertical: Retail, E-Commerce, Automotive, Pharmaceuticals |
| Companies Covered | Trans-Sped Company Group, CEVA Logistics, QLM Logistics Solutions, Waberer's Group, Rhenus Logistics, DB Schenker, Raben Group, DHL Supply Chain, AIRMAX Cargo Budapest Zrt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary Warehousing Sector Market Trends and Innovations
Warehousing technology in Hungary is pivoting from standalone automation toward integrated fulfillment ecosystems where hardware, software, and energy systems interoperate. This convergence is compressing facility design cycles and redefining competitive differentiation around throughput per square meter rather than raw storage volume.
Autonomous mobile robots are modularizing warehouse layouts by eliminating fixed conveyor infrastructure. E-commerce fulfillment centers in Biatorbágy and Gyál are deploying AMR fleets that reconfigure pick paths hourly based on order wave patterns. This flexibility is modularizing capital deployment, allowing operators to scale automation incrementally rather than committing to monolithic fixed systems upfront.
EU Green Deal building performance standards are mandating near-zero operational carbon for new warehouse construction from 2030. Hungarian developers are pre-installing heat pump HVAC and battery storage to secure BREEAM Outstanding ratings that unlock green bond financing. Pharmaceutical and food-grade tenants are prioritizing these certified facilities to meet their own CSRD disclosure obligations.
Consolidated procurement of warehousing services is displacing fragmented multi-provider arrangements. Major retailers are awarding sole-source contracts to integrated 3PLs that control both transport and storage assets. This bundling is most visible among Budapest-based electronics and fashion distributors seeking unified visibility across inbound consolidation and last-mile delivery.
Hungary Warehousing Sector Market Segmentation
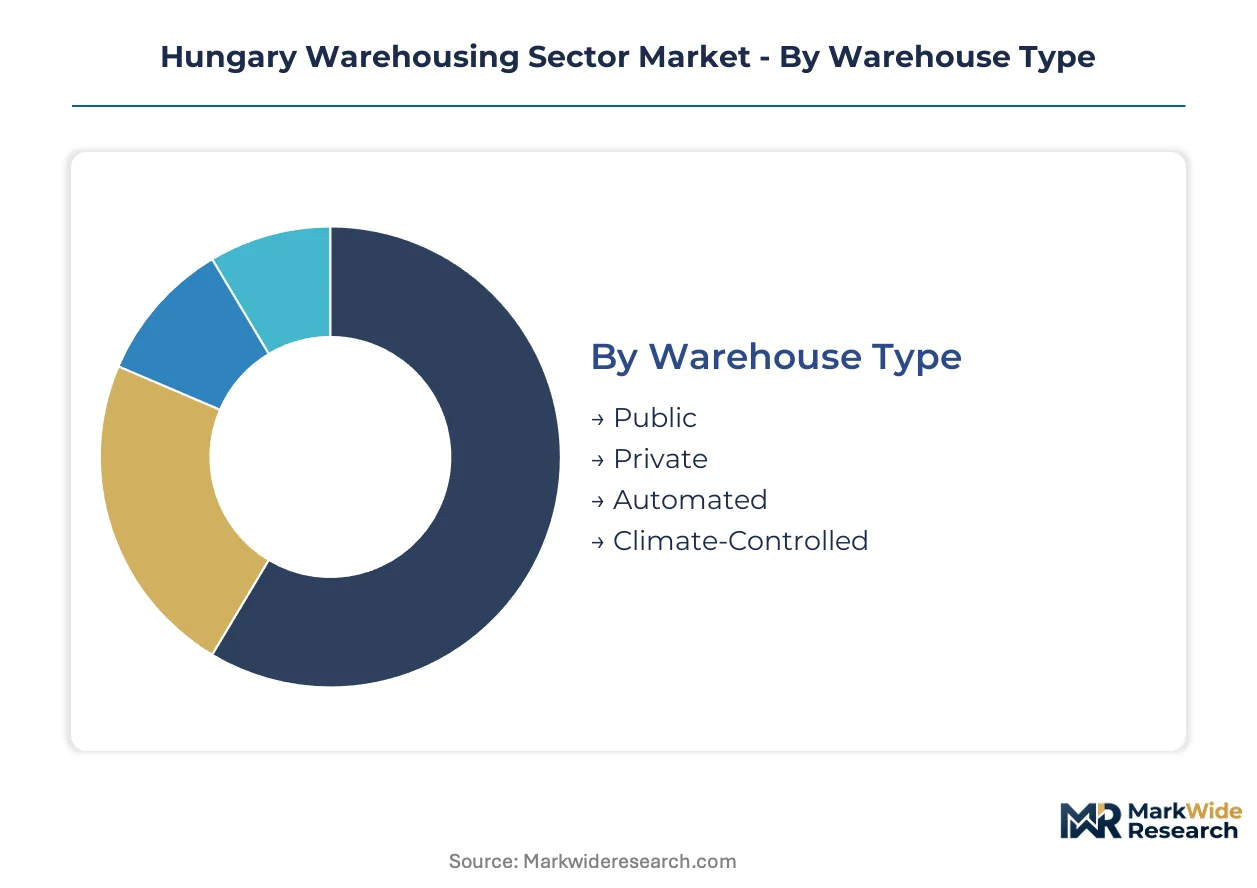
Segmentation in Hungary's warehousing sector reveals how facility design, technology integration, and service specialization map to distinct compliance burdens and capital intensity profiles. Each dimension carries specific regulatory obligations that reshape investment returns and tenant matching strategies.
Warehouse Type:
Certification requirements vary sharply across facility categories, with automated high-bay structures facing Hungary's national building authority seismic reviews and climate-controlled units requiring EU GDP validation for pharmaceutical tenants.
- Automated:These facilities incorporate AS/RS racking and robotic sortation systems with minimum 12-meter clear heights. Demand clusters around Budapest's Biatorbágy corridor where e-commerce 3PLs pursue throughput density per square meter. Labor scarcity in Greater Budapest accelerates lease premiums for these properties.
- Climate-Controlled:Temperature-mapped zones maintain 2-8°C or 15-25°C bands with validated HVAC redundancy. Pharmaceutical distributors in Pest County drive absorption as regional drug hubs consolidate compliant storage under EMA guidelines.
- Public:Multi-tenant facilities serve fragmented shippers with flexible lease terms and shared dock infrastructure.
- Private:Captive facilities align with single-owner inventory cycles, common among automotive component manufacturers.
Automated warehouses sit at the top of the volume ranking, with climate-controlled facilities climbing the fastest.
Technology:
Technology deployment patterns track labor cost gradients and SKU complexity, with capital-heavy solutions concentrating where wage inflation and order fragmentation intersect most acutely.
- Robotics:AMR fleets and piece-picking arms reconfigure pick paths dynamically based on order waves. E-commerce fulfillment centers in Gyál deploy these systems to handle SKU proliferation from cross-border retail platforms.
- WMS:Warehouse management systems orchestrate inventory tracking, labor allocation, and dock scheduling through cloud-native or on-premise architectures. Legacy SAP integrations dominate brownfield retrofits where downtime risk constrains modernization timelines.
- RFID:Radio-frequency identification enables real-time location tracking without line-of-sight scanning constraints.
- IoT:Sensor networks monitor environmental conditions, equipment health, and energy consumption across facility footprints.
Robotics commands the steepest expansion trajectory as 3PLs amortize hardware costs across multi-year fulfillment contracts.
Service Type:
Service specialization determines facility layout ratios—storage-dominant operations maximize cube utilization while fulfillment-heavy sites prioritize pick-face density and outbound dock capacity.
- Fulfillment:These operations combine storage with value-added services including kitting, labeling, and returns processing. Budapest metropolitan corridors attract concentration as electronics and fashion retailers consolidate procurement with integrated transport providers.
- Cross-Docking:Flow-through facilities minimize inventory dwell time through synchronized inbound and outbound scheduling. CEVA Logistics leverages these configurations at its intermodal hubs for Central European distribution velocity.
- Storage:Long-hold inventory buffering serves seasonal demand patterns and supply chain risk mitigation.
- Distribution:Regional break-bulk operations consolidate upstream shipments for downstream route optimization.
Fulfillment services generate the highest revenue per pallet position, with cross-docking gaining share fastest among time-sensitive verticals.
Industry Vertical:
Vertical-specific requirements fragment facility specifications—automotive demands just-in-time sequencing docks while pharmaceutical tenants enforce EU GDP cold-chain validation.
- Pharmaceuticals:These facilities require temperature mapping, backup power systems, and audit trails under EMA distribution guidelines. DB Schenker maintains competitive density through specialized cold-chain infrastructure serving regional drug distribution consolidation.
- E-Commerce:Fragmented SKU profiles and returns processing drive automation adoption. Third-party logistics providers expand automated sortation capacity to handle order volatility from cross-border retail platforms.
- Retail:Seasonal inventory cycles and promotional surge capacity shape warehouse specifications.
- Automotive:Sequenced parts delivery and production-line synchronization dictate facility location relative to assembly plants.
E-commerce verticals absorb the most automated square footage, with pharmaceuticals delivering the highest lease rate premiums per cubic meter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal compliance costs are fragmenting warehousing investment across Central Europe, with developers arbitraging regulatory stringency gaps between member states. Capital migrates toward jurisdictions offering faster permitting for automated facilities while maintaining single-market access.
Germany
Automotive and pharmaceutical distributors drive demand for sequencing-capable warehouses near Stuttgart and Munich production corridors. The KBA enforces stringent facility safety standards that extend development timelines but reduce operational risk. Frankfurt Rhine-Main logistics clusters concentrate cold-chain investments serving EMA-regulated drug distribution.
Poland
E-commerce fulfillment platforms anchor warehouse absorption around Warsaw and Łódź metropolitan zones. National building codes under EU energy performance directives mandate solar-ready roofing for new industrial construction. Upper Silesia logistics corridors attract German automotive suppliers seeking lower land costs with motorway connectivity.
Czech Republic
Just-in-time automotive parts storage dominates warehouse specifications near Brno and Ostrava assembly plants. The national construction authority applies seismic standards comparable to Hungary's 8-12 month permitting friction. Prague peripheral zones concentrate automated high-bay development for electronics distribution.
Slovakia
Cross-border consolidation hubs serve Hungarian and Austrian transit routes from Bratislava and Žilina industrial parks. EU cohesion fund infrastructure subsidies accelerate rail-terminal linked warehouse construction. Western Slovakia logistics zones compete directly with Budapest corridors for Central European distribution contracts.
Romania
Underdeveloped warehousing stock in Transylvania and Banat regions offers first-mover positioning for e-commerce fulfillment serving southeastern EU markets. National building regulations lag Hungarian seismic certification complexity, compressing development timelines. Constanța port-linked zones attract Asian import consolidation operations.
Hungary Warehousing Sector Market Competitive Landscape
Budapest-based operators anchor one tier; Western European logistics specialists hold integrated network positions across Central Europe. The market structure fragments between domestic road-linked providers and international 3PLs with intermodal capabilities. Three archetypes dominate: fleet-integrated domestic hauliers, automated fulfillment campus developers, and pharmaceutical cold-chain validators. Capacity expansion and strategic partnerships constitute the primary competitive vectors as operators secure scarce industrial land around metropolitan corridors.
Among Hungary-based logistics groups, Waberer's Group and Trans-Sped Company Group represent the fleet-integrated archetype, combining captive trucking assets with shed operations to control handoff costs. CEVA Logistics exemplifies the intermodal-network specialist position, leveraging cross-border rail connectivity to anchor Central European distribution density. These three companies occupy distinct competitive spaces—domestic road dominance, international network integration, and automated fulfillment infrastructure—rather than direct confrontation across identical service segments.
| Leading Market Players |
|---|
| Trans-Sped Company Group |
| CEVA Logistics |
| QLM Logistics Solutions |
| Waberer's Group |
| Rhenus Logistics |
| DB Schenker |
| Raben Group |
| DHL Supply Chain |
| AIRMAX Cargo Budapest Zrt |
| Others |
Pricing and Supply Chain Analysis
Fleet-to-shed vertical integration anchors pricing power for domestic road-linked operators while compressing margins for asset-light competitors dependent on third-party trucking capacity. This captive transport control allows integrated 3PLs to bundle storage and haulage at rates that standalone warehouse providers cannot match, particularly across Budapest metropolitan corridors where land scarcity intensifies facility cost premiums.
Pricing Analysis
Distributor margin stacking in multi-tenant public warehousing creates three-tier pricing separation across automated, climate-controlled, and standard bulk storage tiers. Certification under BREEAM and EU GDP validation drives premium lease rates, with pharmaceutical cold-chain facilities commanding the highest per-cubic-meter positioning. Cost compression in speculative greenfield development is intensifying as steel and concrete input volatility extends financing timelines. Mid-size 3PL operators show greatest price sensitivity, while integrated logistics groups with captive fleets absorb rate fluctuations through internal cost allocation.
Supply Chain Analysis
Direct-to-tenant lease channels dominate warehouse absorption, bypassing traditional property brokers for major 3PL operators with multi-year fulfillment contracts. Raw material sourcing draws from German steel fabricators, Italian HVAC systems suppliers, and Polish concrete producers for structural components. Single-source vulnerability concentrates in automated racking systems sourced from Austrian and German engineering specialists. Distribution runs through Budapest's Biatorbágy and Gyál logistics corridors, with secondary clustering around Debrecen emerging for eastern transit routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hungary's warehousing sector functions as a regulatory compounder where EU Green Deal building performance mandates are accelerating tenant demand for BREEAM-certified facilities. This compliance-driven demand shift rewards operators with pre-certified development pipelines.
For Market Incumbents: Deploy automation technician apprenticeship programs to address PLC programming and AGV maintenance scarcity that constrains robotic deployment velocity. Secure long-term land options in Pest County logistics zones before seismic certification friction extends competitor permitting timelines. Threat substitution from robotics-as-a-service vendors demands defensive capability building in predictive maintenance software integration. For New Entrants and Emerging Players: Digital-channel route optimization platforms offer white-space entry points for mid-size 3PLs seeking to bypass legacy WMS integration complexity. Target Debrecen logistics corridor expansion where underdeveloped industrial land enables first-mover positioning for e-commerce fulfillment campuses serving Romanian and Ukrainian transit routes. Lead with CSRD-aligned carbon accounting services as the go-to-market wedge for sustainability-conscious tenants. For Investors and Strategic Acquirers: Consolidation pressure builds where automation capex requirements outstrip mid-size operator balance sheet capacity, creating acquisition opportunities for platform rollup strategies. Long-term viability favors vertically integrated operators with captive fleet assets and BREEAM-certified development pipelines. Watch intermodal terminal capacity expansion at Csepel and Ferencváros as the inflection signal for rail-linked warehousing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics-as-a-Service Partnership | Bundled hardware and predictive maintenance software lowers capex barriers for mid-size 3PL operators. |
| BREEAM Outstanding Certification | Pre-installed heat pump HVAC and battery storage unlocks green bond financing eligibility under EU Green Deal standards. |
| Debrecen Logistics Corridor Expansion | Eastern Hungary's underdeveloped industrial land offers first-mover positioning for cross-border fulfillment campuses. |
| Automation Technician Training Program | Internal PLC programming and AGV maintenance capability addresses 40% wage premiums constraining deployment velocity. |
| CSRD-Aligned Carbon Accounting Platform | Validated renewable energy certificates attract pharmaceutical and food-grade tenants facing sustainability disclosure obligations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics facility developers, 3PL operations directors, pharmaceutical supply chain managers, and commercial real estate investment officers with secondary validation. Bottom-up and top-down triangulation incorporated customs and trade data, national building authority permit filings, EU energy performance directive implementation reports, and BREEAM certification databases alongside SEC filings from listed logistics operators.
Segment-weighting across warehouse type, technology deployment, service specialization, and industry vertical dimensions shaped the analytical framework over the projection horizon. CAGRs derived from facility absorption rates, lease rate trajectories, and automation investment cycles were applied across automated, climate-controlled, public, and private warehouse categories. Forecast inputs included EU Green Deal compliance cost curves, seismic certification timeline distributions, and intermodal terminal capacity utilization patterns.
Construction input cost volatility, regulatory timeline extensions, and automation technology refresh cycles are the dominant revision risks that could alter facility investment return assumptions. Forecasts reflect documented assumptions around energy standard implementation schedules and labor market tightness persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
South Korea Self-Storage Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
Real Estate Management Software Market
Property Management
Property Management Software Market
Property Management
Real Estate (Property) Management Market
Property Management
Qatar Flexible Office Space Market
Property Management
Europe Self Storage Market
Property Management
Property Management Service Market
Property Management
United States Property Management Market
Property Management
Residential Property Management Market
Property Management
US Property Management Software Market
Property Management
Spain Warehousing Market