
 Qatar Flexible Office Space Market | 2026-2036
Qatar Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Flexible Office Space Market Analytics
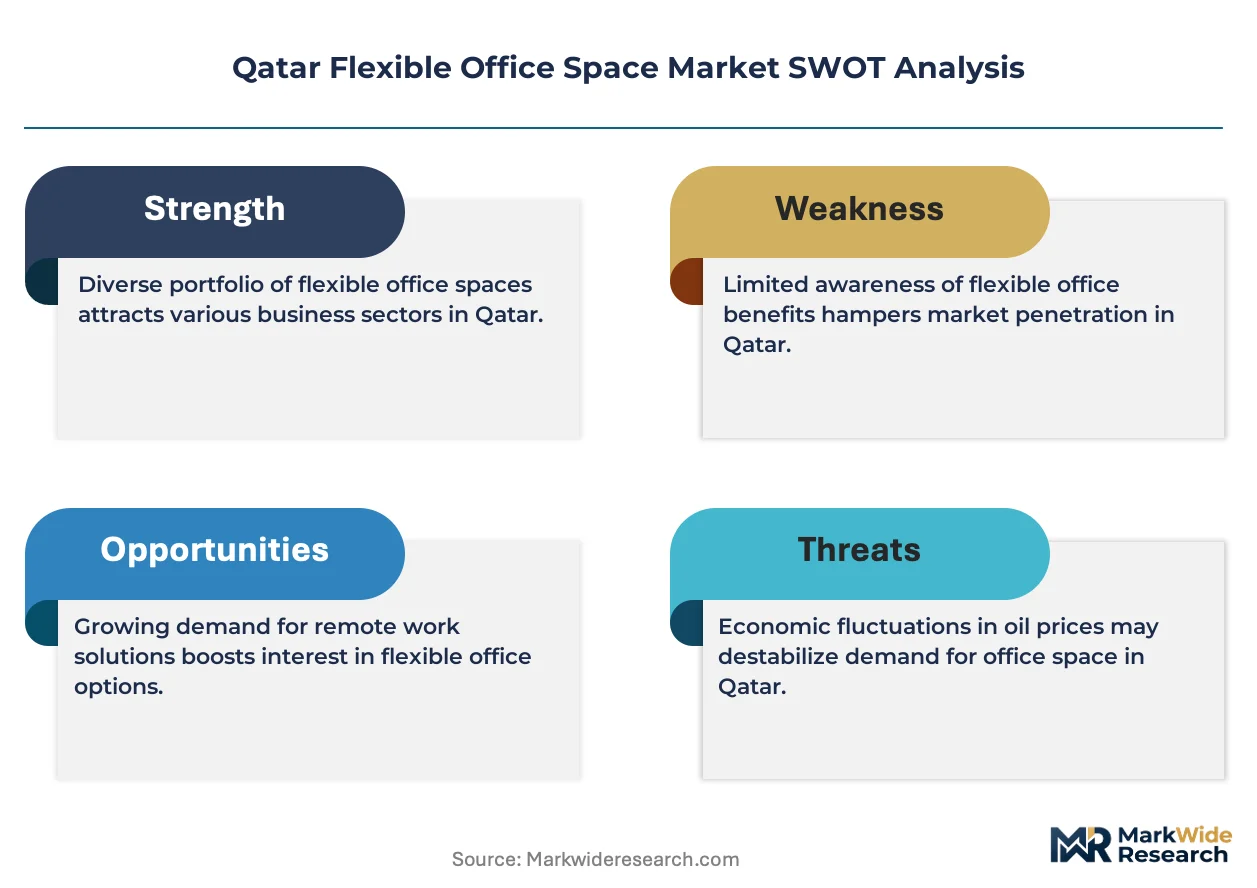
Technology and consulting firm tenancy is expanding across Qatar's flexible office inventory as energy sector employers reduce permanent square footage. Regus Group Companies leverages its established West Bay presence to anchor premium private office demand from European multinationals. Workinton competes through localized Arabic-language service tiers and SME-focused subscription terms. Spaces differentiates via design-forward lounge amenities targeting creative agency tenants.
Qatar Flexible Office Space denotes commercially leased work environments offering variable tenure, shared infrastructure, and managed services rather than conventional fixed-term real estate commitments. Operators typically provide furnished workstations, high-speed connectivity, and on-demand meeting infrastructure within Class A or Class B commercial towers. Co-working spaces and private offices lead current inventory absorption, while virtual office service models capture fastest-growing interest from Gulf-based freelancers and lean consultancies seeking registered business addresses without physical occupancy. Subscription-based pricing structures concentrate margin pools in the mid-market SME segment, where annual contract values balance retention against operational complexity.
Qatar's Ministry of Commerce and Industry governs commercial licensing and foreign ownership thresholds that directly determine which tenant categories can legally occupy flexible workspaces. The Qatar Central Bank's regulatory framework for fintech and digital payment startups shapes demand from financial technology ventures seeking compliant office infrastructure. The Qatar Free Zones Authority offers alternative jurisdictional pathways that compete with mainland flexible office providers for certain international entrants. Stakeholders must monitor how forthcoming commercial property law revisions treat short-license versus long-lease tenant protections.
Market Dynamics
Qatar's commercial licensing streamlining by the Ministry of Commerce and Industry is accelerating flexible workspace absorption as energy sector employers shed permanent real estate commitments and technology consultancies expand variable-tenure footprints.
Growth Catalysts
- Regulatory simplification:The Ministry of Commerce and Industry's streamlined commercial licensing for service sectors reduces entry barriers for foreign consultancies and fintech ventures seeking compliant workspace infrastructure.
- Energy sector restructuring:State-owned and international energy employers are downsizing permanent headquarters square footage, redirecting demand toward serviced offices and co-working subscriptions in Doha's commercial towers.
- Technology adoption:Cloud-based workspace management platforms enable operators to offer on-demand meeting infrastructure and flexible subscription tiers without proportional overhead expansion.
Market Restraints
- Input cost volatility:Class A commercial tower rents in West Bay and Lusail fluctuate with Qatar's construction cycle, compressing operator margins during peak development phases.
- Regulatory friction:The Qatar Central Bank's fintech compliance framework imposes physical infrastructure requirements that conflict with lean virtual office service models for certain financial technology ventures.
- Substitution threat:The Qatar Free Zones Authority offers alternative jurisdictional pathways with dedicated office infrastructure, diverting certain international entrants from mainland flexible workspace providers.
Strategic Opportunities
- Underpenetrated geography:Al Wakrah and Al Khor industrial zones lack flexible workspace supply despite growing SME manufacturing and logistics activity outside Doha's core districts.
- Regulatory tailwind:Anticipated commercial property law revisions may clarify short-license tenant protections, reducing legal uncertainty that currently constrains contract durations.
- Technology convergence:Integration of IoT-enabled occupancy sensors with building management systems allows operators to monetize usage data and optimize space allocation dynamically.
Industry Challenges
- Skill gap:Bilingual Arabic-English community management talent remains scarce, limiting operators' ability to deliver localized service tiers for Gulf SME segments.
- Capex intensity:Premium lounge amenities and design-forward fit-outs require substantial upfront investment with payback periods exceeding typical subscription contract lengths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Flexible Office Space Market |
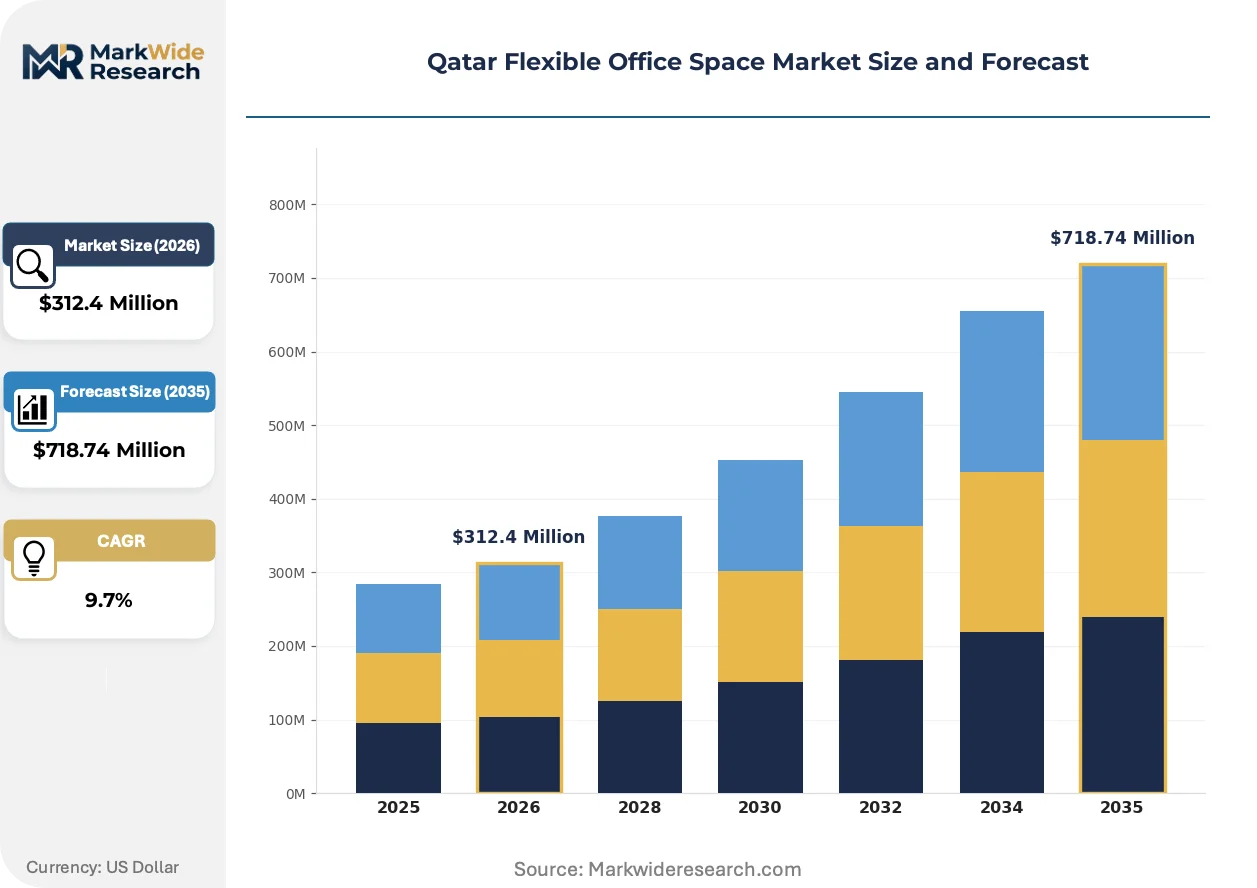
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Office Type: Co-working Spaces, Private Offices, Hot Desks, Business Centers Service Model: Pay-As-You-Go, Subscription-Based, Long-Term Lease, Virtual Office Target Industry: Tech Startups, Freelancers, SMEs, Large Corporations Amenity Type: Meeting Rooms, Event Spaces, Lounge Areas, Kitchen Facilities |
| Companies Covered | spaceOS Limited, Spaces, Servcorp, RAWQ Business Center, Davinci Virtual, Regus Group Companies, Workinton, Regus, Alliance Business Centers Network, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Flexible Office Space Market Evolving Landscape
Workspace technology and tenant service expectations are reshaping competitive differentiation as operators compete for multinational regional headquarters and lean consultancy segments.
Smart building management systems are decentralizing operational control across Qatar's flexible office inventory. These platforms integrate HVAC, access control, and meeting room booking through unified dashboards. Technology consultancies and creative agencies are adopting them fastest to support hybrid work patterns. This decentralization is compressing the advantage of established operators with legacy centralized management structures.
The Qatar Central Bank's evolving fintech regulatory framework is mandating enhanced physical infrastructure compliance for digital payment startups. This creates demand for flexible workspaces with pre-certified server rooms and secure connectivity. Fintech ventures seeking compliant office infrastructure represent the most affected segment, driving operators to pursue specialized certification tiers.
Subscription-based procurement models are displacing traditional fixed-term leases among SME tenants. Annual contract values balance retention against operational complexity for operators. This shift concentrates margin pools in the mid-market segment where Workinton and Regus Group Companies compete most directly. The trend is most visible among Gulf-based freelancers and lean consultancies seeking registered business addresses without physical occupancy.
Qatar Flexible Office Space Market Segmentation
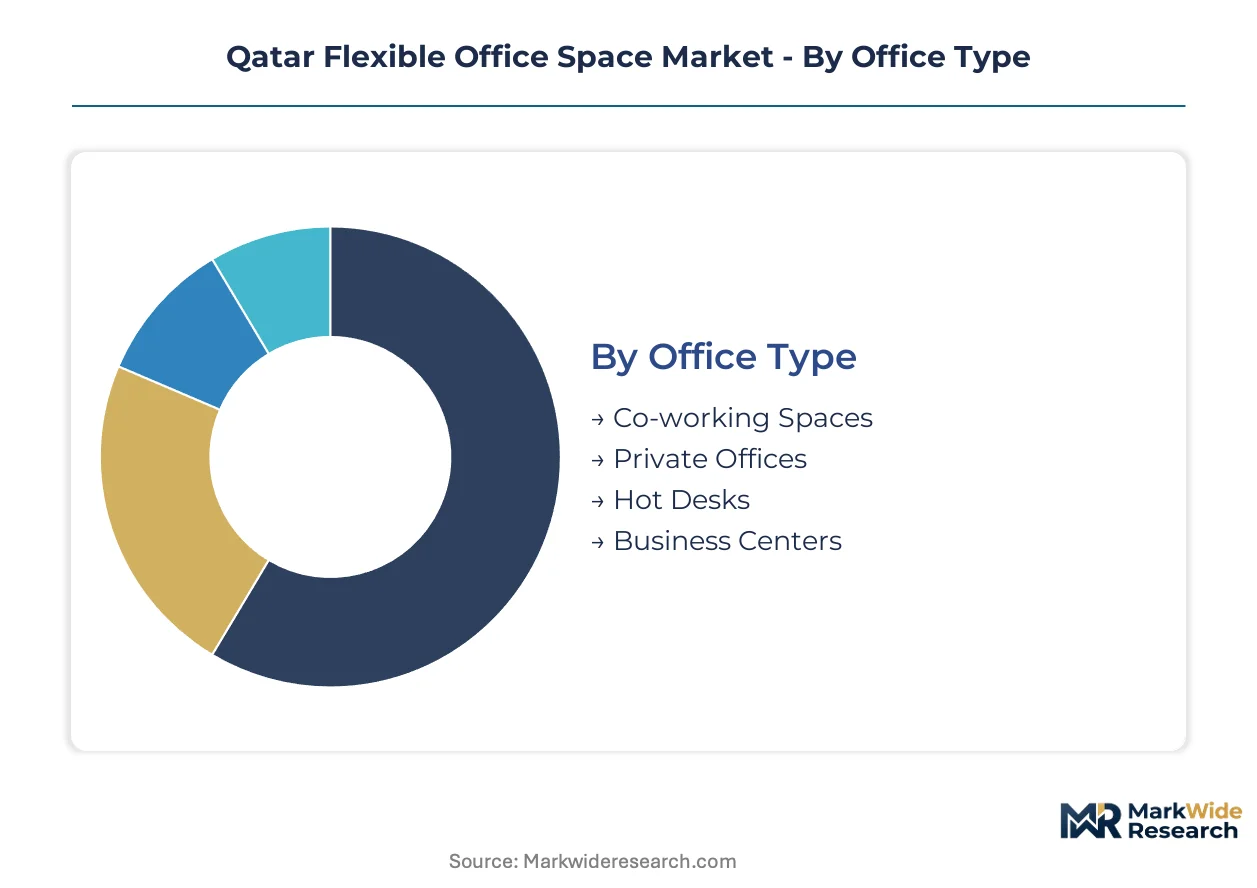
Flexible office operators in Qatar segment inventory to match tenant risk profiles against revenue stability. Subscription tenures and amenity tiers determine margin capture across West Bay and Lusail commercial towers.
Office Type:
Physical workspace configurations differentiate by privacy level and infrastructure commitment.
- Co-working Spaces:Open-plan environments with shared workstations and communal infrastructure. Tech startups in Doha's West Bay district cluster here for network effects and reduced capital outlay.
- Private Offices:Enclosed suites with dedicated access control and branded reception. European multinationals establishing regional headquarters in Lusail demand these for confidentiality compliance and client-facing protocols.
- Hot Desks:Unassigned seating with daily or hourly access credentials. Freelancers and lean consultancies use these for registered business addresses without fixed overhead.
- Business Centers:Fully serviced corporate suites with administrative support and meeting infrastructure. Large corporations downsizing permanent square footage redirect legacy lease commitments here.
Private offices lead on scale; co-working spaces lead on momentum.
Service Model:
Contract structures align tenant cash flow patterns with operator revenue predictability.
- Subscription-Based:Monthly or annual recurring contracts with tiered access levels. SMEs across Qatar's service sectors favor these for budget certainty and operational flexibility.
- Virtual Office:Registered address and mail handling without physical occupancy. Gulf-based freelancers and lean consultancies expanding fastest into this model for licensing compliance at minimal cost.
- Pay-As-You-Go:Usage-based billing for meeting rooms and day passes. Sporadic demand from project-based consultants concentrates in Doha's central business district.
- Long-Term Lease:Fixed multi-year commitments with customization rights. Energy sector employers transitioning from permanent headquarters occupy these for cost predictability.
Subscription-based contracts anchor revenue stability; virtual office services are climbing the fastest.
Target Industry:
Tenant sector concentration shapes amenity programming and community management requirements.
- SMEs:Mid-market enterprises with 10-100 employees seeking scalable square footage. This segment absorbs the majority of flexible inventory in Lusail's emerging business district.
- Tech Startups:Venture-backed and bootstrapped software ventures requiring compliant infrastructure. Fintech ventures specifically seek pre-certified server rooms under Qatar Central Bank guidelines.
- Freelancers:Independent professionals and solo consultants needing professional addresses. Rapid growth among Gulf nationals leveraging streamlined commercial licensing.
- Large Corporations:Established multinationals and state-owned entities restructuring real estate portfolios. Energy sector employers dominate this category as they shed permanent headquarters commitments.
SMEs dominate current absorption; tech startups show steepest expansion trajectory.
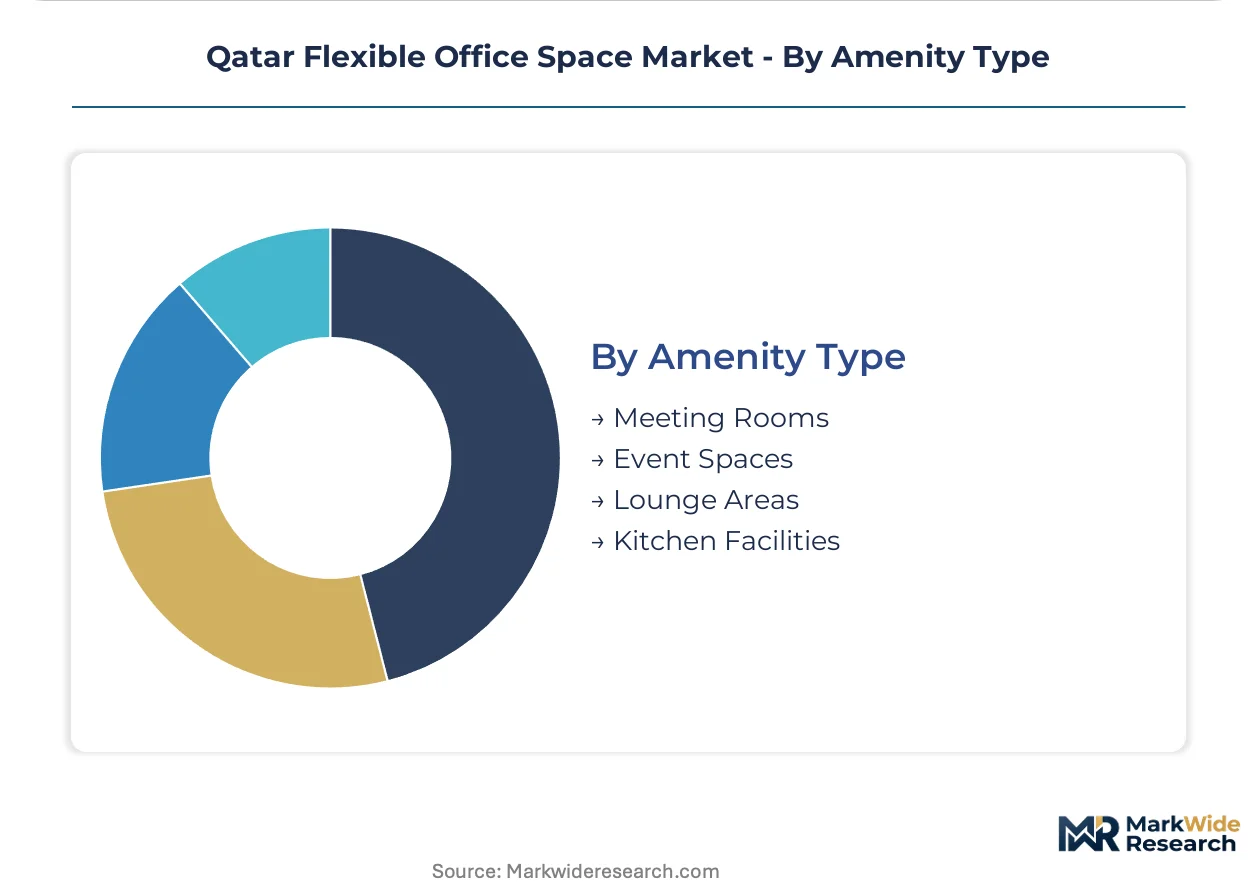
Amenity Type:
Shared infrastructure monetization extends per-tenant revenue beyond base workspace fees.
- Meeting Rooms:Bookable enclosed spaces with AV equipment and catering coordination. Corporate tenants in West Bay generate premium utilization rates for client presentations.
- Lounge Areas:Design-forward communal zones with hospitality programming. Creative agencies differentiate operator selection based on these amenities for talent recruitment.
- Event Spaces:Configurable venues for product launches and industry gatherings. Tech startups leverage these for community building and investor visibility.
- Kitchen Facilities:Catering infrastructure and refreshment services. Standard inclusion across all tiers but quality differentiation influences renewal rates.
Meeting rooms generate highest ancillary revenue; lounge areas drive competitive differentiation most directly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory simplification across Qatar's commercial zones is redirecting tenant formation toward jurisdictions with lower compliance friction, compressing demand concentration in Doha's core districts while peripheral municipalities absorb spillover from licensing bottlenecks.
West Bay
European multinationals establishing regional headquarters drive private office absorption in this central business district. The Ministry of Commerce and Industry's streamlined service-sector licensing reduces entry barriers for foreign consultancies seeking compliant workspace infrastructure. Class A commercial towers here command premium rents as Regus Group Companies anchors established presence.
Lusail
SMEs with 10-100 employees absorb the majority of flexible inventory in this emerging business district. Qatar Central Bank fintech compliance requirements shape demand from digital payment startups seeking pre-certified server infrastructure. New business district zoning concentrates multinational regional headquarters alongside mid-market subscription contracts.
Al Wakrah
Manufacturing and logistics SMEs outside Doha's core generate underpenetrated demand for industrial-zone flexible workspace. The Qatar Free Zones Authority competes for certain international entrants with dedicated office infrastructure alternatives. Growing SME activity here lacks corresponding flexible supply despite proximity to Hamad International Airport logistics corridors.
Al Khor
Energy sector employers restructuring real estate portfolios redirect legacy commitments toward serviced offices in this northern municipality. The Ministry of Commerce and Industry's foreign ownership thresholds determine which tenant categories can legally occupy flexible workspaces here. State-owned energy headquarters downsizing creates demand concentration absent incumbent operator presence.
The Pearl-Qatar
Creative agencies and hospitality-linked consultancies seek design-forward lounge amenities in this mixed-use development. Qatar's commercial property law revisions may clarify short-license tenant protections, reducing legal uncertainty that constrains contract durations. Premium amenity programming here differentiates operator selection for talent recruitment.
Qatar Flexible Office Space Market Competitive Landscape
Portfolio diversification dominates the current landscape as operators balance premium private office commitments against virtual office service expansion. The vendor base organizes around three strategic archetypes: established international networks with standardized service tiers, regional specialists offering localized Arabic-language support, and design-forward boutique operators targeting creative industry tenants. M&A activity remains limited given Qatar's concentrated geographic demand, while technology licensing partnerships accelerate cloud-based workspace management deployment.
Among international network operators, Regus Group Companies and Spaces exemplify the scale-driven archetype with established West Bay presence, while Workinton occupies a position within the regional specialist tier emphasizing SME-focused subscription terms. These three anchors illustrate how competitive positioning stratifies across premium private office, mid-market recurring contract, and virtual office service vectors without proportional physical footprint expansion.
| Leading Market Players |
|---|
| spaceOS Limited |
| Spaces |
| Servcorp |
| RAWQ Business Center |
| Davinci Virtual |
| Regus Group Companies |
| Workinton |
| Regus |
| Alliance Business Centers Network |
| Others |
Value Network & Pricing Analysis
European multinationals establishing regional headquarters in West Bay and Lusail anchor premium private office demand, concentrating pricing power with operators offering compliant infrastructure under Qatar's streamlined commercial licensing framework. This buyer concentration reinforces subscription-based recurring contracts as the dominant pricing model across Class A commercial towers.
Pricing Analysis
Operator margin capture rests on annual contract values balancing retention against operational complexity. Three-tier pricing structure across premium private offices, standard co-working memberships, and economy virtual office tiers differentiates by amenity depth and physical occupancy rights. Cost compression in mid-market SME subscriptions is intensifying because Workinton and Regus Group Companies compete directly on localized service tiers. Freelancers and lean consultancies demonstrate highest price sensitivity, while energy sector employers transitioning from permanent headquarters show lowest sensitivity due to cost predictability requirements.
Supply Chain Analysis
Class A commercial tower supply draws from Qatar's domestic construction cycle and imported fit-out materials from Germany, Italy, and China. Smart building management platforms, IoT-enabled occupancy sensors, and cloud-based workspace software constitute critical technology inputs. Single-source vulnerability in bilingual Arabic-English community management talent constrains service tier expansion. Distribution runs through direct operator-tenant relationships in West Bay and Lusail, with limited channel intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's flexible office market offers geographic-arbitrage value against Dubai's saturated premium inventory, exploiting lower West Bay rents and streamlined Ministry of Commerce and Industry licensing timelines.
For Market Incumbents: Anticipate regulatory friction from Qatar Central Bank fintech compliance requirements by pre-certifying server infrastructure and secure connectivity tiers. Defend against Qatar Free Zones Authority substitution threats by anchoring mainland presence with localized Arabic-language service capabilities. Prioritize vertical integration into cloud-based workspace management platforms to compress operational overhead without proportional staff expansion. For New Entrants and Emerging Players: Enter via Al Wakrah and Al Khor industrial zones where manufacturing and logistics SME activity lacks corresponding flexible workspace supply. Target energy sector employers restructuring real estate portfolios in northern municipalities absent incumbent operator presence. Pursue a certification-first go-to-market angle emphasizing Qatar Central Bank pre-certified infrastructure for fintech ventures. For Investors and Strategic Acquirers: Regional real estate investment trusts with hospitality and commercial property portfolios are the most active acquirer in this space, seeking operational platform integration. Long-term viability hinges on regulatory tailwinds from anticipated commercial property law revisions clarifying short-license tenant protections. Monitor Qatar Central Bank fintech framework evolution as the critical inflection signal for specialized infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Technology Integration | IoT-enabled occupancy sensors allow operators to monetize usage data and optimize space allocation dynamically. |
| Localized Service Tier Development | Arabic-language community management capabilities capture Gulf SME segments underserved by international operators. |
| Fintech Infrastructure Certification | Pre-certified server rooms under Qatar Central Bank guidelines attract digital payment startups seeking compliance. |
| Geographic Expansion to Industrial Zones | Al Wakrah and Al Khor presence captures manufacturing and logistics SME demand outside Doha's core districts. |
| Virtual Office Service Scaling | Registered address offerings without physical occupancy capture fastest-growing freelancer and lean consultancy segments. |
Research Methodology
Bottom-up tenant segmentation modeling reconciled against top-down operator inventory tracking forms the analytical core of this study. Primary interviews with flexible workspace operators, commercial real estate brokers, facility managers at multinational regional headquarters, and Qatar Ministry of Commerce and Industry licensing officials were validated against secondary sources including Qatar Central Bank regulatory circulars, Qatar Free Zones Authority investment reports, commercial property lease databases, and operator subscription pricing disclosures.
Input-output matrices mapped subscription tenure patterns, amenity utilization rates, and sectoral demand concentrations across office type, service model, target industry, and geography dimensions. CAGRs were derived from regression analysis of historical absorption rates against regulatory milestone timing and energy sector employment trends. Forecast inputs incorporated Qatar's construction cycle phases and anticipated commercial property law revision scenarios.
Inputs from operator pricing disclosures and regulatory filings were available through the study window; gaps in forward-looking tenant commitment data introduce uncertainty bands around absorption trajectory assumptions. Forecasts reflect documented assumptions regarding licensing streamlining continuity and energy sector restructuring pace. Regulatory revision timing, fintech compliance framework evolution, and construction cost volatility constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
United States Property Management Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
Real Estate Management Software Market
Property Management
Spain Warehousing Market
Property Management
Real Estate (Property) Management Market
Property Management
US Property Management Software Market
Property Management
Property Management Software Market
Property Management
Property Management Service Market
Property Management
South Korea Self-Storage Market
Property Management
Residential Property Management Market
Property Management
Hungary Warehousing Sector Market
Property Management
Europe Self Storage Market