
 Space Planning and Space Management Solutions Market | 2026-2036
Space Planning and Space Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Space Planning and Space Management Solutions Market Insights
Digital twin integration is reconfiguring how space planning platforms ingest real-time occupancy and environmental data for dynamic floorplan adjustments. Trimble leverages its geospatial heritage to anchor building information modeling workflows within space management suites. IBM TRIRIGA competes through enterprise asset management linkages that extend space data into broader operational technology stacks. Accruent specializes in vertical-specific compliance modules that dominate higher education and healthcare facility deployments.
Space planning and space management solutions comprise software platforms that utilize CAD engines, sensor feeds, and algorithmic allocation models to map, monitor, and modify physical space utilization across built environments. These systems process square footage parameters, occupancy thresholds, and HVAC load data to automate desk booking, room reservations, and maintenance scheduling for facility operators. Cloud-based deployment now leads the deployment model category as enterprises abandon on-premise server maintenance for elastic SaaS architectures with faster update cycles. Workspace optimization commands the solution type segment where AI-driven density algorithms help corporates reduce per-employee real estate footprints without sacrificing collaboration efficacy. Facilities management services generate recurring revenue pools as implementation vendors lock clients into multi-year maintenance and reconfiguration contracts.
OSHA workplace density guidelines in the United States, EU Green Deal building efficiency directives under ECHA frameworks, and Japan METI smart building standards collectively shape product certification requirements and procurement eligibility for space management vendors. BIS building code digitization mandates in India and China's GB standards for intelligent architecture further fragment compliance obligations across multinational deployments. Stakeholders must monitor how evolving carbon disclosure rules transform space utilization metrics from operational cost tools into mandatory ESG reporting inputs.
Market Dynamics
Hybrid work permanence is forcing corporate real estate teams to abandon static floorplans for algorithmic space allocation systems that recalibrate daily based on sensor-derived occupancy patterns.
Growth Catalysts
- OSHA workplace density guidelines:United States facility managers must deploy automated occupancy tracking to demonstrate compliance with post-pandemic square footage requirements per employee.
- IoT sensor price collapse:Bluetooth Low Energy and millimeter-wave presence detectors now cost below ten dollars per unit, enabling dense sensor grids in mid-market buildings.
- Corporate ESG disclosure mandates:EU CSRD rules require granular carbon intensity metrics per square meter, pulling space utilization data into mandatory sustainability reporting workflows.
Market Restraints
- Cloud infrastructure concentration:Three hyperscale providers dominate secure facility data hosting, creating single-point-of-failure exposure for multi-tenant building operators.
- CAD file format lock-in:Proprietary Autodesk and Bentley geometry engines fragment interoperability, forcing costly translation layers for mixed-vendor deployments.
- Legacy BMS integration debt:Twenty-year-old BACnet and Modbus protocols in existing buildings require expensive protocol bridges to feed real-time data into modern space management platforms.
Strategic Opportunities
- India BIS building code digitization:Mandatory digital submission of floorplans for construction permits creates first-mover advantage for SaaS vendors embedding compliance validation.
- Digital twin convergence with BIM:Real-time sensor feeds merging with static building models enable predictive maintenance scheduling that reduces facility downtime.
- Healthcare vertical specialization:Operating room turnover optimization and patient flow management represent underserved use cases with premium pricing tolerance.
Industry Challenges
- Facilities data science talent scarcity:Hybrid skill sets combining HVAC engineering, SQL analytics, and change management command salary premiums that strain vendor margins.
- Multi-year implementation cycles:Enterprise deployments average eighteen months from contract to full sensor network activation, compressing recognized revenue recognition windows.
- Sensor calibration drift:Thermal and CO2-based occupancy counters require quarterly recalibration that most service contracts underestimate, degrading algorithm accuracy over time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Planning and Space Management Solutions Market |
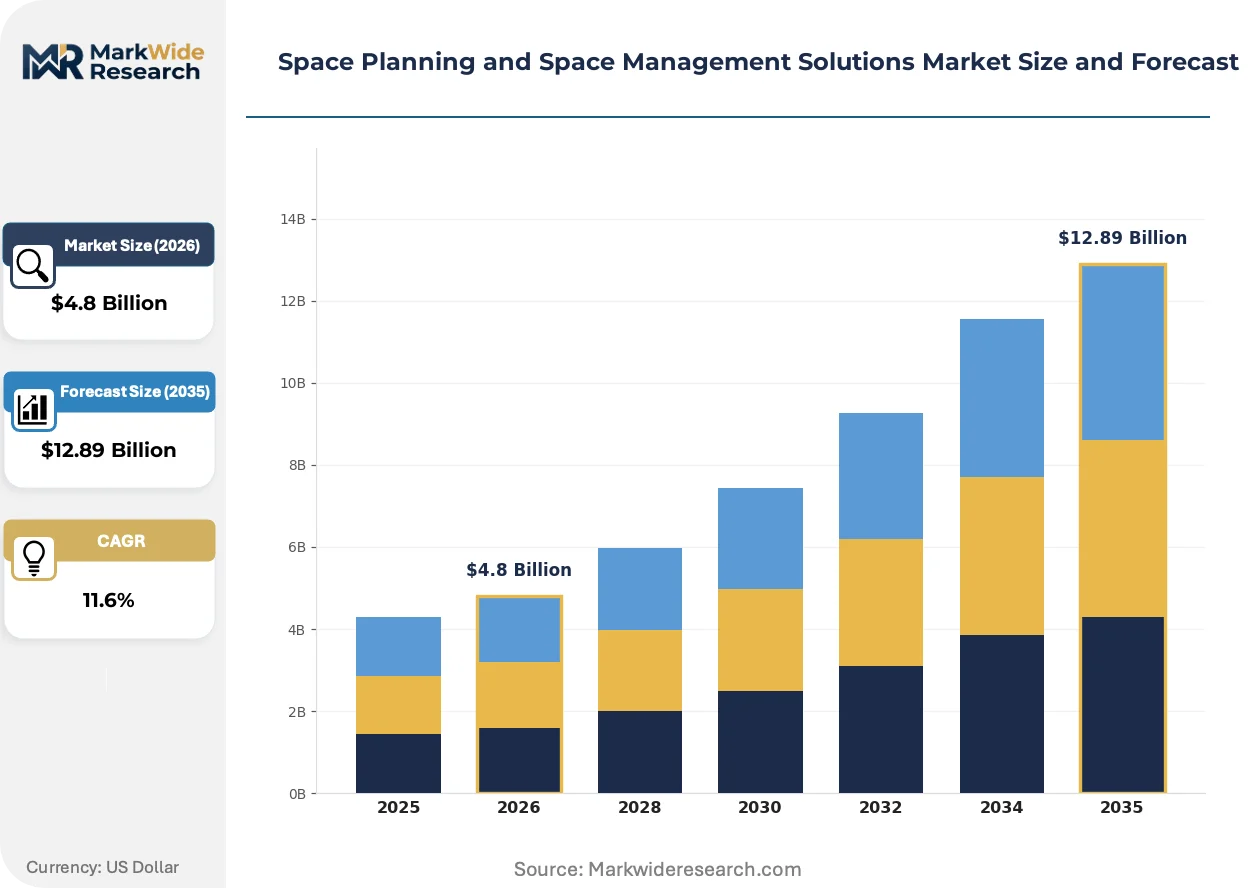
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Workspace Optimization, Facilities Management, Computer-Aided Design, Space Analytics End User: Corporates, Educational Institutions, Healthcare Providers, Government Entities Deployment Model: On-Premise, Cloud-Based, Hybrid, Mobile Application Service Type: Consulting, Implementation, Maintenance, Training |
| Companies Covered | Accruent, Symphony RetailAI, Trimble, JDA Software Group, AssetWorks, Archibus, IBM TRIRIGA, iOFFICE, Planon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Planning and Space Management Solutions Market Trends and Innovations
Real-time environmental sensing and generative layout algorithms are collapsing the traditional design-occupy-feedback loop from months to hours, compressing how quickly buildings adapt to organizational change.
Computer vision occupancy detection is rendering obsolete manual badge-swipe entry systems and scheduled room booking protocols. Fortune 500 headquarters in New York and London now deploy anonymous thermal imaging to identify actual versus claimed space usage, feeding machine learning models that automatically release underutilized conference rooms. This sensor-to-algorithm pipeline is rendering obsolete the category of traditional facilities management software that relied on quarterly manual space audits.
EU Green Deal building efficiency directives under ECHA frameworks now mandate operational energy disclosure for commercial structures exceeding specific thresholds. Property owners in Germany and France must install continuous monitoring infrastructure to document HVAC load per occupied square meter, with penalties for non-compliance escalating annually. This regulatory pressure is accelerating replacement of passive building management systems with active optimization platforms in European Class A office stock.
Enterprise buyers now demand consumption-based pricing tied to measurable square footage reductions rather than perpetual seat licenses. Procurement teams at technology and professional services firms negotiate contracts where vendor fees scale with documented real estate cost avoidance, shifting risk onto solution providers. This outcome-linked commercial structure is most advanced in United States coastal markets where corporate real estate teams face explicit headcount-per-desk reduction targets from CFO mandates.
Space Planning and Space Management Solutions Market Segmentation
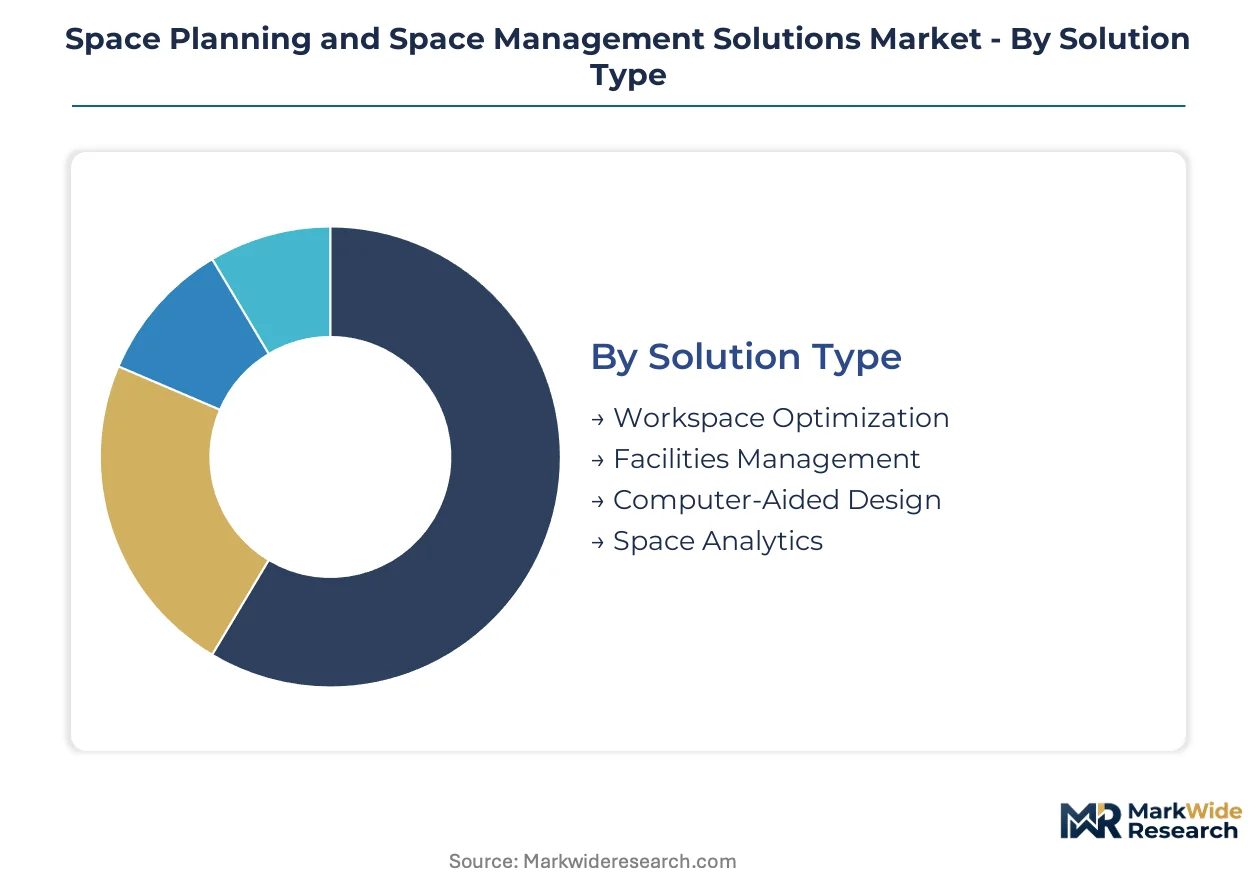
Segmentation reveals how vendor resource allocation diverges across solution architectures and client engagement models. Service intensity, deployment complexity, and compliance exposure vary dramatically by category, reshaping margin structures and partnership requirements.
Solution Type:
After-sales service intensity peaks with solutions requiring continuous sensor recalibration and algorithm retraining, locking vendors into multi-year support contracts.
- Workspace Optimization:AI-driven density algorithms automate desk booking and dynamic zone allocation based on real-time occupancy feeds. Demand concentrates among United States technology firms reducing per-employee real estate footprints under CFO-mandated targets.
- Facilities Management:Integrated maintenance scheduling, vendor dispatch, and asset lifecycle tracking modules dominate higher education and healthcare deployments where compliance documentation requirements are stringent.
- Computer-Aided Design:Static floorplan creation tools with BIM interoperability anchor initial design phases but generate lower recurring revenue than sensor-integrated alternatives.
- Space Analytics:Dashboard and reporting layers aggregate cross-facility utilization metrics for portfolio-level decision-making by corporate real estate teams.
By volume, Facilities Management leads. By growth pace, Workspace Optimization is ahead.
End User:
Cost tier stratification separates premium compliance-driven buyers from price-sensitive mid-market adopters with limited IT integration budgets.
- Corporates:Hybrid work permanence forces algorithmic space allocation replacing static floorplans, with Fortune 500 headquarters deploying anonymous thermal imaging for actual versus claimed usage verification.
- Educational Institutions:Campus-wide classroom utilization optimization and semester-schedule synchronization drive demand, with Accruent's vertical-specific compliance modules dominating this vertical.
- Healthcare Providers:Operating room turnover optimization and patient flow management represent underserved use cases with premium pricing tolerance and strict Joint Commission documentation requirements.
- Government Entities:Federal and municipal facility managers prioritize cybersecurity-hardened on-premise deployments with lengthy procurement cycles but stable multi-year contract structures.
Corporates generate the highest absolute revenue. Healthcare Providers show the steepest expansion trajectory.
Deployment Model:
Application criticality determines architecture choice, with real-time sensor feeds favoring cloud elasticity while classified environments mandate air-gapped infrastructure.
- Cloud-Based:Elastic SaaS architectures with faster update cycles now lead enterprise adoption as organizations abandon on-premise server maintenance burdens.
- On-Premise:Air-gapped installations persist in defense contractors and financial services where data sovereignty requirements override operational convenience.
- Hybrid:Edge-computed sensor preprocessing with cloud analytics aggregation balances latency-sensitive occupancy detection against centralized reporting needs.
- Mobile Application:Desk booking and room reservation interfaces for end-users, typically bundled as client-facing layers atop core platform deployments rather than standalone purchases.
Cloud-Based deployments dominate new contract value. Hybrid architectures are climbing fastest as latency-sensitive use cases multiply.
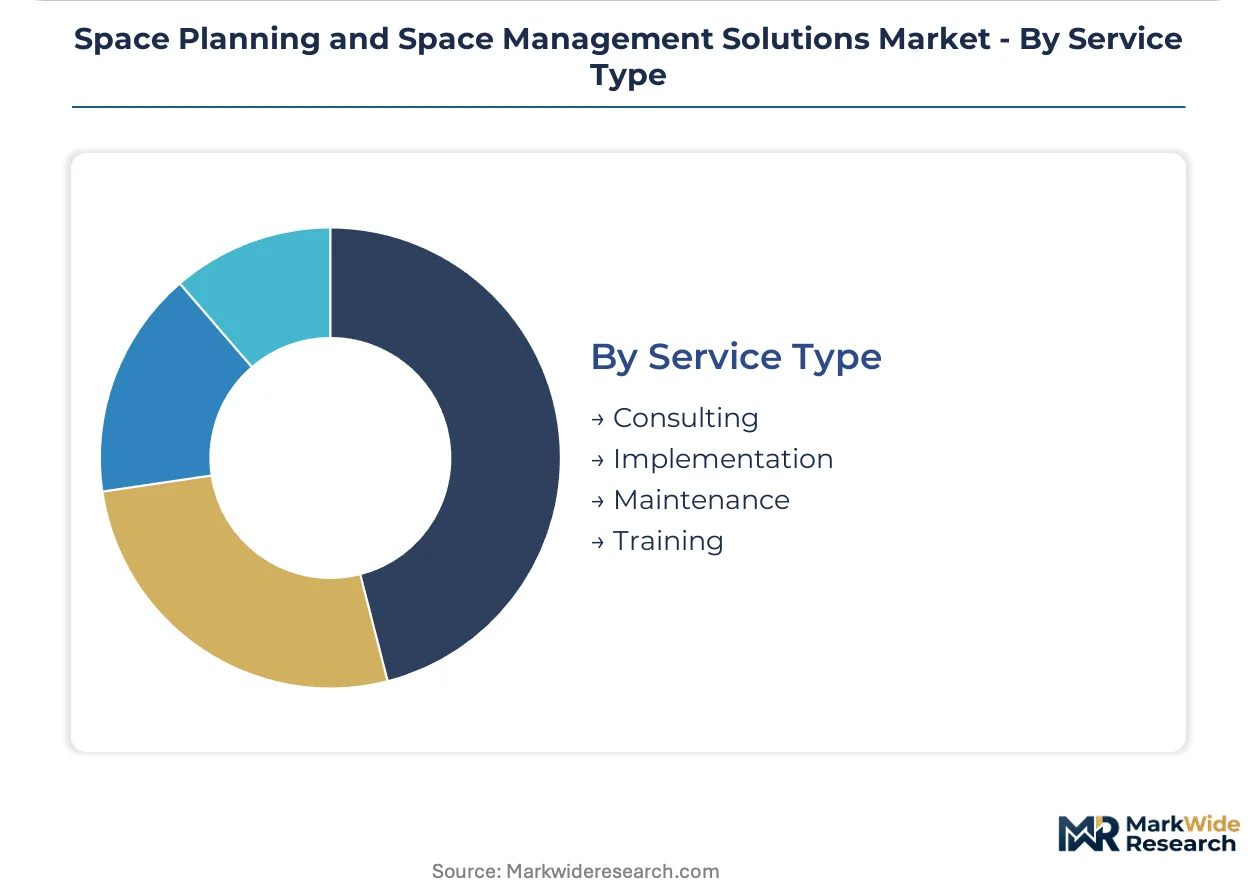
Service Type:
Customer type segmentation separates self-sufficient enterprise IT shops from outsourced-facility operators requiring full vendor-managed deployment.
- Implementation:Sensor network installation, CAD data migration, and BMS protocol bridging average eighteen months from contract to full activation, compressing revenue recognition windows.
- Maintenance:Quarterly sensor recalibration for thermal and CO2-based occupancy counters, plus algorithm tuning, generates the most predictable recurring revenue streams.
- Consulting:Change management and space utilization strategy advisory preceding technical deployment, often delivered by boutique firms partnering with platform vendors.
- Training:End-user adoption programs and facilities staff certification on dashboard interpretation, typically front-loaded within implementation contracts.
Maintenance commands the largest service revenue pool. Implementation services are expanding most quickly as sensor network complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate real estate teams in the United States, Germany, and Japan drive the majority of procurement volume for space planning and space management solutions, with facility modernization budgets concentrated in metropolitan office markets undergoing hybrid work transitions.
United States
Fortune 500 headquarters in New York and Chicago deploy anonymous thermal imaging for actual versus claimed space usage verification. OSHA workplace density guidelines mandate automated occupancy tracking for post-pandemic square footage compliance. Corporate real estate teams in San Francisco and Boston negotiate outcome-linked contracts where vendor fees scale with documented real estate cost avoidance.
Germany
Property owners in Frankfurt and Munich install continuous monitoring infrastructure to document HVAC load per occupied square meter under EU Green Deal building efficiency directives. ECHA frameworks mandate operational energy disclosure for commercial structures exceeding specific thresholds. Class A office stock in Berlin accelerates replacement of passive building management systems with active optimization platforms.
Japan
METI smart building standards shape product certification requirements for space management vendors targeting commercial facility operators. Corporate headquarters in Tokyo and Osaka integrate IoT sensor grids with algorithmic space allocation systems that recalibrate daily based on occupancy patterns. Facility managers in Nagoya prioritize cybersecurity-hardened deployments for manufacturing-integrated office complexes.
India
BIS building code digitization mandates digital submission of floorplans for construction permits, creating first-mover advantage for SaaS vendors embedding compliance validation. IT campuses in Bengaluru and Hyderabad deploy cloud-based workspace optimization tools to manage fluctuating hybrid work attendance. Facility operators in Mumbai and Delhi-NCR abandon on-premise server maintenance for elastic SaaS architectures with faster update cycles.
United Kingdom
Corporate real estate teams in London's Canary Wharf and City districts demand consumption-based pricing tied to measurable square footage reductions rather than perpetual seat licenses. EU CSRD rules pull space utilization data into mandatory sustainability reporting workflows for multinational headquarters. Professional services firms in Manchester and Birmingham negotiate contracts with explicit headcount-per-desk reduction targets from CFO mandates.
Space Planning and Space Management Solutions Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment models, with enterprise software vendors leveraging existing customer relationships against vertical-focused challengers. The vendor base organizes into three tiers: geospatial heritage platforms anchoring building information modeling workflows, enterprise asset management suites extending space data into operational technology stacks, and vertical-specific compliance modules dominating higher education and healthcare deployments. Strategic moves concentrate on cloud migration partnerships and sensor network integration capabilities.
Within the enterprise asset management tier, IBM TRIRIGA and Accruent occupy positions that exemplify divergent specialization strategies. IBM TRIRIGA represents the breadth-oriented archetype linking space data into broader operational technology infrastructure. Accruent anchors the vertical-specific vector with compliance module concentration in higher education and healthcare facility deployments. Trimble sits within the geospatial heritage category, leveraging positioning technology roots to anchor building information modeling workflows within integrated space management suites.
| Leading Market Players |
|---|
| Accruent |
| Symphony RetailAI |
| Trimble |
| JDA Software Group |
| AssetWorks |
| Archibus |
| IBM TRIRIGA |
| iOFFICE |
| Planon |
| Others |
Pricing and Supply Chain Analysis
China's dominance in Bluetooth Low Energy and millimeter-wave sensor manufacturing concentrates component sourcing for space management platforms, pushing margin pools toward downstream algorithm developers and vertical-specific compliance module vendors rather than hardware suppliers.
Pricing Analysis
Cost-plus contracts with quarterly sensor price indexation dominate mid-market deployments, anchoring vendor fees to component input volatility. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade BIM-integrated suites from lightweight SaaS desk-booking tools. Cost compression in the economy tier intensifies as open-source occupancy detection algorithms commoditize basic functionality. Small and mid-sized facility operators exhibit acute price sensitivity, while healthcare systems and Fortune 500 corporates tolerate premium tiers for Joint Commission documentation and outcome-linked cost avoidance guarantees.
Supply Chain Analysis
Export-control restrictions on advanced thermal imaging arrays and edge AI processors limit flows from United States and Japanese suppliers to Chinese system integrators, fragmenting hardware procurement channels. Component sourcing concentrates in China, Taiwan, and South Korea for sensor fabrication, with Germany and Japan anchoring precision HVAC integration hardware. Supply chains draw from silicon wafers, rare-earth magnet assemblies, and proprietary CAD geometry engines. Single-source vulnerability around NVIDIA edge computing modules creates procurement bottlenecks for real-time digital twin deployments. Distribution runs through direct enterprise sales teams for large deployments and regional systems integrators for mid-market implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Space planning and space management solutions represent a high-growth disruption as EU CSRD carbon disclosure mandates transform utilization metrics from operational cost tools into mandatory ESG reporting inputs, forcing procurement acceleration across multinational corporates.
For Market Incumbents: Harden cloud infrastructure partnerships against hyperscale concentration risk by diversifying across AWS, Azure, and Google Cloud with contractual failover provisions. Consolidate sensor calibration service capabilities in-house to capture recurring maintenance revenue streams that emerging competitors underestimate. Defensive positioning must counter open-source algorithm challengers eroding pricing power in the workspace optimization segment. For New Entrants and Emerging Players: Establish a beachhead in healthcare operating room turnover optimization, an underserved use case with premium pricing tolerance and strict documentation requirements that incumbent EAM suites address poorly. Target Indian SaaS compliance validation as BIS building code digitization mandates create first-mover structural advantage. A channel partnership strategy with established facilities management service providers accelerates enterprise access without eighteen-month direct sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward vertical-specific compliance module developers with dominant higher education and healthcare footprints, as regulatory complexity deepens moats against horizontal platform competitors. Long-term viability hinges on algorithmic differentiation rather than sensor hardware exposure. Watch for inflection when outcome-linked pricing contracts exceed fifty percent of new bookings, signaling vendor confidence in measurable ROI delivery and buyer willingness to shift implementation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Network Integration Partnership | IBM TRIRIGA's enterprise asset management linkages extend space data into operational technology stacks for unified facility command. |
| Vertical Compliance Module Acquisition | Accruent's higher education and healthcare specialization demonstrates how regulatory documentation requirements create pricing power. |
| Digital Twin Platform Launch | Trimble leverages geospatial heritage to anchor BIM workflows within real-time sensor-fed space management suites. |
| Cloud Migration Service Expansion | Elastic SaaS architectures with faster update cycles now lead enterprise adoption as organizations abandon on-premise burdens. |
| Outcome-Linked Pricing Restructure | Corporate real estate teams in United States coastal markets negotiate contracts scaling vendor fees with documented square footage reductions. |
Research Methodology
A spread of perspectives from corporate real estate executives, facilities management directors, IoT sensor procurement leads, and cloud platform integration specialists converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and BIS building code digitization mandates. Bottom-up sensor shipment estimates and top-down enterprise software spending allocations were triangulated to anchor market sizing.
Demand-supply balance framing shaped the analytical approach across the analysis window, with segmentation modeling across deployment architecture, solution type, vertical industry, and regional regulatory cluster. CAGRs were derived from installed base growth curves and replacement cycle dynamics rather than simple extrapolation. Forecast inputs incorporated IoT sensor price collapse trajectories and EU Green Deal compliance timeline acceleration.
Sensitivities concentrate around CSRD enforcement consistency and hybrid work permanence durability as revision triggers. Forecasts reflect documented assumptions about sensor network activation timelines and algorithm accuracy degradation curves. Material shifts in OSHA workplace density guideline stringency or METI smart building standard adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
Europe Self Storage Market
Property Management
Hungary Warehousing Sector Market
Property Management
United States Property Management Market
Property Management
US Property Management Software Market
Property Management
Real Estate Management Software Market
Property Management
Qatar Flexible Office Space Market
Property Management
South Korea Self-Storage Market
Property Management
Property Management Software Market
Property Management
Spain Warehousing Market
Property Management
Property Management Service Market
Property Management
Real Estate (Property) Management Market
Property Management
Residential Property Management Market