
 United States Property Management Market | 2026-2036
United States Property Management Market Size, Share, and Industry Trends Forecast 2026-2036
United States Property Management Market Analysis
Third-party property management agreements and fee-based service models are narrowing the capital barrier for mid-size investors to access institutional-grade operations. Greystar Real Estate Partners leverages its vertically integrated platform across development, investment, and management functions. CBRE Group, Inc. sustains competitive density through its global brokerage network feeding captive management mandates. Lincoln Property Company anchors regional market presence with concentrated Sun Belt exposure.
Property management encompasses the operational oversight of real estate assets, spanning tenant acquisition, lease administration, rent collection, maintenance coordination, and financial reporting through standardized accounting protocols. The discipline serves to preserve asset value, optimize income streams, and ensure regulatory compliance across income-producing real estate. Residential Management commands the largest service-type revenue pool given the scale of U.S. rental housing stock, while Property Management Software within the technology dimension captures the fastest expansion as operators replace legacy systems. Multi-Family Properties represent the most structurally institutionalized property type, with margin pools concentrating where operators bundle Asset Management with on-site services.
The Department of Housing and Urban Development enforces fair housing standards that shape tenant screening protocols and accessibility requirements across federally assisted properties. The Consumer Financial Protection Bureau governs fee disclosures and debt collection practices affecting property management billing workflows. State-level landlord-tenant laws, including California's rent control frameworks and Texas's comparatively permissive eviction procedures, create jurisdictional complexity that favors operators with multi-state compliance infrastructure. Stakeholders must monitor how municipal source-of-income discrimination ordinances and building electrification mandates reshape operating cost structures and technology procurement priorities.
Market Dynamics
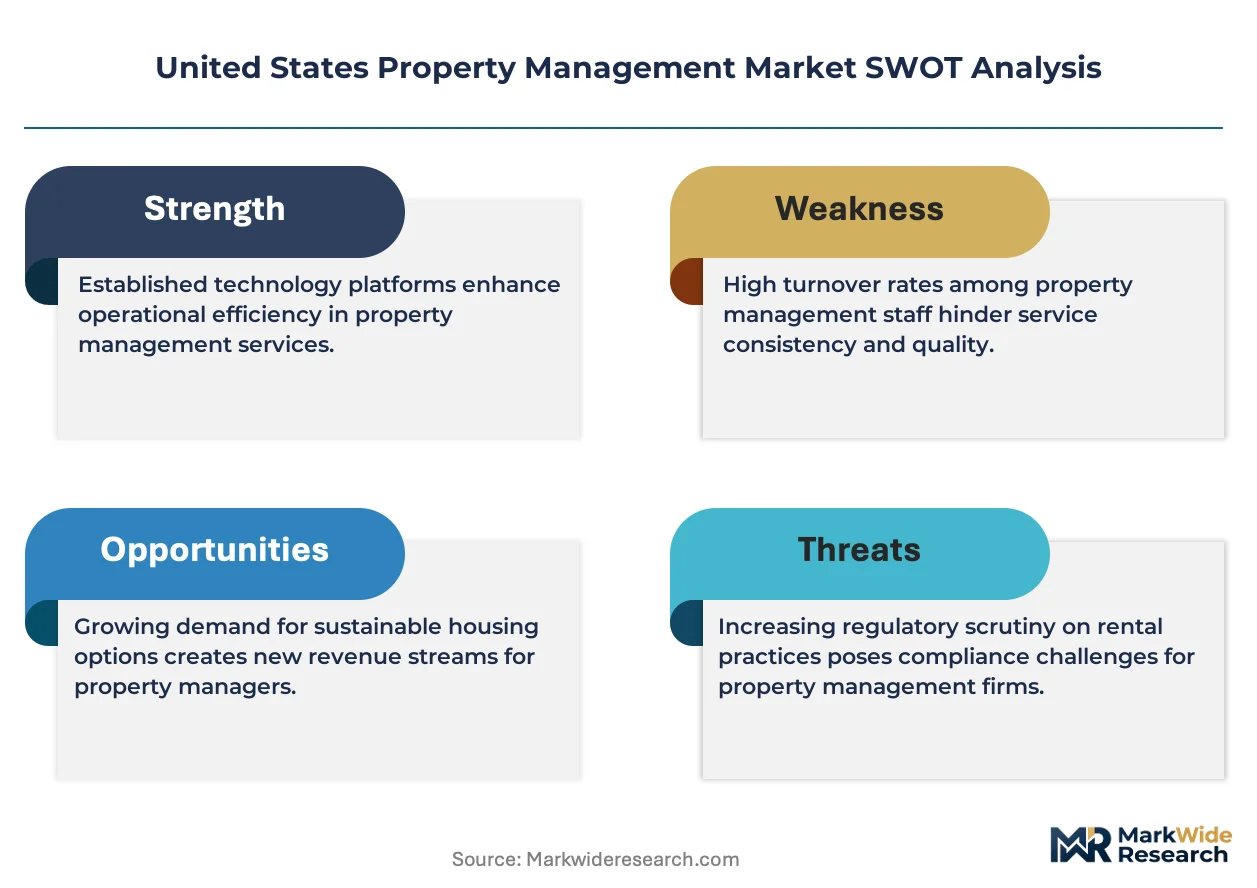
The institutionalization of U.S. rental housing is compressing margins for fragmented operators while elevating compliance burdens from HUD's intensified fair housing enforcement. Capital deployment into build-to-rent single-family communities is reshaping competitive positioning toward vertically integrated platforms capable of spanning development through operations.
Growth Catalysts
- HUD Fair Housing Enforcement:The Department of Housing and Urban Development's expanded accessibility audits are mandating integrated compliance software, pulling property managers toward centralized tenant screening and documentation platforms.
- Build-to-Rent Single-Family:Institutional capital flows into scattered-site single-family rentals are creating demand for technology stacks that unify dispersed asset oversight under common operating protocols.
- Sun Belt Demographic Migration:Population inflows into Dallas, Phoenix, and Atlanta are deepening rental housing demand and concentrating third-party management contract opportunities in these metros.
Market Restraints
- Labor Cost Escalation:On-site maintenance technician wages in gateway metros have outpaced rent growth, compressing net operating income for fee-based operators.
- Software Vendor Concentration:Dominance of a handful of property management software providers limits pricing leverage for mid-size management firms negotiating enterprise licenses.
- Eviction Moratorium Legacy:Extended state-level tenant protections in jurisdictions like California and New York continue to elongate bad-debt resolution timelines and elevate working capital requirements.
Strategic Opportunities
- Secondary Sun Belt Markets:Nashville, Charlotte, and Austin present underpenetrated expansion terrain where institutional ownership density remains below primary-tier metros.
- Electrification Mandates:Municipal building decarbonization ordinances in California and Washington are creating retrofit project pipelines that property managers can capture through affiliated construction services.
- AI-Enabled Predictive Maintenance:Convergence of IoT sensor networks with machine learning diagnostics offers white-space positioning for operators able to bundle proactive maintenance into management fee structures.
Industry Challenges
- Certified Property Manager Scarcity:The Institute of Real Estate Management's CPM designation pipeline has failed to keep pace with portfolio growth, constraining operator expansion velocity.
- Legacy System Integration:Migration from fragmented point solutions to unified platforms demands substantial capex and operational disruption, particularly for mid-market operators with heterogeneous technology estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Property Management Market |
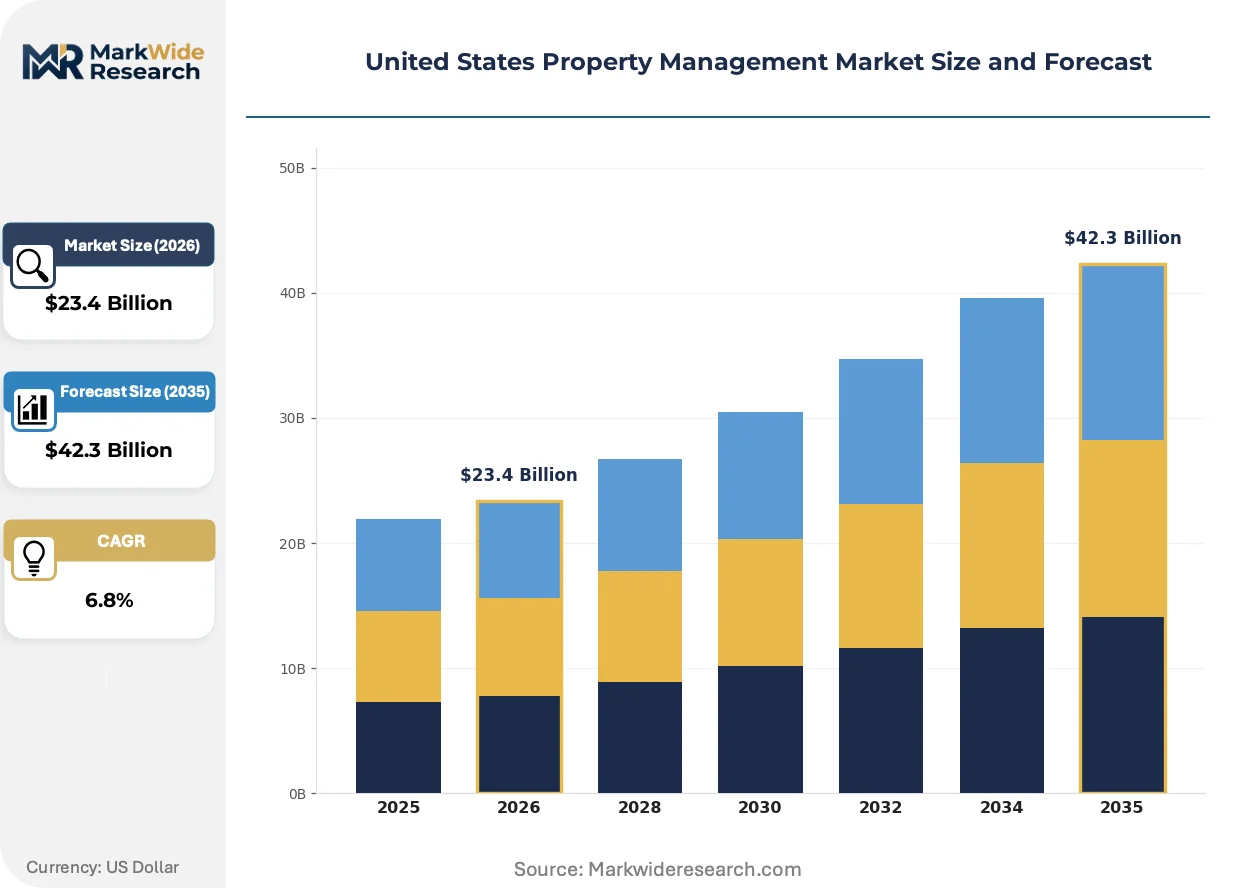
| Market Size in 2026 | $23.4 Billion |
| Market Size in 2035 | $42.3 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Management, Commercial Management, Asset Management, Maintenance Services Property Type: Single-Family Homes, Multi-Family Properties, Office Buildings, Retail Spaces Client Type: Individual Owners, Real Estate Investors, Corporations, Nonprofits Technology: Property Management Software, Cloud Solutions, Mobile Applications, Tenant Portals |
| Companies Covered | Greystar Real Estate Partners, CBRE Group, Inc., Willow Bridge Property Company, Cushman & Wakefield, RPM Living, Asset Living, FPI Management, Lincoln Property Company, Prologis, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Property Management Market Emerging Trajectories
Property management technology is pivoting from back-office automation toward resident-facing experience platforms that embed payments, maintenance requests, and community engagement into unified mobile interfaces. This shift is compressing the competitive relevance of operators unable to deliver seamless digital tenant journeys.
Cloud-native property management platforms are rendering obsolete the server-based legacy systems that dominated multifamily operations through the 2010s. Mid-size operators in Texas and Florida are adopting these platforms at accelerating pace, consolidating previously siloed accounting, leasing, and maintenance functions into single databases that enable real-time portfolio analytics and compress administrative headcount per unit.
The Department of Housing and Urban Development's 2024 guidance on algorithmic tenant screening is forcing disclosure of automated decision factors and human override protocols. Property managers utilizing AI-driven screening tools must now document adverse action reasoning with greater granularity, elevating compliance infrastructure costs most acutely for operators of federally subsidized housing across the Southeast and Southwest.
Institutional investors are consolidating vendor relationships and demanding unbundled fee transparency that separates base management fees from ancillary service markups. This procurement compression is displacing the bundled service models that historically obscured true cost structures, pressuring operators in Atlanta and Dallas to restructure pricing and expose margins to direct competitive comparison.
United States Property Management Market Segmentation
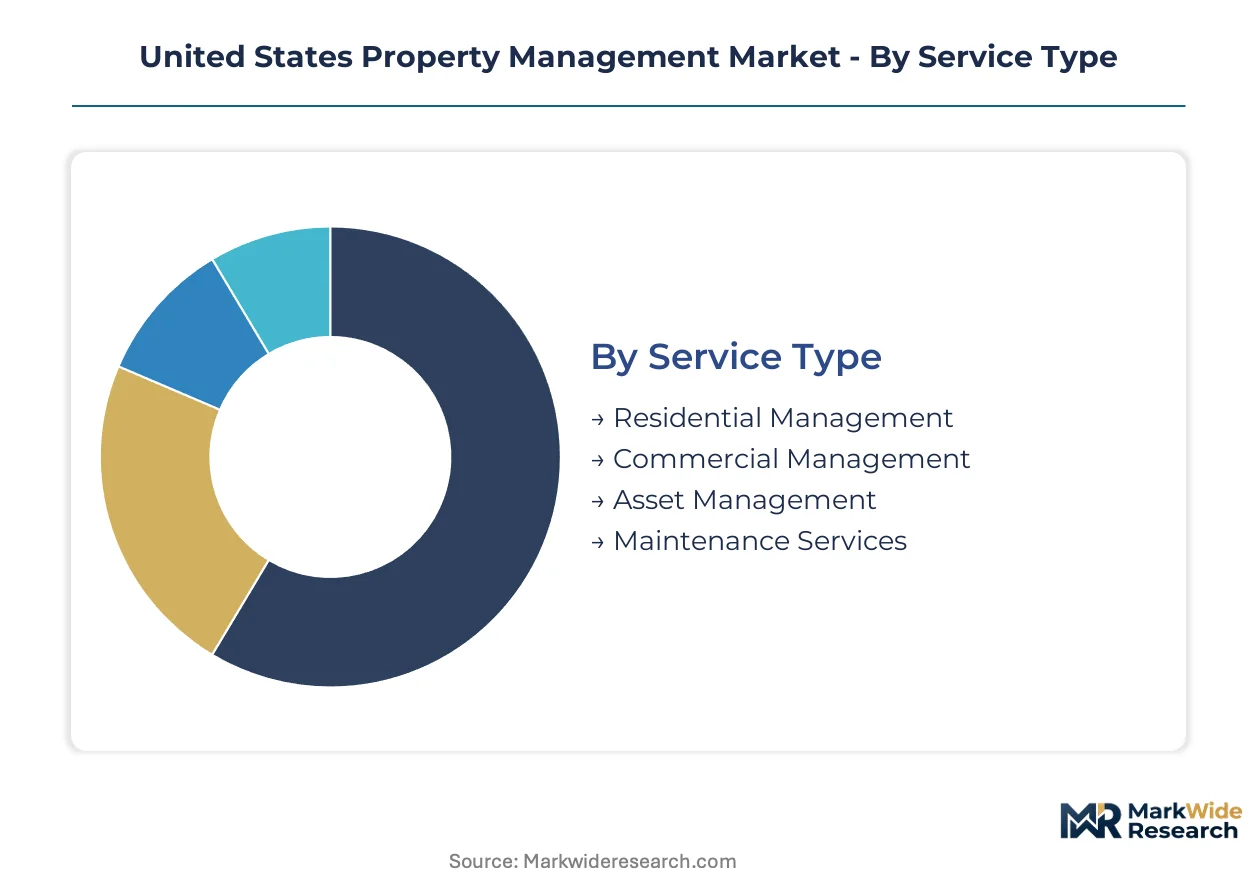
Property management operators structure service portfolios around distinct asset classes and client sophistication levels. Segmentation reveals where margin pools concentrate and which technology investments yield competitive differentiation across operational models.
Service Type:
After-sales service intensity varies dramatically across service categories, with ongoing tenant relations demanding sustained operational commitment versus transactional asset advisory.
- Residential Management:Encompasses tenant acquisition, lease administration, rent collection, and maintenance coordination for rental housing portfolios. Demand concentrates in Sun Belt metros including Dallas, Phoenix, and Atlanta where institutional investor ownership has deepened and third-party management contracts are expanding.
- Commercial Management:Covers office, retail, and industrial property operations with specialized lease structures and capital improvement planning. Property managers serving office buildings in gateway metros face compressed fee structures as hybrid work patterns reduce tenant service intensity requirements.
- Asset Management:Strategic oversight of property performance, capital deployment, and investor reporting distinct from day-to-day operations. Real estate investment trusts and pension fund advisors drive demand for unbundled fee transparency.
- Maintenance Services:Coordinates vendor networks, preventive programs, and emergency response for physical asset preservation. Labor cost escalation in gateway metros has outpaced rent growth, squeezing net operating income for fee-based operators.
By volume, Residential Management leads. By growth pace, Asset Management is climbing the fastest as institutional capital demands strategic advisory layers.
Property Type:
Cost tier differentiation separates premium institutional-grade assets from fragmented ownership structures with diverging technology procurement budgets.
- Multi-Family Properties:Apartment communities with centralized management infrastructure and standardized operating protocols. Institutional ownership density in Dallas, Phoenix, and Atlanta creates concentrated demand for integrated platforms bundling on-site services with financial reporting.
- Single-Family Homes:Scattered-site rentals requiring distributed oversight and technology stacks capable of unifying dispersed assets. Build-to-rent community development in suburban Sun Belt markets is reshaping competitive positioning toward vertically integrated operators.
- Office Buildings:Commercial workspace with complex tenant improvement obligations and escalating amenity expectations. Hybrid work patterns have elongated lease-up timelines and elevated capital reserve requirements for repositioning obsolete stock.
- Retail Spaces:Shopping centers and street-front properties with percentage rent structures and co-tenancy clause complexity. Experiential retail concentration in high-foot-traffic submarkets favors operators with specialized lease administration capabilities.
By revenue concentration, Multi-Family Properties dominates. By expansion velocity, Single-Family Homes is gaining share fastest as institutional capital flows into build-to-rent development.
Client Type:
Customer sophistication determines procurement patterns, with institutional investors demanding unbundled fee transparency that fragmented owners rarely negotiate.
- Real Estate Investors:Institutional limited partners, real estate investment trusts, and private equity funds with portfolio-scale management mandates. These clients drive standardization requirements and centralized reporting protocols across multi-state holdings.
- Individual Owners:Mom-and-pop landlords with limited-unit portfolios and price-sensitive service preferences. Third-party management agreements are narrowing capital barriers for mid-size investors to access institutional-grade operations.
- Corporations:Occupiers seeking facility management for owned or long-leased corporate real estate. Enterprise clients prioritize integrated workplace experience platforms over traditional property oversight.
- Nonprofits:Affordable housing providers and community development organizations with specialized compliance obligations. HUD fair housing enforcement elevates documentation requirements for federally assisted properties.
By contract value, Real Estate Investors leads. By growth pace, Individual Owners is expanding most quickly as fractional ownership platforms democratize rental housing investment.
Technology:
Maturity gradients separate legacy server-based systems from cloud-native platforms with diverging integration costs and capability roadmaps.
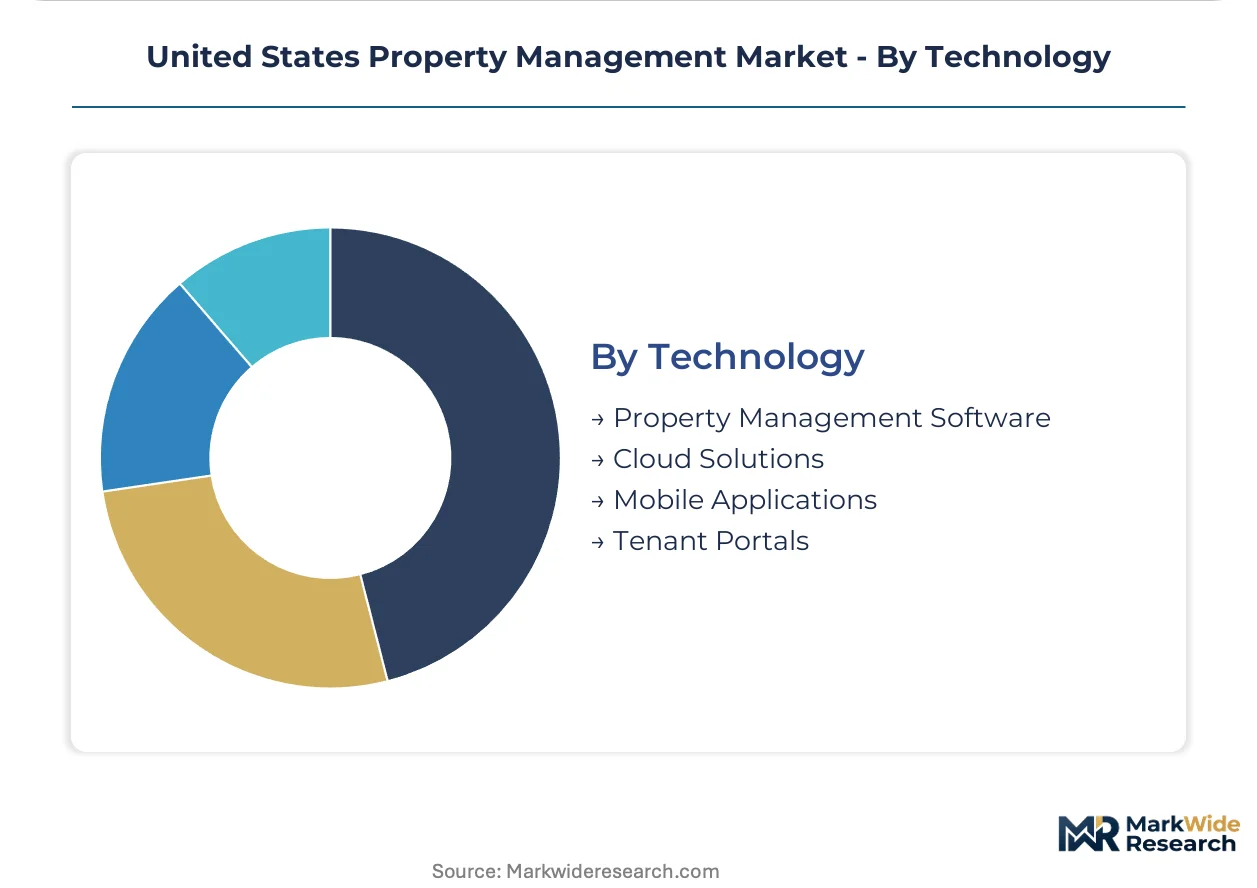
- Property Management Software:Core platforms unifying accounting, leasing, and maintenance functions into single databases. Mid-size operators in Texas and Florida are adopting cloud-native solutions at accelerating pace to compress administrative headcount per unit.
- Cloud Solutions:Scalable infrastructure eliminating on-premise server maintenance and enabling real-time portfolio analytics. Vendor concentration among a handful of providers limits pricing leverage for mid-size management firms negotiating enterprise licenses.
- Mobile Applications:Resident-facing interfaces embedding payments, maintenance requests, and community engagement. The shift toward seamless digital tenant journeys is compressing competitive relevance for operators with fragmented point solutions.
- Tenant Portals:Self-service platforms for lease documents, payment history, and communication threading. HUD's algorithmic screening guidance is forcing disclosure of automated decision factors and human override protocols.
By deployment scale, Property Management Software leads. By adoption velocity, Mobile Applications shows the steepest expansion trajectory as resident experience platforms displace back-office automation priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Housing and Urban Development's evolving fair housing enforcement is elevating compliance software requirements across state jurisdictions. State-level landlord-tenant laws create divergent operating cost structures that favor operators with multi-state compliance infrastructure.
Texas
Institutional investor ownership of rental housing has deepened in Dallas and Houston, driving demand for integrated management platforms. The state's comparatively permissive eviction procedures attract capital deployment from national real estate investment trusts. Austin's build-to-rent single-family development pipeline is reshaping competitive positioning toward vertically integrated operators.
California
Rent control frameworks in Los Angeles and San Francisco compress fee structures for third-party managers while elevating compliance documentation burdens. Municipal building electrification mandates in San Diego and Oakland are creating retrofit project pipelines. The state's extended tenant protections continue to elongate bad-debt resolution timelines.
Florida
Population inflows into Miami and Tampa are deepening rental housing demand and concentrating management contract opportunities. Mid-size operators in Orlando are adopting cloud-native platforms at accelerating pace to compress administrative headcount per unit. The state's lack of rent control attracts institutional capital seeking yield stability.
Georgia
Atlanta anchors the Southeast's deepest institutional ownership density for multifamily assets. The city's third-party property management agreements are narrowing capital barriers for mid-size investors. Municipal source-of-income discrimination ordinances in Fulton County are reshaping tenant screening protocols and technology procurement priorities.
Arizona
Phoenix's Sun Belt demographic migration has concentrated build-to-rent community development and scattered-site single-family rental demand. Property managers serving federally subsidized housing across Maricopa County face elevated compliance infrastructure costs from HUD's algorithmic screening guidance. The metro's technology procurement patterns favor unified platforms over fragmented point solutions.
United States Property Management Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated platforms capable of spanning development through operations. Fragmented mid-market operators face margin compression from institutional procurement demands for unbundled fee transparency. Three archetypes dominate: global brokerage networks feeding captive management mandates, regional Sun Belt specialists with concentrated metro exposure, and technology-forward operators bundling asset management with on-site services. Competitive intensity manifests through M&A activity targeting secondary market expansion and strategic partnerships integrating construction services into management fee structures.
Among vertically integrated developers, Greystar Real Estate Partners exemplifies the platform model spanning investment, development, and management functions. CBRE Group, Inc. anchors the global brokerage-to-management conversion archetype, while Lincoln Property Company represents regional Sun Belt concentration. These operators occupy positions where institutional investor consolidation of vendor relationships demands unbundled fee transparency and standardized reporting protocols across multi-state holdings.
| Leading Market Players |
|---|
| Greystar Real Estate Partners |
| CBRE Group, Inc. |
| Willow Bridge Property Company |
| Cushman & Wakefield |
| RPM Living |
| Asset Living |
| FPI Management |
| Lincoln Property Company |
| Prologis, Inc. |
| Others |
Supply Flow & Price Mechanics
Interstate freight corridors connecting Dallas, Phoenix, and Atlanta carry elevated logistics costs that amplify supply concentration effects and widen price spreads between institutional-grade operators and fragmented competitors. These corridor dynamics compress margins for mid-size firms while rewarding vertically integrated platforms with captive vendor networks.
Pricing Analysis
Certification level creates the primary spread in management fee structures, with CPM-designated operators commanding premium positioning over non-credentialed competitors. Institutional investors negotiate unbundled fee transparency that separates base management from ancillary markups, while individual owners remain price-sensitive to bundled service packages. Pricing pressure stems from software vendor concentration that limits enterprise license leverage for mid-size firms. Large REITs exhibit least price sensitivity given portfolio-scale procurement power.
Supply Chain Analysis
Extended payment terms from software vendors to mid-size operators have become a critical working capital mechanism as eviction moratorium legacies elongate receivables cycles. Technology procurement concentrates among domestic cloud-native platform providers and specialized IoT sensor manufacturers in Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for integrated compliance modules required by HUD enforcement. Distribution runs through direct enterprise sales teams and value-added reseller networks serving regional operator clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive advantages. HUD's intensified fair housing enforcement and algorithmic screening disclosure requirements erect compliance barriers that favor established operators with multi-state infrastructure.
For Market Incumbents: Entrench market position through captive construction service integration capturing electrification mandate retrofit pipelines. Deepen CPM certification pipelines to constrain competitor expansion velocity. Threaten emerging technology-forward entrants by accelerating AI-enabled predictive maintenance bundling into standard fee structures.
For New Entrants and Emerging Players: Establish a beachhead in secondary Sun Belt markets including Nashville and Charlotte where institutional ownership density remains below primary-tier metros. Target build-to-rent single-family communities with technology stacks unifying dispersed asset oversight. Pursue white-label platform partnerships with regional developers lacking operational capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with cloud-native platform deployment and concentrated Sun Belt geographic exposure. Long-term viability hinges on regulatory compliance infrastructure depth and vendor consolidation resilience. Acquisition targets should demonstrate unbundled fee transparency capabilities and multi-state HUD audit readiness. Watch municipal source-of-income discrimination ordinance proliferation as inflection indicator for compliance technology demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies accounting, leasing, and maintenance into single databases enabling real-time portfolio analytics. |
| Certification Investment | CPM pipeline expansion addresses scarcity constraining operator expansion velocity across Sun Belt metros. |
| Geographic Expansion | Secondary market penetration in Nashville and Charlotte captures underpenetrated institutional capital deployment. |
| Strategic Partnership | Construction service affiliation captures municipal electrification mandate retrofit project pipelines. |
| Product Launch | AI-enabled predictive maintenance bundling creates white-space positioning in proactive service models. |
Methodological Framework
Desk research of HUD enforcement guidance, state landlord-tenant statutes, and municipal ordinance databases preceded structured interviews with property management executives, CPM designation holders, institutional investor asset managers, and software vendor account directors. Secondary validation drew from SEC REIT filings, Institute of Real Estate Management membership data, and commercial real estate transaction records. Bottom-up unit economics modeling triangulated against top-down market sizing across service type, property type, and technology deployment dimensions.
Assumptions held fixed include prevailing HUD enforcement intensity, Sun Belt demographic migration velocity, and cloud-native platform adoption curves among mid-size operators. Segmentation modeling spanned service type, property type, client sophistication tier, and technology maturity gradient. CAGRs derived from regression analysis of historical contract value growth and forward-looking institutional capital deployment patterns. Forecast inputs incorporated software vendor pricing trajectories and certified property manager pipeline projections.
Stress conditions across eviction timeline elongation, labor cost escalation velocity, and software vendor consolidation scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and capital market access for build-to-rent development. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
Real Estate Management Software Market
Property Management
Property Management Service Market
Property Management
Real Estate (Property) Management Market
Property Management
South Korea Self-Storage Market
Property Management
Spain Warehousing Market
Property Management
Residential Property Management Market
Property Management
Hungary Warehousing Sector Market
Property Management
Europe Self Storage Market
Property Management
Qatar Flexible Office Space Market
Property Management
US Property Management Software Market
Property Management
Property Management Software Market
Property Management
Space Planning and Space Management Solutions Market