
 Spain Warehousing Market | 2026-2036
Spain Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Warehousing Market Insights
Madrid's logistics corridor is reconfiguring Spain's distribution geography through speculative and build-to-suit warehouse development. Prologis leverages its pan-European platform to anchor premium last-mile positions across Madrid and Barcelona. Goodman Group sustains development velocity through in-house construction and design capabilities. Merlin Properties competes by converting underutilized commercial assets into modern logistics stock.
Warehousing encompasses enclosed facilities for goods storage, inventory management, and order fulfillment, typically spanning 5,000 to over 100,000 square meters with clear heights of 10-12 meters to accommodate racking systems and automated material handling. These structures serve as critical nodes in supply chains, enabling buffer stock positioning, cross-docking, and value-added services before final distribution. Distribution centers lead warehouse type demand as retailers consolidate fragmented storage into centralized fulfillment nodes. E-commerce dominates end-user growth, forcing specifications toward higher automation and faster throughput. Automated storage within storage systems captures expanding capital allocation as labor scarcity and throughput requirements intensify.
Spain's Logistics Center Law and municipal zoning frameworks shape warehouse siting, while CE marking and EU energy performance standards govern construction specifications and operational compliance. The national building code and regional environmental impact assessments further constrain greenfield development timelines. Stakeholders must monitor evolving last-mile zoning restrictions and automation investment thresholds to secure competitive positioning.
Market Dynamics
E-commerce fulfillment velocity is compressing warehouse specification cycles across Spain's logistics corridor, forcing developers to pre-position automation-ready infrastructure before tenant commitment.
Growth Catalysts
- Logistics Center Law incentives:Municipal tax abatements and accelerated permitting in designated zones are pulling speculative development ahead of signed leases in Madrid and Barcelona corridors.
- Automated storage and retrieval systems (AS/RS):Labor scarcity in Spanish logistics hubs is accelerating capital deployment toward vertical storage density and robotic picking workflows.
- Cross-border e-commerce flows:Iberian Peninsula positioning as a gateway to North African and Latin American markets is expanding bonded warehouse demand around Valencia and Algeciras port zones.
Market Restraints
- Land scarcity in prime corridors:Greenfield availability within 30 kilometers of Madrid's M-40 orbital has compressed to sub-5% of 2019 levels, inflating land basis for new entrants.
- Construction input volatility:Steel and reinforced concrete cost swings are eroding development pro forma certainty, particularly for speculative grade-A projects.
- CE marking compliance timelines:Extended certification cycles for automated material handling equipment are delaying tenant fit-out completion and revenue recognition.
Strategic Opportunities
- Secondary city cold chain penetration:Underdeveloped temperature-controlled infrastructure in Zaragoza and Bilbao corridors offers first-mover positioning for pharma and fresh grocery verticals.
- EU Green Deal alignment:Building Performance Directive mandates are creating premium rent capture for net-zero-ready warehouses with on-site solar and heat pump systems.
- Dark store conversion:Vacant big-box retail in Barcelona's periphery is being repositioned as hyperlocal fulfillment nodes, bypassing greenfield development timelines entirely.
Industry Challenges
- Automation integration complexity:Warehouse management system interoperability with legacy enterprise resource planning platforms is extending commissioning periods and inflating IT consultancy spend.
- Specialized technician scarcity:Shortage of certified maintenance engineers for automated racking and robotic systems is elevating operational risk and service contract pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Warehousing Market |
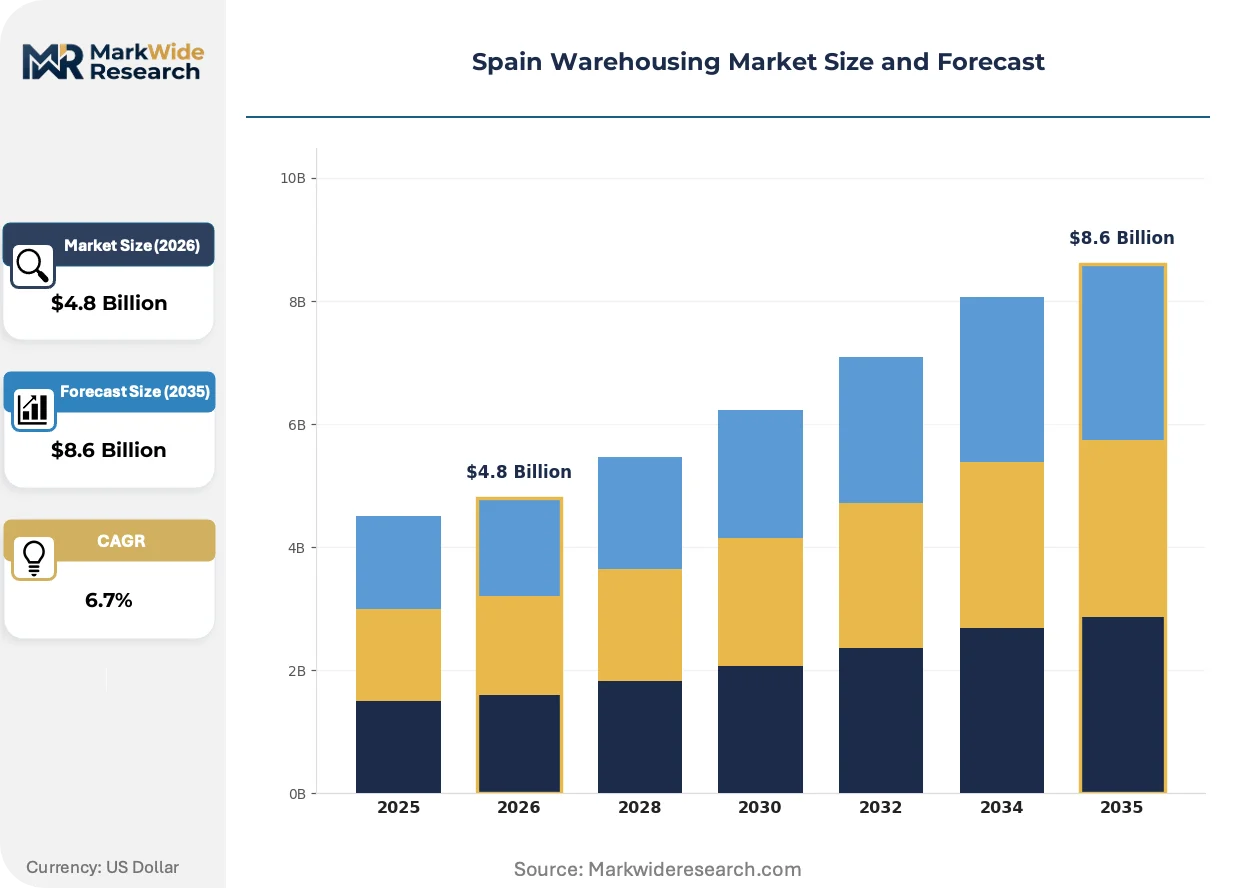
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Warehouse Type: Public Warehouse, Private Warehouse, Distribution Center, Automated Warehouse End User: Retail, E-commerce, Manufacturing, Food & Beverage Storage System: Racking System, Automated Storage, Pallet Storage, Bulk Storage Technology: Warehouse Management System, Robotics, IoT Solutions, RFID |
| Companies Covered | Prologis, Segro, Goodman Group, Merlin Properties, Logicor, Panattoni, VGP, CTP Invest, DHL Supply Chain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Warehousing Market Trends and Innovations
Physical infrastructure and digital control layers are fusing into unified operational systems, compressing the traditional separation between building shell and tenant technology stack.
Autonomous mobile robots (AMRs) are hybridizing warehouse labor models by enabling goods-to-person workflows without fixed infrastructure commitment. Mid-size 3PL operators in Valencia and Seville corridors are piloting AMR fleets on short-term rental terms. This flexibility is compressing automation adoption timelines from multi-year capex cycles to operational expenditure scaling.
Spain's transposition of the EU Energy Performance of Buildings Directive is mandating nearly-zero energy standards for new logistics stock exceeding 5,000 square meters. Developers in the Madrid-Barcelona axis are pre-installing photovoltaic arrays and battery storage to secure occupancy certificates. Premium rent spreads for BREEAM Excellent-rated facilities are widening against standard stock.
Same-day delivery promises from grocery and fashion platforms are forcing inventory positioning into 15-minute drive-time catchments from dense population centers. Dark store operators in Barcelona's Sant Andreu and Madrid's Usera districts are securing short-term industrial leases with break clauses. This geographic demand rotation is fragmenting traditional hub-and-spoke distribution logic into cellular fulfillment networks.
Spain Warehousing Market Segmentation
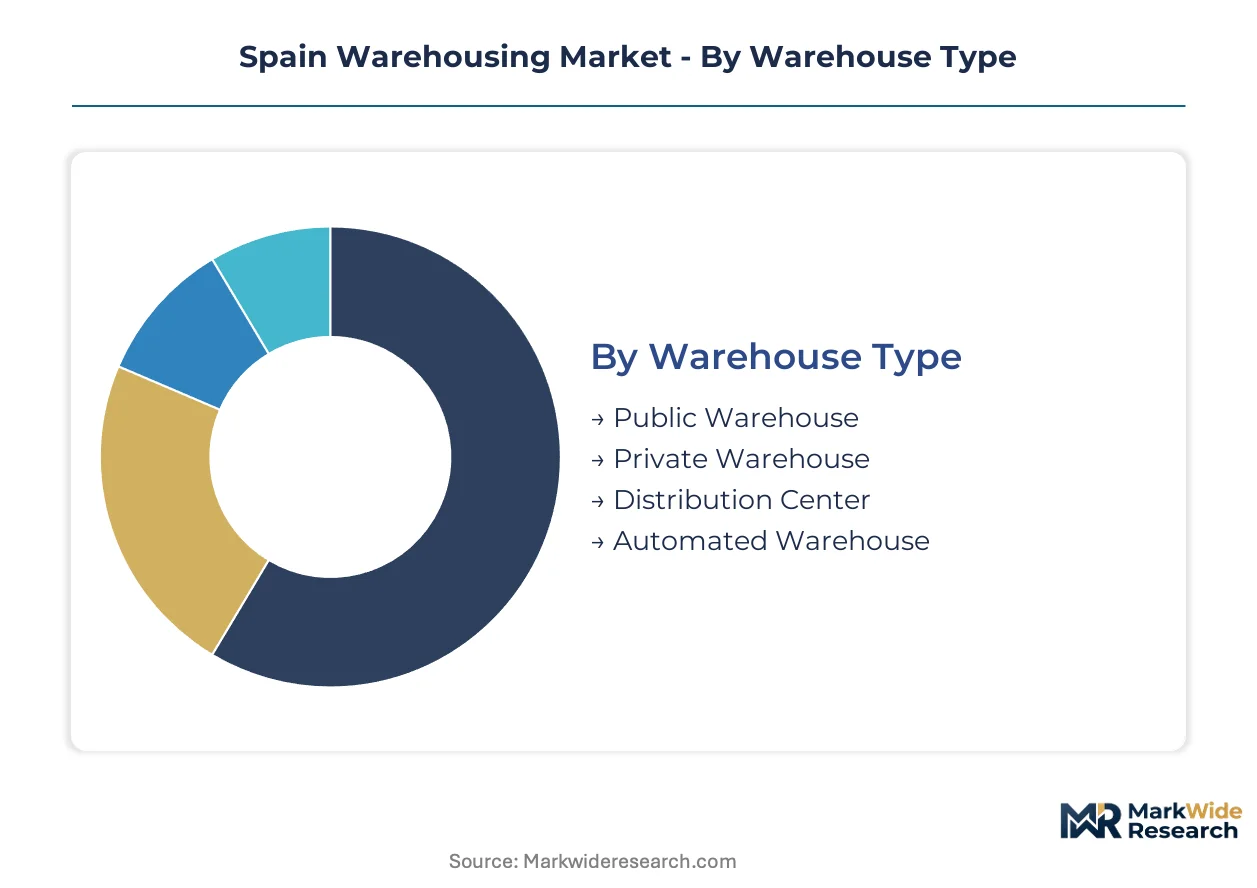
Segmentation in Spain's warehousing market reveals how capital allocation and operational requirements diverge across tenant profiles. Specification cycles, automation intensity, and lease structures vary substantially by warehouse type and end-use vertical.
Warehouse Type:
After-sales service intensity escalates from public multi-tenant facilities through automated single-user warehouses, with distribution centers commanding the highest technical support embedded in lease structures.
- Distribution Center:Centralized nodes consolidating fragmented inventory into fulfillment hubs with 10-12 meter clear heights for dense racking. Demand concentrates around Madrid-Barcelona corridor zones where E-commerce fulfillment networks compress delivery windows. CE marking compliance for automated material handling equipment extends tenant fit-out timelines.
- Automated Warehouse:Facilities pre-equipped with vertical storage density and robotic picking infrastructure, typically exceeding 50,000 square meters. Labor scarcity in Spanish logistics hubs accelerates capital deployment toward AS/RS systems in Valencia and Algeciras port zones. Extended commissioning periods inflate IT consultancy spend during WMS-ERP integration.
- Public Warehouse:Multi-tenant facilities offering flexible lease terms and shared labor pools for seasonal demand spikes.
- Private Warehouse:Single-user dedicated facilities with customized layouts for captive inventory control.
By volume, Distribution Center leads. By growth pace, Automated Warehouse is ahead.
End User:
Margin structures diverge sharply across tenant categories, with E-commerce operators accepting premium rents for automation-ready infrastructure while Manufacturing tenants prioritize cost efficiency over specification.
- E-commerce:Fulfillment velocity requirements compressing warehouse specification cycles toward higher automation and faster throughput. Inventory positioning is fragmenting into 15-minute drive-time catchments from dense population centers in Barcelona's Sant Andreu and Madrid's Usera districts. Dark store operators secure short-term industrial leases with break clauses.
- Retail:Omnichannel consolidation driving demand for centralized fulfillment nodes with cross-docking capabilities. Regional retail chains in Zaragoza and Bilbao corridors are retrofitting legacy storage into temperature-controlled infrastructure for fresh grocery verticals.
- Food & Beverage:Temperature-controlled requirements with stringent EU hygiene standards and cold chain integrity mandates.
- Manufacturing:Buffer stock positioning for just-in-sequence production supply with lower automation thresholds.
By lease volume, Retail occupies the largest share. By expansion trajectory, E-commerce is climbing the fastest.
Storage System:
Supply concentration favors racking system providers with pan-European manufacturing footprints, while automated storage vendors face extended certification cycles under EU machinery directives.
- Automated Storage:Vertical lift modules and shuttle systems maximizing cube utilization in land-constrained Madrid M-40 corridor. Capital allocation is intensifying as labor scarcity and throughput requirements escalate. Specialized technician scarcity elevates operational risk and service contract pricing.
- Racking System:Selective, drive-in, and push-back configurations forming the structural backbone of conventional warehouses. Demand remains concentrated in secondary city corridors where speculative grade-A projects face construction input volatility.
- Pallet Storage:Standardized unit load handling compatible with conventional forklift operations and WMS tracking.
- Bulk Storage:Floor-stacked inventory for non-rackable goods with minimal infrastructure requirements.
By installed base, Racking System dominates. By capital deployment growth, Automated Storage is gaining share fastest.
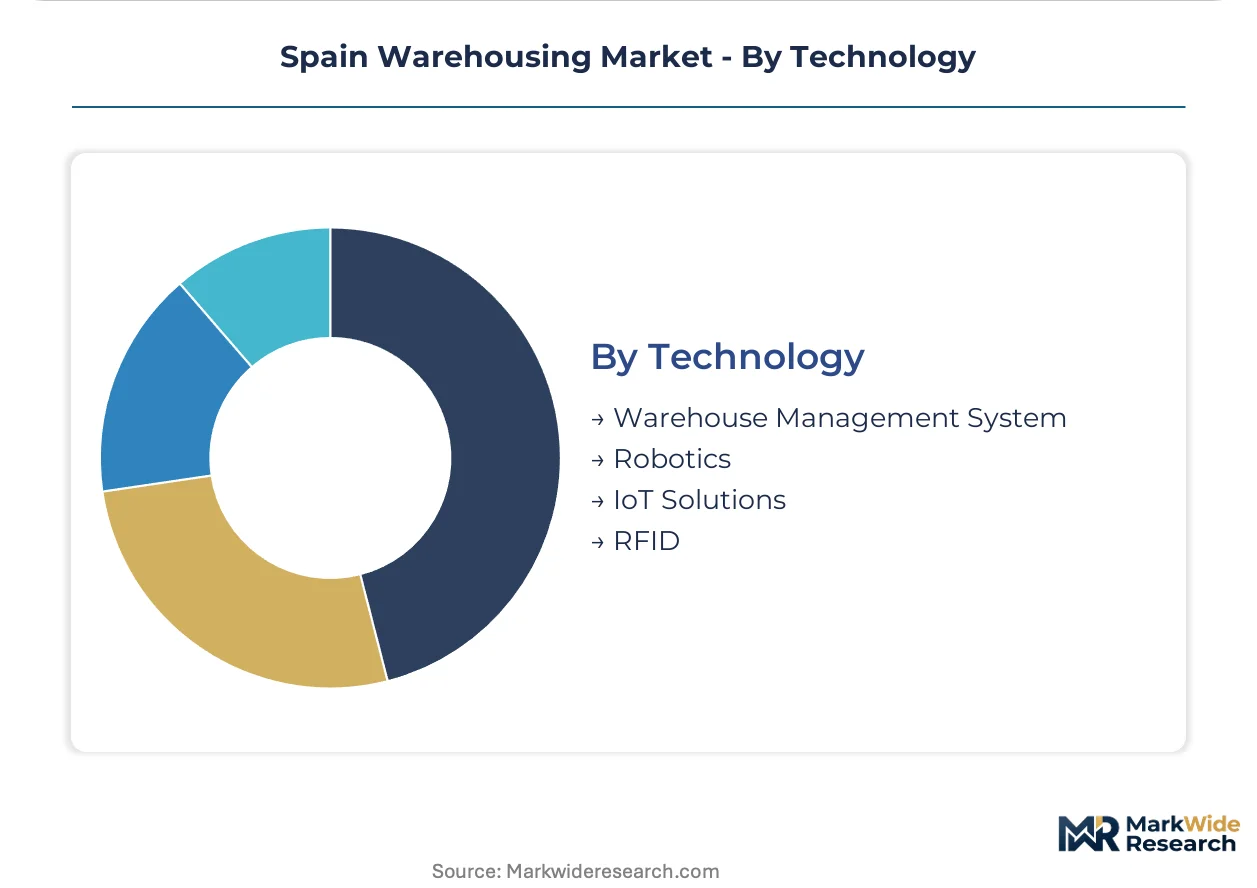
Technology:
Customer type stratification separates enterprise-grade integrated platforms from modular point solutions targeting mid-size 3PL operators.
- Warehouse Management System:Software layer orchestrating inventory tracking, order fulfillment, and labor optimization across multi-node networks. Interoperability with legacy ERP platforms extends commissioning periods. Mid-size 3PL operators in Valencia and Seville corridors pilot AMR fleets on short-term rental terms.
- Robotics:Autonomous mobile robots hybridizing labor models through goods-to-person workflows without fixed infrastructure commitment. Flexibility compresses automation adoption timelines from multi-year capex cycles to operational expenditure scaling.
- IoT Solutions:Sensor networks monitoring environmental conditions, equipment health, and energy consumption for predictive maintenance.
- RFID:Radio-frequency identification enabling real-time inventory visibility and automated gate verification.
By deployment penetration, WMS leads. By investment momentum, Robotics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Logistics Center Law anchors the Iberian warehousing corridor, concentrating speculative development around Madrid and Barcelona while regional port zones capture cross-border fulfillment demand.
Madrid
E-commerce fulfillment velocity drives speculative grade-A construction within the M-40 orbital zone. The Logistics Center Law provides municipal tax abatements and accelerated permitting for designated logistics parks. Land availability has compressed to sub-5% of 2019 levels, forcing developers toward vertical storage density and AS/RS pre-positioning.
Catalonia
The Barcelona metropolitan corridor fragments traditional hub-and-spoke logic through dark store conversion of vacant big-box retail. CE marking compliance for automated material handling equipment extends tenant fit-out timelines. Sant Andreu and peripheral districts host hyperlocal fulfillment nodes operating on short-term industrial leases with break clauses.
Valencia
Port-centric bonded warehouse demand expands as Iberian Peninsula positioning captures North African and Latin American cross-border flows. EU Energy Performance of Buildings Directive mandates drive nearly-zero energy standards for new stock exceeding 5,000 square meters. Photovoltaic arrays and battery storage systems secure occupancy certificates ahead of competitor markets.
Andalusia
The Algeciras port zone anchors transshipment warehousing for Mediterranean-African trade corridors. Regional environmental impact assessments constrain greenfield development timelines compared to central corridor zones. Temperature-controlled infrastructure remains underdeveloped for pharma verticals seeking first-mover positioning.
Basque Country
Bilbao corridor logistics zones attract cold chain penetration for fresh grocery and pharmaceutical verticals. Construction input volatility for steel and reinforced concrete erodes development pro forma certainty. Secondary city positioning offers lower land basis than Madrid-Barcelona axis competitors.
Spain Warehousing Market Competitive Landscape
Capability concentration sits with pan-European platform operators; scale advantage sits with regional specialists with in-house construction velocity. The market structures around three tiers: global logistics REITs with premium last-mile positioning, European developers with design-build capabilities, and regional asset converters repurposing commercial stock. Consolidation pressure intensifies through speculative development ahead of signed leases and automation-ready infrastructure pre-commitment.
Among global platform operators, Prologis and Segro exemplify the premium-tier archetype through pan-European network density. Goodman Group and Merlin Properties occupy distinct positioning vectors—Goodman through in-house construction and design velocity, Merlin through commercial asset conversion into modern logistics stock. Logicor and Panattoni represent the mid-market expansion tier targeting secondary corridors with build-to-suit flexibility.
| Leading Market Players |
|---|
| Prologis |
| Segro |
| Goodman Group |
| Merlin Properties |
| Logicor |
| Panattoni |
| VGP |
| CTP Invest |
| DHL Supply Chain |
| Others |
Pricing and Supply Chain Analysis
Steel and reinforced concrete supply from Turkey and North Africa anchors development cost structures across Spain's logistics corridor, concentrating margin capture with developers possessing in-house construction velocity and long-term supplier offtake agreements.
Pricing Analysis
Madrid-Barcelona axis commands 25-35% rent premiums over secondary corridors, with three-tier pricing structure across BREEAM Excellent-certified premium stock, standard grade-A facilities, and legacy Class-B conversions. Certification grade and automation readiness drive price differentiation, while construction input volatility compresses speculative developer margins. E-commerce operators exhibit lowest price sensitivity, accepting premium rents for last-mile positioning; mid-size 3PLs in Valencia and Seville corridors face acute cost pressure.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements for racking system providers and automated equipment vendors, straining working capital for mid-tier contractors. Spain's logistics construction draws from German engineering inputs, Chinese steel components, and domestic concrete supply. Single-source vulnerability concentrates in automated storage and retrieval system controllers from German and Japanese manufacturers. Distribution runs through pan-European platform operators with captive installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
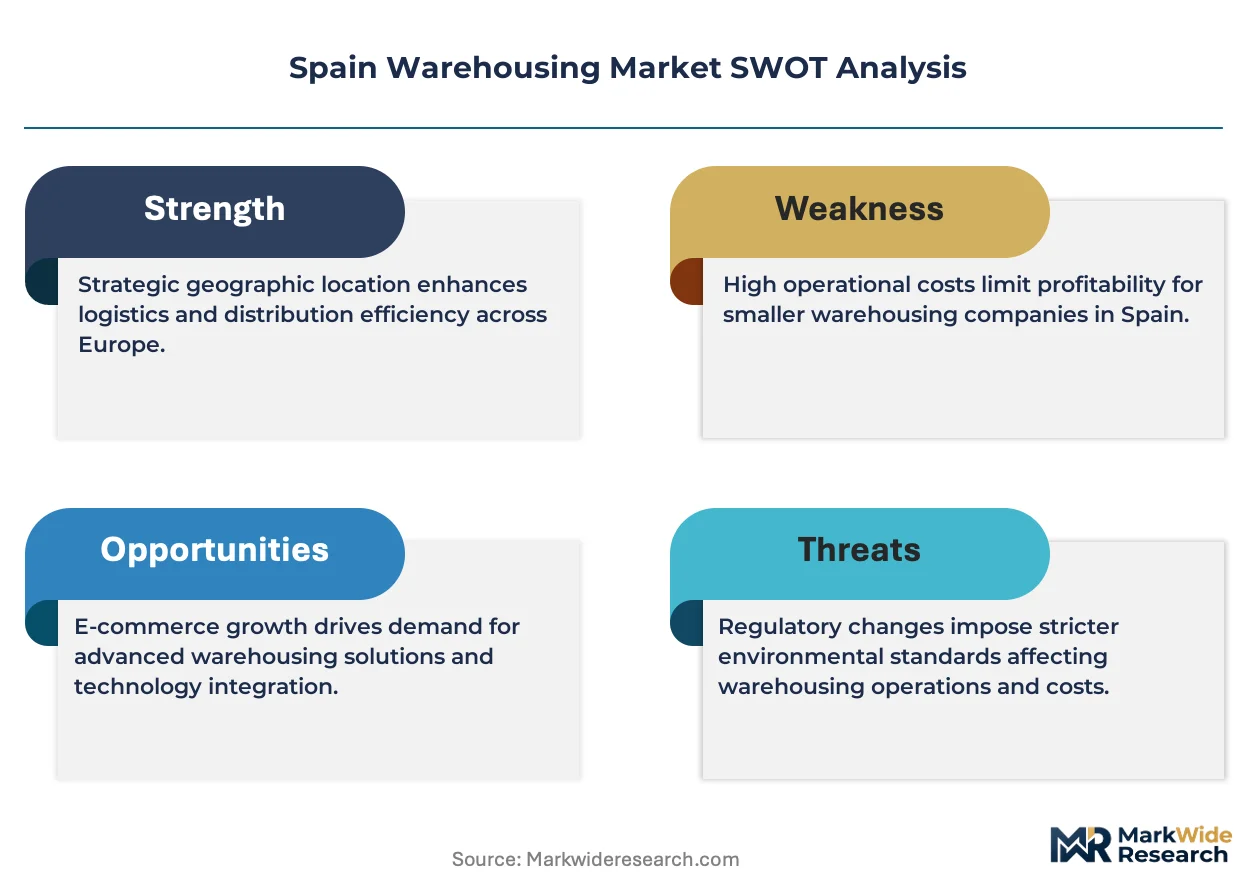
Spain's warehousing market constitutes a defensive-moat opportunity anchored in regulatory entrenchment: the Logistics Center Law's municipal tax abatements and accelerated permitting create structural barriers for unanchored competitors.
For Market Incumbents: Entrench through backward integration into land banking within the M-40 orbital zone and captive maintenance engineering capabilities for automated racking systems. Automation integration complexity and specialized technician scarcity threaten operational continuity; CE marking compliance investment secures tenant fit-out velocity against speculative entrants.
For New Entrants and Emerging Players: Zaragoza and Bilbao corridor cold chain infrastructure offers underpenetrated white-space for pharma and fresh grocery verticals. Dark store conversion of vacant big-box retail in Barcelona's periphery bypasses greenfield development timelines entirely. Build-to-suit flexibility with short-term lease structures targets mid-size 3PL operators priced out of Madrid-Barcelona premium stock.
For Investors and Strategic Acquirers: Capital is best deployed toward European developers with in-house design-build velocity and regional asset converters with commercial-to-logistics repositioning track records. Long-term viability rests on automation-ready infrastructure pre-commitment ahead of tenant demand crystallization. Monitor municipal zoning amendments for last-mile restriction signals as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation-Ready Infrastructure Pre-Positioning | AS/RS-capable shell construction captures e-commerce fulfillment velocity ahead of lease signing. |
| Dark Store Conversion | Vacant big-box retail repositioning in Barcelona's Sant Andreu bypasses greenfield permitting timelines. |
| Net-Zero Certification Investment | BREEAM Excellent-rated facilities command widening rent spreads under EU Energy Performance Directive mandates. |
| Secondary City Cold Chain Buildout | Temperature-controlled infrastructure in Zaragoza corridor secures first-mover positioning for pharmaceutical verticals. |
| Pan-European Platform Consolidation | Scale advantage in Madrid-Barcelona corridor logistics zones reinforces last-mile network density against fragmented competitors. |
Research Methodology
Desk research of municipal zoning filings, EU regulatory transposition documents, and logistics REIT SEC disclosures preceded structured interviews with warehouse development executives, 3PL operations directors, and automated equipment procurement leads. Primary fieldwork with Madrid and Barcelona corridor site managers, Valencia port zone bonded warehouse operators, and Basque Country cold chain specialists combined with secondary validation from Spain's national building code interpretations and regional environmental impact assessment records. Bottom-up unit economics and top-down sectoral demand triangulation anchored market sizing.
Assumptions held fixed include Logistics Center Law incentive continuity and EU Green Deal building performance trajectory, while construction input cost volatility and automation adoption pace were modeled as scenario variables across the projection horizon. Segmentation modeling incorporated warehouse type, end-user vertical, storage system technology, and regional logistics zone dimensions. CAGRs derived from historical absorption rates and forward development pipeline analysis, with e-commerce fulfillment velocity and cross-border trade flow intensity as key demand-side inputs.
Practitioners should monitor municipal zoning amendments, steel and concrete cost indices, and CE marking compliance timeline extensions for early signals of forecast deviation. Macroeconomic contraction, regulatory incentive withdrawal, or technological disruption in autonomous mobile robot deployment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
US Property Management Software Market
Property Management
South Korea Self-Storage Market
Property Management
Real Estate (Property) Management Market
Property Management
Europe Self Storage Market
Property Management
Hungary Warehousing Sector Market
Property Management
Qatar Flexible Office Space Market
Property Management
Real Estate Management Software Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
Residential Property Management Market
Property Management
United States Property Management Market
Property Management
Property Management Service Market
Property Management
Property Management Software Market