
 Saudi Arabia Seafood Market | 2026-2036
Saudi Arabia Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Seafood Market Analytics
Premium-grade fresh seafood is reorganizing procurement priorities across Saudi Arabia's hospitality and retail sectors. Tabuk Fisheries Co. leverages its Red Sea farm sites to supply hotels with same-day-harvested fish. National Aquaculture Group anchors domestic shrimp production through integrated hatchery-to-processing operations. Almunajem Foods controls cold-chain distribution across Riyadh and the Eastern Province, extending reach into institutional catering.
Saudi Arabia seafood encompasses finfish, crustaceans, and mollusks harvested from wild fisheries or aquaculture systems, typically processed to moisture content below 80 percent for fresh retail or blast-frozen at minus 35 degrees Celsius for shelf-stable distribution. The category serves protein substitution in foodservice menus and retail meal preparation. Fish dominates volume throughput in supermarket and foodservice channels, while shrimp captures disproportionate margin in premium hotel and restaurant segments. Flexible packaging and vacuum-sealed formats are gaining share in online retail as delivery platforms expand same-day seafood logistics.
The Saudi Food and Drug Authority enforces Hazard Analysis Critical Control Point standards across import and domestic processing facilities, elevating compliance costs for smaller traders. The General Authority for Food and Drug Administration's traceability mandates now require lot-level documentation from vessel or farm through retail shelf. Stakeholders must monitor how the National Water Company's aquaculture licensing reforms affect farm expansion permits along the Red Sea coast.
Market Dynamics
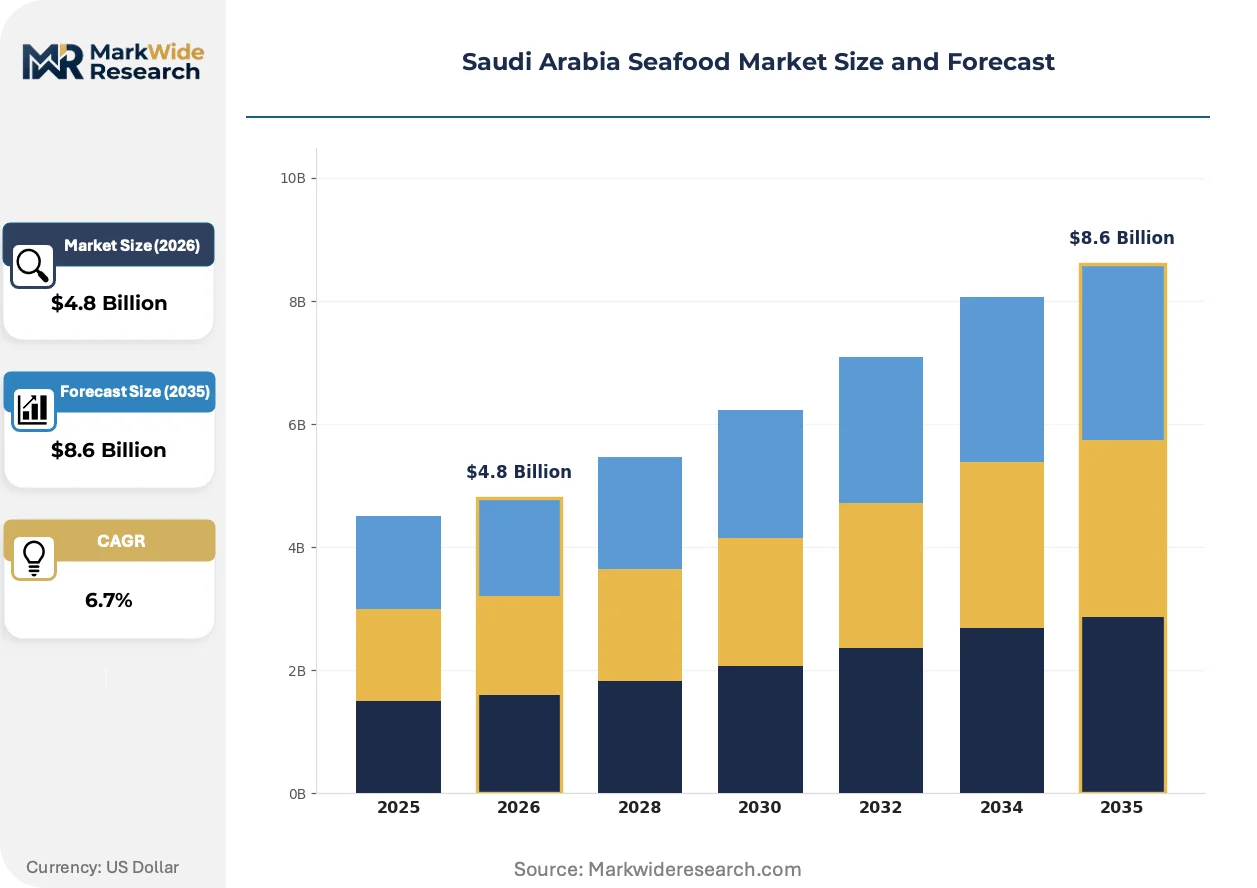
The Saudi Food and Drug Authority's Hazard Analysis Critical Control Point mandates are forcing capital redeployment across cold-chain infrastructure, while Red Sea aquaculture licensing reforms concentrate production permits in coastal governorates.
Growth Catalysts
- SFDA Cold-Chain Mandates:Tightened traceability requirements from vessel to retail shelf are accelerating consolidation among distributors capable of lot-level documentation.
- Red Sea Aquaculture Licensing:The National Water Company's streamlined permit process for coastal farm sites is expanding domestic finfish and shrimp output capacity.
- Foodservice Channel Premiumization:Jeddah and Riyadh hotels are prioritizing same-day-harvested seafood, pulling supply toward integrated hatchery-to-harvest operations.
Market Restraints
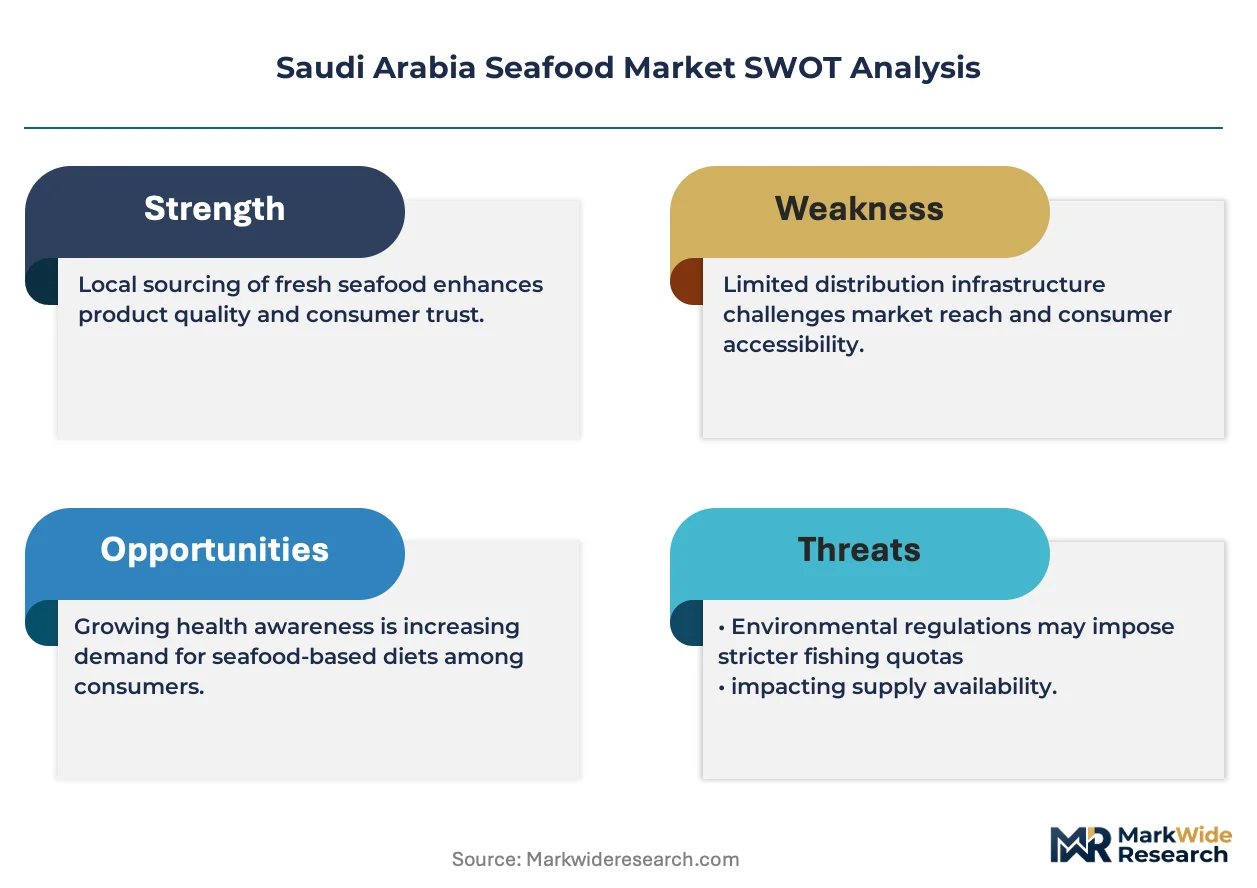
- Import Dependency Concentration:Frozen shrimp and whitefish supply clusters through Jeddah Islamic Port, creating single-point vulnerability for Riyadh and Eastern Province distribution.
- Energy Input Cost Volatility:Seawater recirculation systems and blast-freezing operations expose aquaculture farms and processing facilities to electricity tariff fluctuations.
- Technical Shelf-Life Limitation:Fresh seafood moisture content above 80 percent restricts same-day delivery radius, constraining e-commerce penetration outside major metros.
Strategic Opportunities
- Asir and Najd Retail Underpenetration:Supermarket seafood counters remain sparse in Abha and Buraidah, creating first-mover space for cold-chain distributors with vacuum-sealed packaging capabilities.
- Institutional Catering Direct Supply:Hospital and university meal programs are bypassing wholesale markets, opening contract farming arrangements for domestic aquaculture operators.
- SFDA Traceability Technology Convergence:Blockchain-based lot tracking combined with IoT temperature monitoring is enabling premium pricing for documented origin seafood in hotel procurement.
Industry Challenges
- HACCP Certification Timeline Compression:Smaller importers face 12-18 month compliance windows for facility upgrades, forcing exit or acquisition by integrated distributors.
- Refrigerated Fleet Capex Intensity:Compliance with minus 35 degrees Celsius blast-freeze standards requires fleet replacement cycles that strain mid-tier logistics operators.
- Multispecies Hatchery Skill Scarcity:Domestic production of European seabass and gilthead seabream fry depends on imported technical expertise, constraining farm expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Seafood Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shrimps, Crabs, Mollusks Sales Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Packaging Type: Flexible Packaging, Cans, Vacuum Sealed, Foam Containers Grade: Premium, Standard, Frozen, Fresh |
| Companies Covered | Tabuk Fisheries Co., IZAFCO Fish Packing Company, National Aquaculture Group (NAQUA), Sealand Foods, Sammak, Saudi Fisheries Company, Almunajem Foods, Shell Fisheries Company W.L.L., Arab Fisheries Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Seafood Market Evolving Landscape
Recirculating aquaculture systems and automated grading technology are compressing harvest-to-retail timelines, while regulatory traceability mandates are digitizing supply chain documentation.
Recirculating aquaculture systems with biofiltration and oxygen injection are enabling land-based finfish production independent of Red Sea water quality fluctuations. National Aquaculture Group and Tabuk Fisheries Co. are deploying these systems at commercial scale for seabass and seabream. This controlled-environment approach is supplanting open-net pen operations in coastal waters, reducing disease risk and harvest variability while permitting inland farm siting closer to Riyadh consumption centers.
The Saudi Food and Drug Authority's 2023 traceability protocol requires vessel-level documentation for all imported seafood, with digital submission through the SFDA's unified electronic system. Processing facilities must maintain temperature logs at 15-minute intervals for cold-chain validation. Hotels and high-end restaurants in Jeddah are now requiring blockchain-verified origin certificates as a procurement condition, filtering suppliers unable to provide granular catch documentation.
Foodservice buyers in Riyadh are consolidating orders through specialized seafood procurement platforms that aggregate demand across hotel chains and restaurant groups. These platforms bypass traditional wholesale market intermediaries, offering direct farm-to-kitchen logistics with guaranteed same-day delivery windows. The model is most visible in the premium hotel segment, where executive chefs prioritize consistent species availability and documented sustainability credentials over spot-market price flexibility.
Saudi Arabia Seafood Market Segmentation
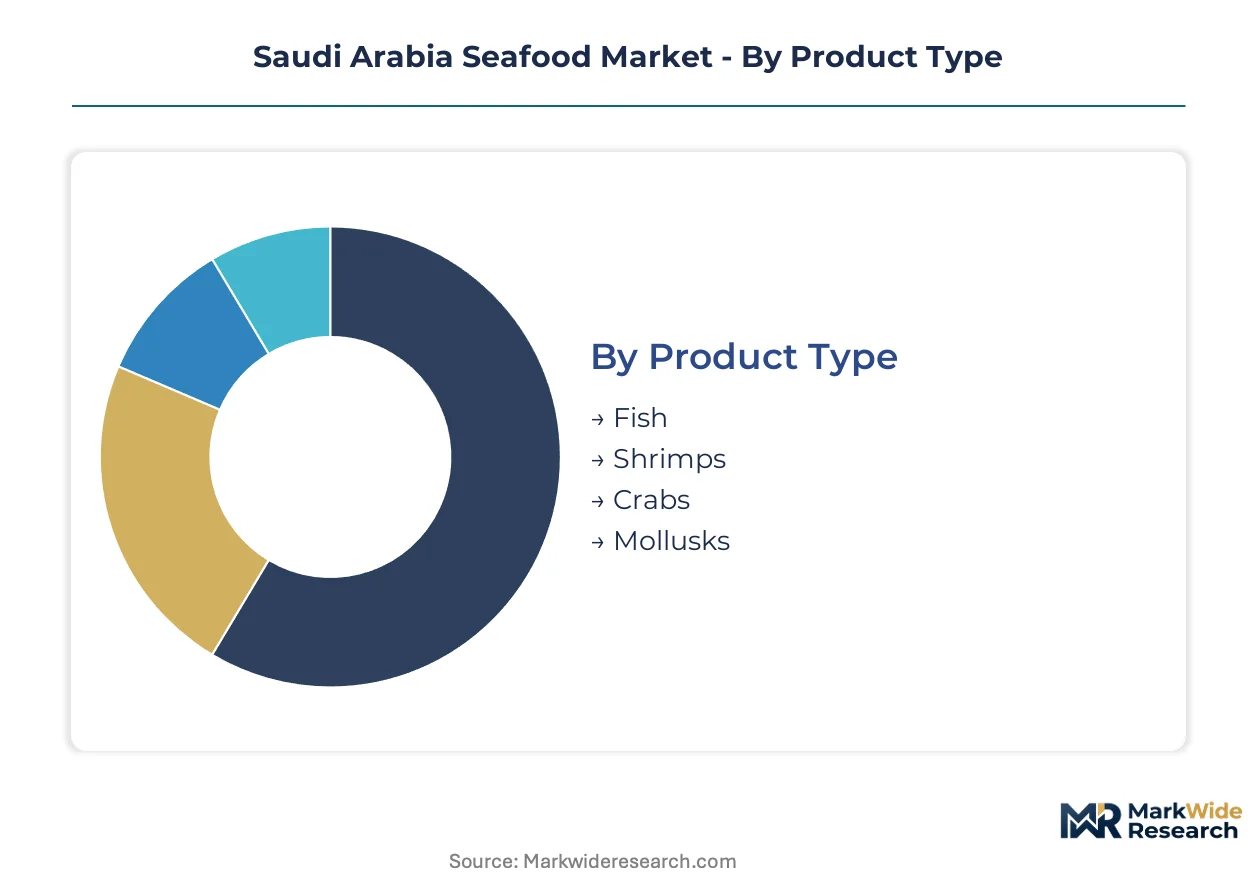
Segmentation in Saudi Arabia's seafood market tracks how regulatory pressure and channel evolution reshape procurement patterns. SFDA traceability mandates and cold-chain investments are fragmenting traditional supply routes while concentrating volume in compliant formats and certified grades.
Product Type:
Plant-based protein alternatives and poultry substitution campaigns in Jeddah and Riyadh foodservice channels place varying pressure on seafood categories depending on price positioning and preparation format.
- Fish:Finfish species including hammour, seabass, and seabream dominate hotel and restaurant menus across the Red Sea coastal cluster. Jeddah's premium hotel segment sources same-day-harvested fish through integrated aquaculture operations, with Tabuk Fisheries Co. and National Aquaculture Group controlling hatchery-to-harvest supply chains for consistent quality and documented origin.
- Shrimps:Penaeus species and black tiger varieties command disproportionate margin in fine-dining and catering applications. Domestic production concentrates in Yanbu and Al-Lith farm clusters, though import dependency persists for processed and value-added shrimp products entering through Jeddah Islamic Port.
- Crabs:Blue swimmer and mud crab varieties serve niche hospitality segments in Eastern Province resort properties.
- Mollusks:Squid, cuttlefish, and oyster products face limited domestic aquaculture capacity, relying heavily on frozen imports for foodservice processing.
Fish retains volume leadership across all channels; shrimps hold the steepest expansion curve in premium foodservice procurement.
Sales Channel:
Channel cost structures diverge sharply based on cold-chain compliance requirements and SFDA documentation burdens, with smaller intermediaries facing forced consolidation.
- Online Retail:Same-day delivery platforms are expanding vacuum-sealed and flexible-packaging formats for Riyadh and Jeddah metro consumers. Temperature-controlled logistics partnerships with Almunajem Foods and specialized seafood distributors enable this channel's growth despite technical shelf-life constraints outside major urban centers.
- Supermarkets:Retail seafood counters in Panda, Carrefour, and Lulu networks concentrate fresh fish and frozen shrimp SKUs. The SFDA's lot-level traceability mandates favor integrated suppliers capable of blockchain-verified documentation, squeezing traditional wholesale intermediaries.
- Specialty Stores:Independent fishmongers in Jeddah's Central Fish Market and Riyadh's Al-Batha district serve ethnic communities and traditional preparation preferences.
- Food Service:Hotels, restaurants, and catering operations in Jeddah and Riyadh are consolidating procurement through specialized platforms that aggregate demand and guarantee species availability with sustainability credentials.
Food service channels capture the highest value per kilogram; online retail is climbing fastest as delivery infrastructure matures.
Packaging Type:
Packaging selection tracks directly against distribution radius and channel temperature control capabilities, with premium formats enabling geographic extension of fresh product reach.
- Flexible Packaging:Modified atmosphere and vacuum-sealed pouches are displacing traditional foam and ice configurations in supermarket and online channels. These formats extend shelf life for domestic aquaculture products reaching Riyadh from Red Sea farm sites.
- Cans:Tuna and mackerel in brine or oil serve institutional catering and retail pantry stocking, with import concentration through Jeddah Islamic Port.
- Vacuum Sealed:Premium hotel and restaurant procurement increasingly requires vacuum-sealed fresh products with integrated temperature loggers for SFDA cold-chain validation.
- Foam Containers:Traditional wet-fish packaging persists in wholesale market transactions and specialty store supply, though regulatory pressure is accelerating format transition.
Flexible packaging leads volume in modern retail; vacuum sealed formats are expanding most quickly in premium hospitality procurement.
Grade:
Grade stratification reflects the divergence between domestic aquaculture certification tiers and import quality classifications, with procurement premiums attaching to documented origin and harvest timing.
- Premium:Same-day-harvested, HACCP-certified products from integrated Saudi farms command placement in Jeddah and Riyadh five-star hotel kitchens. Blockchain traceability and vessel-level documentation are becoming standard procurement conditions for this tier.
- Standard:Blast-frozen imports and domestic farm products meeting baseline SFDA safety standards serve mid-tier restaurants and retail counters across Asir and Najd regions.
- Frozen:Minus 35 degrees Celsius blast-frozen products dominate import throughput through Jeddah Islamic Port, supplying Riyadh and Eastern Province distribution with extended shelf stability.
- Fresh:Unfrozen products with moisture content below 80 percent serve immediate-consumption foodservice and retail segments within same-day delivery radius of Red Sea harvest points.
Frozen grade holds volume leadership through import dependency; premium grade is gaining share fastest as hotel procurement requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Harvest operations and cold-chain infrastructure concentrate along Saudi Arabia's Red Sea coastline, with distribution networks radiating inland toward consumption centers in the central and eastern regions.
Western Region
Jeddah and Yanbu anchor domestic aquaculture output and import throughput for finfish and shrimp. The Saudi Food and Drug Authority's cold-chain mandates are accelerating warehouse upgrades at Jeddah Islamic Port. Tabuk Fisheries Co. operates integrated farm sites supplying same-day-harvested product to premium hotel kitchens.
Central Region
Riyadh's foodservice and retail channels drive the highest per-kilogram procurement values in the Kingdom. National Water Company licensing reforms are enabling inland recirculating aquaculture systems closer to this consumption center. Almunajem Foods controls temperature-controlled distribution infrastructure serving supermarket and institutional catering accounts.
Eastern Province
Dammam and Khobar hospitality properties source seafood through Jeddah Islamic Port import corridors, creating logistics cost premiums versus western region buyers. The General Authority for Food and Drug Administration's traceability requirements favor distributors with blockchain-verified documentation capabilities. Resort properties in Al-Khobar represent niche demand for crab and mollusk varieties.
Asir and Najd
Abha and Buraidah retail markets remain underpenetrated by modern seafood counters, with traditional wet-fish vendors dominating local supply. Vacuum-sealed packaging and modified atmosphere technologies are enabling geographic extension of fresh product reach from Red Sea farm sites. First-mover distributors are establishing cold-chain partnerships with regional supermarket operators.
Saudi Arabia Seafood Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated aquaculture operators commanding premium placement while import-dependent distributors compete on volume throughput. The market structure reflects a tiered consolidation pattern: three domestic farm-to-fork conglomerates control hatchery-to-harvest supply chains, mid-tier cold-chain specialists manage regional distribution, and fragmented import traders face regulatory pressure to consolidate. Strategic moves center on HACCP certification acquisition and refrigerated fleet expansion to meet SFDA compliance windows.
Among integrated aquaculture operators, Tabuk Fisheries Co. and National Aquaculture Group occupy positions exemplifying hatchery-to-harvest control, while Almunajem Foods represents the cold-chain distribution archetype spanning institutional and retail channels. These three anchors illustrate how regulatory traceability mandates are filtering market participation toward capital-intensive operational models.
| Leading Market Players |
|---|
| Tabuk Fisheries Co. |
| IZAFCO Fish Packing Company |
| National Aquaculture Group (NAQUA) |
| Sealand Foods |
| Sammak |
| Saudi Fisheries Company |
| Almunajem Foods |
| Shell Fisheries Company W.L.L. |
| Arab Fisheries Co. |
| Others |
Value Network & Pricing Analysis
Blast-freeze capacity utilization at Jeddah Islamic Port underwrites pricing power for integrated cold-chain operators while squeezing margin for import-dependent traders without vessel-level documentation capabilities. Scale concentration in Red Sea aquaculture clusters creates floor pricing for same-day-harvested premium grades, with National Water Company licensing reforms accelerating capacity additions that moderate upward price pressure in domestic finfish categories.
Pricing Analysis
SFDA Hazard Analysis Critical Control Point mandates dictate the pricing tier structure across Saudi Arabia seafood procurement, with HACCP certification separating premium farm-direct contracts from standard import spot markets. Price differentiation rests on blockchain-verified origin documentation and same-day harvest timing for hotel buyers, while frozen import grades face compression from electricity tariff volatility affecting blast-freeze operations. Cost compression in standard-tier frozen shrimp is intensifying because Riyadh foodservice buyers are consolidating orders through specialized procurement platforms. Quick-service restaurant chains show highest price sensitivity; five-star hotel executive chefs prioritize documented sustainability credentials over spot-market flexibility.
Supply Chain Analysis
Jeddah Islamic Port throughput underwrites supply security for Riyadh and Eastern Province distribution networks, with single-point vulnerability concentrated in frozen whitefish and processed shrimp import corridors. Raw material flows draw from Vietnam, India, and Ecuador for penaeid shrimp varieties, while European seabass and gilthead seabream fry feed from Mediterranean hatchery partnerships. Tariff exposure sits with reprocessed value-added products transiting through third-country packaging hubs. Distribution runs through Almunajem Foods temperature-controlled fleet for supermarket and institutional accounts, with specialized seafood platforms disintermediating traditional wholesale market intermediaries in premium hotel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated foodservice procurement platforms in Jeddah and Riyadh, fragmenting traditional wholesale market intermediaries and compressing margin capture for undifferentiated import traders.
For Market Incumbents: Shield margin position by accelerating HACCP certification acquisition for processing facilities ahead of SFDA compliance windows, and deepen backward integration into Red Sea hatchery operations to secure fry supply against imported technical expertise constraints. Threat substitution from poultry protein campaigns in mid-tier restaurant segments demands documented origin certification as defensive differentiation. For New Entrants and Emerging Players: Anchor in Asir and Najd retail underpenetration where vacuum-sealed packaging capabilities enable first-mover establishment of seafood counters in Abha and Buraidah supermarket networks. The most penetrable segment is institutional catering direct supply for hospital and university meal programs bypassing wholesale markets. Go-to-market angle should leverage recirculating aquaculture system technology partnerships for inland farm siting closer to Riyadh consumption centers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cold-chain specialists with blockchain-verified traceability infrastructure over commodity import traders facing regulatory consolidation pressure. Long-term viability across the projection horizon rests on captive supply integration from hatchery through processing. Acquisition target archetype: mid-tier distributors with refrigerated fleet assets and SFDA electronic submission system compliance. Signal to watch is National Water Company aquaculture licensing reform implementation pace affecting domestic production permit availability.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Investment | SFDA compliance windows are forcing facility upgrades that filter smaller traders from participation. |
| Recirculating Aquaculture System Deployment | Land-based production independent of Red Sea water quality reduces disease risk and harvest variability. |
| Blockchain Traceability Integration | Hotels now require vessel-level documentation as standard procurement condition for premium placement. |
| Refrigerated Fleet Expansion | Minus 35 degrees Celsius blast-freeze standards require capital deployment that strains mid-tier logistics operators. |
| Institutional Catering Direct Supply | Hospital and university meal programs are bypassing wholesale markets for contract farming arrangements. |
Research Methodology
Operator-level perspectives from aquaculture farm managers, cold-chain logistics directors, hotel procurement executives, and SFDA compliance officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through Saudi Food and Drug Authority regulatory filings, National Water Company licensing databases, Jeddah Islamic Port customs throughput records, and supermarket seafood counter audit data. Bottom-up volume modeling from farm-level production capacity and top-down demand triangulation from foodservice procurement platform aggregation produced convergent estimates.
Sensitivity analysis tested input assumptions across the projection horizon, with segmentation dimensions spanning product type, sales channel, packaging format, and grade tier alongside regional consumption cluster density. CAGRs were derived from trend extrapolation moderated by regulatory implementation pacing and infrastructure buildout timelines. Industry-specific forecast inputs included electricity tariff trajectories affecting blast-freeze operations and Red Sea water temperature variability projections impacting open-net pen yields.
Material uncertainties — SFDA enforcement intensity, National Water Company permit approval velocity, and foodservice platform consolidation pace — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and infrastructure investment commitments. Practitioners should keep alternative scenarios live as cold-chain compliance cost trajectories and domestic aquaculture expansion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Smoked Whiting Market
Seafood
Mussels Market
Seafood
Seafood Processing Market
Seafood
Rainbow Trout Market
Seafood
Europe Salmon Market
Seafood
Fish Protein Market
Seafood
Canned Tuna Market
Seafood
Canned Sardines Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
North America Seafood Market
Seafood
Dried Scallop Market
Seafood
Asia-Pacific Seafood Market
Seafood
Halibut Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Crustacean Market
Seafood
Seafood Flavors Market