
 Halibut Market | 2026-2036
Halibut Market Size, Share, and Industry Trends Forecast 2026-2036
Halibut Market Outlook
Foodservice buyers are redrawing procurement patterns across the halibut supply chain. Marine Harvest leverages integrated hatchery-to-harvest operations across Norwegian coastal zones. Cooke Aquaculture anchors North American supply through vertically controlled sites in Atlantic Canada. Clearwater Seafoods dominates offshore quota holdings for Greenland halibut, sustaining premium positioning in sushi-grade segments.
Halibut denotes large flatfish species within the Pleuronectidae family, reaching market weights of 10–40 kilograms after four to eight years of grow-out in cold-water marine environments. The fish yields lean, white-fleshed fillets valued for flake texture and neutral flavor profiles in premium culinary applications. Fresh halibut commands the highest margin pool among product type segments due to perishability-driven scarcity and chef preference for whole-fish butchery. Frozen halibut competes on volume in retail channels where blast-freezing technology preserves cellular integrity for home preparation. Vacuum-sealed packaging extends shelf life and supports direct-to-consumer online retail expansion, though bulk packaging retains cost advantages in foodservice procurement.
NOAA Fisheries administers catch limits under the Magnuson-Stevens Act for Pacific halibut stocks, while the EU's Common Fisheries Policy governs Northeast Atlantic quotas. EFSA contaminant thresholds for heavy metals in predatory fish shape maximum residue limits for export-bound product. Stakeholders must monitor quota negotiation outcomes between the International Pacific Halibut Commission and coastal state delegations, as these agreements directly determine raw material availability for processing investments.
Market Dynamics
NOAA catch quotas under the Magnuson-Stevens Act are compressing Pacific halibut landings while Norwegian aquaculture clusters scale Atlantic halibut farm output, creating a bifurcated supply structure that favors vertically integrated cold-water producers.
Growth Catalysts
- EU Common Fisheries Policy reform:The revised technical measures framework incentivizes selective gear adoption in Northeast Atlantic demersal fisheries, reducing bycatch mortality and preserving quota-eligible biomass for targeted halibut harvesters.
- Recirculating aquaculture systems:Closed-containment RAS technology enables land-based Atlantic halibut grow-out in temperature-controlled environments, decoupling production from coastal site availability and seasonal thermal fluctuations.
- Premium foodservice channel expansion:White-tablecloth restaurant groups in Copenhagen, Oslo, and Reykjavik are expanding raw-bar and whole-fish presentation formats that command menu price premiums for fresh domestic halibut.
Market Restraints
- Input cost volatility:Marine protein feed ingredients—fishmeal and fish oil derived from Peruvian anchovy and North Atlantic capelin—fluctuate with El Niño cycles and quota negotiations, compressing farmed halibut margin structures.
- Supply concentration risk:Wild Pacific halibut biomass concentrates in Alaska's regulatory areas 2C and 3A, where International Pacific Halibut Commission survey data determines annual catch limits with limited buffer for processing capacity planning.
- Substitution threat:Farmed turbot from Spanish Galician facilities and wild-caught sablefish from British Columbia longline fleets compete for the same white-fleshed, flake-textured plate presentation in North American and European foodservice.
Strategic Opportunities
- Direct-to-consumer channel innovation:Vacuum-sealed portion packs and subscription-box fulfillment models are opening household penetration in Germany and the United Kingdom, bypassing traditional wholesale auction structures.
- Carbon accounting tailwinds:The EU Green Deal's Farm to Fork Strategy and national eco-label schemes in Norway are creating preference premiums for low-carbon-intensity farmed halibut against air-freighted wild product.
- Technology convergence:Blockchain-enabled provenance tracking combined with AI-driven feed optimization platforms allows integrated producers to offer batch-specific sustainability credentials to ESG-mandated institutional buyers.
Industry Challenges
- Veterinary certification timelines:Obtaining aquaculture health certificates from national veterinary services for live egg and juvenile transfers between Norwegian breeding facilities and grow-out sites involves multi-month approval queues that constrain genetic improvement cycles.
- Processing labor gaps:Skilled fish butchers capable of yield-maximizing halibut breakdown—separating loins, cheeks, and collars for differentiated pricing—are scarce in remote coastal processing centers from Homer, Alaska to Nuuk, Greenland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halibut Market |
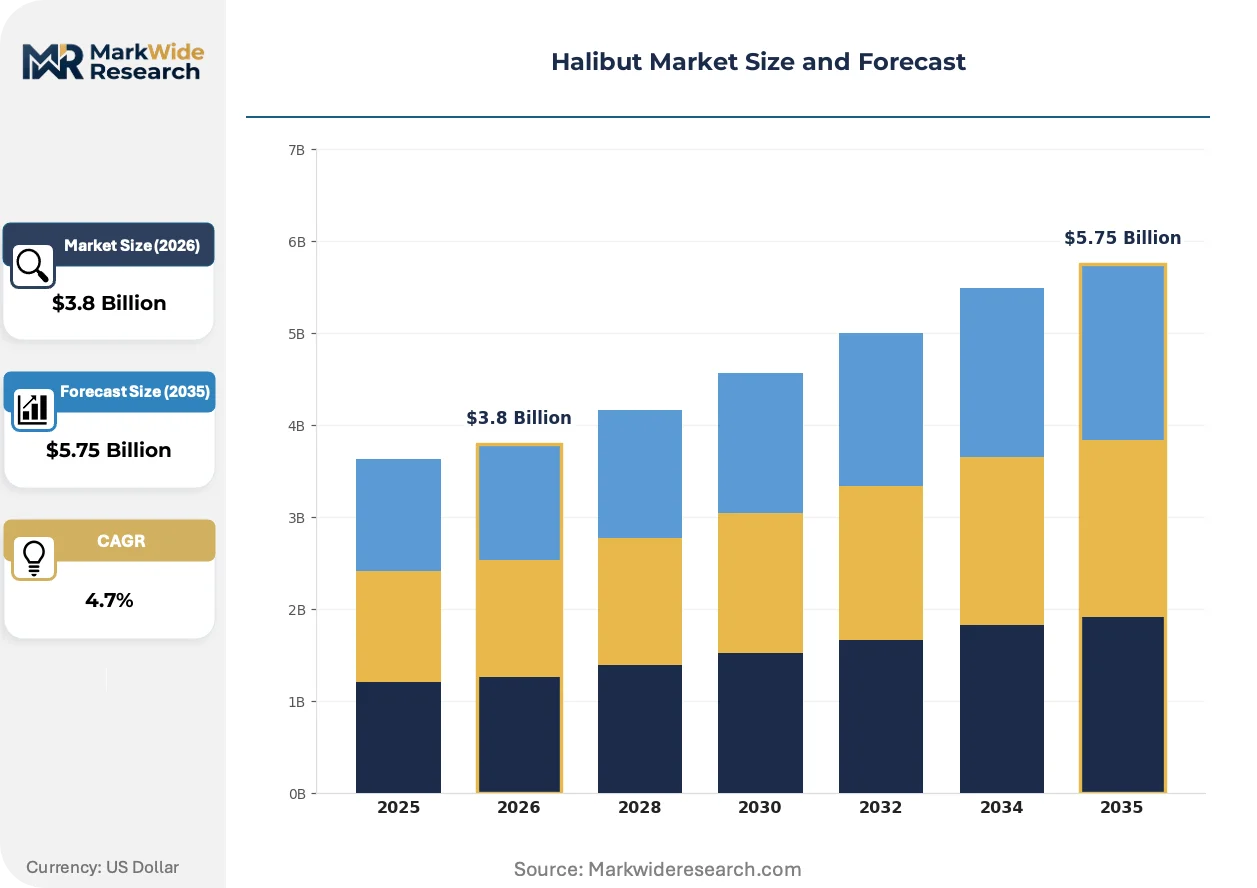
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Halibut, Frozen Halibut, Smoked Halibut, Dried Halibut Packaging Type: Vacuum-Sealed, Canned, Bulk Packaging, Retail Packs Distribution Channel: Supermarkets, Fish Markets, Online Retailers, Foodservice End User: Restaurants, Households, Catering Services, Food Manufacturers |
| Companies Covered | Marine Harvest, Cooke Aquaculture, Stolt Sea Farm, Cermaq Group, Clearwater Seafoods, Fiskerikjøp AS, Ocean Choice International, High Liner Foods, Leader Creek Fisheries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halibut Market Strategic Shifts
Biological production systems and distribution infrastructure are undergoing parallel reinvention. Cold-chain digitization, alternative feed formulations, and precision aquaculture hardware are converging to reshape how halibut reaches end buyers.
Single-cell protein derived from methanotrophic bacteria is supplanting conventional fishmeal in Norwegian Atlantic halibut grow-out diets. Marine Harvest and land-based RAS operators are reformulating feed rations at commercial scale. This ingredient transition is compressing dependency on wild-capture reduction fisheries while introducing novel supply relationships with industrial biotechnology suppliers.
EFSA has tightened maximum residue limits for heavy metals in predatory fish, prompting processing investments in rapid-testing protocols. Norwegian exporters to continental Europe are deploying ICP-MS screening at plant gates. The fresh fillet segment bears the highest compliance burden, as real-time certification must accompany each shipment to avoid border detention.
Chef buyers in Copenhagen and Stockholm are consolidating purchasing through specialized seafood procurement platforms that aggregate demand across restaurant groups. These digital intermediaries displace traditional wholesale auction participation. The shift is most visible in Scandinavia, where transparent pricing and lot-traceability have become standard contract terms for premium whitefish sourcing.
Halibut Market Segmentation
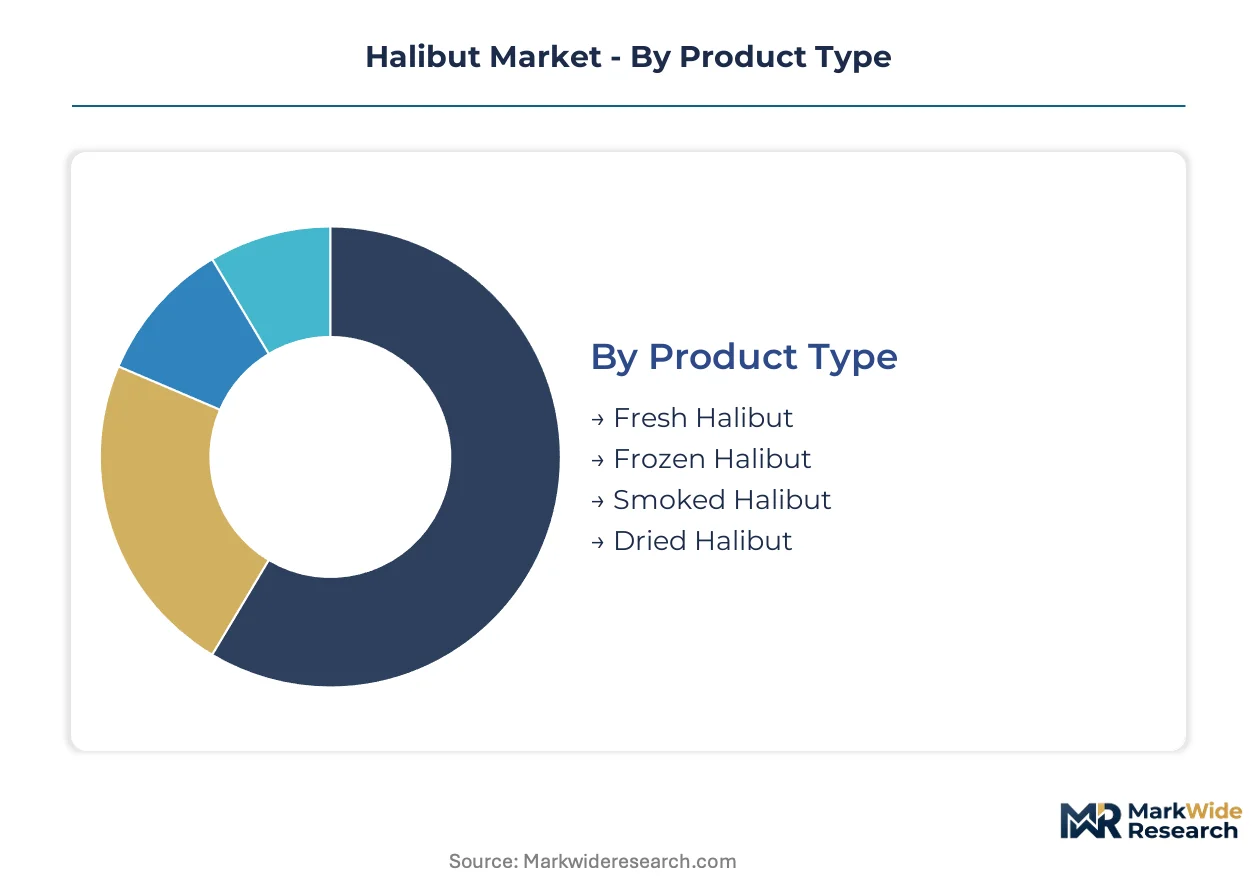
Halibut procurement patterns diverge sharply across product formats and channel structures. Norwegian aquaculture clusters supply fresh fillets to Copenhagen and Oslo restaurants while Alaskan wild-caught volumes freeze for retail distribution in Germany and the United Kingdom.
Product Type:
Fresh halibut concentrates in domestic Scandinavian foodservice channels; frozen, smoked, and dried formats drive export volumes to continental Europe and North America.
- Fresh Halibut:Whole-fish and H&G (headed and gutted) presentations dominate white-tablecloth procurement in Norway, Denmark, and Iceland. Perishability limits radius to 48-hour cold-chain delivery, creating scarcity premiums in Reykjavik and Stockholm raw-bar concepts.
- Frozen Halibut:Blast-frozen at sea or shore plants in Alaska and Greenland, this segment supplies German supermarkets and British meal-kit providers. Cellular integrity preservation via IQF technology maintains flake texture through home preparation.
- Smoked Halibut:Traditional cold-smoking in Scottish and Norwegian facilities serves deli counters in London and Paris. Smaller-batch artisan production commands price multiples over commodity frozen fillets.
- Dried Halibut:Air-dried stockfish variants from Norwegian Lofoten archipelago supply Nigerian and Portuguese import markets. Extended shelf life supports containerized ocean freight economics.
Fresh halibut holds the largest share; momentum sits with frozen formats expanding in direct-to-consumer channels.
Packaging Type:
Packaging economics track customer scale and shelf-life requirements across institutional and household buyers.
- Vacuum-Sealed:Modified-atmosphere packaging extends refrigerated shelf life from 7 to 21 days, enabling Norwegian exporters to reach Milan and Madrid without air freight. Premium positioning in British and German online seafood subscriptions depends on this format.
- Canned:Retort-pouched and tin-packed halibut from Alaskan canneries serves emergency food programs and military procurement. Thermal processing destroys delicate flake texture, limiting this segment to price-sensitive institutional buyers.
- Bulk Packaging:10-kilogram master cartons of frozen fillets supply Copenhagen restaurant groups and Reykjavik hotel chains. Direct vessel-to-warehouse logistics minimize handling costs for high-volume foodservice accounts.
- Retail Packs:200-gram skinless portions in printed cartons occupy chilled cases in Waitrose, Whole Foods Market, and ICA Supermarket locations. Portion standardization reduces consumer preparation friction.
Bulk packaging dominates foodservice procurement; vacuum-sealed formats are climbing the fastest in e-commerce penetration.
Distribution Channel:
Channel selection determines margin capture and traceability investment requirements for Norwegian and Alaskan producers.
- Supermarkets:Albertsons, Tesco, and Coop Norge chains specify Marine Stewardship Council or Aquaculture Stewardship Council certification for fresh counter placement. Private-label frozen fillet programs concentrate buying power with three to four Nordic suppliers.
- Fish Markets:Traditional auction halls in Bergen and Aalesund remain active for whole-fish trade, though volume is shifting to digital platforms. Skilled fishmongers in these markets perform yield-maximizing breakdown for restaurant walk-ins.
- Online Retailers:Subscription boxes from companies like Fiskerikajen and direct-to-consumer platforms bypass wholesale auction structures. Real-time inventory visibility and next-day delivery capabilities are reshaping household purchasing in Germany and the United Kingdom.
- Foodservice:Broadline distributors including Sysco and regional Nordic seafood specialists aggregate demand across independent restaurants and hotel groups. Chef preference for whole-fish butchery sustains H&G and dressed formats in this channel.
Foodservice channels command the highest average selling prices; online retailers represent the steepest expansion trajectory.
End User:
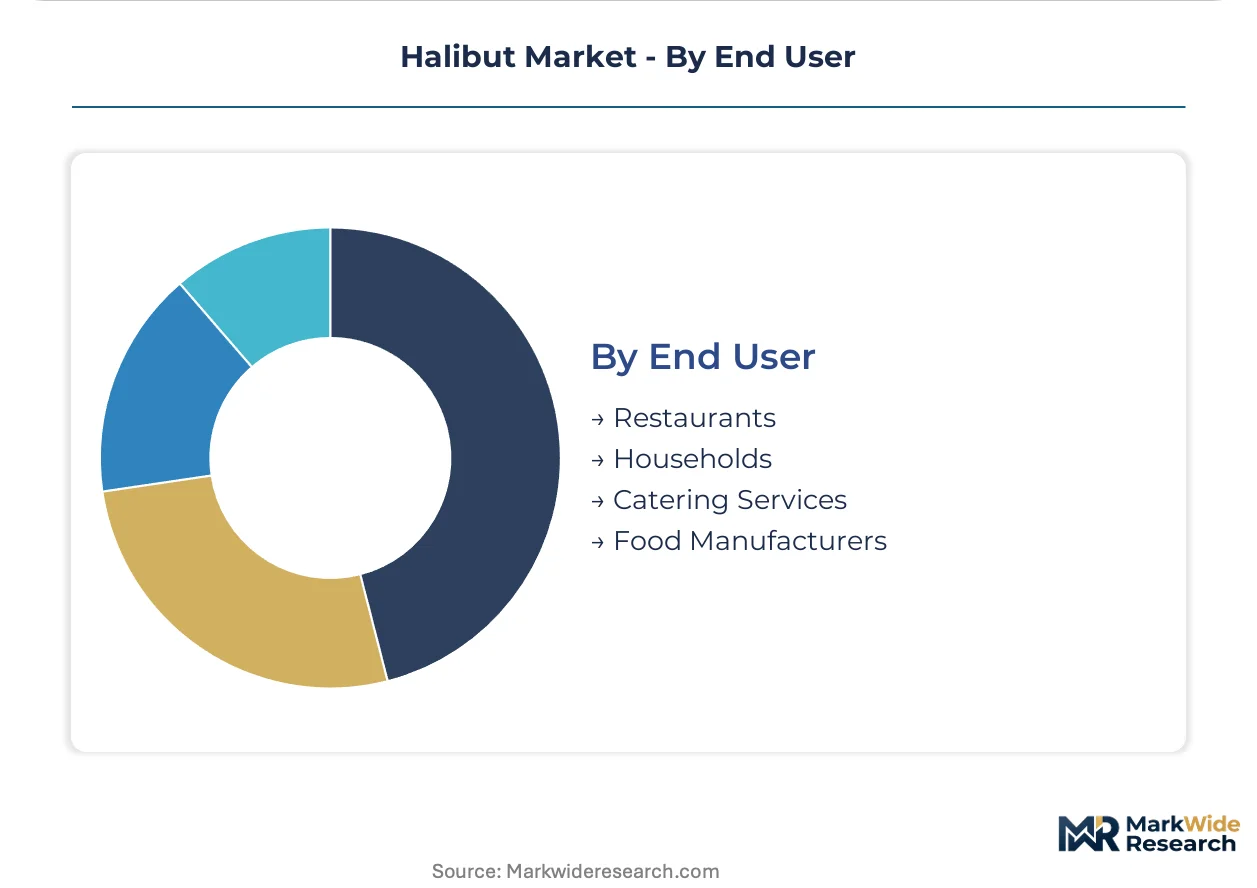
End-user requirements vary in specification stringency, from raw-bar presentation standards to processed-ingredient cost targets.
- Restaurants:Copenhagen's Noma alumni network and Oslo's Maaemo-inspired establishments specify line-caught or farm-raised provenance with 48-hour harvest-to-kitchen documentation. Whole-fish purchasing allows cheek and collar utilization in tasting menus.
- Households:German and British consumers purchase 150-200 gram skinless portions for home preparation, with sustainability credentials influencing supermarket selection. Meal-kit providers including Gousto and HelloFresh specify frozen halibut for recipe inclusion.
- Catering Services:Institutional feeding operations in Norwegian offshore oil platforms and Alaskan fishing lodges require frozen, individually quick-frozen portions with extended frozen shelf life. Cost-per-portion optimization dominates procurement criteria.
- Food Manufacturers:Ready-meal producers in the United Kingdom and Netherlands incorporate flaked halibut into premium fish pie and fishcake formulations. Consistent flake size and moisture content specifications require frozen raw material with batch uniformity.
Restaurants generate the highest margin per kilogram; food manufacturers are gaining share fastest in volume terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian aquaculture clusters supply fresh Atlantic halibut to Copenhagen and Stockholm restaurants, while Alaskan shore plants freeze Pacific halibut for German retail distribution.
Norway
Oslo's white-tablecloth restaurant groups drive demand for line-farmed Atlantic halibut with 48-hour harvest documentation. The Norwegian Food Safety Authority enforces strict veterinary certification for live egg transfers between breeding and grow-out facilities. Marine Harvest operates integrated hatchery-to-harvest sites along coastal zones from Trøndelag to Nordland.
United States
Seattle and San Francisco chefs compete for limited fresh Pacific halibut during the March-November fishing season. NOAA Fisheries administers catch limits under the Magnuson-Stevens Act, compressing landings in regulatory areas 2C and 3A. Homer, Alaska anchors wild halibut processing with shore-based plants freezing at-sea catches for domestic retail.
Canada
Toronto and Vancouver foodservice buyers source both farmed Atlantic and wild Pacific halibut for premium menu placements. Fisheries and Oceans Canada coordinates with the International Pacific Halibut Commission on quota allocations for British Columbia longline fleets. Cooke Aquaculture controls vertically integrated sites in Atlantic Canada, supplying North American broadline distributors.
Germany
Munich and Hamburg households purchase vacuum-sealed frozen portions through online seafood subscriptions and supermarket chilled cases. EFSA contaminant thresholds for heavy metals shape import screening protocols at Hamburg and Bremerhaven ports. German retailers specify Aquaculture Stewardship Council certification for fresh counter placement of Norwegian farmed product.
United Kingdom
London restaurant groups and meal-kit providers specify frozen halibut for home preparation and recipe inclusion. The UK's departure from the EU Common Fisheries Policy created separate quota negotiation frameworks for Northeast Atlantic stocks. Scottish cold-smoking facilities in the Highlands supply deli counters in London and Paris with traditional artisan production.
Halibut Market Competitive Environment
Player mix skews toward vertically integrated aquaculture operators controlling hatchery-to-harvest operations. The competitive set fragments across Norwegian farmed producers, Alaskan wild-caught processors, and North American integrated seafood groups. Three archetypes dominate: coastal aquaculture clusters with captive breeding programs, quota-holding offshore harvesters, and broadline distributors with private-label frozen programs. Capacity expansion and backward integration into egg supply represent the dominant competitive moves.
Among Norwegian-integrated producers, Marine Harvest exemplifies the coastal aquaculture archetype with controlled breeding through grow-out operations. Cooke Aquaculture occupies a position representing North American vertical integration across Atlantic Canada sites. Clearwater Seafoods anchors the quota-holder archetype for Greenland halibut, supplying sushi-grade segments through offshore holdings.
| Leading Market Players |
|---|
| Marine Harvest |
| Cooke Aquaculture |
| Stolt Sea Farm |
| Cermaq Group |
| Clearwater Seafoods |
| Fiskerikjøp AS |
| Ocean Choice International |
| High Liner Foods |
| Leader Creek Fisheries |
| Others |
Value Chain & Pricing Dynamics
Single-cell protein feed ingredient substitution is redrawing procurement geography for Norwegian Atlantic halibut producers while simultaneously compressing feed cost volatility and reshaping margin structures across farmed and wild-caught tiers.
Pricing Analysis
Blast-freezing technology pricing gaps separate at-sea frozen product from shore-based fresh fillet premiums, with RAS-grown Atlantic halibut commanding mid-tier positioning between wild Pacific scarcity and commodity frozen retail. Certification tier—Aquaculture Stewardship Council versus conventional farmed—drives price differentiation alongside harvest-to-kitchen documentation speed. Margins are tightening in frozen retail channels as German supermarket private-label programs consolidate buying power with Nordic suppliers. Foodservice buyers in Copenhagen and Oslo show lowest price sensitivity, while British meal-kit subscribers exhibit highest elasticity to portion cost increases.
Supply Chain Analysis
Forty-eight-hour cold-chain lead times constrain fresh halibut distribution radius and concentrate premium foodservice supply within Norwegian coastal zones and Icelandic landing ports. Farmed output draws from Norway, wild Pacific landings rest on Alaska, and Greenland halibut processing hinges on Nuuk shore plants. Fishmeal and fish oil from Peruvian anchovy and North Atlantic capelin represent critical input dependencies. Single-source vulnerability concentrates in Alaska's regulatory areas 2C and 3A where IPHC survey data determines annual catch limits. Distribution runs through Bergen and Aalesund auction halls shifting toward digital platforms, with vacuum-sealed formats bypassing traditional wholesale structures for German and British online retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled fish butcher scarcity in remote coastal processing centers from Homer to Nuuk is constraining yield-maximizing breakdown capacity and fragmenting margin capture across the value chain.
For Market Incumbents: Compound hatchery-to-harvest control through captive egg supply and genetic improvement programs to defend against RAS operator encroachment and feed input cost volatility. Secure veterinary certification queue priority with Norwegian Food Safety Authority to accelerate breeding cycle timelines. Deepen backward integration into single-cell protein feed ingredient partnerships with industrial biotechnology suppliers. For New Entrants and Emerging Players: Aquaculture Stewardship Council certification fast-track offers entry wedge into German supermarket fresh counter placement and British online subscription channels where sustainability credentials command price premiums. Target vacuum-sealed direct-to-consumer formats in underpenetrated British and German household segments. Pursue land-based RAS site development in temperature-controlled environments decoupled from coastal quota constraints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Norwegian coastal aquaculture clusters holding integrated breeding-through-grow-out operations but lacking feed technology partnerships. Five-to-ten year viability hinges on successful feed ingredient transition and carbon accounting compliance for EU Green Deal alignment. Monitor IPHC quota negotiation outcomes between coastal state delegations as inflection indicator for wild-caught processing capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Single-Cell Protein Feed Supply | Reduces dependency on Peruvian anchovy and North Atlantic capelin volatility for Norwegian RAS operators. |
| Land-Based RAS Capacity Expansion | Decouples Atlantic halibut production from coastal site availability and IPHC quota constraints. |
| Aquaculture Stewardship Council Certification Investment | Unlocks Albertsons, Tesco, and Coop Norge fresh counter placement for farmed Norwegian product. |
| Direct-to-Consumer Channel Development | Bypasses Bergen and Aalesund auction structures for German and British household penetration. |
| Blockchain-Enabled Provenance Tracking Deployment | Supports ESG-mandated institutional buyer requirements through batch-specific sustainability credentials. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of IPHC stock assessment reports, NOAA Fisheries catch limit documentation, EFSA contaminant threshold databases, and Norwegian Food Safety Authority veterinary certification records. Interviews with hatchery operations managers, Alaskan shore plant processing directors, Copenhagen restaurant procurement heads, German supermarket category buyers, and British meal-kit supply chain planners informed demand-side validation. Top-down market sizing triangulated against bottom-up production volume aggregation across Norwegian aquaculture clusters and Alaskan regulatory areas.
Segmentation dimensions modeled include product format, packaging type, distribution channel, and end-user specification stringency across the projection horizon. CAGRs derived from production capacity expansion trajectories, quota negotiation outcome scenarios, and channel shift elasticity parameters. Feed ingredient cost curves and cold-chain logistics cost indices served as industry-specific forecast inputs alongside chef buyer preference surveys in Scandinavian white-tablecloth segments.
Decision-makers should treat outputs as directional under assumptions of stable IPHC quota negotiation frameworks and continued EFSA heavy metal threshold enforcement; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Seafood Processing Market
Seafood
Fish Maw Market
Seafood
Fish Protein Market
Seafood
Organic Salmon Market
Seafood
Seafood Powders Market
Seafood
United States Lobster Market
Seafood
Sea Bream Market
Seafood
Surimi Market
Seafood
Edible Seaweed Market
Seafood
Europe Salmon Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
Canned Fishery Product Market
Seafood
Lobster Market
Seafood
Fish Protein Concentrate Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
COD Market