
 Trout Market | 2026-2036
Trout Market Size, Share, and Industry Trends Forecast 2026-2036
Trout Market Intelligence
The EU Green Deal is rebalancing procurement criteria across European foodservice distributors, forcing suppliers to document carbon intensity and water-use efficiency. Grieg Seafood ASA leverages its integrated Norwegian hatchery network to meet these traceability mandates. Mowi ASA sustains competitive positioning through vertically controlled smolt-to-harvest operations in Scotland and Norway. Clear Springs Foods LLC anchors North American supply with land-based raceway systems that bypass wild-catch variability.
Trout comprises cold-water salmonid species farmed or caught for human consumption, typically exhibiting pink to orange flesh coloration from astaxanthin-rich feed formulations and protein content exceeding eighteen percent. The fish serves protein needs across retail, foodservice, and export channels where freshness and origin verification command price premiums. Freshwater trout dominates volume flows through restaurants and fishmongers seeking whole-gill-intact product for display-counter appeal. Smoked trout captures margin concentration in European retail, where vacuum-sealed packs extend shelf life and support premium positioning. Frozen trout occupies cost-sensitive export corridors, particularly where distributors serve landlocked markets with limited fresh supply access.
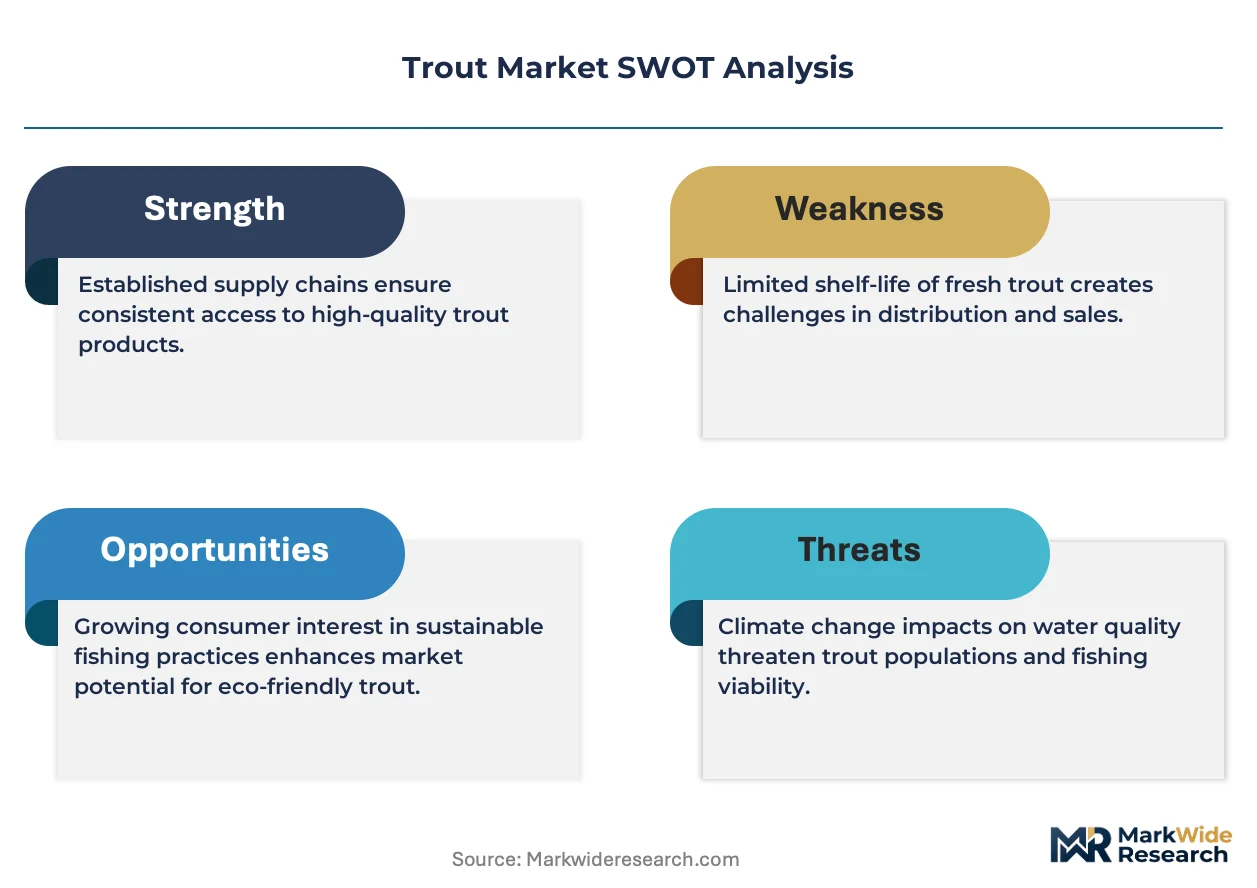
The EU Green Deal and REACH frameworks govern chemical inputs in European aquaculture, while the FDA and USDA co-regulate food safety and labeling in the United States, creating divergent compliance burdens for cross-border suppliers. Norway's national seafood regulator enforces strict sea-lice thresholds and escape-prevention standards that shape farm-site licensing and production capacity. Stakeholders must monitor evolving antibiotic-use restrictions and alternative-feed ingredient approvals, as these regulatory pivots will determine which production systems retain market access and which face stranded capacity.
Market Dynamics
EU Green Deal carbon-intensity mandates are restructuring procurement criteria across European foodservice distributors, forcing suppliers to document water-use efficiency and origin traceability or forfeit contract eligibility.
Growth Catalysts
- EU Green Deal certification requirements:Foodservice distributors in Germany and France now require documented carbon footprints for farmed seafood, creating competitive advantage for compliant Norwegian suppliers.
- White-tablecloth restaurant traceability demands:Chefs in premium dining segments prioritize domestically sourced protein with verifiable hatchery-to-harvest documentation.
- Norwegian fjord cold-chain infrastructure:Integrated live-harvest export systems enable same-day air freight to continental European markets.
Market Restraints
- Astaxanthin feed additive cost volatility:Synthetic carotenoid prices fluctuate with petrochemical feedstock markets, compressing margins for non-integrated farmers.
- Sea-lice treatment concentration:Norway's national seafood regulator enforces strict infestation thresholds that limit production density at licensed farm sites.
- Plant-based seafood substitution:Pea-protein and algae-based alternatives capture price-sensitive retail segments in Northern European supermarkets.
Strategic Opportunities
- Land-based recirculating aquaculture systems:RAS technology enables production in water-stressed regions of Spain and Italy without fjord access.
- EU Green Deal sustainable aquaculture benchmarks:Early certification under tightening import standards secures preferential access to Dutch and Belgian distribution hubs.
- Smoked trout vacuum-packaging innovation:Extended shelf-life formats penetrate convenience retail channels in urban UK markets.
Industry Challenges
- Sea-lice monitoring technician shortage:Specialized marine parasitology skills command wage premiums in Scottish and Norwegian production zones.
- REACH framework chemical approval timelines:Alternative feed ingredient registrations face multi-year ECHA evaluation periods that delay formulation changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trout Market |
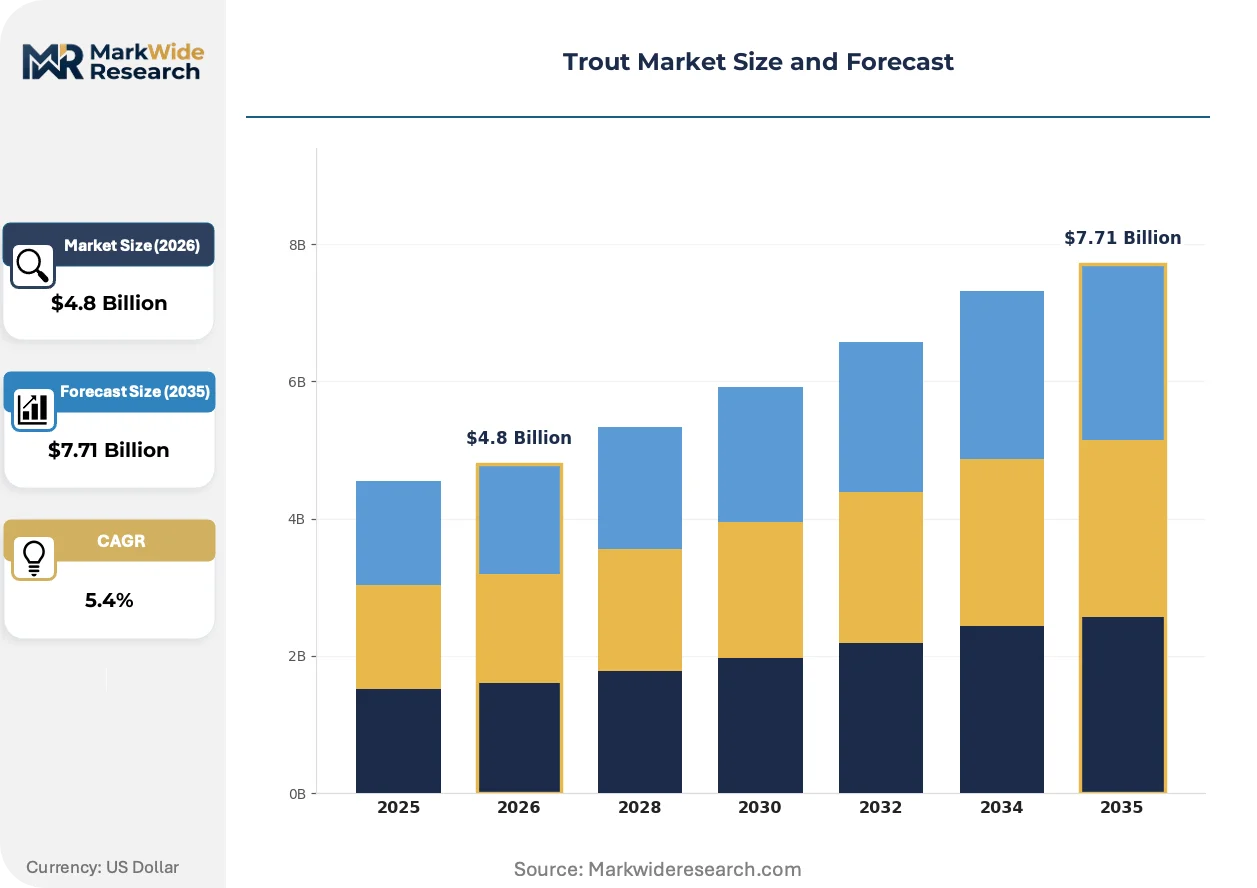
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freshwater Trout, Smoked Trout, Frozen Trout, Dried Trout End User: Restaurants, Retailers, Fishmongers, Exporters Distribution Channel: Online, Direct Sales, Distributors, Wholesale Packaging Type: Vacuum-Sealed Packs, Cans, Bulk Boxes, Fillets |
| Companies Covered | Grieg Seafood ASA, Pacific Seafood Group, Marine Harvest, Riverence, Clear Springs Foods LLC, Mowi ASA, Cooke Aquaculture Inc., AquaMaof, Cermaq Group AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trout Market Strategic Shifts & Innovations
Production technology and regulatory compliance systems are converging to reshape competitive advantage in trout aquaculture, with traceability infrastructure and alternative feed formulations commanding disproportionate investment flows.
Single-cell protein derived from microbial fermentation is expanding into salmonid feed formulations as a fishmeal replacement. Norwegian hatchery operators are adopting bacterial biomass at pilot scale to reduce wild-catch dependency. This ingredient shift is expanding into premium pricing tiers as carbon footprint verification becomes a procurement filter for German retail chains.
REACH framework amendments governing chemical inputs in European aquaculture are tightening residue monitoring protocols. ECHA evaluation timelines for novel feed additives now extend eighteen to thirty-six months, forcing producers to lock formulations earlier in product development cycles. Smoked trout processors in Denmark and Poland face the steepest compliance costs due to multi-site supply aggregation requirements.
Chef-direct sourcing contracts are displacing traditional wholesale auction systems in premium foodservice segments. Copenhagen and Stockholm restaurants now contract directly with designated Norwegian farm sites for named-parcel delivery. This channel restructuring concentrates volume with vertically integrated suppliers capable of batch-level documentation.
Trout Market Segmentation
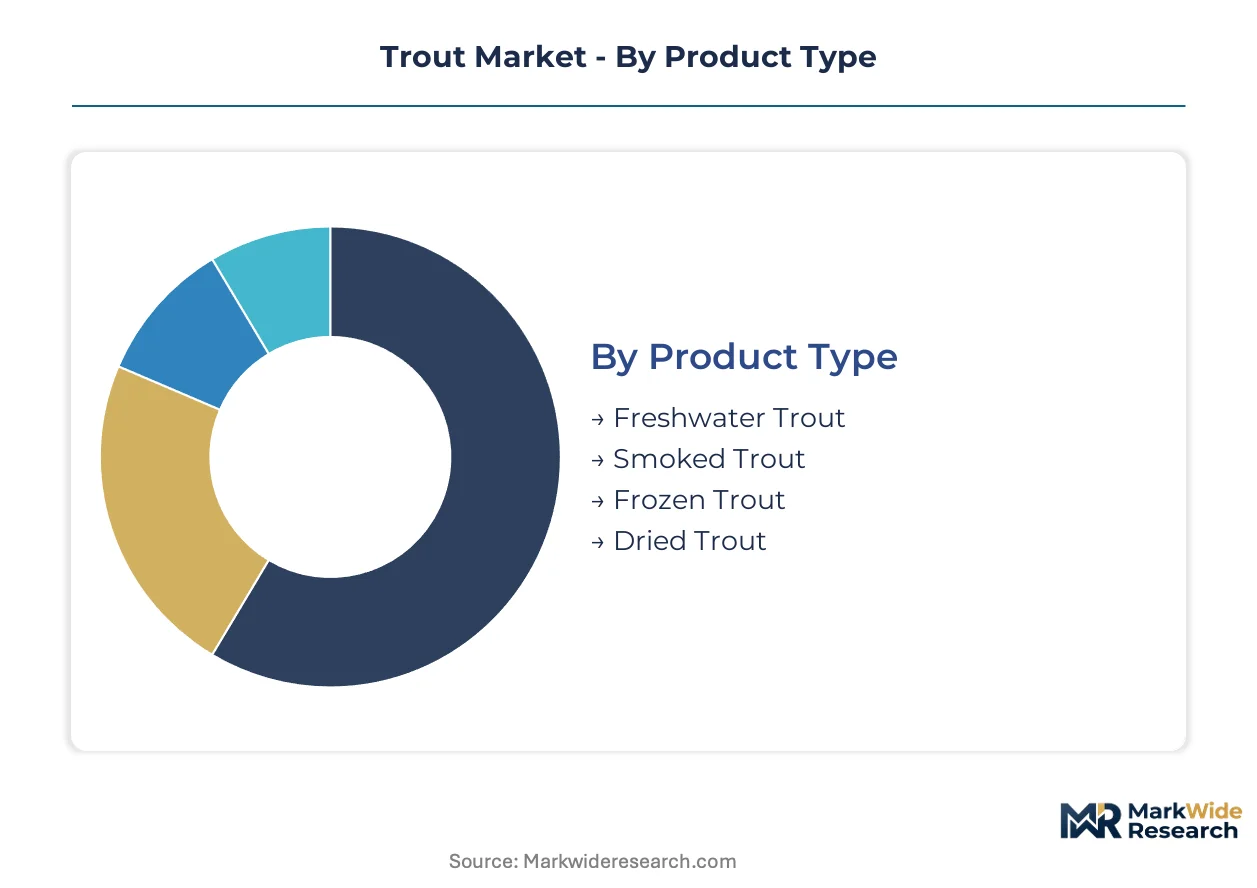
Trout market segmentation reveals how product form, buyer type, and logistics infrastructure interact to determine margin capture. Each dimension carries distinct certification burdens and cold-chain requirements that reshape supplier competitive position.
Product Type:
Standardization dominates commodity-grade frozen formats while customization concentrates in fresh and smoked tiers where origin documentation commands price premiums.
- Freshwater Trout:Whole-gill-intact specimens with pink-to-orange flesh coloration from astaxanthin feed formulations. Norwegian fjord-based clusters supply white-tablecloth restaurants in Germany and France through same-day air freight corridors where traceability mandates from the EU Green Deal filter procurement eligibility.
- Smoked Trout:Vacuum-sealed packs with extended shelf life through controlled wood-smoke processing. Danish and Polish processors capture margin concentration in UK convenience retail where urban consumers prioritize grab-and-go protein formats.
- Frozen Trout:Blast-frozen fillets for cost-sensitive export corridors serving landlocked Central European markets.
- Dried Trout:Dehydrated strips for specialty snack applications in East Asian import channels.
Most installed capacity flows through Freshwater Trout. Expansion is steepest in Smoked Trout.
End User:
Volume scale concentrates with large-format buyers while margin accrues to relationship-driven channels requiring batch-level documentation.
- Restaurants:Premium dining segments in Copenhagen and Stockholm contract directly with designated Norwegian farm sites for named-parcel delivery with verifiable hatchery-to-harvest documentation.
- Retailers:German supermarket chains now require carbon footprint verification for farmed seafood, filtering supplier pools toward integrated Norwegian operators.
- Fishmongers:Display-counter appeal drives demand for whole-gill-intact product with origin labeling for consumer transparency.
- Exporters:Aggregators serving Middle Eastern and Southeast Asian markets prioritize frozen formats with extended logistics windows.
Restaurants absorb the highest share of premium-grade volume. Retailers are expanding most quickly as certification requirements consolidate procurement.
Distribution Channel:
Control over documentation and temperature integrity separates direct and integrated channels from arm's-length wholesale systems.
- Online:E-commerce platforms serving UK and Dutch urban consumers with subscription-based fresh delivery and origin-verified batch tracking.
- Direct Sales:Chef-direct contracts displacing traditional wholesale auctions in Scandinavian premium foodservice.
- Distributors:European foodservice distributors in Belgium and the Netherlands apply EU Green Deal procurement filters that exclude non-compliant suppliers.
- Wholesale:Cost-driven aggregation for frozen trout moving through Rotterdam and Hamburg port hubs.
Distributors handle the majority of licensed farm output. Online channels are climbing the fastest as urban delivery infrastructure matures.
Packaging Type:
Shelf-life extension and presentation format determine channel access and margin tier.
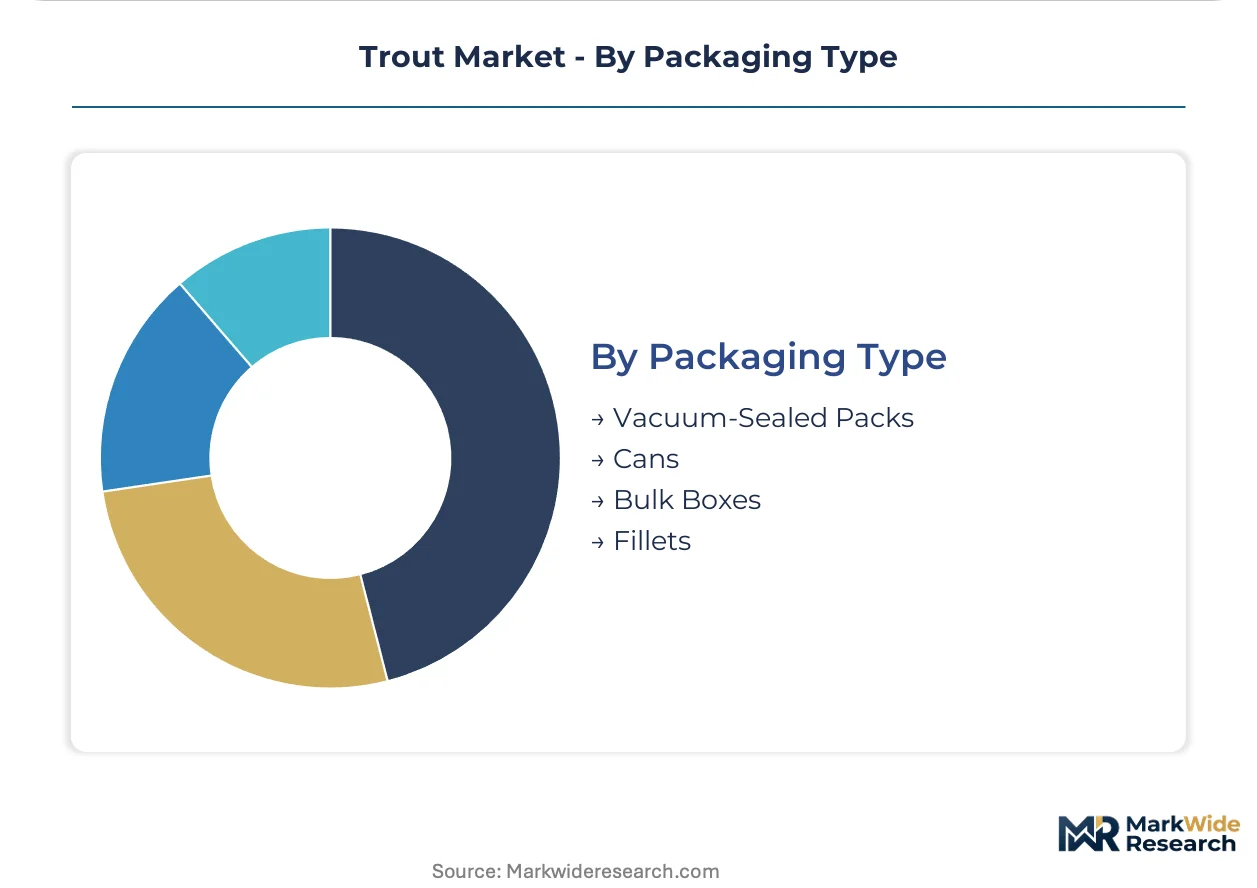
- Vacuum-Sealed Packs:Modified-atmosphere packaging for smoked trout extending retail shelf life while preserving texture integrity for European supermarket placement.
- Cans:Thermally processed formats for emergency foodservice inventory and export markets with limited cold-chain reliability.
- Bulk Boxes:Industrial-scale frozen shipments for processor input and institutional catering contracts.
- Fillets:Portion-controlled fresh cuts for restaurant back-of-house efficiency with minimal preparation labor.
Bulk Boxes move the largest physical volume. Vacuum-Sealed Packs are gaining share fastest as retail convenience formats expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trout aquaculture originated in medieval European monastic ponds before industrializing in 19th-century Denmark and Germany. Modern production now clusters around fjord systems, alpine lake districts, and integrated cold-chain corridors that enable live-harvest air freight to premium foodservice markets.
Norway
White-tablecloth restaurants in Copenhagen and Stockholm source directly from designated Hardangerfjord farm sites with batch-level traceability. The Norwegian Food Safety Authority enforces strict sea-lice thresholds and escape-prevention standards that shape licensing density. Bergen-based export processors coordinate same-day air freight to continental European markets through integrated cold-chain infrastructure.
Scotland
Chef-direct contracts from Edinburgh and Glasgow premium dining segments prioritize hatchery-to-harvest documentation for whole-gill-intact specimens. The UK's Animal and Plant Health Agency regulates chemical inputs and residue monitoring under retained EU REACH frameworks. Loch Lomond and the Trossachs production zones concentrate smolt-to-harvest operations serving domestic foodservice and export channels.
United States
Land-based raceway systems in Idaho and Pennsylvania bypass wild-catch variability to supply retail and restaurant segments with consistent volume. The FDA and USDA co-regulate food safety, labeling, and feed additive approvals, creating compliance burdens for imported product. Hagerman Valley operations anchor North American freshwater trout supply with integrated hatchery networks.
Denmark
Smoked trout vacuum-packaging innovation penetrates UK convenience retail through controlled wood-smoke processing in Danish facilities. The Danish Veterinary and Food Administration enforces EU Green Deal carbon-intensity documentation requirements for farmed seafood exports. Billund and Jutland processing clusters aggregate supply from Norwegian and Scottish farm sites for extended shelf-life formats.
Poland
Cost-sensitive frozen trout fillets serve landlocked Central European markets through blast-freezing capacity near Gdańsk port corridors. The country's national veterinary inspectorate aligns with EFSA residue monitoring protocols for aquaculture products. Masovian Voivodeship distribution hubs consolidate volume for re-export to German supermarket chains requiring carbon footprint verification.
Trout Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification and traceability vectors, with integrated Norwegian operators capturing foodservice premiums while non-integrated farmers face feed cost volatility. Market structure tilts toward consolidation among vertically controlled smolt-to-harvest specialists and land-based raceway operators with captive supply chains. Three archetypes dominate: fjord-based integrated producers, land-based recirculating system specialists, and multi-site smoked trout processors. Competitive moves concentrate on geographic expansion into water-stressed Southern European markets and strategic partnerships for alternative feed ingredient sourcing.
Among Norwegian-integrated operators, Grieg Seafood ASA and Mowi ASA exemplify the premium-tier archetype through controlled hatchery networks and direct chef contracts. Clear Springs Foods LLC anchors the land-based specialist position with raceway production bypassing wild-catch dependency. These three occupy positions that reflect the industry's divergence between traceability-verified premium supply and cost-optimized commodity flows.
| Leading Market Players |
|---|
| Grieg Seafood ASA |
| Pacific Seafood Group |
| Marine Harvest |
| Riverence |
| Clear Springs Foods LLC |
| Mowi ASA |
| Cooke Aquaculture Inc. |
| AquaMaof |
| Cermaq Group AS |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EU Green Deal-compliant Norwegian fjord production and non-certified commodity flows manifests in both pricing power and supply chain configuration. Premium foodservice buyers in Copenhagen and Stockholm pay substantial markups for batch-level traceability, while frozen export corridors compete on astaxanthin feed formulation costs and cold-chain efficiency.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs trout market transactions. Premium tiers capture margin through EU Green Deal carbon-intensity certification and chef-direct hatchery-to-harvest documentation, while economy tiers compete on blast-frozen fillet volumes for Central European supermarket chains. Pricing pressure stems from synthetic astaxanthin feed additive volatility tied to petrochemical feedstock markets, compressing margins for non-integrated farmers. Retailers in Germany demonstrate highest price sensitivity due to carbon footprint verification mandates filtering supplier pools, whereas white-tablecloth restaurants in Scandinavia show lowest sensitivity given traceability requirements.
Supply Chain Analysis
Certification gating through EU Green Deal benchmarks and REACH framework residue protocols shapes supplier eligibility across European distribution channels. Production concentrates in Norway, Scotland, and Denmark, with Norwegian fjord-based clusters supplying live-harvest air freight corridors and Danish processors aggregating for smoked vacuum-pack formats. Raw material dependencies include synthetic astaxanthin carotenoids, fishmeal alternatives, and microbial fermentation-derived single-cell proteins. Supply chain risk centers on ECHA evaluation timelines for novel feed additives creating formulation lock-in periods. Distribution runs through integrated cold-chain systems for fresh product and Rotterdam-Hamburg port hubs for frozen consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trout aquaculture represents a late-cycle quality story where foodservice procurement shifts toward verifiable origin documentation and carbon-intensity certification separate premium capture from commodity margin erosion. This demand pivot rewards integrated operators with hatchery-to-harvest control while stranding non-compliant capacity.
For Market Incumbents: Acquire land-based recirculating aquaculture system technology to secure production access in water-stressed Southern European markets beyond fjord geography. Consolidate backward integration into alternative feed ingredient supply through partnerships with microbial fermentation operators, reducing exposure to synthetic astaxanthin price volatility and ECHA approval delays. Defensive positioning requires early REACH framework compliance investment before residue monitoring protocols tighten further. For New Entrants and Emerging Players: Enter via chef-direct sourcing contracts in premium Scandinavian foodservice segments where incumbent wholesalers lack batch-level documentation capability. Target Spanish and Italian urban markets with RAS-based freshwater production, bypassing Norwegian supply concentration and EU Green Deal import certification barriers for non-EU origin. Go-to-market leverage rests on subscription-based fresh delivery platforms with integrated origin-verified batch tracking for UK and Dutch urban consumers. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically controlled smolt-to-harvest specialists possessing captive hatchery networks and direct restaurant relationships. Long-term viability over the projection horizon favors operators with demonstrated REACH compliance and alternative feed formulation pipelines. Monitor ECHA approval velocity for microbial fermentation-derived proteins as the critical inflection signal distinguishing premium-tier feed cost structures from commodity exposure.| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Certification Investment | Early compliance secures preferential access to Dutch and Belgian distribution hubs before mandates tighten. |
| Land-Based RAS Capacity Expansion | Production in Spain and Italy bypasses fjord geography constraints and Norwegian regulatory density limits. |
| Alternative Feed Ingredient Partnership | Microbial fermentation biomass reduces wild-catch dependency and satisfies German retail carbon footprint filters. |
| Chef-Direct Channel Development | Named-parcel contracts with Copenhagen and Stockholm restaurants displace traditional wholesale auction systems. |
| Smoked Trout Packaging Innovation | Vacuum-sealed extended shelf-life formats penetrate UK convenience retail with grab-and-go protein positioning. |
Research Approach
Direct dialogue with aquaculture farm managers, European foodservice procurement directors, smoked trout processing facility operators, and regulatory affairs specialists at national seafood authorities grounded this analysis. Secondary validation drew from EU Green Deal implementation documents, ECHA chemical registration databases, Norwegian Food Safety Authority sea-lice threshold reports, and customs trade data for salmonid exports. Bottom-up farm-site capacity assessments combined with top-down foodservice distributor volume estimates through cross-referencing across the analysis window.
Segment-level value and volume outputs emerged from modeling across product form tiers, buyer type categories, distribution channel structures, and regional regulatory clusters. CAGRs were derived through regression analysis of historical production volumes against certification adoption curves and feed cost trajectories. Industry-specific forecast inputs incorporated EU Green Deal procurement mandate rollout schedules and ECHA evaluation timeline patterns for novel aquaculture inputs.
Inputs from hatchery operators and foodservice distributors were available through the study window; gaps in real-time sea-lice treatment cost data and alternative feed ingredient pilot-scale performance metrics introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding REACH framework amendment implementation velocity and chef-direct contract penetration rates. A model refresh is warranted upon material change in ECHA approval timelines for microbial fermentation-derived proteins or EU Green Deal carbon-intensity threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Canned Tuna Market
Seafood
Food Clamshells Market
Seafood
Caviar Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
United States Lobster Market
Seafood
Organic Seafood Market
Seafood
Processed Seafood Market
Seafood
Fish Fermentation Market
Seafood
Fish Nutrition Market
Seafood
China Crustaceans Market
Seafood
Fish Meal Market
Seafood
Seafood Processing Market
Seafood
Toothfish Market
Seafood
Asian Sea Bass Market
Seafood
Seafood Flavors Market
Seafood
Salmon Fish Market