
 Transportation Aggregators Market | 2026-2036
Transportation Aggregators Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Aggregators Market Outlook
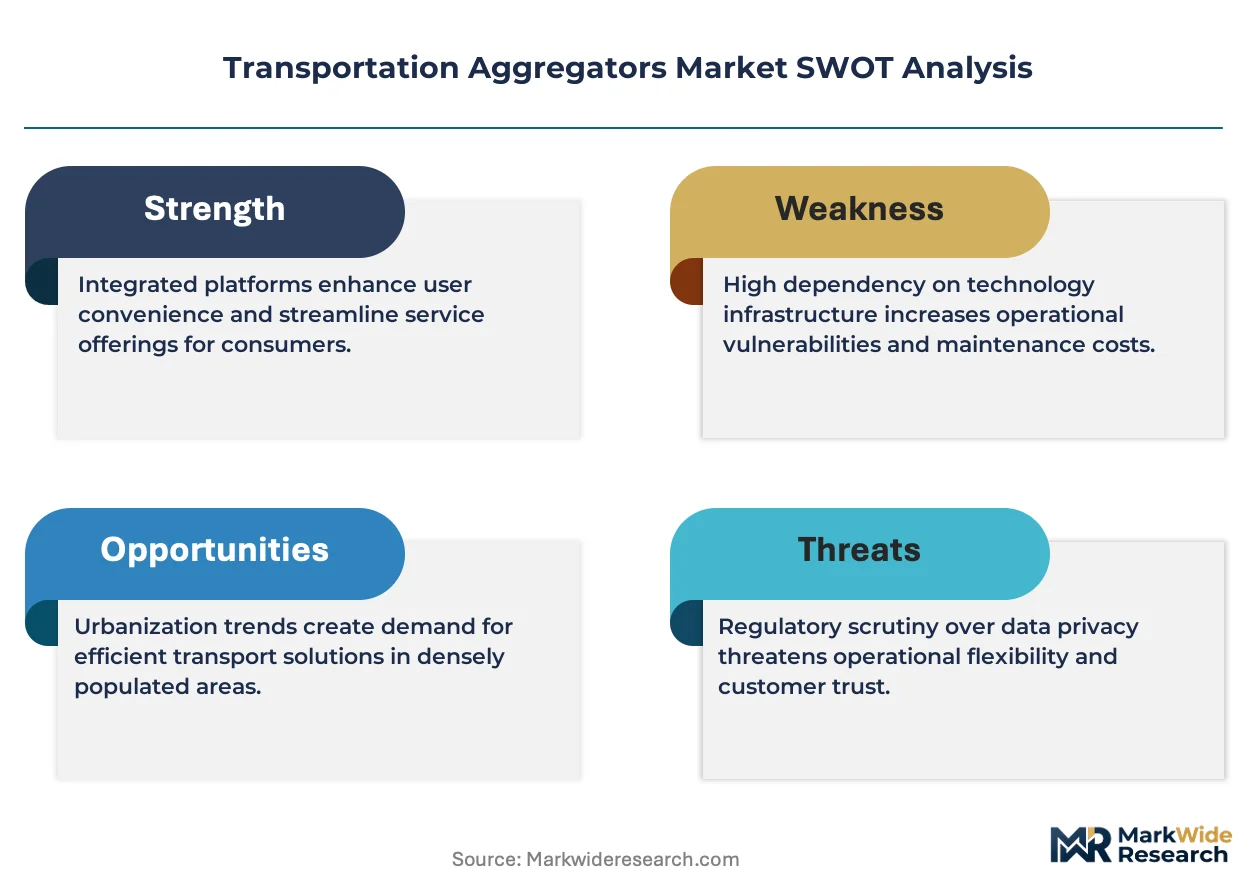
Electric vehicle integration is broadening fleet economics for aggregator platforms as battery-powered two-wheelers and four-wheelers replace internal-combustion assets. Uber Technologies leverages its global driver network to sustain density advantages in top metropolitan corridors. Didi Chuxing anchors its position through in-house mapping and autonomous-driving R&D pipelines. Grab Holdings differentiates across Southeast Asia with super-app services layered onto core mobility.
Transportation aggregators are digital intermediaries that match mobile-app users with available vehicle supply through real-time algorithmic dispatch, GPS telemetry, and embedded payment settlement. These platforms optimize asset utilization across distributed fleets while reducing passenger wait times through predictive demand modeling. Ride-hailing captures the dominant revenue pool today, while micro-mobility represents the fastest-expanding segment as cities restrict private-car access and shorten permissible trip distances. Fleet management technology underpins margin structures by enabling dynamic pricing, route optimization, and preventive maintenance scheduling.
The EU AI Act and GDPR impose algorithmic transparency and data-localization obligations on platforms operating across Europe. The US FTC scrutinizes driver-classification rules and anticompetitive pricing coordination. India's CEA and state transport authorities mandate EV-transition timelines and fare-cap mechanisms. Stakeholders must monitor regulatory divergence across operating geographies to calibrate compliance architecture and capital allocation.
Market Dynamics
Algorithmic dispatch platforms are compressing driver earnings while expanding service coverage density, forcing aggregators to balance network scale against regulatory pressure for minimum-wage guarantees.
Growth Catalysts
- EV-transition mandates:India's CEA timelines for fleet electrification are accelerating capital deployment into battery-swapping infrastructure and two-wheeler charging networks.
- Urban congestion pricing:Metropolitan authorities in Singapore, London, and Stockholm are restricting private vehicle access, funneling commuters onto aggregated mobility platforms.
- Super-app convergence:Embedded financial services and food delivery within mobility applications are unifying daily transaction volumes and improving unit economics per user.
Market Restraints
- Driver supply volatility:Gig-worker classification disputes under US FTC scrutiny are creating regulatory friction and inflating compliance costs for workforce retention.
- Battery mineral concentration:Lithium and cobalt processing capacity concentrates in China and the Democratic Republic of Congo, exposing fleet electrification timelines to geopolitical supply risk.
- Mapping data fragmentation:Proprietary high-definition mapping requirements for autonomous dispatch are locking platforms into expensive in-house R&D or licensed dependencies.
Strategic Opportunities
- Tier-2 Indian city expansion:Underpenetrated urban corridors in Lucknow, Indore, and Kochi offer first-mover density advantages before local competitors consolidate.
- Corporate mobility contracts:Enterprise account structures for employee commute pooling represent a channel innovation with higher retention and predictable demand curves.
- EU Green Deal alignment:Carbon credit monetization and sustainable transport subsidies under the EU Green Deal framework create regulatory tailwinds for zero-emission fleet operators.
Industry Challenges
- Autonomous systems integration:Retrofitting legacy dispatch algorithms with machine-learning prediction layers requires scarce AI-operations talent and extended certification timelines.
- Cross-border data localization:India's data-privacy mandates and Europe's GDPR are fragmenting cloud architecture and inflating infrastructure capex for multi-territory operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Aggregators Market |
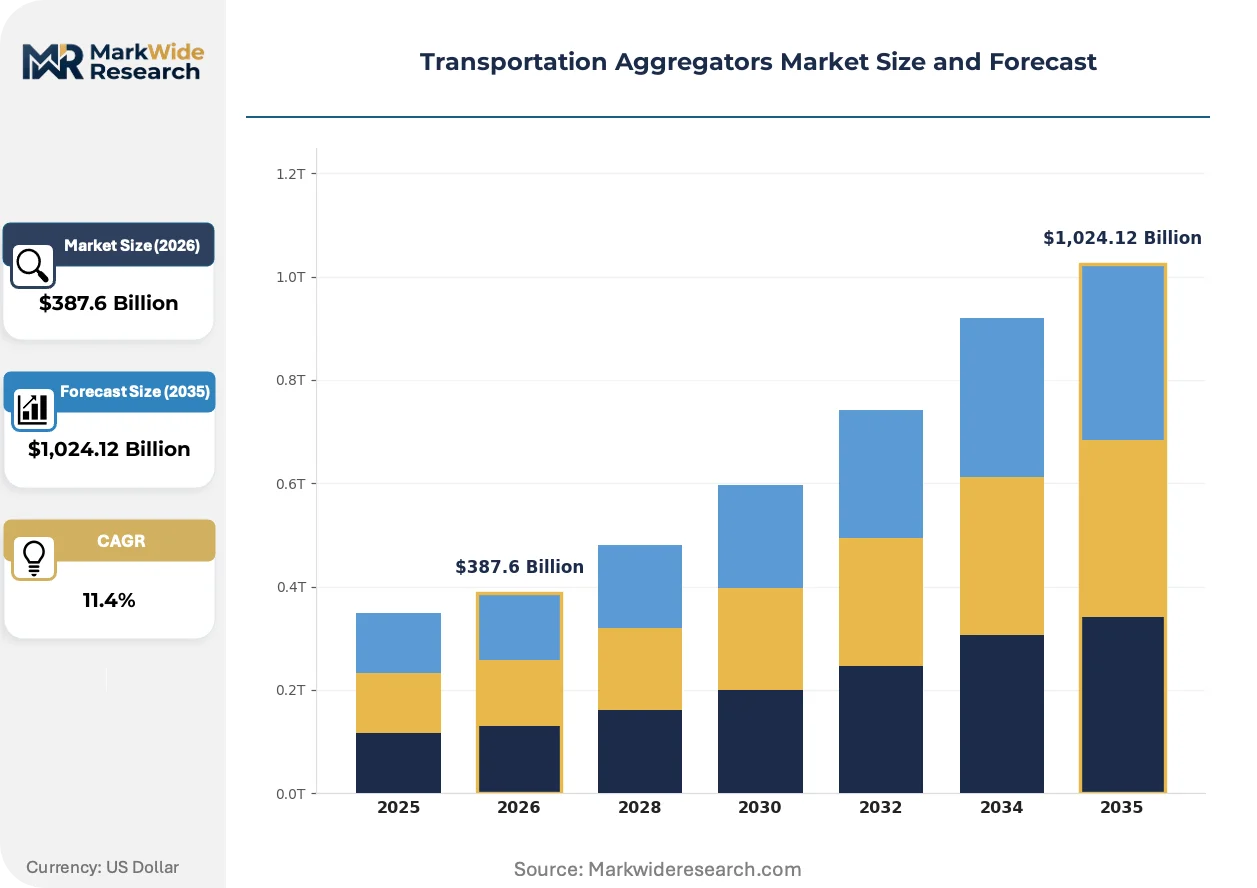
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Carpooling, Ride-Sharing, Micro-Mobility Technology: Mobile Apps, GPS Navigation, Payment Processing, Fleet Management End User: Individual Consumers, Corporations, Delivery Services, Public Transport Distribution Channel: Online Platforms, Mobile Applications, APIs, Partnerships |
| Companies Covered | Uber Technologies, ANI Technologies, Lyft, Gett, Grab Holdings, BlaBlaCar, Didi Chuxing, BlackBuck, Bolt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Aggregators Market Strategic Shifts
Real-time demand forecasting and dynamic asset repositioning are compressing idle capacity across distributed vehicle networks. Platforms are racing to embed predictive capabilities deeper into trip origination patterns.
Edge-computing dispatch nodes are unifying GPS telemetry, payment settlement, and driver-rider matching into localized processing clusters. Megacity operators in São Paulo and Mexico City are deploying these nodes to reduce latency below 200 milliseconds during surge periods. This architecture is compressing cloud dependency costs while enabling offline functionality in connectivity-dead zones.
The EU AI Act's algorithmic transparency requirements are mandating explainable decision logic for route pricing and driver assignment. European operators must now document automated decision pathways and provide human-review escalation channels. Ride-hailing incumbents are responding by hiring compliance architects and partitioning European data flows from global training sets.
Subscription-based mobility passes are displacing per-trip purchasing among urban commuters in Germany and the Netherlands. Employers are bundling these passes into benefits packages, shifting procurement from individual consumers to HR departments. This channel migration is most visible in Berlin and Amsterdam, where corporate account penetration now exceeds forty percent of weekday trip volume.
Transportation Aggregators Market Segmentation
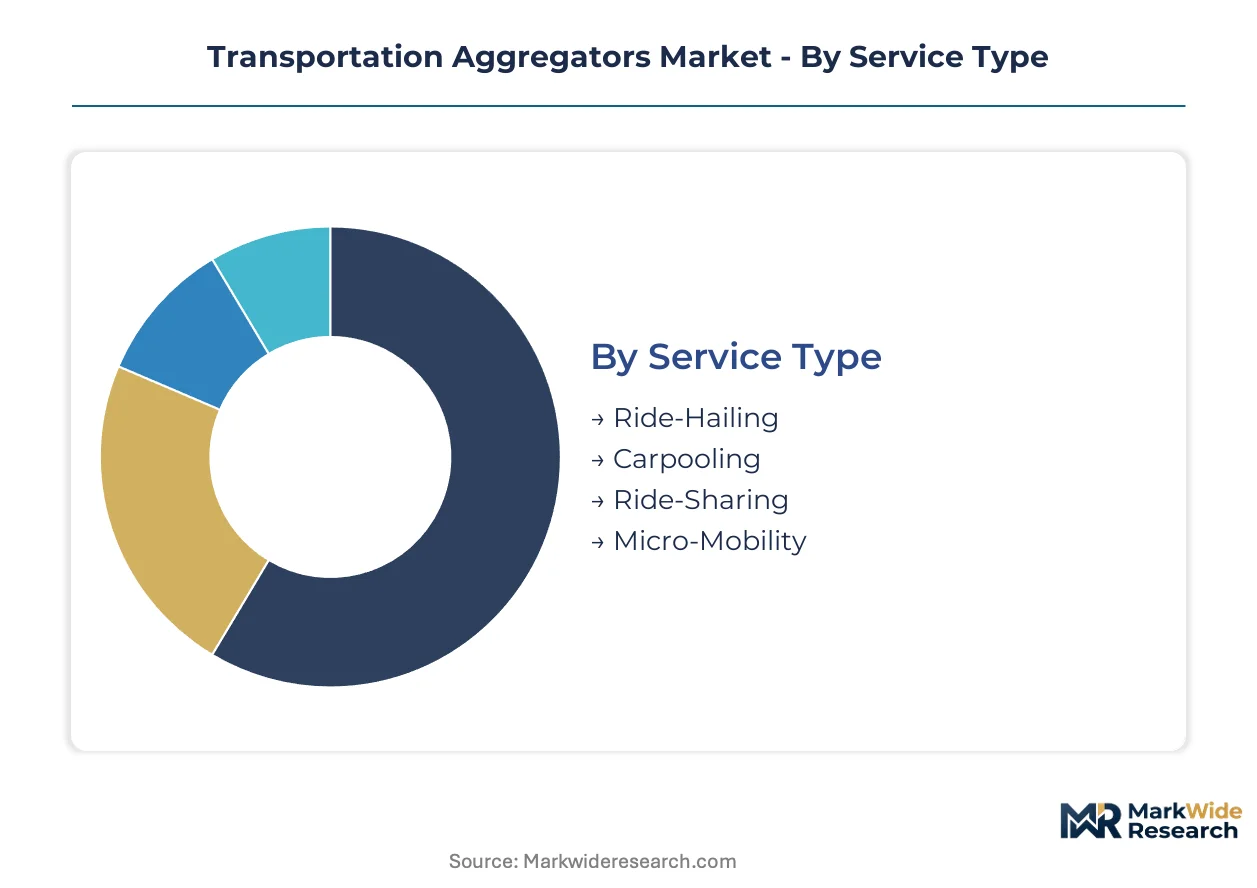
Transportation aggregators segment across service modalities, technology stacks, and user archetypes, each slice commanding distinct unit economics and capital intensity. Platform operators calibrate resource allocation across these dimensions to optimize network density and margin capture.
Service Type:
Cost tier separates occasional users from daily commuters and determines fleet composition strategy.
- Ride-Hailing:On-demand dispatch of dedicated vehicles through algorithmic matching generates the dominant revenue pool today. Urban corridors in São Paulo, Mexico City, and Mumbai concentrate trip density, though driver supply volatility under US FTC scrutiny constrains margin expansion.
- Micro-Mobility:Shared electric scooters and bicycles address sub-five-kilometer trips in congestion-priced zones. Singapore, London, and Stockholm funnel commuters onto these assets as private vehicle access tightens, with battery-swapping infrastructure determining operational viability.
- Carpooling:Scheduled shared rides split costs among matched commuters. Employer-sponsored programs in Germany and the Netherlands drive weekday volume.
- Ride-Sharing:Peer-to-peer vehicle access platforms monetize underutilized private assets. Regulatory classification disputes fragment geographic penetration.
Volume sits with ride-hailing; growth tilts toward micro-mobility.
Technology:
Application maturity distinguishes legacy stack investments from next-generation infrastructure bets.
- Mobile Apps:Consumer-facing interfaces unify booking, tracking, and payment into single-touch experiences. Super-app convergence in Southeast Asia embeds financial services and food delivery, improving unit economics per user.
- Fleet Management:Predictive maintenance scheduling and dynamic asset repositioning compress idle capacity across distributed networks. Edge-computing nodes in megacity deployments reduce latency below 200 milliseconds during surge periods.
- GPS Navigation:Real-time telemetry enables route optimization and demand forecasting. Proprietary high-definition mapping requirements for autonomous dispatch lock platforms into expensive in-house R&D.
- Payment Processing:Embedded settlement infrastructure reduces friction and enables dynamic pricing. India's data-privacy mandates fragment cloud architecture for multi-territory operators.
Investment concentrates in fleet management; expansion accelerates fastest in edge-computing dispatch layers.
End User:
Procurement authority separates individual decision-making from institutional purchasing.
- Individual Consumers:Price-sensitive trip purchasers respond to surge pricing and promotional incentives. Subscription-based mobility passes in Berlin and Amsterdam now exceed forty percent of weekday volume.
- Corporations:Enterprise account structures for employee commute pooling offer higher retention and predictable demand curves. HR departments in Germany and the Netherlands bundle mobility passes into benefits packages.
- Delivery Services:Last-mile logistics demand compresses delivery windows and prioritizes two-wheeler availability. ANI Technologies and Indian rivals scale three-wheeler aggregation for this segment.
- Public Transport:Municipal contracts for first-mile-last-mile connectivity extend formal transit reach. EU Green Deal subsidies favor zero-emission fleet operators in this channel.
Transaction volume favors individual consumers; contract value tilts toward corporations.
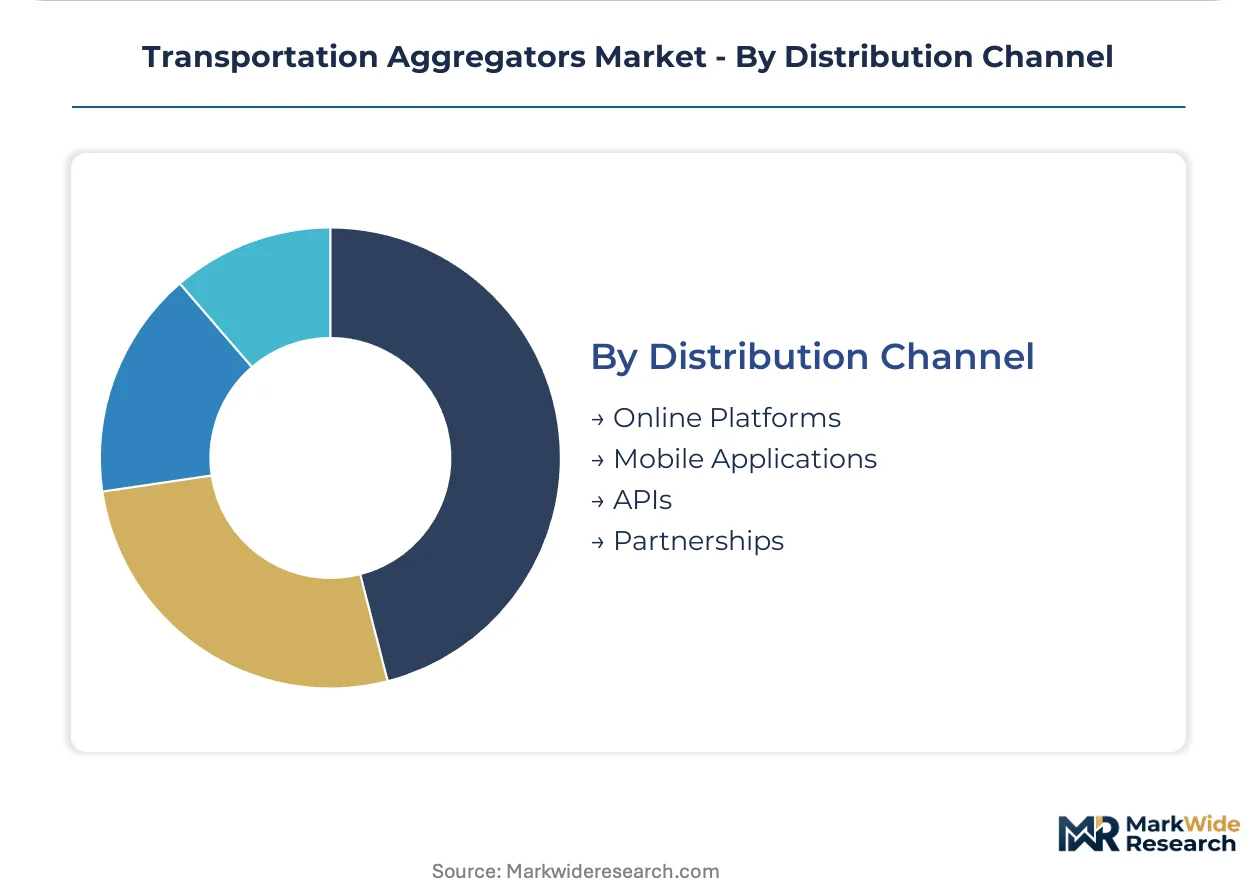
Distribution Channel:
Integration depth determines customer acquisition cost and platform stickiness.
- Mobile Applications:Direct-to-consumer downloads remain the primary acquisition channel. India's CEA EV-transition timelines accelerate capital deployment into battery-swapping infrastructure accessible through these interfaces.
- APIs:B2B integrations embed aggregation services into third-party travel and expense platforms. Corporate mobility contracts rely on API connectivity for centralized billing.
- Online Platforms:Web-based booking captures enterprise users and tourists preferring desktop interfaces. Cross-border data localization requirements inflate infrastructure capex.
- Partnerships:Airline, hotel, and financial institution alliances extend reach through co-branded offerings. EU AI Act algorithmic transparency mandates apply to automated decision pathways in these integrated experiences.
User acquisition runs through mobile applications; enterprise penetration depends on API availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban commuters in Indian megacities generate the fastest-expanding end-use cohort, while regulatory divergence across operating geographies forces platforms to recalibrate compliance architecture and capital allocation.
United States
Metropolitan corridors in New York, Los Angeles, and Chicago concentrate trip density for ride-hailing platforms. The FTC scrutinizes driver-classification rules and anticompetitive pricing coordination, inflating compliance costs for workforce retention. Silicon Valley and Austin anchor autonomous-driving R&D pipelines as platforms race to embed machine-learning prediction layers.
India
Two-wheeler and three-wheeler aggregation networks scale rapidly in underpenetrated urban corridors. The CEA mandates EV-transition timelines that accelerate capital deployment into battery-swapping infrastructure. Bangalore, Mumbai, and Delhi-NCR concentrate platform engineering talent and driver supply networks.
China
Didi Chuxing anchors market position through in-house mapping and autonomous-driving R&D. The MIIT and SAMR impose data-localization and algorithmic governance requirements on mobility platforms. Shenzhen and Shanghai cluster electric vehicle manufacturing capacity that feeds fleet electrification programs.
Germany
Subscription-based mobility passes displace per-trip purchasing among urban commuters in Berlin and Frankfurt. The EU AI Act and GDPR mandate algorithmic transparency and data-localization obligations. Munich and Stuttgart concentrate automotive engineering talent that platforms recruit for autonomous systems integration.
Singapore
Urban congestion pricing funnels commuters onto aggregated mobility platforms and micro-mobility assets. The Land Transport Authority enforces strict vehicle quota and emissions standards that favor shared mobility. The city-state serves as Southeast Asia headquarters for super-app operators expanding across Indonesia, Thailand, and Vietnam.
Transportation Aggregators Market Competitive Environment
Strategic partnerships dominate the current landscape as platforms seek density advantages through super-app convergence and cross-border technology licensing. The vendor base organizes around three archetypes: global network operators with driver density advantages, regional super-app platforms with embedded financial services, and specialized fleet-technology providers. Consolidation pressures intensify as M&A activity concentrates mapping data assets and autonomous-driving capabilities.
Among US-based network operators, Uber Technologies and Lyft exemplify the scale-driven archetype through metropolitan corridor density. ANI Technologies anchors the India-focused specialization tier with two-wheeler and three-wheeler aggregation networks. These three entities represent divergent strategic postures: global horizontal expansion, regional vertical integration, and emerging-market asset-light models.
| Leading Market Players |
|---|
| Uber Technologies |
| ANI Technologies |
| Lyft |
| Gett |
| Grab Holdings |
| BlaBlaCar |
| Didi Chuxing |
| BlackBuck |
| Bolt |
| Others |
Value Chain & Pricing Dynamics
Ride-hailing premium tiers anchored in corporate mobility contracts diverge sharply from micro-mobility economy rates, with this bifurcation manifesting in fleet composition strategies and driver incentive structures across operating geographies. Battery-swapping infrastructure investments in India and subscription bundling in Germany reshape both cost bases and procurement patterns for platform operators.
Pricing Analysis
Volume-mass ride-hailing trips subsidize margin-thin operations while corporate mobility contracts capture premium pricing through predictable demand curves. Three-tier pricing structure across premium, standard, and economy levels segments by service modality, with dynamic surge algorithms and subscription passes as differentiation drivers. Cost compression in driver incentives is intensifying because gig-worker classification disputes inflate workforce retention expenses. Individual consumers exhibit highest price sensitivity, while enterprise HR departments demonstrate lowest sensitivity through bundled benefits procurement.
Supply Chain Analysis
Lithium-ion cell supply rests on Chinese cathode processing and Congolese cobalt mining concentration. Battery mineral feedstocks, high-definition mapping data, and edge-computing hardware constitute critical input dependencies. Single-source vulnerability in rare earth processing exposes fleet electrification timelines to geopolitical disruption. Distribution runs through platform-owned charging networks and third-party battery-swapping station partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where proprietary mapping data and autonomous-driving R&D pipelines determine long-term competitive position. Platforms are pursuing backward integration into fleet electrification infrastructure as the decisive downstream lever.
For Market Incumbents: Hedge against driver supply volatility by accelerating captive EV fleet deployment under India's CEA mandates. Secure exclusive battery-swapping partnerships in Bangalore and Delhi-NCR to lock in charging density before local rivals consolidate network coverage. For New Entrants and Emerging Players: The price-point gap between premium corporate mobility contracts and economy micro-mobility rates offers white-space entry. Target underpenetrated tier-2 Indian corridors in Lucknow and Indore with asset-light two-wheeler aggregation. Pursue municipal first-mile-last-mile contracts as the anchor go-to-market channel. For Investors and Strategic Acquirers: Re-rating potential sits with specialized fleet-technology providers given EU AI Act compliance tailwinds for algorithmic transparency tools. Long-term viability over a multi-year horizon favors platforms with in-house mapping capabilities and autonomous R&D pipelines. Acquisition target archetype: edge-computing dispatch node specialists with megacity deployment track records. Signal to watch: corporate account penetration exceeding forty percent of weekday volume in European corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Deployment | India's CEA timelines accelerate capital deployment into two-wheeler charging networks. |
| Super-App Convergence | Embedded financial services in Southeast Asia unify daily transaction volumes per user. |
| Corporate Mobility Contract Acquisition | Enterprise account structures in Germany deliver higher retention and predictable demand curves. |
| Autonomous-Driving R&D Pipeline | Proprietary high-definition mapping requirements lock platforms into expensive in-house development. |
| EU Green Deal Alignment | Carbon credit monetization creates regulatory tailwinds for zero-emission fleet operators. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this transportation aggregators analysis. Primary interviews with platform operations executives, fleet procurement managers, driver network coordinators, and municipal transport authority officials combined with SEC disclosures, CEA mandate documents, EU AI Act regulatory texts, and ride-hailing transaction databases. Bottom-up trip volume modeling and top-down market sizing triangulated across data streams.
Granularity-level modeling distinguished service modality, fleet propulsion architecture, and end-user procurement authority across the analysis window. Segmentation dimensions included ride-hailing versus micro-mobility, internal-combustion versus electric vehicle fleets, and individual consumer versus corporate enterprise demand. CAGRs derived from algorithmic trip density projections and urban congestion pricing policy trajectories. Driver supply elasticity and battery mineral cost curves served as industry-specific forecast inputs.
Inputs from platform operator disclosures and municipal procurement records were available through the study window; gaps in real-time driver earnings data introduce uncertainty bands around workforce retention forecasts. Projections reflect assumptions regarding EV-transition timeline adherence and congestion pricing policy implementation. Regulatory divergence across FTC, CEA, and EU AI Act jurisdictions, plus battery mineral supply disruptions, warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
Cross-Border Road Transport Market