
 Latin America Washing Machine Market | 2026-2036
Latin America Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Washing Machine Market Foresight
The Latin America washing machine market is recalibrating around a widening gap between premium front-load systems and commodity top-load units. Whirlpool Corporation leverages its regional manufacturing footprint to anchor mid-tier positioning across Mexico and Central America. Mabe differentiates through localized drum configurations suited to irregular voltage conditions in Andean markets.
A washing machine is an electromechanical appliance engineered to clean textiles through programmed cycles of agitation, rinsing, and centrifugal extraction, typically operating at spin speeds between 800 and 1600 revolutions per minute and consuming 300 to 1500 watts depending on motor topology. Its primary commercial purpose spans household garment care, commercial laundry services, and industrial textile processing facilities. Front-load and smart-technology segments command margin concentration due to higher unit economics and connected-service attach rates, while semi-automatic units retain volume dominance in rural and peri-urban zones where water pressure inconsistency limits fully automatic penetration. Compact models are gaining fastest in Brazil's major metropolitan corridors where apartment square footage constraints dictate appliance dimensions.
Brazil's INMETRO and Mexico's CONUEE energy-efficiency labeling frameworks shape product certification requirements and import eligibility across the two largest national markets, directly influencing motor technology selection and water-consumption specifications. Argentina's CNC enforcement of safety standards under IRAM certification adds compliance complexity for cross-border suppliers serving Mercosur trade routes. Stakeholders must monitor how pending harmonization between national efficiency regimes affects platform standardization decisions and regional inventory deployment strategies.
Market Dynamics
INMETRO's tightening energy-efficiency tiers are compressing manufacturer margins while accelerating inverter-motor adoption across Brazilian production lines. This regulatory ratchet is forcing platform consolidation decisions that will reshape competitive positioning through 2035.
Growth Catalysts
- Urban tenancy expansion:Rental property operators in São Paulo and Mexico City are accelerating appliance refresh cycles as lease competition intensifies. Multi-unit residential procurement now drives volume in southeastern Brazil.
- CONUEE labeling alignment:Mexico's efficiency framework is harmonizing with Brazilian standards, reducing certification duplication for cross-border suppliers. This regulatory convergence is lowering entry costs for regional manufacturers.
- Inverter-motor platforms:Variable-frequency drive technology is cutting per-cycle energy consumption by 30-40% in certified units. Brazilian assembly plants are retooling to capture INMETRO A-grade positioning.
Market Restraints
- Copper and steel input volatility:Drum and motor housing materials face price swings tied to commodity exchange fluctuations. Cost pass-through remains constrained by price-sensitive rural demand.
- Andean voltage instability:Grid fluctuation in Peru, Bolivia, and Ecuador limits fully automatic penetration. Semi-automatic units retain structural cost advantages in these markets.
- IRAM certification friction:Argentina's safety enforcement creates cross-border inventory segmentation. Mercosur routing complexity adds working capital requirements for regional distributors.
Strategic Opportunities
- Compact-form factor white space:São Paulo's micro-apartment stock is driving demand for sub-60cm width machines. No dominant supplier has optimized for this dimensional constraint.
- Connected-service attach rates:Wi-Fi-enabled diagnostics and predictive maintenance subscriptions are penetrating premium segments. Smart-technology integration is opening recurring revenue streams.
- Central American channel expansion:Guatemala and Costa Rica show underpenetrated automatic-washer penetration relative to GDP per capita. Direct retail partnerships are displacing traditional distributor layers.
Industry Challenges
- Inverter-drive engineering talent scarcity:Brazilian and Mexican plants face recruitment gaps for motor-control firmware specialists. Compensation inflation is compressing R&D budgets.
- Dual-certification timeline compression:Simultaneous INMETRO and CONUEE testing creates launch delays. Parallel approval processes extend time-to-market by 4-6 months.
- Legacy drum-supplier integration:Stainless-steel forming capacity is concentrating with three regional metalworkers. Captive supply negotiations are intensifying procurement friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Washing Machine Market |
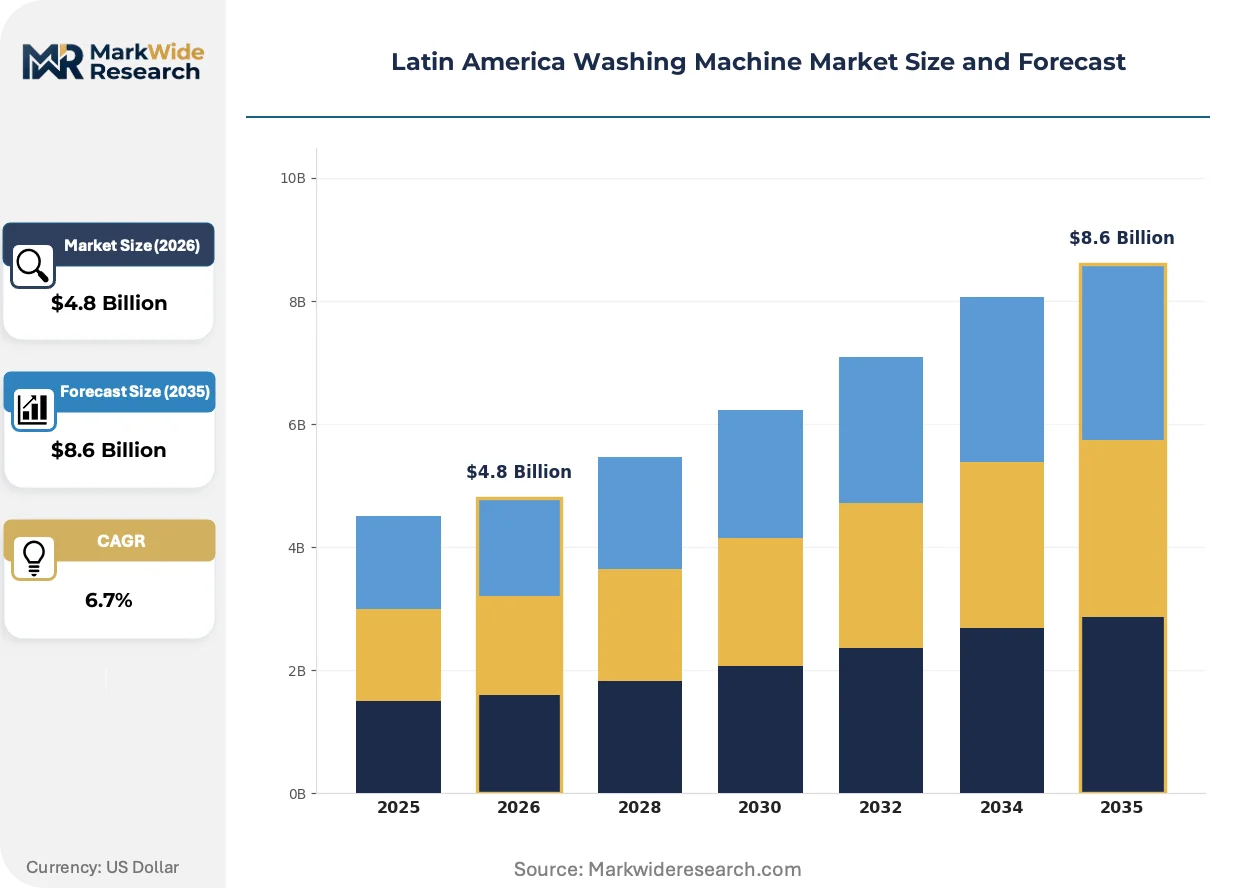
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Load, Front Load, Compact, Semi-Automatic Technology: Smart Technology, Energy-Efficient, Inverter, Traditional End User: Households, Commercial, Industrial, Rental Properties Distribution Channel: Online Retail, Brick-and-Mortar, Direct Sales, Distributors |
| Companies Covered | LG Electronics, Mabe, Whirlpool Corporation, Panasonic Corporation, Group SEB, Electrolux AB, Bosch, Miele, Samsung Electronics, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Washing Machine Market Shifts & Advancements
Product architecture is bifurcating around energy-efficiency certification tiers while distribution models fragment between traditional retail and direct-to-property-manager channels. These simultaneous shifts are compressing mid-tier positioning.
Direct-drive inverter motors are overtaking belt-drive induction systems in Brazilian and Mexican manufacturing. Front-load platform engineers are specifying torque-dense permanent-magnet designs to hit INMETRO A-grade thresholds. Rental property procurement teams are specifying these platforms for operating-cost reduction in multi-year lease structures.
CONUEE's 2024 efficiency tier expansion is mandating water-consumption limits that disqualify top-load agitator designs from import eligibility. Mexican customs enforcement is blocking non-compliant shipments at Veracruz and Lázaro Cárdenas ports. Front-load drum manufacturers are accelerating stainless-steel forming capacity to capture displaced volume.
Apartment-dweller preference is rotating toward compact capacity classes as floor-area constraints tighten in São Paulo, Rio de Janeiro, and Mexico City. Traditional 10-12kg machines are losing share to 7-8kg units in urban retail channels. Property managers are specifying these smaller footprints for studio and one-bedroom inventory refresh cycles.
Latin America Washing Machine Market Segmentation
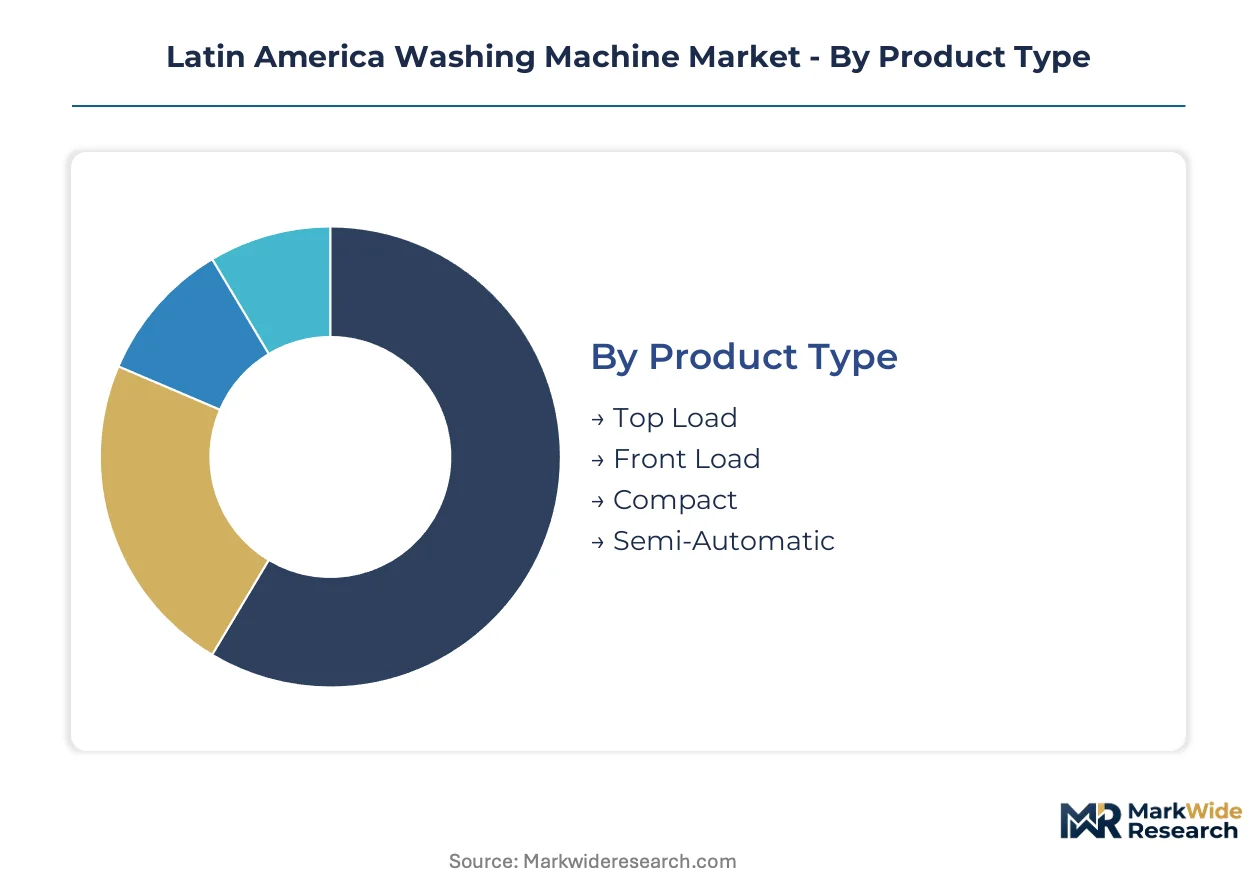
Segmentation in Latin America's washing machine market reveals how regulatory pressure and housing density reshape procurement patterns. Manufacturers must align platform decisions with INMETRO certification tiers while serving divergent voltage conditions across Andean and coastal markets.
Product Type:
Drum orientation and automation level define platform economics and certification eligibility across Brazilian and Mexican assembly lines.
- Front Load:Horizontal-axis drum configuration with tumble-action washing cycles. São Paulo's rental property operators specify these units for water-consumption compliance in multi-year lease structures. INMETRO A-grade certification concentrates demand in southeastern Brazil.
- Top Load:Vertical-axis agitator systems with faster cycle completion times. Rural distributors across Mexico's northern states move volume where water pressure inconsistency limits front-load penetration.
- Compact:Sub-60cm width machines engineered for micro-apartment installations. São Paulo's studio inventory refresh cycles absorb regional production capacity.
- Semi-Automatic:Twin-tub designs requiring manual water transfer. Bolivia and Ecuador's grid instability sustains structural demand for voltage-resilient platforms.
Top Load leads on scale; Compact leads on momentum.
Technology:
Motor topology and connectivity features separate premium positioning from commodity procurement in property manager specifications.
- Inverter:Variable-frequency drive motors cutting per-cycle energy draw by 30-40%. Brazilian plants retool assembly lines to capture INMETRO efficiency premiums ahead of tier tightening.
- Smart Technology:Wi-Fi-enabled diagnostics with predictive maintenance subscriptions. Mexico City's high-end residential towers specify these for remote monitoring of common-area laundry facilities.
- Energy-Efficient:Platforms meeting CONUEE and INMETRO baseline thresholds. Cross-border suppliers consolidate SKUs around harmonized certification requirements.
- Traditional:Belt-drive induction motors without variable-speed control. Price-sensitive rural markets in northeastern Brazil retain volume concentration.
Traditional platforms retain volume dominance; Inverter systems gain share fastest.
End User:
Procurement scale and operating-cost sensitivity fragment demand across residential and commercial deployment contexts.
- Rental Properties:Multi-unit residential operators accelerating refresh cycles in Mexico City and São Paulo. Lease competition drives specification of connected, efficiency-certified units.
- Households:Individual family purchases dominating unit volume. Replacement timing correlates with INMETRO label visibility in retail channels.
- Commercial:Laundromat and hospitality operators with high-utilization requirements. Front-load durability specifications concentrate demand in urban corridors.
- Industrial:Textile processing facilities with specialized extraction and finishing needs. Distinct from consumer-grade supply chains.
Households anchor absolute volume; Rental Properties expand most quickly.
Distribution Channel:
Channel selection determines margin capture and inventory velocity across divergent market maturities.
- Brick-and-Mortar:Appliance specialty retailers and hypermarkets sustaining majority volume. São Paulo's shopping corridors concentrate premium product visibility.
- Direct Sales:Property manager procurement bypassing distributor markups. Rental operators in Mexico City consolidate purchasing through manufacturer agreements.
- Online Retail:E-commerce platforms gaining traction in urban markets with reliable delivery infrastructure. São Paulo and Rio de Janeiro show highest conversion rates.
- Distributors:Traditional wholesale layers serving rural and peri-urban zones. Working capital requirements concentrate with three regional metalworkers supplying drum components.
Brick-and-Mortar retains structural dominance; Direct Sales climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil absorbs larger procurement volumes than Mexico, yet Mexican assembly lines export more efficiently into Central American corridors. Argentina's certification friction creates inventory segmentation that Colombian distributors exploit for cross-border arbitrage.
Brazil
São Paulo's rental property operators specify INMETRO A-grade inverter platforms for multi-year lease structures. INMETRO's tightening efficiency tiers compress manufacturer margins while accelerating motor retooling. Southeastern Brazil concentrates replacement demand where dense apartment stock sustains refresh cycles.
Mexico
Mexico City property managers consolidate purchasing through direct manufacturer agreements bypassing distributor markups. CONUEE's 2024 efficiency tier expansion blocks non-compliant shipments at Veracruz and Lázaro Cárdenas ports. Nuevo León assembly plants capture displaced volume from Andean voltage instability.
Argentina
IRAM certification enforcement creates cross-border inventory segmentation that extends working capital requirements. The CNC safety standards under IRAM add compliance complexity for Mercosur trade route suppliers. Buenos Aires retail channels absorb premium front-load units despite import friction.
Colombia
Bogotá's appliance distributors leverage Argentina's certification delays for regional arbitrage positioning. The national energy efficiency labeling program harmonizes with Brazilian thresholds reducing SKU duplication. Antioquia's manufacturing corridor supplies compact units for micro-apartment installations.
Chile
Santiago's high-rise residential towers drive specification of connected-service platforms for common-area laundry facilities. The national energy efficiency authority tightens import eligibility mirroring CONUEE trajectory. Valparaíso logistics corridors concentrate inbound shipment consolidation for Andean redistribution.
Latin America Washing Machine Market Competitive Landscape
Top-tier vendors anchor premium front-load and smart-technology positioning, while mid-tier fabrications concentrate around efficiency-certified commodity platforms. The competitive structure bifurcates between inverter-motor specialists and traditional belt-drive suppliers serving voltage-unstable zones. Two strategic archetypes dominate: regional manufacturing footprint holders and localized drum-configuration specialists. Capacity expansion and platform consolidation represent the dominant competitive moves through the forecast horizon.
Within the regional manufacturing tier, Whirlpool Corporation and Mabe exemplify divergent localization strategies. LG Electronics occupies a position bridging premium technology integration with mid-tier volume scale. These three anchors represent how competitive positioning recalibrates around INMETRO certification capture and Andean voltage resilience respectively.
| Leading Market Players |
|---|
| LG Electronics |
| Mabe |
| Whirlpool Corporation |
| Panasonic Corporation |
| Group SEB |
| Electrolux AB |
| Bosch |
| Miele |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
Family-owned metalworking specialists across southeastern Brazil have consolidated stainless-steel drum forming capacity, tightening procurement leverage for appliance assemblers while compressing margin buffers on mid-tier platforms. Their captive supply negotiations with Whirlpool and Mabe plants directly shape pricing discipline across INMETRO-certified and uncertified product tiers.
Pricing Analysis
Connected-service bundling separates premium front-load platforms from unconnected commodity units in rental property procurement. Three-tier pricing structure across premium, standard, and economy levels tracks INMETRO certification grade and after-sales service inclusion. Pricing pressure stems from copper and steel input volatility that manufacturers cannot fully pass to price-sensitive rural buyers in northeastern Brazil. Property managers in São Paulo show least price sensitivity due to operating-cost amortization across multi-year lease structures.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from São Paulo and Nuevo León assembly hubs into Central American corridors and Andean markets. Component sourcing draws from Brazil, Mexico, and China for motor assemblies, electronic control boards, and stainless-steel drum housings. Single-source vulnerability concentrates in regional metalworkers supplying formed drum components to multiple OEMs. Distribution runs through appliance specialty retailers and direct property-manager agreements bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's washing machine market functions as a geographic-arbitrage play where manufacturers exploit regulatory timing gaps between Brazil's INMETRO tier tightening and Mexico's CONUEE harmonization to optimize certification investments and inventory deployment.
For Market Incumbents: Extend inverter-motor platform coverage into compact-form factor white space before specialized entrants capture São Paulo micro-apartment demand. Secure captive supply agreements with the three regional drum metalworkers to defend against input cost volatility threatening mid-tier margins. Certification investment in simultaneous INMETRO-CONUEE testing protocols compresses launch timelines against emerging competitors. For New Entrants and Emerging Players: Launch via direct-to-property-manager channels in Guatemala and Costa Rica where automatic-washer penetration lags GDP per capita and traditional distributor layers create margin capture opportunity. Target compact 7-8kg capacity classes for São Paulo studio inventory refresh cycles where no dominant supplier has optimized dimensional constraints. Specify voltage-resilient platforms for Bolivian and Ecuadorian grid conditions that limit incumbent front-load penetration. For Investors and Strategic Acquirers: Appliance manufacturers with Central American assembly footprint are the most active acquirer in this space, seeking platform consolidation to capture harmonized certification benefits. Long-term viability hinges on inverter-drive engineering talent acquisition and connected-service subscription attach rates. Monitor INMETRO tier enforcement velocity as inflection indicator for margin compression timing across Brazilian production lines.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter-Motor Platform Expansion | Captures INMETRO A-grade positioning ahead of regulatory tier tightening in southeastern Brazil. |
| Compact-Form Factor Development | Addresses São Paulo micro-apartment dimensional constraints where supply gaps persist. |
| Direct Property-Manager Channel Buildout | Bypasses distributor markups in Mexico City and accelerates volume consolidation. |
| Connected-Service Subscription Launch | Opens recurring revenue streams through Wi-Fi-enabled diagnostics in premium residential towers. |
| Central American Manufacturing Footprint | Positions for CONUEE-INMETRO harmonized certification exports into underpenetrated corridors. |
Research Methodology
Multiple input streams — appliance manufacturer production data, rental property operator procurement records, regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant engineering directors, property manager procurement heads, retail category buyers, and INMETRO certification specialists were validated against secondary sources including customs trade records, CONUEE efficiency registry filings, and SEC 10-K disclosures from listed appliance manufacturers.
Historical shipment volumes were cross-referenced against panel input from distribution channel partners to anchor growth trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type, motor technology tier, end-user procurement scale, and distribution channel structure alongside regional regulatory cluster alignment. CAGRs were derived from fitted trend analysis incorporating urban tenancy expansion rates and efficiency mandate compliance curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price spike scenarios or accelerated INMETRO tier enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Undercounter Refrigerators Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
Major Home Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
Oman Major Home Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Built-In Appliance Market
Home Appliances
India Laundry Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Italy Home Appliances Market