
 Fungal Testing Kits Market | 2026-2036
Fungal Testing Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Fungal Testing Kits Market Analysis
The EU In Vitro Diagnostic Regulation is pivoting the cost-of-entry calculus for molecular fungal diagnostics, forcing manufacturers to rebuild technical documentation and clinical evidence portfolios. Thermo Fisher Scientific leverages its CE-IVD portfolio breadth to sustain laboratory channel dominance across European member states. bioMérieux anchors its competitive position through automated blood culture and syndromic panel integration. Abbott Laboratories differentiates via point-of-care connectivity and health system procurement contracts.
Fungal testing kits comprise in vitro diagnostic devices designed to detect, identify, or quantify pathogenic fungi in clinical specimens through culture-based, immunological, or nucleic acid amplification methods, with sensitivity thresholds typically ranging from 10 to 100 colony-forming units per milliliter depending on the target organism and matrix. These products serve primarily to guide antifungal therapy selection, monitor treatment response, and support hospital infection control surveillance. Polymerase Chain Reaction-based platforms command premium positioning due to accelerated turnaround times and species-level resolution for Candida and Aspergillus complexes. Diagnostic Laboratories represent the most concentrated end-user margin pool, though Home Care channels are expanding as self-collection devices gain regulatory clearances for superficial dermatophyte screening.
The FDA's Class II special controls for in vitro diagnostic devices and the EU IVDR's performance evaluation requirements collectively shape product development roadmaps and market access timelines for fungal assay manufacturers. ISO 15189 accreditation standards for medical laboratories further filter kit selection toward analytically validated, quality-controlled platforms. Stakeholders must monitor evolving antifungal resistance patterns and corresponding reference method updates that could obsolete existing assay target panels.
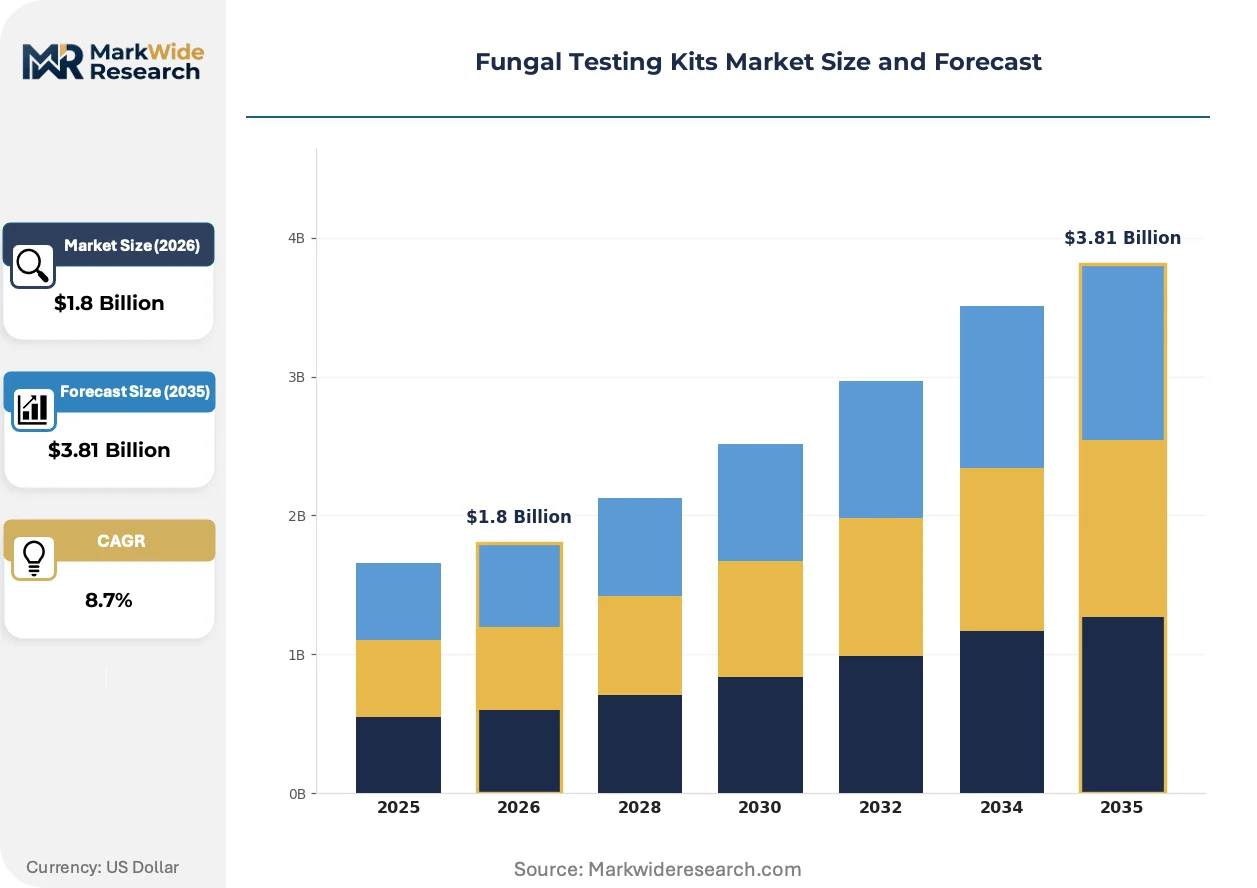
Market Dynamics
The EU In Vitro Diagnostic Regulation is forcing manufacturers to rebuild clinical evidence portfolios and technical documentation, compressing market access timelines while elevating R&D burn rates for molecular fungal diagnostic platforms.
Growth Catalysts
- Hospital-acquired infection surveillance mandates:United States healthcare facilities face mandatory environmental and clinical fungal screening protocols, expanding kit procurement volumes across acute care networks.
- CE-IVD pathway maturation:European laboratories accelerate molecular platform adoption as notified body capacity stabilizes under IVDR implementation frameworks.
- Immunocompromised patient expansion:Oncology and transplant unit censuses climb, creating sustained diagnostic demand for Candida and Aspergillus detection.
Market Restraints
- Notified body bottleneck:EU IVDR conformity assessment queues extend certification timelines, freezing product launches for 18-24 months.
- Reagent supply concentration:Polymerase chain reaction master mix production clusters in Germany and the United States, exposing distributors to single-source vulnerability.
- Culture-based reference standard persistence:Gold-standard mycological methods delay molecular assay reimbursement parity in public health systems.
Strategic Opportunities
- Home-based dermatophyte screening:Self-collection devices with CLIA-waived status unlock direct-to-consumer channels previously restricted to clinical settings.
- Antifungal stewardship integration:Syndromic panel connectivity with pharmacy information systems creates subscription revenue models in integrated delivery networks.
- ISO 15189 accreditation tailwind:Laboratory quality standard enforcement in Asia-Pacific markets filters procurement toward analytically validated platforms.
Industry Challenges
- Mycology technologist scarcity:Specialized microscopy and culture interpretation skills contract as training programs shutter, forcing laboratories toward automation.
- Assay target panel obsolescence risk:Evolving azole resistance mutations in Aspergillus fumigatus demand continuous R&D to maintain clinical sensitivity claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fungal Testing Kits Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerase Chain Reaction, Enzyme Immunoassay, Plate Culture, Microscopy End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Distribution Channel: Online Retail, Direct Sales, Distributors, Pharmacies Technology: Centrifugation, Nucleic Acid Probes, Fluorescence, Immunoassay |
| Companies Covered | Thermo Fisher Scientific, Abbott Laboratories, Roche Diagnostics, bioMérieux, BD, Bio-Rad Laboratories, PerkinElmer, Merck KGaA, Cepheid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fungal Testing Kits Market Emerging Trajectories
Next-generation sequencing workflows and point-of-care connectivity architectures are compressing turnaround times while fragmenting traditional laboratory service models across diagnostic networks.
Loop-mediated isothermal amplification platforms are overtaking conventional polymerase chain reaction systems in resource-limited settings. District hospitals in India and Brazil adopt these devices for same-day Candida species identification. The technology is overtaking centralized reference laboratory workflows by eliminating cold-chain specimen transport dependencies.
CE marking under EU IVDR Annex IX now requires prospective clinical performance studies for Class C devices, eliminating legacy literature-based equivalence pathways. Manufacturers face expanded notified body audit scope covering post-market surveillance systems. European molecular diagnostic vendors respond by consolidating quality management functions and acquiring clinical trial capabilities in-house.
Integrated delivery networks now unbundle mycology testing from exclusive reference laboratory contracts, awarding point-of-care connectivity contracts to vendors with health information exchange interoperability. Hospital procurement committees prioritize platforms with automated result transmission to antimicrobial stewardship dashboards. This pattern concentrates in United States metropolitan markets where Medicare readmission penalties intensify infection control investment.
Fungal Testing Kits Market Segmentation
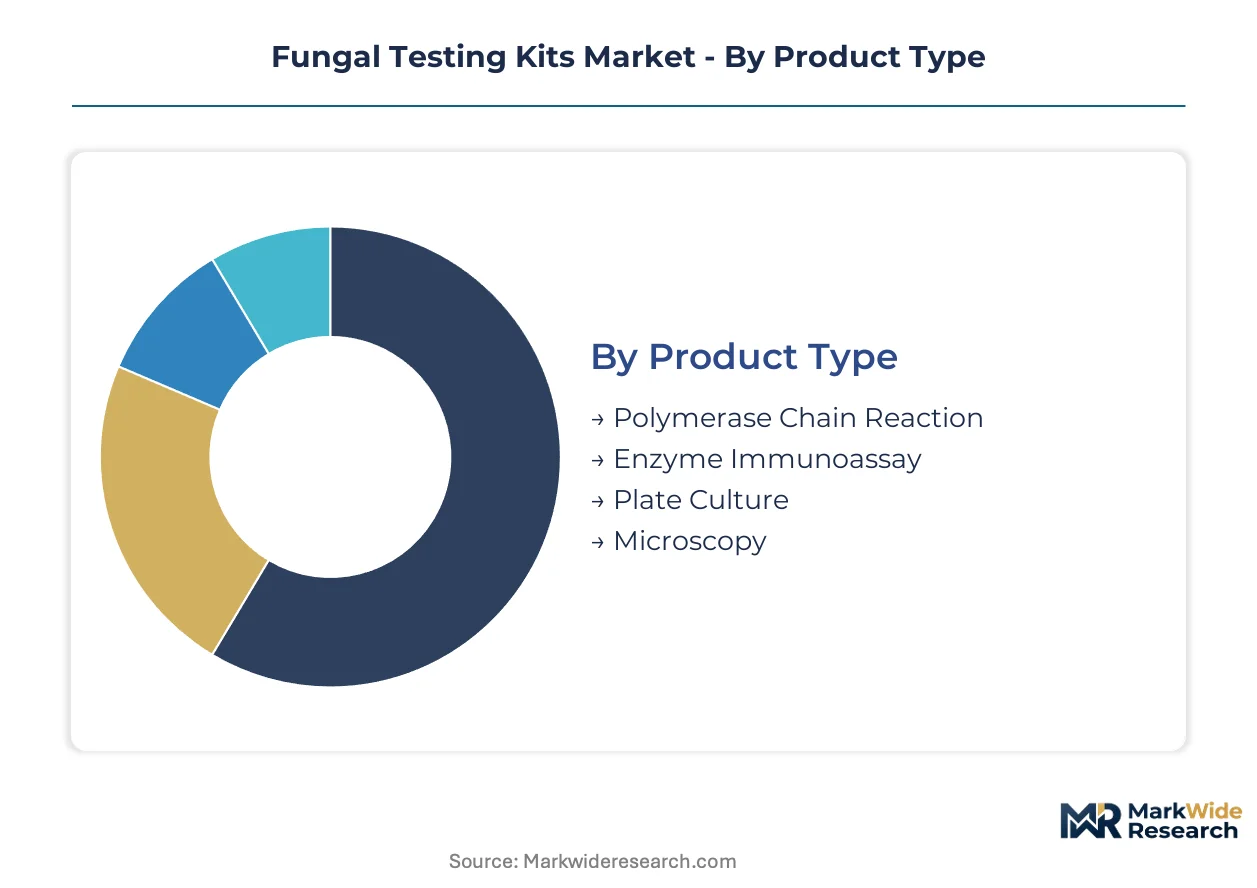
Segmentation in fungal testing kits reveals how diagnostic workflows split between high-complexity laboratory platforms and decentralized point-of-care systems. Procurement patterns diverge sharply across these boundaries, with integrated health networks favoring automated solutions while resource-limited settings prioritize portability and cold-chain independence.
Product Type:
Standalone molecular platforms dominate high-throughput laboratory installations, while embedded cartridge systems penetrate point-of-care networks requiring minimal technical oversight.
- Polymerase Chain Reaction:Thermal cycling instrumentation amplifies fungal DNA with species-level resolution for Candida and Aspergillus complexes. Demand concentrates in United States hospital laboratories where FDA-cleared assays support antimicrobial stewardship programs and reimbursement parity with culture-based methods.
- Enzyme Immunoassay:Antigen-antibody binding reactions detect fungal cell wall components in serum or bronchoalveolar lavage specimens. European diagnostic laboratories under EU IVDR pressure favor these platforms for their established clinical evidence portfolios and streamlined conformity assessment pathways compared to novel molecular claims.
- Plate Culture:Sabouraud dextrose and chromogenic agar formulations remain the gold-standard reference method for phenotypic identification and antifungal susceptibility testing.
- Microscopy:Potassium hydroxide preparation and calcofluor white fluorescence require specialized mycology technologist expertise increasingly scarce in clinical laboratories.
Volume placements concentrate in Plate Culture; the faster expansion belongs to Polymerase Chain Reaction.
End User:
Customer type determines kit specification, with acute care facilities demanding STAT turnaround capabilities and home settings requiring self-collection simplicity.
- Hospitals:Inpatient microbiology laboratories process sterile-site specimens from immunocompromised oncology and transplant units under mandatory infection surveillance protocols. United States metropolitan health systems drive procurement volumes through centralized purchasing agreements tied to health information exchange connectivity.
- Diagnostic Laboratories:Reference mycology services handle specimen overflow from hospitals lacking on-site expertise, with ISO 15189 accreditation filtering vendor selection toward analytically validated platforms. These facilities anchor the concentrated margin pool for manufacturers through high-volume contracts and syndromic panel subscriptions.
- Research Institutions:Academic medical centers and contract research organizations utilize investigational assays for clinical trial endpoints and epidemiological surveillance studies.
- Home Care:Direct-to-consumer dermatophyte screening devices with CLIA-waived status unlock channels previously restricted to clinical settings, though regulatory clearances lag behind superficial fungal infection prevalence.
Procurement volumes cluster in Diagnostic Laboratories; Home Care channels are climbing the fastest as self-collection devices gain regulatory momentum.
Distribution Channel:
Channel structure reflects kit complexity, with capital-intensive platforms requiring direct technical support and consumables flowing through consolidated distributor networks.
- Online Retail:E-commerce platforms serve home-based screening devices and over-the-counter dermatophyte kits, bypassing traditional clinical procurement committees. Direct-to-consumer channels expand as manufacturers invest in digital patient education and telemedicine integration for result interpretation.
- Direct Sales:Manufacturer field service organizations install and validate molecular diagnostic platforms in hospital laboratories, embedding technical specialists within customer sites for assay training and troubleshooting. These relationships lock in reagent annuity streams through exclusive supply agreements.
- Distributors:Regional medical supply wholesalers aggregate consumable orders from smaller laboratories and outpatient clinics, consolidating logistics across multiple vendor portfolios.
- Pharmacies:Community and hospital outpatient pharmacies stock point-of-care fungal screening devices for immediate patient access, particularly in markets with pharmacist prescribing authority.
Revenue concentration sits with Direct Sales; Online Retail is gaining share fastest as home screening devices proliferate.
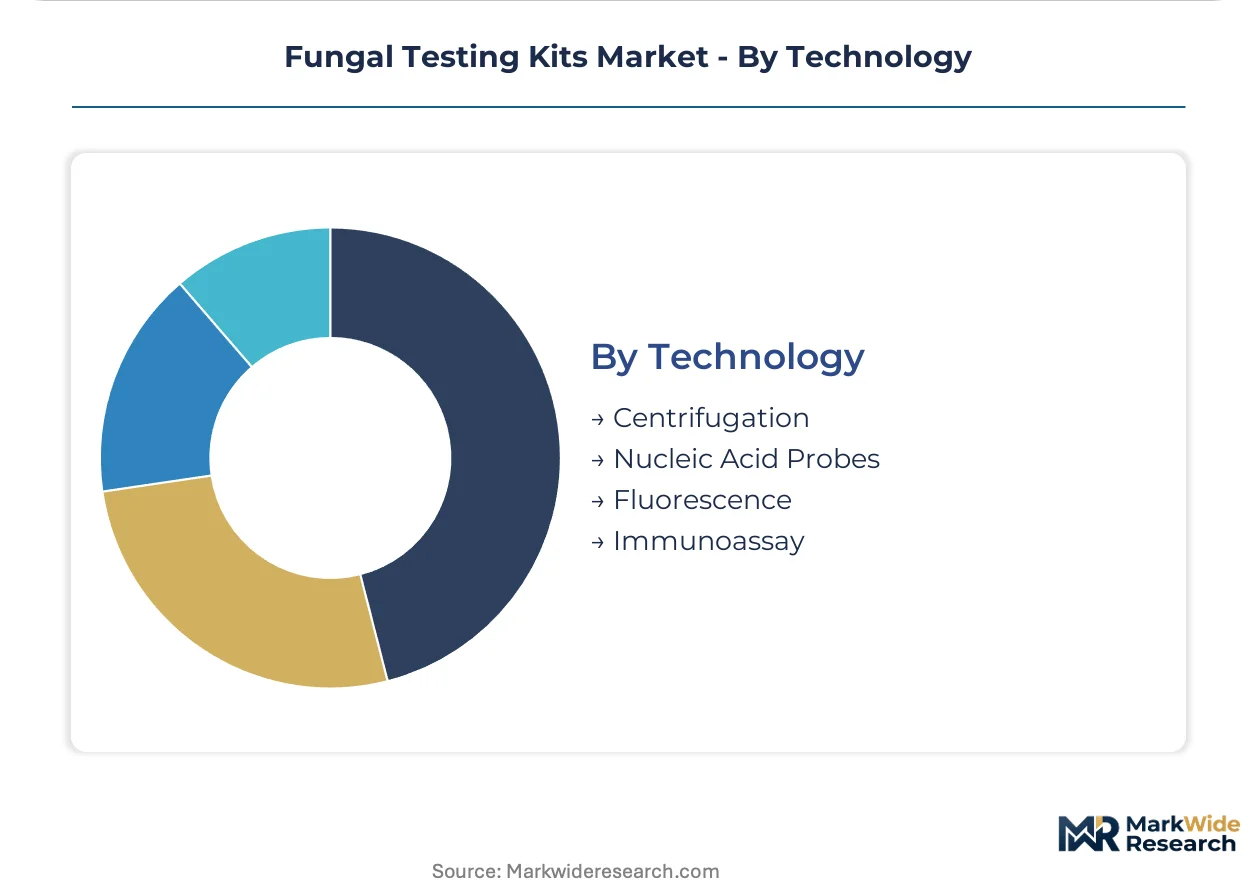
Technology:
Technical approach determines analytical sensitivity, specificity, and workflow integration requirements, with fluorescence and probe-based methods commanding premium positioning.
- Centrifugation:Density gradient separation concentrates fungal elements from clinical specimens prior to downstream detection, serving as a sample preparation module integrated into automated platforms rather than a standalone diagnostic endpoint.
- Nucleic Acid Probes:Hybridization-based detection targets species-specific ribosomal RNA sequences without amplification, offering simplified workflow for resource-limited settings. District hospitals in India and Brazil adopt these systems where cold-chain logistics for PCR reagents prove unreliable.
- Fluorescence:Confocal and widefield microscopy with fungal-specific stains enables rapid presumptive identification in experienced hands. These systems anchor reference laboratory workflows where mycology technologist expertise persists.
- Immunoassay:Lateral flow and enzyme-linked formats deliver qualitative or semi-quantitative results at point-of-care, with connectivity modules transmitting data to antimicrobial stewardship dashboards.
Installed base concentrates in Immunoassay; Nucleic Acid Probes are expanding most quickly in emerging market district hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized diagnostic zones in Massachusetts and California concentrate molecular assay development, while German industrial clusters anchor European manufacturing capacity for fungal testing platforms.
United States
Hospital-acquired infection surveillance mandates from CMS drive procurement volumes across acute care networks. FDA Class II special controls for in vitro diagnostic devices shape product development timelines and clinical trial requirements. The Boston-Cambridge corridor hosts dense clusters of molecular diagnostic developers advancing PCR-based fungal detection platforms.
Germany
Reference mycology laboratories under statutory health insurance contracts sustain demand for automated culture and identification systems. EMA guidance on companion diagnostics and BfArM oversight of medical devices elevate conformity assessment standards. The Rhine-Main metropolitan region concentrates reagent manufacturing and notified body technical review capacity.
India
Expanding oncology and transplant unit censuses in tertiary care hospitals generate diagnostic demand for Candida and Aspergillus detection. CDSCO medical device rules and state-level laboratory accreditation programs filter procurement toward quality-controlled platforms. District hospitals in Maharashtra and Karnataka adopt loop-mediated isothermal amplification devices for same-day species identification.
Japan
Aging immunocompromised populations and hematology unit expansion sustain molecular diagnostic adoption. PMDA consultation pathways for in vitro diagnostics accelerate regulatory review for novel fungal assays. The Kansai region around Osaka anchors automated blood culture system manufacturing and distribution networks.
Brazil
Public health system consolidation under SUS creates procurement scale for syndromic diagnostic panels. ANVISA medical device regulations and INMETRO conformity assessment requirements structure market access pathways. São Paulo state laboratories drive adoption of point-of-care connectivity platforms for antimicrobial stewardship integration.
Fungal Testing Kits Market Vendor Landscape
United States producers anchor the premium molecular tier; European specialists hold consolidated positions in automated culture and immunoassay segments. The vendor base separates into three functional layers: diversified life science conglomerates with broad diagnostic portfolios, mid-scale automation specialists, and emerging point-of-care connectivity vendors. Strategic moves concentrate on assay menu expansion through technology licensing and vertical integration into reagent manufacturing to secure supply continuity.
Among diversified conglomerates, Thermo Fisher Scientific and Abbott Laboratories exemplify the full-platform archetype spanning research-use-only through clinical diagnostics. bioMérieux occupies a distinct position as the automation-centric European specialist. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning: Waltham-based Thermo Fisher leverages CE-IVD breadth; Abbott's Illinois headquarters supports health system procurement contracting; and French bioMérieux S.A. concentrates on integrated blood culture and syndromic panel workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Roche Diagnostics |
| bioMérieux |
| BD |
| Bio-Rad Laboratories |
| PerkinElmer |
| Merck KGaA |
| Cepheid |
| Others |
Supply Flow & Price Mechanics
EU IVDR clinical evidence mandates gate qualified supply access and premium-tier pricing for molecular fungal diagnostics, compressing certification timelines while elevating R&D burn rates that manufacturers must recover through tiered product positioning.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid turnaround capabilities with premium positioning while spot inventory of legacy immunoassay kits trades at contracted discounts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared PCR platforms with health information exchange connectivity from CE-IVD immunoassays and unvalidated research-use-only reagents. Price differentiation rests on ISO 15189 accreditation status and syndromic panel integration depth. Cost compression in the economy tier is intensifying because district hospitals in emerging markets prioritize cold-chain-independent alternatives. Diagnostic laboratories demonstrate lowest price sensitivity due to stewardship-driven procurement mandates, while home care channels exhibit highest elasticity pending CLIA-waiver expansion.
Supply Chain Analysis
Reverse-logistics infrastructure for expired reagent returns and instrument refurbishment remains underdeveloped, forcing laboratories into premature platform obsolescence rather than component-level renewal. Manufacturing concentrates in Germany, the United States, and Japan, with PCR master mix production clustering around Frankfurt and Boston metropolitan regions. Raw material dependencies span thermostable polymerases from recombinant bacterial fermentation, fluorophore-labeled oligonucleotides from specialized chemical synthesis houses, and precision-molded consumables from medical-grade polymer processors. Single-source vulnerability in thermocycler componentry exposes distributors to extended lead time volatility. Distribution runs through manufacturer field service organizations for capital platforms and regional medical wholesalers for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
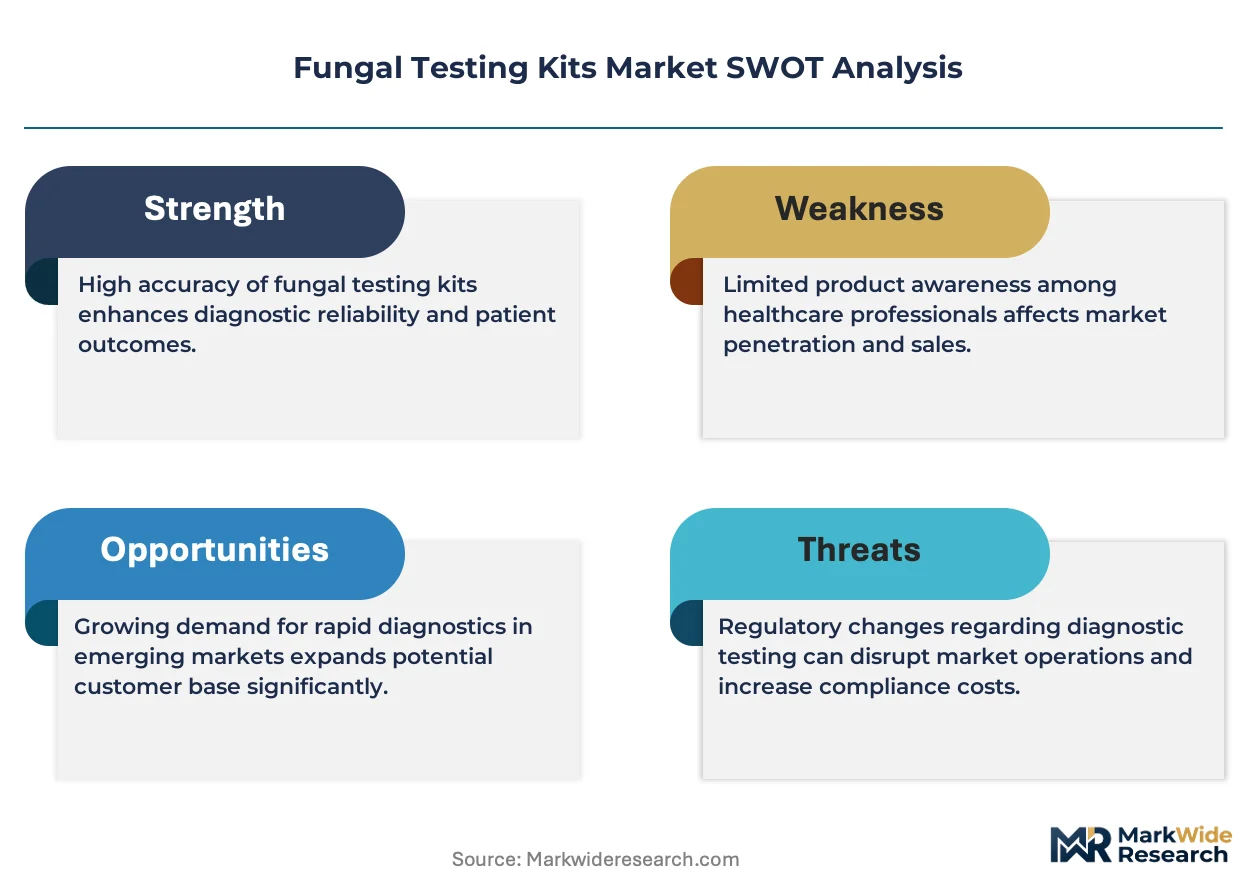
Notified body certification queues constitute the binding capacity constraint, propping pricing power for IVDR-compliant manufacturers while freezing market access for backlog-affected competitors.
For Market Incumbents: Deploy syndromic panel connectivity as the anchor lever to deepen health system procurement lock-in. Consolidate quality management functions in-house to compress IVDR audit cycles. Acquire clinical trial capabilities to eliminate third-party dependency for prospective performance studies. Counter loop-mediated isothermal amplification displacement in emerging markets through localized cartridge manufacturing partnerships. For New Entrants and Emerging Players: Point-of-care dermatophyte screening with telemedicine result interpretation represents the most penetrable white-space target. District hospital networks in Maharashtra and Karnataka offer lowest competitive density for same-day species identification platforms. Pursue CDSCO medical device registration paired with state-level laboratory accreditation programs as the primary go-to-market angle. For Investors and Strategic Acquirers: ANVISA approval acceleration for syndromic panels in São Paulo state laboratories is the leading indicator that antimicrobial stewardship integration is reaching procurement inflection. Five-to-ten year viability favors platforms with reagent manufacturing backward integration and health information exchange interoperability. Target mid-scale automation specialists with captive ISO 15189 consultancy capabilities. Monitor EU IVDR notified body capacity expansion announcements as the signal for compressed certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Pathway Completion | Annex IX Class C certification unlocks European hospital laboratory procurement committees. |
| Health Information Exchange Integration | Automated stewardship dashboard connectivity secures integrated delivery network exclusivity. |
| Loop-Mediated Isothermal Amplification Launch | Cold-chain independence captures district hospital volume in India and Brazil. |
| CLIA-Waived Self-Collection Device | Direct-to-consumer dermatophyte screening bypasses clinical procurement bottlenecks. |
| Antifungal Stewardship Partnership | Pharmacy information system integration creates subscription revenue in Medicare penalty-exposed markets. |
Methodological Framework
Independent corroboration across hospital microbiology laboratory directors, IVD regulatory affairs specialists, and antimicrobial stewardship pharmacists underwrites the qualitative findings. Primary interviews with biomedical engineers, GPO contracts managers, and mycology technologist training program administrators captured workflow integration constraints. Secondary validation drew from FDA 510(k) filings, EMA IVDR guidance documents, CDSCO medical device registration databases, and hospital procurement contract repositories. Bottom-up kit volume modeling triangulated against top-down healthcare expenditure attribution across the analysis window.
Comparable-period anchoring tied projection assumptions to historical reference intervals spanning IVDR implementation phases and pre-pandemic diagnostic utilization baselines. Segmentation dimensions modeled encompassed product type, end-user facility tier, distribution channel structure, and regional regulatory cluster. CAGRs derived from slope-consistent trajectory analysis applied to validated base-year estimates. Forecast inputs incorporated immunocompromised patient census projections, antifungal resistance mutation surveillance data, and notified body capacity expansion schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR audit scope expansion or thermocycler component trade restriction scenarios. Material deviation in CDSCO enforcement intensity, CMS readmission penalty recalibration, or azole resistance mutation epidemiology warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Rapid Sterility Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Allergy Skin Test Market
Testing Services
Solid Tumor Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Mycological Testing Market
Testing Services
Home DNA Testing Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
Global Sterility Testing Market
Testing Services
Active B12 Test Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Toxicology Testing Services Market
Testing Services
Phenytoin Testing Market