
 Shrink Bands Market | 2026-2036
Shrink Bands Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Bands Market Analytics
Capital-intensity divergence between extrusion-capable film producers and downstream converters is reorganizing competitive tiers in shrink bands. Berry Global Group leverages integrated resin-to-sleeve operations across North American pharmaceutical corridors. Amcor plc anchors European beverage demand through specialized PET-glycol modified formulations. Fuji Seal International competes in Asian personal care markets with precision-printed high-shrinkage configurations.
Shrink bands are heat-activated polymer sleeves, typically manufactured from PVC, PET, or oriented polyolefin substrates with shrink initiation temperatures between 70°C and 100°C, that contract radially to conform tightly to container contours for tamper evidence and label integration. PVC formulations dominate legacy food packaging applications where cost sensitivity overrides sustainability preferences. Polyolefin grades are gaining share in pharmaceutical packaging due to superior clarity and recyclability alignment with EPR frameworks. PLA biopolymer variants occupy niche premium personal care channels where brand owners mandate compostable end-of-life pathways.
FDA regulations under the Drug Supply Chain Security Act mandate unit-level traceability that elevates shrink band specifications for pharmaceutical serialization. REACH restrictions on phthalate plasticizers in Europe are redirecting PVC demand toward non-phthalate and polyolefin alternatives. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that will redefine material recovery obligations for multi-layer sleeve structures.
Market Dynamics
Regulatory mandates for pharmaceutical traceability are compressing specification cycles across shrink band converters, forcing rapid material transitions from legacy PVC toward polyolefin and printable substrates that accommodate serialization codes.
Growth Catalysts
- Drug Supply Chain Security Act compliance:FDA unit-level traceability requirements are elevating tamper-evident sleeve specifications for pharmaceutical serialization, pulling demand toward high-clarity printable grades.
- Biologics cold-chain expansion:Temperature-stable polyolefin formulations are capturing share in contract packaging services for injectable therapies requiring sub-zero distribution integrity.
- Extended producer responsibility frameworks:California and New York state-level material recovery laws are accelerating design-for-recycling investments in mono-layer sleeve structures.
Market Restraints
- Resin supply concentration:North American PET glycol-modified feedstock relies on concentrated Gulf Coast petrochemical corridors, exposing converters to hurricane-season volatility.
- Phthalate substitution costs:REACH restrictions on plasticizer chemistry are forcing European PVC processors toward higher-cost non-phthalate formulations with narrower processing windows.
- Multi-layer incompatibility:Current mechanical recycling infrastructure cannot separate printed PET-PVC laminates, creating end-of-life liability for brand owners under emerging EPR schemes.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO serialization mandates for exported generics are creating first-mover advantage for converters establishing local sleeve printing capacity.
- Personal care refill systems:Snap-fit shrink band configurations for reusable aluminum bottles are opening premium channels in Korean and Japanese cosmetic markets.
- Digital watermark integration:Covert machine-readable markers embedded during extrusion are enabling automated sortation at materials recovery facilities, aligning with EU Green Deal circularity targets.
Industry Challenges
- Extrusion-printing skill convergence:Converter workforces must master both blown film gauge control and rotogravure registration precision, creating recruitment bottlenecks in Midwest US manufacturing corridors.
- Validation timeline compression:Pharmaceutical customers are compressing qualification cycles for new sleeve specifications from 18 months to 8 months, straining quality systems.
- Legacy sealer retrofit requirements:Steam tunnel infrastructure at beverage bottlers requires costly modification to process lower-shrink-force polyolefin alternatives without container distortion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Bands Market |
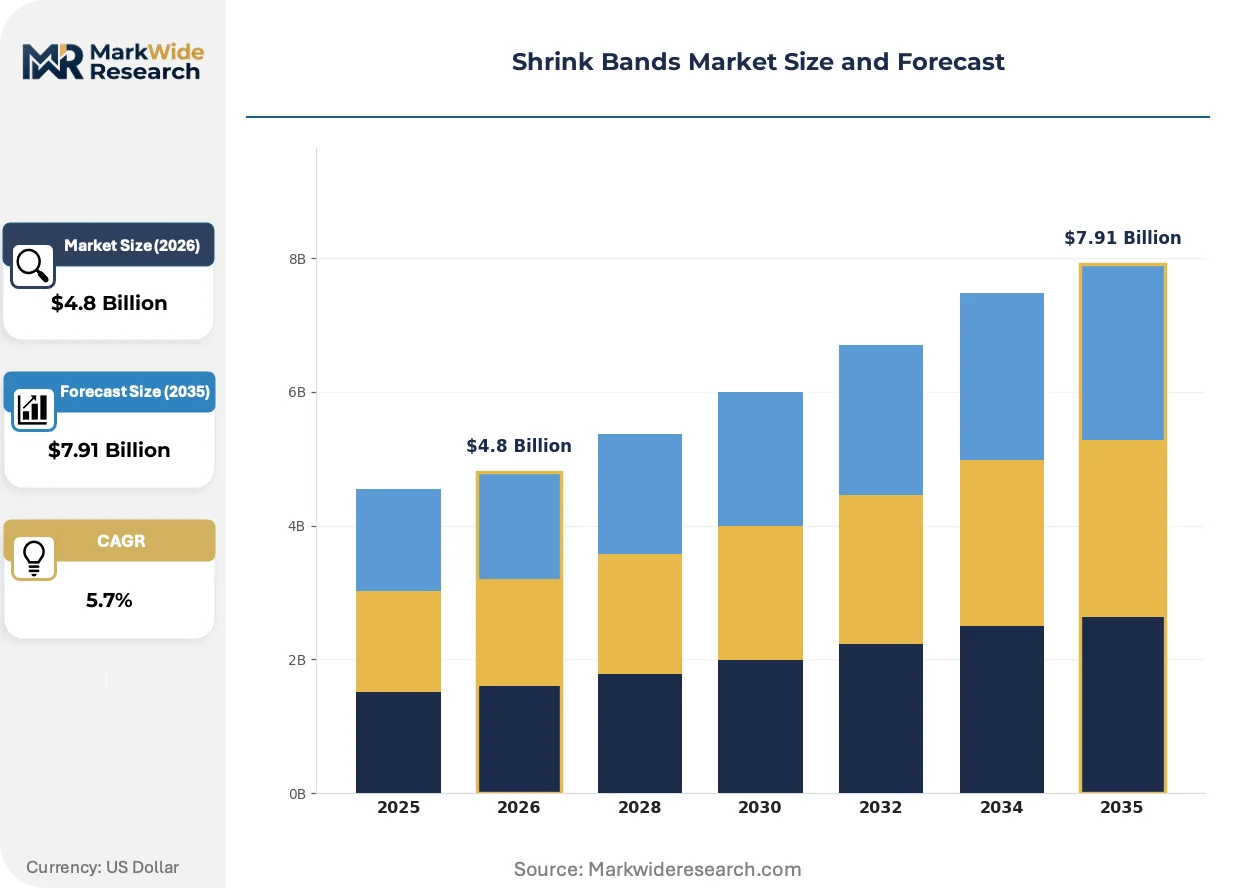
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, PET, Polyolefin, PLA Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Personal Care Packaging Thickness: Less than 50 Microns, 50-100 Microns, 100-200 Microns, More than 200 Microns Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Berry Global Group, Amcor plc, Fuji Seal International, CCL Industries, Clondalkin Group Holdings BV, Bemis Company, Huhtamaki, Klockner Pentaplast, LINTEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Bands Market Evolving Landscape
Heat-shrink sleeve technology is diverging along three axes: substrate chemistry, printing integration depth, and end-of-life design. These vectors are simultaneously enabling new applications and compressing margins for undifferentiated commodity production.
Digital printing integration is fragmenting the conventional pre-printed sleeve supply chain. Direct-to-sleeve inkjet systems are enabling pharmaceutical lot-specific serialization with 48-hour turnaround, bypassing cylinder-engraving lead times. Contract packagers in New Jersey and North Carolina are installing hybrid flexo-digital lines that switch between long-run beverage work and short-run clinical trial materials, collapsing the minimum economic order quantity from 50,000 units toward 5,000 units.
REACH Annex XIV phthalate restrictions are redirecting European pharmaceutical sleeve demand toward glycol-modified PET and oriented polyolefin substrates. ECHA substance evaluation timelines are compressing formulation windows, forcing compounders to pre-certify alternative plasticizer packages before regulatory deadlines. German converters are qualifying bio-based PET feedstocks from renewable ethylene glycol to maintain clarity performance while satisfying CSRD Scope 3 disclosure requirements.
Refill-commerce packaging formats are displacing single-use containers in premium personal care channels. Korean beauty brands are specifying perforated tear-strip shrink bands for aluminum bottle systems that survive 50+ use cycles. Procurement at these houses now weights total cost of ownership over unit sleeve price, favoring converters with in-house structural design capability and rapid prototyping services.
Shrink Bands Market Segmentation
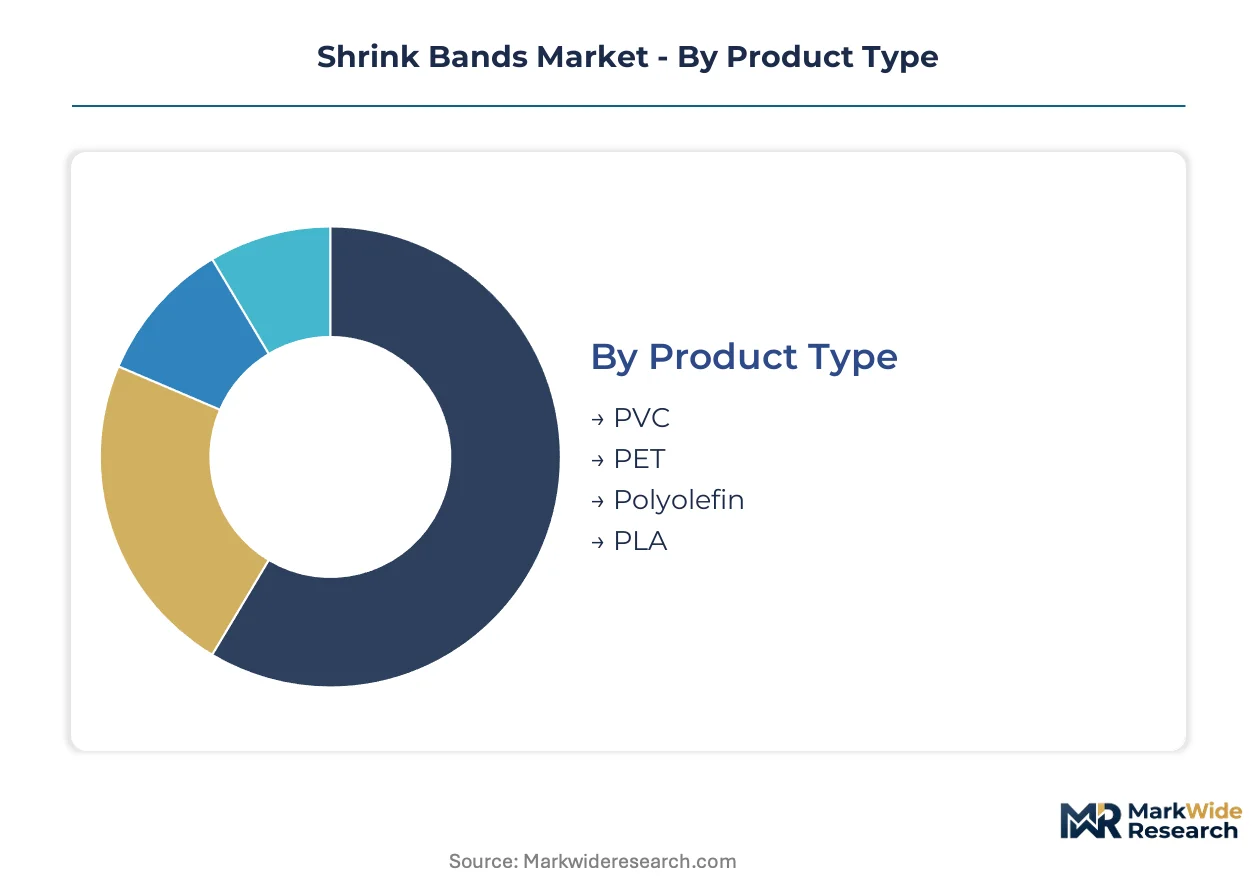
Shrink band segmentation reveals how substrate chemistry, end-use compliance, and supply chain configuration create distinct competitive arenas. Each dimension carries divergent margin profiles and regulatory exposure that reshape converter investment priorities.
Product Type:
FDA serialization mandates and REACH plasticizer restrictions are bifurcating demand between legacy PVC and next-generation substrates with cleaner compliance profiles.
- PVC:Chlorinated polymer formulations with phthalate plasticizers dominate legacy food packaging where unit economics override sustainability metrics. FDA food-contact approvals and established heat-sealing infrastructure preserve installed base demand despite EPR headwinds.
- PET:Glycol-modified copolyesters deliver pharmaceutical-grade clarity and dimensional stability for unit-level traceability codes. German contract packagers for biologics are scaling PET sleeve capacity to meet EMA serialization deadlines.
- Polyolefin:Oriented polypropylene and polyethylene grades offer superior recyclability alignment with California and New York extended producer responsibility frameworks.
- PLA:Polylactic acid biopolymer variants serve premium personal care channels where Korean and Japanese cosmetic houses mandate compostable end-of-life pathways.
PVC handles the majority of throughput; PET is expanding most quickly on share as pharmaceutical traceability requirements tighten.
Application:
End-use concentration determines specification intensity, with pharmaceutical and personal care segments commanding premium pricing for validated supply chains.
- Food Packaging:Cost-optimized PVC sleeves for jarred sauces and condiments prioritize seal integrity over print sophistication. Midwest US co-packers for private-label retailers run high-volume rotary sealers with minimal changeover flexibility.
- Beverage Packaging:PET-glycol modified formulations for carbonated and non-carbonated bottles require precise shrink-force control to prevent container distortion during steam tunnel processing.
- Pharmaceutical Packaging:High-clarity printable grades with tamper-evident perforations serve injectable therapies and oral solid dosage forms. CDSCO serialization mandates for Indian-exported generics are accelerating local sleeve printing investment.
- Personal Care Packaging:Perforated tear-strip configurations for aluminum refill bottles in Korean beauty markets emphasize total cost of ownership over unit sleeve price.
Food packaging retains volume leadership; pharmaceutical packaging is gaining share fastest on regulatory pull-through.
Thickness:
Gauge selection balances material cost against mechanical performance, with pharmaceutical and beverage applications driving specification migration toward thinner, higher-performance films.
- Less than 50 Microns:Ultra-thin oriented polyolefin films for lightweight beverage bottles and sample-size pharmaceutical vials. Japanese converters are qualifying sub-40 micron grades for mineral water applications to reduce plastic tax exposure.
- 50-100 Microns:Standard pharmaceutical and personal care specifications offering puncture resistance without excessive material consumption. New Jersey contract packagers specify 75-micron PET for clinical trial materials requiring 48-hour digital print turnaround.
- 100-200 Microns:Heavy-duty food jar applications and industrial chemical containers where abuse resistance dominates material efficiency considerations.
- More than 200 Microns:Specialty drum and pail labeling for hazardous materials transport compliance.
50-100 micron specifications handle the majority of throughput; sub-50 micron grades are climbing the fastest on lightweighting mandates.
Distribution Channel:
Channel structure reflects customer scale and specification complexity, with direct relationships dominating pharmaceutical validation requirements.
- Online:E-procurement platforms serving small-batch personal care startups and craft beverage producers with low minimum order quantities. Digital-native brands in Brooklyn and Austin specify custom-printed sleeves through web-based configurators.
- Retail:Big-box and club store private-label programs for standardized food and beverage applications with predictable volume profiles.
- Wholesale:Distributor networks for regional beverage bottlers and mid-tier food processors lacking direct converter relationships.
- Direct Sales:Dedicated account management for pharmaceutical majors requiring 18-to-8-month qualification timeline compression and integrated serialization support.
Direct sales handles the majority of pharmaceutical and high-specification throughput; online channels are expanding most quickly on small-batch digital printing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shrink band consumption patterns diverge sharply by geography: pharmaceutical serialization drives premium substrate adoption in regulated Western markets, while cost-optimized food packaging dominates emerging economies with less stringent tamper-evident mandates.
United States
FDA Drug Supply Chain Security Act compliance is elevating demand for high-clarity printable PET sleeves with integrated serialization capabilities. State-level extended producer responsibility laws in California and New York are accelerating design-for-recycling investments in mono-layer polyolefin structures. Contract packaging clusters in New Jersey and North Carolina are installing hybrid flexo-digital printing lines to serve compressed pharmaceutical qualification timelines.
Germany
EMA serialization deadlines for biologics are scaling contract packaging capacity for glycol-modified PET sleeves with cold-chain stability. REACH Annex XIV phthalate restrictions are redirecting pharmaceutical demand toward non-plasticizer polyolefin alternatives. Industrial concentrations in Bavaria and Baden-Württemberg host converters qualifying bio-based PET feedstocks to satisfy CSRD Scope 3 disclosure requirements.
India
CDSCO serialization mandates for exported generics are creating first-mover opportunities for local sleeve printing capacity investment. The country's national pharmaceutical regulator has tightened traceability requirements for contract manufacturers supplying regulated markets. Ahmedabad and Hyderabad pharmaceutical corridors are attracting converters establishing dedicated facilities for high-volume generic packaging.
China
NMPA drug traceability requirements are expanding domestic demand for tamper-evident sleeve configurations in injectable therapies. The Ministry of Ecology and Environment's dual carbon goals are pressuring converters toward lighter-gauge films and recyclable substrate alternatives. Yangtze River Delta packaging clusters are retrofitting extrusion lines to process oriented polyolefin grades with reduced shrink-force profiles.
South Korea
MFDS pharmaceutical serialization enforcement is pulling demand toward precision-printed sleeves with unit-level traceability codes. Korean beauty brands are specifying perforated tear-strip configurations for aluminum refill bottle systems in premium personal care channels. Seoul-Incheon manufacturing corridors are developing snap-fit sleeve designs optimized for 50+ use-cycle durability.
Shrink Bands Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in shrink band supply. Resin-to-sleeve operations command pricing power in pharmaceutical corridors where validation requirements create switching costs. Downstream converters without extrusion capability compete on digital printing agility and short-run flexibility. Strategic moves concentrate on backward integration into film extrusion and geographic expansion into Indian pharmaceutical packaging.
Among integrated North American operators, Berry Global Group anchors resin-to-sleeve positioning across pharmaceutical corridors. Amcor plc exemplifies European beverage-focused specialization through glycol-modified PET formulations. Fuji Seal International occupies a position within Asian personal care markets where precision-printed high-shrinkage configurations command premium positioning. These three represent divergent archetypes: captive resin integration, substrate-specific beverage optimization, and regional precision-printing specialization.
| Leading Market Players |
|---|
| Berry Global Group |
| Amcor plc |
| Fuji Seal International |
| CCL Industries |
| Clondalkin Group Holdings BV |
| Bemis Company |
| Huhtamaki |
| Klockner Pentaplast |
| LINTEC Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between pharmaceutical contract packagers and resin-to-sleeve converters lock in both PET glycol-modified feedstock access and price visibility across the 70°C to 100°C shrink initiation range. These arrangements insulate German biologics packagers from Gulf Coast hurricane-season volatility while exposing smaller downstream converters to spot-market resin premiums.
Pricing Analysis
Contract-based long-term offtake dominates pharmaceutical corridors where FDA validation timelines create switching costs, while spot-market transactions serve food packaging buyers with less specification intensity. Price differentiation separates FDA-serialization-grade PET sleeves from commodity PVC food-jar configurations. Cost compression in standard polyolefin grades is intensifying because REACH Annex XIV phthalate restrictions force rapid formulation transitions. Food packaging buyers exhibit highest price sensitivity; pharmaceutical majors prioritize supply security over unit cost.
Supply Chain Analysis
Inventory buffers for PET glycol-modified resin stretch 8-12 weeks at North American converters, compressing to 4-6 weeks for polyolefin alternatives with more diversified feedstock origins. Supply concentrates in the United States, Germany, and China, with extrusion-capable film production drawing from concentrated Gulf Coast petrochemical corridors. Raw material dependencies include ethylene glycol, purified terephthalic acid, and oriented polyolefin resins. Single-source vulnerability around glycol-modified PET feedstock creates exposure to weather-related disruption. Distribution runs through direct sales for pharmaceutical validation requirements and wholesale networks for regional beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shrink bands market sits in early-cycle expansion as pharmaceutical serialization mandates penetrate Indian and Chinese export corridors, pulling substrate demand toward high-clarity printable grades with integrated traceability capabilities.
For Market Incumbents: Secure backward integration into blown film extrusion to defend margin position against resin price volatility and qualification-timeline compression. Captive PET glycol-modified capacity insulates against Gulf Coast supply disruption while accelerating pharmaceutical customer onboarding. Invest in hybrid flexo-digital printing lines to capture small-batch clinical trial demand with 48-hour turnaround capabilities.
For New Entrants and Emerging Players: Anchor in Indian pharmaceutical packaging corridors where CDSCO serialization mandates for exported generics outpace local converter capacity expansion. Target sleeve printing facilities in Ahmedabad and Hyderabad corridors with dedicated high-volume generic packaging lines. Lead with rapid prototyping services and structural design capability for aluminum refill bottle systems in Korean beauty markets.
For Investors and Strategic Acquirers: Extrusion-capable mid-tier converters with pharmaceutical validation credentials represent the most defensible acquisition profile. Long-term viability hinges on EPR framework alignment and digital watermark integration for automated materials recovery. Watch for state-level extended producer responsibility implementation in California and New York as inflection signals for mono-layer sleeve demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive PET glycol-modified supply secures pharmaceutical validation pipelines against Gulf Coast disruption. |
| Hybrid Flexo-Digital Printing Installation | New Jersey and North Carolina contract packagers collapse minimum order quantities from 50,000 toward 5,000 units. |
| Digital Watermark Integration | Covert machine-readable markers embedded during extrusion enable automated sortation at EU materials recovery facilities. |
| Geographic Expansion into Indian Pharmaceutical Corridors | CDSCO serialization mandates for exported generics outpace local sleeve printing capacity in Ahmedabad and Hyderabad. |
| Bio-Based PET Feedstock Qualification | German converters satisfy CSRD Scope 3 disclosure requirements through renewable ethylene glycol sourcing. |
Research Methodology
Cross-validation between primary interviews with extrusion engineers, pharmaceutical packaging procurement managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation. Secondary sources include FDA Drug Supply Chain Security Act guidance documents, ECHA REACH Annex XIV substance evaluations, CDSCO serialization circulars, and SEC 10-K filings from integrated resin-to-sleeve operators. Bottom-up triangulation across substrate chemistry segments and top-down reconciliation against end-use demand patterns ensures internal consistency.
Sensitivity analysis around resin price volatility and regulatory timeline compression tests forecast robustness across the projection horizon. Segmentation dimensions modeled include substrate chemistry, application vertical, thickness specification, and distribution channel structure. CAGRs derive from trend extrapolation of pharmaceutical serialization adoption curves and EPR framework penetration. Industry-specific inputs encompass FDA validation timeline compression from 18 months to 8 months and REACH plasticizer substitution cost trajectories.
Material uncertainties — regulatory deadline delays, hurricane-season supply disruption, and mechanical recycling infrastructure gaps for multi-layer laminates — sit outside the modeled envelope. Forecasts reflect documented assumptions about serialization mandate enforcement intensity and EPR implementation pacing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Drum Plugs Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
PCR Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Flapper Caps Market