
 Latin America Biopesticide Market | 2026-2036
Latin America Biopesticide Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Biopesticide Market Foresight
Synthetic chemical active ingredients is decoupling from premium crop protection economics across Latin America's major agricultural zones. Bayer CropScience AG leverages its microbial strain libraries to anchor biological solutions within integrated pest management portfolios. Bioceres Crop Solutions sustains Argentine market presence through specialized seed-treatment biologicals tied to regional crop rotations.
Latin America biopesticides comprise living organisms or naturally derived compounds formulated to suppress agricultural pests through biological mechanisms such as antagonism, parasitism, or induced systemic resistance, typically requiring colony-forming unit counts above 10^9 CFU per milliliter for viable field efficacy. These agents serve commercial agriculture by reducing synthetic pesticide residues destined for export markets with strict maximum residue limits. Microbial formulations dominate current volume given established fermentation infrastructure and reproducible quality controls, while bioinsecticide demand accelerates fastest as fall armyworm pressure intensifies across tropical maize belts. Liquid formulations capture the largest margin pools due to compatibility with existing spray equipment and longer shelf stability under variable storage conditions.
Brazil's ANVISA governs toxicological evaluations for biological crop protection products, while Argentina's national agricultural regulator oversees field efficacy trials and environmental fate assessments for commercial registration. The EU Green Deal's Farm to Fork pesticide reduction targets reshape Latin American export-oriented farming, compelling growers to adopt residue-compliant biological alternatives. Stakeholders must monitor regulatory harmonization progress across MERCOSUR states and align R&D pipelines with accelerating importer sustainability protocols.
Market Dynamics
EU Green Deal pesticide reduction mandates are compressing Latin American export agriculture into residue-compliant biological systems, forcing rapid reconfiguration of crop protection procurement across Brazil's Cerrado and Argentina's Pampas.
Growth Catalysts
- ANVISA Registration Streamlining:Brazil's toxicological evaluation reforms slash biopesticide approval timelines from 36 to 18 months, accelerating commercial field deployment for microbial formulations.
- Soybean Export Compliance:German and Dutch importers enforce sub-0.01 ppm residue thresholds on oilseed shipments, compelling Mato Grosso growers to substitute synthetic pyrethroids with Bacillus thuringiensis-based bioinsecticides.
- Fermentation Infrastructure Scaling:Automated bioreactor networks in São Paulo state achieve 10^12 CFU batch consistency, collapsing per-unit production costs for entomopathogenic fungal products.
Market Restraints
- Petrochemical Input Volatility:Polyethylene glycol and surfactant prices tied to Gulf Coast naphtha benchmarks create 15-20% quarterly formulation cost swings, squeezing margin structures for liquid microbial concentrates.
- Cold Chain Concentration Risk:Shelf-stability requirements above 4°C concentrate distribution through three São Paulo-based logistics operators, creating single-point failure exposure for temperature-sensitive Trichoderma harzianum products.
- Synthetic Chemistry Substitution:Generic neonicotinoid re-registration in Argentina's northern provinces undercuts biological pricing by 40-60% in non-export soybean segments, limiting penetration beyond premium residue-sensitive channels.
Strategic Opportunities
- Colombian Coffee Highlands:Antioquia and Caldas department cooperatives face imminent EU deforestation regulation compliance deadlines, opening biological leafminer control contracts currently served by organophosphate legacy products.
- Drone Application Convergence:UAV-mounted electrostatic spray systems paired with ultra-low-volume bioinsecticide formulations enable 2.5-hectare-per-minute coverage rates, unlocking precision deployment economics previously unattainable with ground rigs.
- MERCOSUR Harmonization Protocol:Pending mutual recognition agreements for microbial strain registrations would eliminate redundant efficacy trials, collapsing multi-country market entry costs for Argentine-developed biocontrol agents.
Industry Challenges
- Microbial Formulation Expertise Gap:Latin American universities graduate fewer than 200 industrial microbiologists annually with fermentation-scale competency, forcing manufacturers to import Brazilian or Spanish technical staff for bioprocess optimization roles.
- Field Efficacy Validation Bottlenecks:SENASA Argentina mandates three-season replicated trials for novel biocontrol strains, extending registration timelines beyond patent protection windows for genetically modified microbial variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Biopesticide Market |
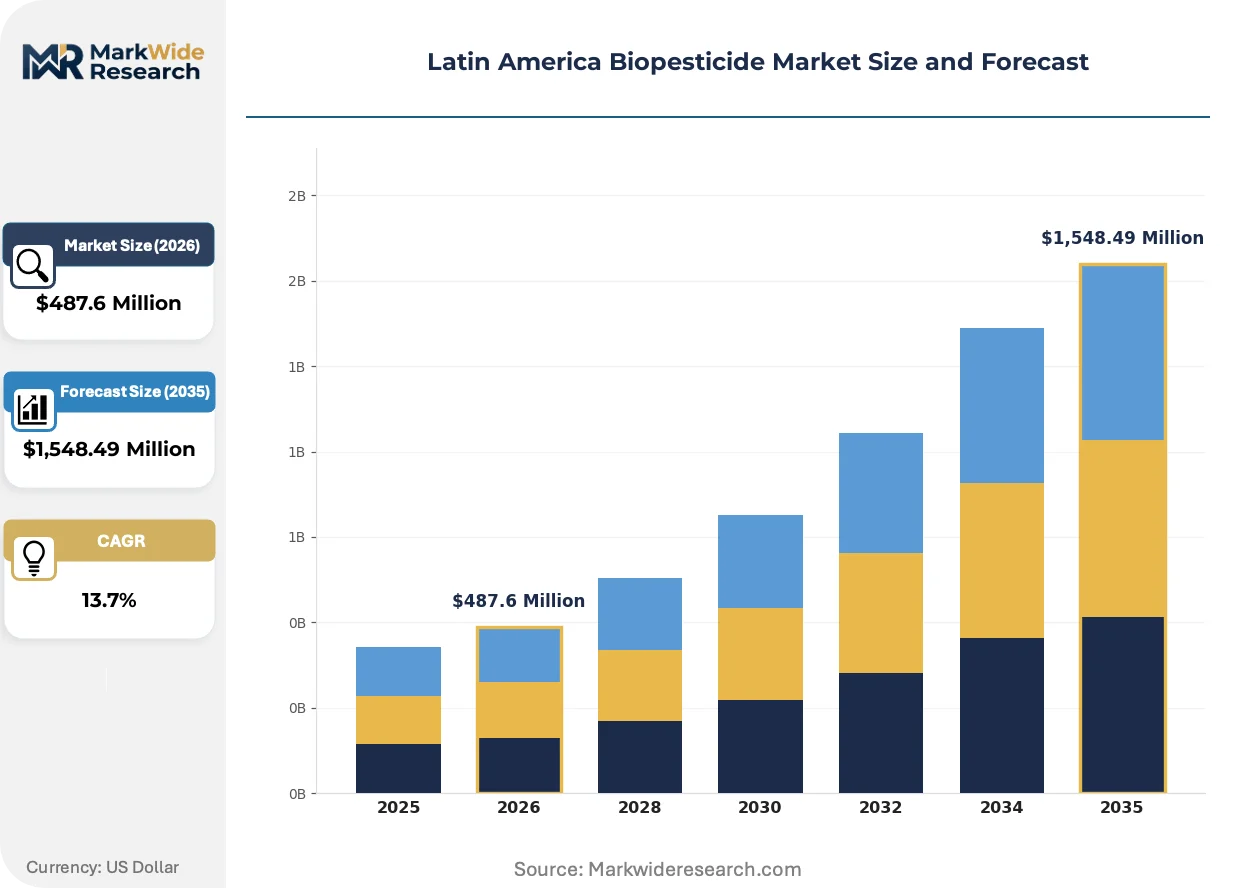
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,548.49 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Biofungicide, Bioinsecticide, Bioherbicide Formulation: Liquid, Powder, Granules, Emulsifiable Concentrate Crop Type: Cereals, Fruits, Vegetables, Oilseeds Sales Channel: Direct Sales, Distributors, Online Retail, Nurseries |
| Companies Covered | Bayer CropScience AG, Bioceres Crop Solutions, Corteva Agriscience, Marrone Bio Innovations, Valent Biosciences Corporation, BASF SE, Sumitomo Chemical Co., Ltd., Andermatt Biocontrol, Koppert Biological Systems, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Biopesticide Market Shifts & Advancements
Biological crop protection is undergoing rapid technical standardization as fermentation reproducibility and formulation stability converge with precision application hardware, compressing the performance gap against synthetic chemistry in high-volume row-crop systems.
Lyophilized microbial concentrates are consolidating field efficacy consistency across variable storage conditions. These stabilized powder formulations maintain 10^9 CFU viability through 24-month shelf cycles without refrigeration. Large-scale maize operations in Paraná state adopt them at 3x prior-year rates. The technology is consolidating supplier power around three Brazilian fermentation houses with captive freeze-drying capacity.
EU Green Deal Farm to Fork pesticide reduction targets reshape Latin American export compliance architecture. The framework mandates 50% synthetic pesticide reduction by 2030 for agricultural imports into member states. Brazilian soybean cooperatives in Rio Grande do Sul accelerate biological integration programs to preempt certificate-of-origin rejections at Rotterdam port terminals.
Buyer procurement is compressing toward residue-guaranteed supply contracts with biological performance clauses. Argentine wheat exporters to UK flour mills now specify maximum synthetic residue thresholds below 0.05 ppm, with biopesticide application documented via blockchain-verified spray logs. This specification shift concentrates purchasing through vertically integrated grain handlers with captive biological advisory services.
Latin America Biopesticide Market Segmentation
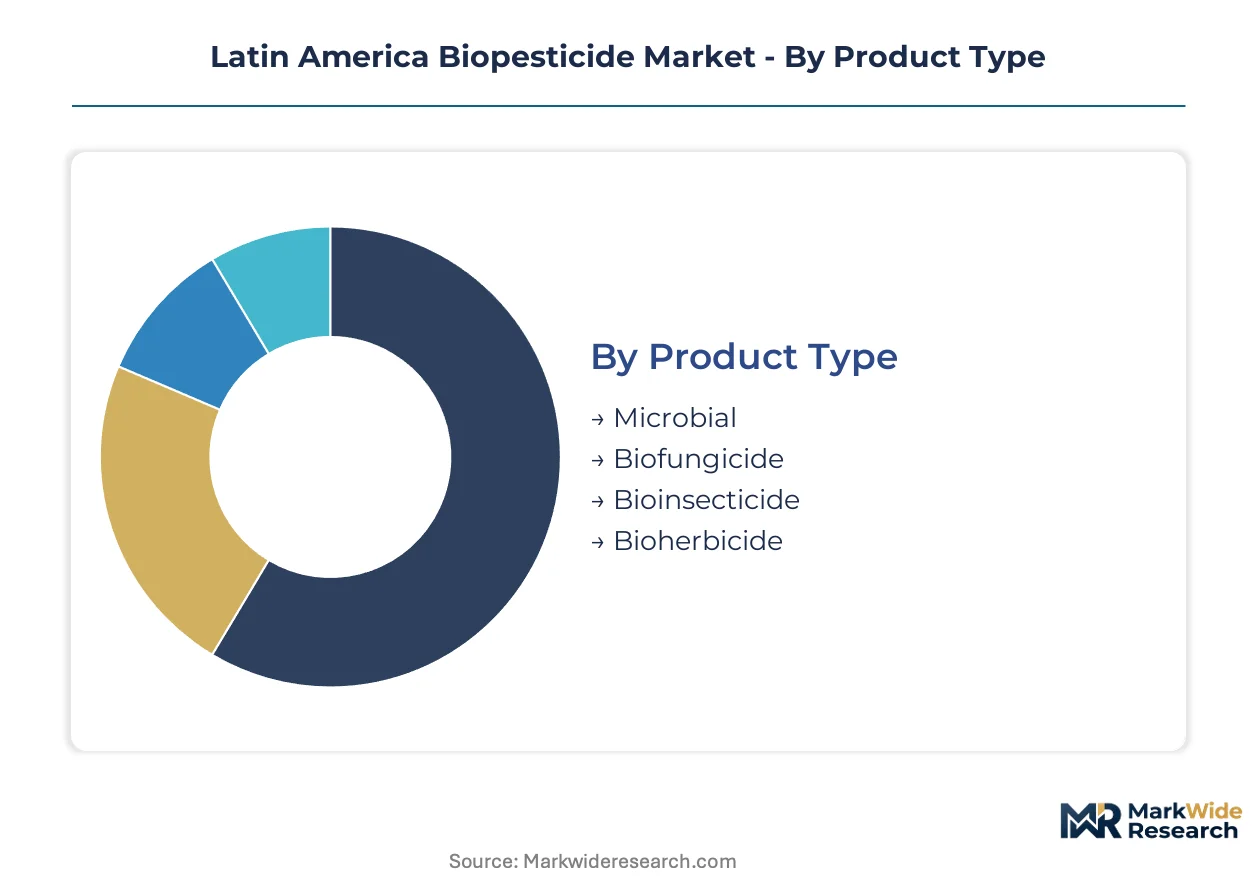
Biopesticide procurement in Latin America fragments across four structural dimensions. Each category reflects distinct technical requirements, distribution economics, and regulatory exposure that shape supplier positioning and farmer adoption patterns.
Product Type:
Standardization dominates microbial formulations while specialized biocontrol agents demand customized fermentation protocols and strain-specific registration pathways.
- Microbial:Living organisms including bacteria, fungi, and viruses formulated at colony-forming unit counts above 10^9 CFU per milliliter. São Paulo fermentation houses supply Brazil's Cerrado soybean belt where residue compliance pressures concentrate demand for Bacillus thuringiensis products.
- Bioinsecticide:Entomopathogenic agents targeting fall armyworm and soybean looper populations. Paraná maize operations adopt these at accelerating rates as pyrethroid resistance spreads and EU import thresholds tighten below 0.01 ppm.
- Biofungicide:Trichoderma and Bacillus-based formulations suppressing soilborne pathogens in high-value vegetable systems.
- Bioherbicide:Phytopathogenic microbial strains and natural compound extracts for weed suppression in organic certification programs.
Most installed capacity flows through Microbial. Expansion is steepest in Bioinsecticide.
Formulation:
Cost tiers separate premium stabilized concentrates from commodity-grade raw fermentation broths, with liquid formats commanding margin premiums through equipment compatibility advantages.
- Liquid:Aqueous suspensions and oil-based concentrates compatible with existing spray equipment across Brazil's mechanized row-crop operations. Longer shelf stability under variable storage conditions supports distribution through São Paulo-based cold chain networks.
- Powder:Lyophilized microbial concentrates maintaining 10^9 CFU viability through 24-month cycles without refrigeration. Large-scale maize operations in Paraná state adopt these at triple prior-year rates.
- Granules:Solid carrier-based formulations for soil incorporation in perennial crop systems.
- Emulsifiable Concentrate:Oil-in-water systems enabling ultra-low-volume application through drone-mounted electrostatic sprayers.
Liquid formulations absorb the majority of production volume. Powder formats are climbing the fastest as lyophilization capacity scales.
Crop Type:
Application intensity varies sharply: export-oriented oilseeds drive residue-sensitive biological adoption while domestic cereals tolerate higher synthetic chemical thresholds.
- Oilseeds:Soybean operations across Mato Grosso and Rio Grande do Sul integrate biopesticides preemptively to secure EU certificate-of-origin compliance. German and Dutch importers enforce sub-0.01 ppm residue thresholds that compel Bacillus thuringiensis substitution for synthetic pyrethroids.
- Fruits:Citrus and grape operations in Argentina's Mendoza province face SENASA-mandated pre-export residue screening. Blockchain-verified spray logs document biological application for UK flour mill contracts specifying maximum synthetic thresholds below 0.05 ppm.
- Vegetables:High-value tomato and pepper systems in Sinaloa, Mexico utilize biofungicides against Phytophthora pressure.
- Cereals:Wheat and maize in non-export channels retain synthetic chemistry dominance where generic neonicotinoid pricing undercuts biological alternatives by 40-60%.
Oilseeds channel the largest absolute volume. Fruits are gaining share fastest as EU deforestation regulation deadlines approach.
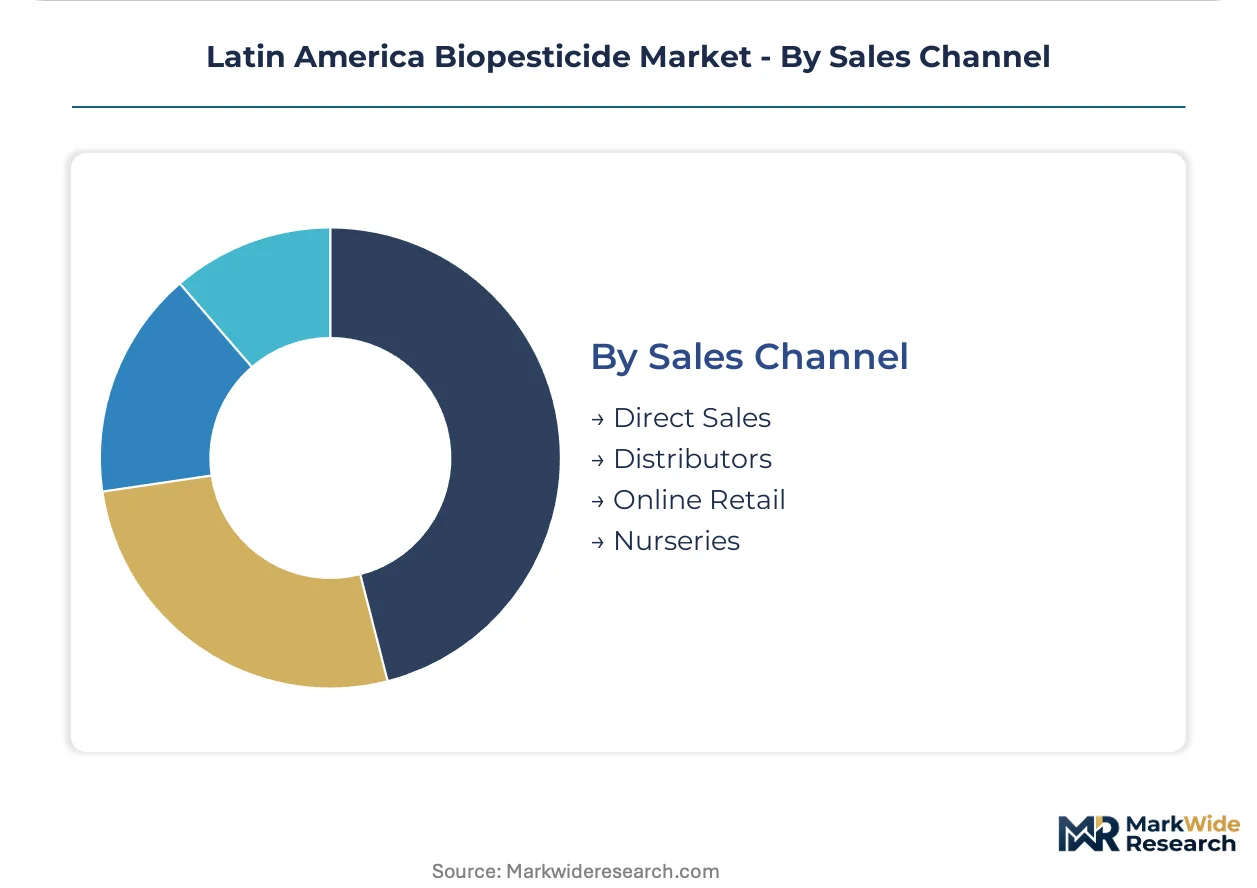
Sales Channel:
Customer type stratification concentrates high-touch advisory through distributors while direct sales capture vertically integrated plantation operators with captive agronomy teams.
- Distributors:Regional agrochemical networks across Brazil's agricultural belts combine biological products with synthetic portfolios and application equipment. These intermediaries aggregate demand from Mato Grosso cooperatives and provide technical support for microbial handling protocols.
- Direct Sales:Large-scale operators in Argentina's Pampas and Brazil's Cerrado procure through dedicated account structures. Vertically integrated grain handlers specify residue-guaranteed supply contracts with biological performance clauses.
- Nurseries:Seedling producers incorporating biocontrol into propagation protocols for transplant-ready vegetable stock.
- Online Retail:E-commerce platforms serving smallholder segments with standardized microbial formulations and digital application guidance.
Distributors maintain the deepest installed relationships. Direct Sales is expanding most quickly as procurement centralizes through major grain handlers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado agricultural belt commands the dominant share of Latin American biopesticide deployment, driven by soybean export compliance pressures and ANVISA regulatory modernization that compresses product registration timelines.
Brazil
Mato Grosso soybean cooperatives substitute synthetic pyrethroids with Bacillus thuringiensis bioinsecticides to meet German and Dutch sub-0.01 ppm residue thresholds. ANVISA toxicological evaluation reforms slash approval timelines from 36 to 18 months, accelerating commercial field deployment. São Paulo fermentation houses supply stabilized microbial concentrates to mechanized operations across the Cerrado and southern agricultural belts.
Argentina
Pampas grain handlers specify residue-guaranteed supply contracts with biological performance clauses for UK flour mill exports. SENASA mandates three-season replicated trials for novel biocontrol strains, extending registration timelines beyond patent protection windows for genetically modified microbial variants. Buenos Aires-based technical teams optimize fermentation-scale bioprocesses for regional crop rotations.
Mexico
Sinaloa vegetable systems deploy biofungicides against Phytophthora pressure in high-value tomato and pepper operations. The country's national agricultural regulator oversees field efficacy trials for commercial registration of microbial formulations. Guadalajara distribution networks channel standardized products to smallholder segments through emerging e-commerce platforms.
Colombia
Antioquia and Caldas coffee cooperatives face imminent EU deforestation regulation compliance deadlines, opening biological leafminer control contracts. The national agricultural authority evaluates environmental fate assessments for biocontrol product registration. Medellín-based advisory services integrate biological pest management into cooperative procurement protocols.
Chile
Central Valley fruit exporters adopt biofungicides to preempt EU certificate-of-origin rejections at Rotterdam terminals. The national agricultural service conducts toxicological evaluations for biological crop protection products. Santiago technical centers validate microbial formulation stability for temperature-sensitive distribution through concentrated logistics networks.
Latin America Biopesticide Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and fermentation infrastructure, creating a tiered structure where multinational agrochemical portfolios anchor premium positions while specialized biological houses capture residue-sensitive niches. Market structure consolidates around three strategic archetypes: diversified agrochemical conglomerates with microbial strain libraries, dedicated biocontrol specialists with captive fermentation capacity, and regional seed-treatment formulators tied to local crop rotations. Dominant competitive moves include backward integration into bioreactor networks and technology licensing partnerships that collapse multi-country market entry costs.
Within the diversified agrochemical tier, Bayer CropScience AG and BASF SE exemplify global players leveraging microbial strain libraries to anchor biological solutions within integrated pest management portfolios. Bioceres Crop Solutions occupies a position as a regional specialist, sustaining Argentine market presence through technical proximity to Pampas grain handlers and specialized formulation expertise tied to regional agricultural systems.
| Leading Market Players |
|---|
| Bayer CropScience AG |
| Bioceres Crop Solutions |
| Corteva Agriscience |
| Marrone Bio Innovations |
| Valent Biosciences Corporation |
| BASF SE |
| Sumitomo Chemical Co., Ltd. |
| Andermatt Biocontrol |
| Koppert Biological Systems |
| Others |
Supply & Pricing Matrix
Polyethylene glycol and surfactant costs tied to Gulf Coast naphtha benchmarks cascade through Latin American biopesticide pricing tiers, with quarterly formulation cost swings of 15-20% squeezing margin structures for liquid microbial concentrates destined for Brazil's mechanized soybean operations.
Pricing Analysis
Input-cost pass-through from petrochemical feedstocks dominates margin compression in liquid microbial concentrates, with polyethylene glycol and surfactant volatility creating 15-20% quarterly formulation cost swings. Three-tier pricing structure across premium lyophilized powders, standard liquid suspensions, and economy-grade raw fermentation broths separates residue-sensitive export growers from domestic cereal producers. Pricing pressure stems from generic neonicotinoid re-registration in Argentina's northern provinces, which undercuts biological alternatives by 40-60% in non-export soybean segments. Domestic cereal growers exhibit highest price sensitivity, while EU-exporting cooperatives in Mato Grosso tolerate premium tiers for residue compliance certainty.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive Trichoderma harzianum products concentrate through three São Paulo-based cold chain operators, creating single-point failure exposure when shelf-stability requirements above 4°C are breached. Geographic supply concentration centers on Brazil, Argentina, and Mexico, with São Paulo fermentation houses and Buenos Aires technical teams anchoring regional production. Raw material dependencies draw from Gulf Coast petrochemical feedstocks, Brazilian sugarcane-derived fermentation substrates, and imported lyophilization equipment. Single-source vulnerability runs through concentrated cold chain logistics for temperature-stabilized products. Distribution runs through regional agrochemical networks combining biological portfolios with synthetic crop protection and application equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American biopesticide markets function as a geographic-arbitrage play between ANVISA's streamlined 18-month registration timelines in Brazil and SENASA's extended three-season trial mandates in Argentina, compressing time-to-revenue for microbial formulations developed in São Paulo state.
For Market Incumbents: Extend formulation stability advantages by investing in captive lyophilization capacity, as temperature-sensitive logistics create service differentiation against generic competitors. Backward integration into automated bioreactor networks in São Paulo state secures 10^12 CFU batch consistency, defending against emerging fermentation houses in Mexico's Guadalajara corridor. For New Entrants and Emerging Players: The 40-60% price gap between premium residue-compliant biologicals and economy-grade synthetic chemistry in Argentina's domestic cereals opens white-space targeting of mid-tier cooperatives seeking EU pre-certification. Colombia's Antioquia coffee highlands present the most penetrable geography, with imminent EU deforestation regulation deadlines displacing organophosphate legacy products. A drone-application bundling strategy with UAV-mounted electrostatic spray systems captures precision deployment economics previously unattainable with ground rigs. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation-scale expertise scarcity meets accelerating residue compliance mandates across MERCOSUR export agriculture. Long-term viability over the next decade hinges on regulatory harmonization progress and cold chain infrastructure buildout. Acquisition targets should display captive bioreactor capacity and ANVISA registration track records. Practitioners should monitor EU Green Deal pesticide reduction enforcement at Rotterdam port terminals as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Captive freeze-drying infrastructure in São Paulo eliminates cold chain dependency for Trichoderma products. |
| ANVISA Registration Acceleration | Pre-approval consultation pathways compress toxicological evaluation timelines for novel microbial strains. |
| Drone Application Partnership | UAV-mounted electrostatic systems enable 2.5-hectare-per-minute bioinsecticide coverage in Paraná maize. |
| MERCOSUR Harmonization Lobbying | Mutual recognition agreements for microbial strain registrations collapse multi-country market entry costs. |
| Blockchain Spray Log Integration | Verified application documentation satisfies UK flour mill contracts specifying sub-0.05 ppm residue thresholds. |
Research Methodology
Multiple input streams — fermentation facility technical assessments, ANVISA registration database analysis, and EU import compliance documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant managers at São Paulo bioreactor facilities, procurement leads at Argentine grain cooperatives, regulatory affairs specialists navigating SENASA trial mandates, and distribution channel partners across Brazil's agricultural belts informed operational dynamics. Secondary validation drew from ANVISA toxicological evaluation filings, SENASA field efficacy trial records, EU Green Deal Farm to Fork policy documents, and Brazilian customs trade data on microbial formulation imports.
Cross-referencing historical adoption patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, formulation stability tier, crop-specific residue sensitivity, and sales channel concentration. CAGRs were derived through iterative reconciliation of supply-side capacity expansion timelines with demand-pull from EU importer compliance deadlines. Industry-specific forecast inputs incorporated ANVISA registration reform implementation pace and cold chain logistics infrastructure buildout rates.
Caveats apply where regulatory enforcement intensity at EU port terminals or petrochemical input cost volatility could materially shift the outlook. Forecasts reflect assumptions regarding MERCOSUR harmonization progress and sustained EU Green Deal pesticide reduction targets. Practitioners should monitor Rotterdam certificate-of-origin rejection rates and Gulf Coast naphtha benchmark movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
India Biomass Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Plant-Based Biologics Market