
 Europe Pipeline Security Market | 2026-2036
Europe Pipeline Security Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pipeline Security Market Foresight
European pipeline security capacity is decoupling from legacy perimeter-defense models as operators confront hybrid threats to subsea and overland infrastructure. Siemens AG leverages its industrial automation heritage to anchor control-system security for major trunk lines across Germany and the Netherlands. Honeywell International Inc. competes through integrated SCADA-firewall architectures that sustain operator confidence in high-consequence areas. BAE Systems differentiates via sovereign-cyber capabilities that dominate defense-adjacent pipeline contracts in the United Kingdom.
Europe pipeline security encompasses physical and cyber protection systems for hydrocarbon and utility transport networks, incorporating fiber-optic intrusion detection, drone-based aerial surveillance, and encrypted industrial-control protocols operating at sub-second response latencies. Monitoring Systems leads technology deployment as operators prioritize real-time leak and tamper detection over reactive investigation. Threat Detection is accelerating fastest where subsea cable and pipeline corridors face elevated sabotage risk. Oil & Gas Companies concentrate margin pools through bundled service contracts spanning installation, consulting, and continuous monitoring.
The EU Critical Entities Resilience Directive and national implementations by Germany's BSI and France's ANSSI mandate systematic risk assessments and redundancy planning for cross-border pipelines. CE marking under the Radio Equipment Directive and IEC 62443 cybersecurity standards shape product certification and market access for security hardware and software vendors. Stakeholders must weigh cloud-based deployment architectures against hybrid models as national data-sovereignty rules fragment procurement requirements across member states.
Market Dynamics
The EU Critical Entities Resilience Directive is forcing pipeline operators across Northern Europe to replace reactive maintenance with continuous monitoring architectures. This regulatory pressure is compressing procurement cycles and elevating cybersecurity from operational expense to board-level risk priority.
Growth Catalysts
- Nord Stream Aftermath:Subsea sabotage incidents have triggered emergency security upgrades across Baltic Sea corridor infrastructure. Operators in Germany and Denmark now mandate redundant detection layers for all cross-border lines.
- IEC 62443 Certification:Industrial cybersecurity standards for control systems are becoming de facto procurement filters. Vendors without certified products face automatic disqualification from German and Dutch trunk line tenders.
- Hydrogen Pipeline Repurposing:Existing natural gas networks require upgraded leak detection and material integrity systems to handle hydrogen blends. Conversion projects in the Netherlands and Spain are generating bundled security contracts.
Market Restraints
- Specialized Sensor Supply:Fiber-optic intrusion detection systems rely on photonic components concentrated among German and Swiss suppliers. Capacity constraints extend lead times for large-diameter pipeline deployments.
- CE Marking Complexity:The Radio Equipment Directive's evolving cybersecurity annexes create certification bottlenecks. Hardware vendors face retesting costs that deter mid-tier product lines from European market entry.
- Legacy SCADA Integration:Decades-old control protocols in Eastern European pipeline networks lack native encryption. Retrofit complexity slows security modernization in Polish and Romanian corridors.
Strategic Opportunities
- Portuguese Atlantic LNG Terminals:Iberian regasification expansion requires pipeline security for new hydrogen-ready import infrastructure. Early movers can anchor long-term service contracts before competitive saturation.
- AI-Drone Convergence:Machine-vision algorithms paired with autonomous aerial surveillance are reducing patrol costs for remote Alpine and Scandinavian pipeline segments. Technology bundlers capture premium positioning.
- EU Green Deal Funding:Just Transition Mechanism allocations for fossil fuel-dependent regions include security modernization clauses. Polish and Romanian operators can access subsidized upgrade programs.
Industry Challenges
- OT-Cybersecurity Talent Scarcity:Pipeline control systems require engineers fluent in both industrial automation and threat intelligence. Germany's BSI reports critical shortages in certified industrial security professionals.
- Cross-Border Data Sovereignty:Cloud-based monitoring platforms face fragmentation under national data localization rules. Operators spanning Germany, France, and Benelux must architect hybrid deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pipeline Security Market |
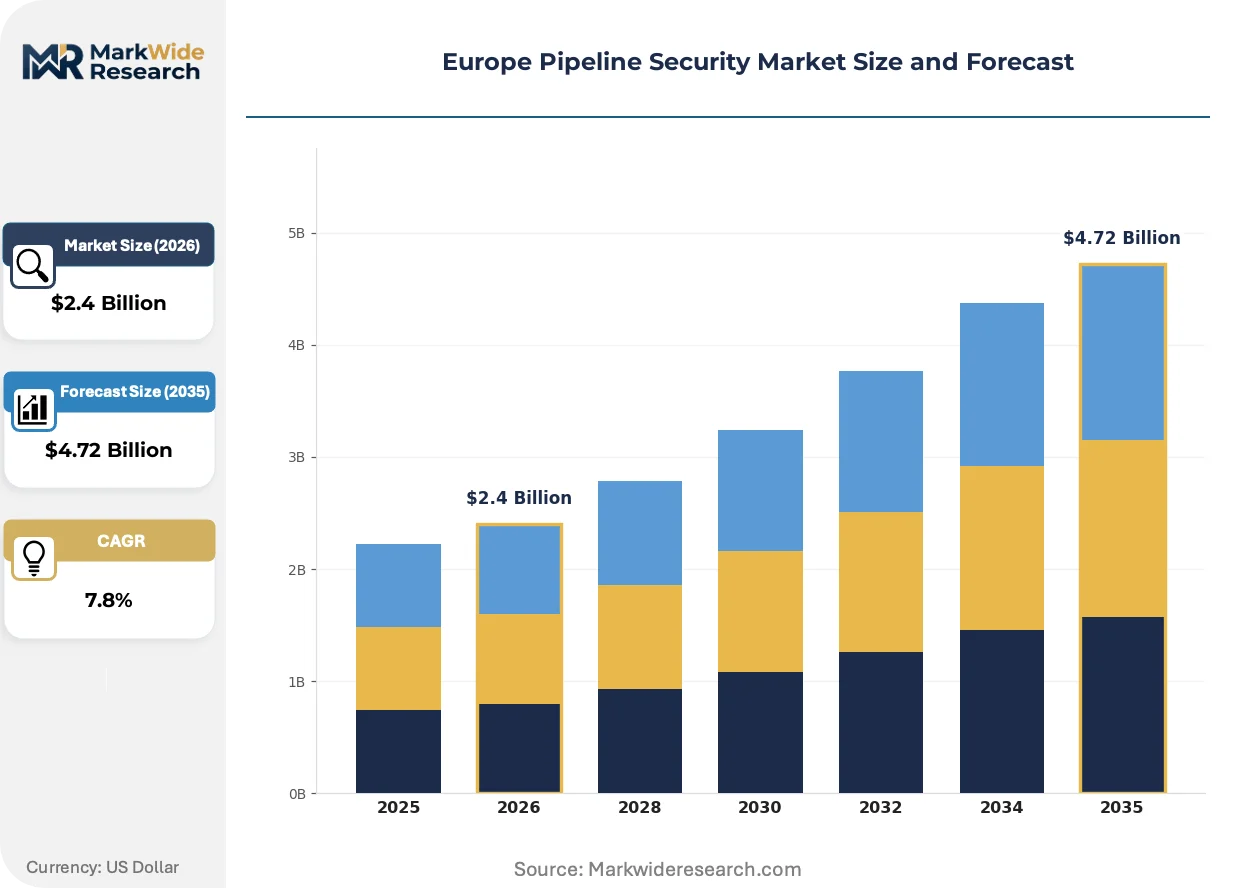
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monitoring Systems, Access Control, Threat Detection, Surveillance Solutions End User: Oil & Gas Companies, Utilities, Government Agencies, Industrial Facilities Service Type: Installation Services, Consulting Services, Maintenance Services, Monitoring Services Deployment: On-premises, Cloud-based, Hybrid, Embedded Systems |
| Companies Covered | Honeywell International Inc., General Electric Company, ABB Ltd., Rockwell Automation, Inc., Siemens AG, BAE Systems, Schneider Electric, Johnson Controls, Emerson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pipeline Security Market Shifts & Advancements
Distributed fiber-optic sensing is displacing point-source detectors across European trunk lines. Regulatory mandates for sub-second leak localization are compressing technology refresh cycles and elevating real-time analytics to core infrastructure.
Fiber-optic distributed acoustic sensing transforms standard telecom-grade cables into continuous vibration monitors. German operators along the Rhine corridor are retrofitting existing fiber conduits rather than laying dedicated security infrastructure. This reuse pattern is consolidating vendor relationships around integrated sensing-telecom providers and marginalizing standalone security hardware specialists.
France's ANSSI has extended critical infrastructure notification requirements to pipeline SCADA anomalies. Operators must now report suspected cyber intrusions within 24 hours or face operational license review. French and Belgian natural gas distributors are most affected, accelerating deployment of encrypted protocol gateways and segmented network architectures.
Service unbundling is fragmenting traditional turnkey contracts. Dutch and Norwegian operators now separate hardware procurement from continuous monitoring subscriptions. This purchasing pattern favors specialized security operations centers in The Hague and Oslo over bundled engineering-construction firms, redistributing margin toward pure-play monitoring providers.
Europe Pipeline Security Market Segmentation
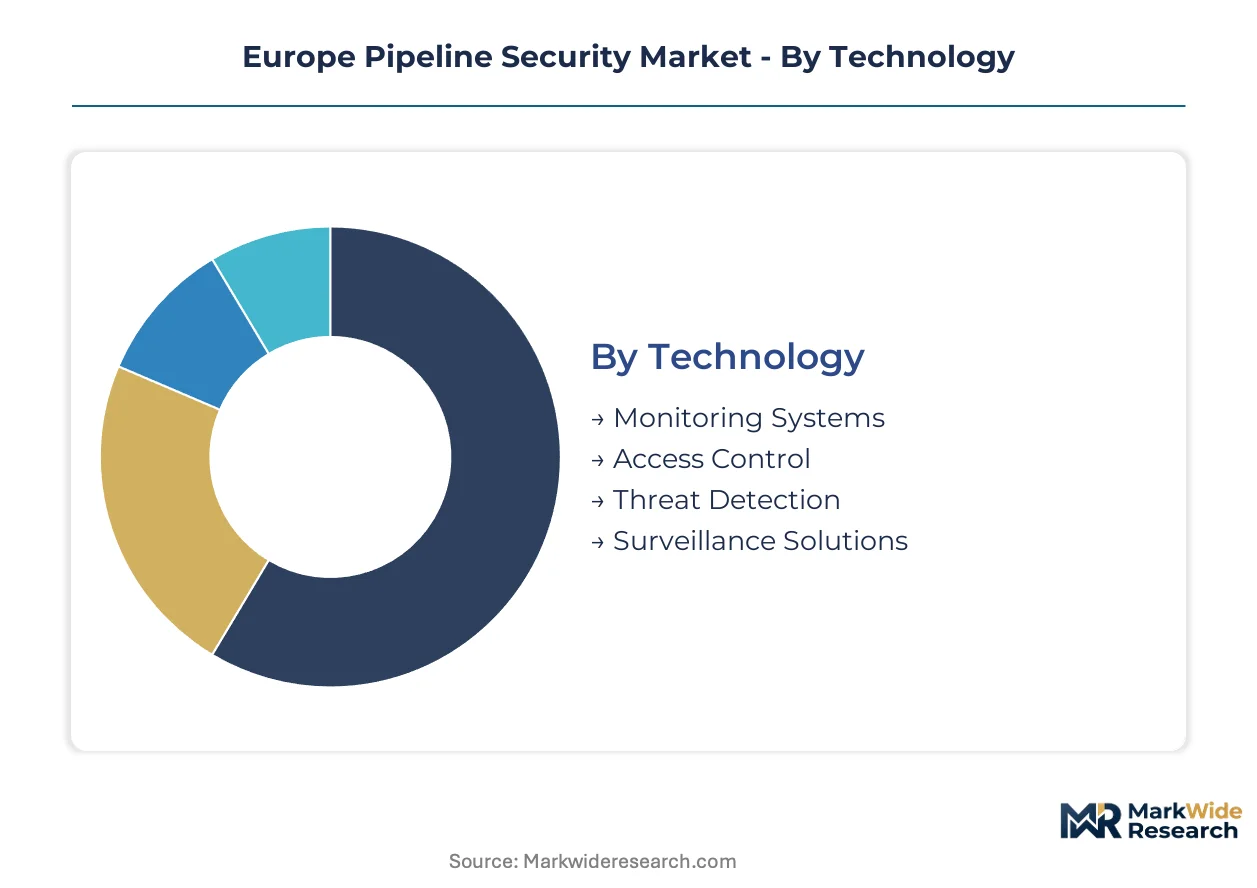
Pipeline security procurement in Europe fragments across four structural dimensions that determine contract value, renewal cadence, and vendor selection criteria. Technology choices anchor capital deployment, while service arrangements reshape margin distribution between hardware suppliers and ongoing operators.
Technology:
Capital intensity varies sharply across detection modalities, with distributed sensing networks demanding tenfold higher upfront investment than perimeter access controls.
- Monitoring Systems:Fiber-optic distributed acoustic sensing transforms standard telecom cables into continuous vibration monitors. German operators along the Rhine corridor prioritize retrofitting existing fiber conduits over dedicated security infrastructure, consolidating procurement around integrated sensing-telecom providers.
- Threat Detection:AI-enhanced anomaly detection for SCADA networks requires substantial software licensing and integration labor. French and Belgian natural gas distributors deploy encrypted protocol gateways to meet ANSSI's 24-hour incident notification mandate.
- Access Control:Biometric and credential-based entry systems for compressor stations and valve assemblies.
- Surveillance Solutions:Drone-based aerial patrols with machine-vision algorithms for remote Alpine and Scandinavian segments.
Most installed capacity flows through Monitoring Systems. Expansion is steepest in Threat Detection.
End User:
Procurement scale and compliance burden concentrate margin pools differently across buyer categories, with cross-border infrastructure operators commanding bundled multi-year contracts.
- Oil & Gas Companies:Integrated majors and midstream specialists operate high-consequence trunk lines requiring redundant detection layers. German and Danish operators now mandate dual-sensor coverage for all Baltic Sea corridor infrastructure following Nord Stream sabotage.
- Government Agencies:Defense-adjacent pipeline contracts in the United Kingdom favor sovereign-cyber capabilities with classified clearance requirements.
- Utilities:Natural gas and hydrogen distribution networks in the Netherlands and Spain.
- Industrial Facilities:Refinery and petrochemical complex interconnectors with internal pipeline networks.
Contract value peaks with Oil & Gas Companies. Procurement velocity is climbing fastest among Utilities converting hydrogen-ready infrastructure.
Service Type:
Revenue recurrence and margin stability separate installation-heavy project work from subscription-based monitoring arrangements.
- Monitoring Services:Continuous security operations center oversight with 24/7 anomaly response. Dutch and Norwegian operators now unbundle hardware from monitoring subscriptions, redistributing margin toward pure-play providers in The Hague and Oslo.
- Consulting Services:Risk assessments and redundancy planning mandated by Germany's BSI and France's ANSSI under the EU Critical Entities Resilience Directive.
- Installation Services:Physical deployment of sensors, cameras, and control system hardware.
- Maintenance Services:Scheduled calibration, firmware updates, and component replacement.
Revenue concentration sits with Monitoring Services. Consultancy margins are expanding most quickly under regulatory compliance pressure.
Deployment:
Data sovereignty requirements and legacy system constraints fragment architecture choices across national boundaries.
- Hybrid:Segmented architectures combining on-premises SCADA gateways with cloud analytics platforms. Operators spanning Germany, France, and Benelux must architect hybrid deployments to satisfy fragmented national data localization rules.
- On-premises:Air-gapped control systems for highest-consequence infrastructure with zero external connectivity.
- Cloud-based:Centralized monitoring platforms facing operational license risks where cross-border data flows are restricted.
- Embedded Systems:Edge-computing sensors with local processing for sub-second response latencies.
Hybrid architectures carry the largest committed project pipeline. Embedded Systems are gaining share fastest where real-time response is non-negotiable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance-cost arbitrage is reshaping procurement patterns as operators migrate security spending toward jurisdictions with streamlined certification pathways. German and Dutch regulators impose the steepest technical requirements, while Southern European markets offer faster deployment timelines for standardized systems.
Germany
Baltic Sea corridor operators mandate redundant detection layers following Nord Stream infrastructure sabotage. The Federal Office for Information Security enforces IEC 62443 certification as a de facto procurement filter for control system vendors. The Rhine corridor industrial cluster around Frankfurt and Düsseldorf concentrates fiber-optic retrofit projects that repurpose existing telecom infrastructure.
Netherlands
Hydrogen pipeline conversion projects generate bundled security contracts for leak detection and material integrity systems. The Radio Equipment Directive's CE marking requirements shape hardware certification timelines for North Sea terminal operators. The Hague hosts specialized security operations centers that capture unbundled monitoring subscriptions from Dutch and Norwegian pipeline operators.
France
The National Cybersecurity Agency mandates 24-hour incident notification for SCADA anomalies affecting natural gas distributors. Encrypted protocol gateways and segmented network architectures dominate procurement in the Paris basin and Belgian border corridors. The Lyon industrial region anchors deployment of AI-enhanced threat detection for high-consequence trunk lines.
United Kingdom
Defense-adjacent pipeline contracts favor sovereign-cyber capabilities with classified clearance requirements. The North Sea oil and gas infrastructure cluster around Aberdeen drives demand for integrated physical-cyber protection systems. London-based security consultancies capture margin from risk assessment mandates under national critical infrastructure regulations.
Poland
Just Transition Mechanism allocations subsidize security modernization for fossil fuel-dependent pipeline networks. Legacy SCADA protocols lacking native encryption slow retrofit projects in Eastern European corridors. The Silesian industrial region concentrates hydrogen-ready infrastructure conversion with upgraded monitoring requirements.
Europe Pipeline Security Market Competitive Landscape
German industrial conglomerates anchor one tier; Anglo-American automation specialists hold another through integrated control-system offerings. The vendor base concentrates around three strategic archetypes: diversified industrial technology groups, pure-play cybersecurity providers, and defense-heritage contractors with sovereign-clearance capabilities. Competitive dynamics center on certification pre-positioning and long-term service contract capture rather than hardware margin extraction. M&A activity targets niche sensing technology assets, while strategic partnerships bundle drone surveillance with fiber-optic monitoring platforms.
Within the diversified industrial tier, Siemens AG and ABB Ltd. exemplify control-system heritage players that leverage automation installed bases to anchor security procurement. Honeywell International Inc. occupies a position among integrated platform providers competing through bundled SCADA-firewall architectures. BAE Systems represents the defense-contractor archetype dominating UK government-adjacent pipeline security mandates.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| General Electric Company |
| ABB Ltd. |
| Rockwell Automation, Inc. |
| Siemens AG |
| BAE Systems |
| Schneider Electric |
| Johnson Controls |
| Emerson |
| Others |
Supply & Pricing Matrix
Photonic sensor components from German and Swiss suppliers cascade through three distinct pricing tiers as they reach pipeline operators. Input concentration among specialized fiber-optic manufacturers elevates hardware costs for large-diameter deployments, while software licensing fees for AI-enhanced threat detection compress margins for mid-tier vendors competing against integrated industrial conglomerates.
Pricing Analysis
Distributor margins on security hardware compress as direct OEM relationships expand among major trunk line operators. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62443-certified control systems from uncertified alternatives, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from unbundled service contracts that redistribute recurring revenue toward pure-play monitoring providers. Utilities converting hydrogen-ready infrastructure exhibit highest price sensitivity, while oil and gas majors prioritize redundancy over cost optimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Dutch pipeline operators, bypassing traditional distribution layers for control system procurement. Manufacturing concentrates in Germany, Switzerland, and the Netherlands for photonic sensing components, with software development anchored in France and the United Kingdom. Raw material dependencies include rare-earth-doped optical fibers, precision laser diodes, and hardened semiconductor components. Single-source vulnerability in distributed acoustic sensing modules creates structural risk for large-project timelines. Distribution runs through integrated engineering-procurement-construction firms for bundled contracts, while unbundled monitoring subscriptions flow directly to specialized security operations centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Critical Entities Resilience Directive functions as a regulatory compounder, mandating systematic risk assessments that elevate cybersecurity from operational expense to board-level priority and compress procurement cycles across Northern Europe.
For Market Incumbents: Deepen certification pre-positioning for IEC 62443 control system standards before they harden into automatic disqualification filters. Anchor long-term service contracts through bundled hardware-monitoring arrangements that resist unbundling pressure from Dutch and Norwegian operators. Vertical integration into fiber-optic sensing manufacturing mitigates photonic component supply constraints that extend lead times for Rhine corridor retrofit projects. For New Entrants and Emerging Players: Polish and Romanian operators accessing Just Transition Mechanism subsidies represent the most penetrable buyer archetype for security modernization contracts. Iberian LNG terminal expansion around Portuguese Atlantic infrastructure offers white-space positioning before competitive saturation. A sovereign-cyber positioning strategy unlocks defense-adjacent pipeline contracts in the United Kingdom where classified clearance requirements filter out non-domestic vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where fiber-optic sensing technology and AI-enhanced threat detection capabilities remain fragmented among niche specialists. Long-term viability favors vendors with installed bases in hydrogen pipeline conversion corridors and recurring monitoring revenue streams. Acquisition targets should demonstrate ANSSI or BSI certification pathways and established relationships with cross-border infrastructure operators. The signal to watch is unbundling velocity in Dutch and Norwegian procurement patterns, which redistributes margin toward pure-play monitoring providers and away from integrated engineering firms.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Certification Investment | Pre-positions vendors for German BSI procurement filters that now mandate certified control systems. |
| Fiber-Optic Sensing Acquisition | Captures photonic component supply capacity concentrated among German and Swiss manufacturers. |
| Hydrogen-Ready Security Bundling | Locks in long-term contracts for leak detection upgrades during Netherlands and Spain pipeline conversions. |
| Security Operations Center Expansion | Captures unbundled monitoring subscriptions shifting margin from engineering firms in The Hague and Oslo. |
| Sovereign-Cyber Capability Buildout | Opens UK defense-adjacent pipeline contracts requiring classified clearance and domestic data residency. |
Research Methodology
Direct dialogue with pipeline security directors, SCADA engineers, industrial cybersecurity consultants, and procurement officers at major trunk line operators grounded qualitative assessment. Secondary validation drew from BSI technical guidelines, ANSSI critical infrastructure notifications, EU Critical Entities Resilience Directive implementation texts, and IEC 62443 certification databases. Bottom-up project pipeline analysis and top-down regulatory mandate sizing were triangulated to bound market estimates.
Segment-level outputs across technology, end user, service type, and deployment architecture were generated through structured modeling of procurement cycle compression and compliance cost pass-through. CAGRs were derived from regression of historical security spending against regulatory milestone timing and infrastructure event response patterns. Forecast inputs included hydrogen pipeline conversion timelines, subsea sabotage incident frequency, and national data sovereignty rule fragmentation across Germany, France, and Benelux.
Underlying measurement precision varies by segment; monitoring systems and threat detection carry tighter precision than access control and surveillance given more visible procurement data. Forecasts reflect assumptions about regulatory enforcement consistency, photonic component supply expansion, and OT-cybersecurity talent pipeline development. Periodic stress-testing of base assumptions is recommended against Nord Stream-type infrastructure events, CE marking cybersecurity annex revisions, and national data localization rule changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market