
 Utilities Security Market | 2026-2036
Utilities Security Market Size, Share, and Industry Trends Forecast 2026-2036
Utilities Security Market Analysis
Market Overview
European industrial automation suppliers is broadening their utilities security portfolio through dedicated substation protection divisions. Schneider Electric SE leverages its deep energy management heritage to anchor integrated OT-IT security architectures across transmission operators. Siemens AG competes through native cybersecurity layers embedded within its power distribution automation suites. Nozomi Networks Inc. specializes in real-time threat visibility for industrial control networks serving water and energy utilities.
Utilities security encompasses the integrated protection of critical infrastructure encompassing power generation, transmission, water treatment, and waste management systems through layered physical access control, network intrusion detection, and encrypted SCADA communications operating across IEC 61850 and DNP3 protocols. The primary purpose is ensuring continuity of essential services while preventing unauthorized manipulation of operational technology environments. Cybersecurity services command the dominant margin pool as ransomware attacks against energy providers intensify regulatory scrutiny and insurance requirements. Cloud-based deployment models represent the fastest-expanding segment as utilities migrate monitoring and analytics away from aging on-premises architectures. Physical security through surveillance cameras and perimeter access control remains mature with replacement-driven demand concentrated at nuclear and hydroelectric facilities.
FERC enforces mandatory reliability standards through NERC CIP in the United States, while the EU Network and Information Security Directive imposes incident reporting and risk management obligations on energy and water operators across member states. IEC 62351 and ISO 27001 provide the technical baselines shaping product certification requirements and procurement specifications for utility security vendors. Stakeholders must monitor evolving attacker tactics targeting remote access pathways and evaluate zero-trust architecture investments before the next regulatory compliance cycle tightens.
Market Dynamics
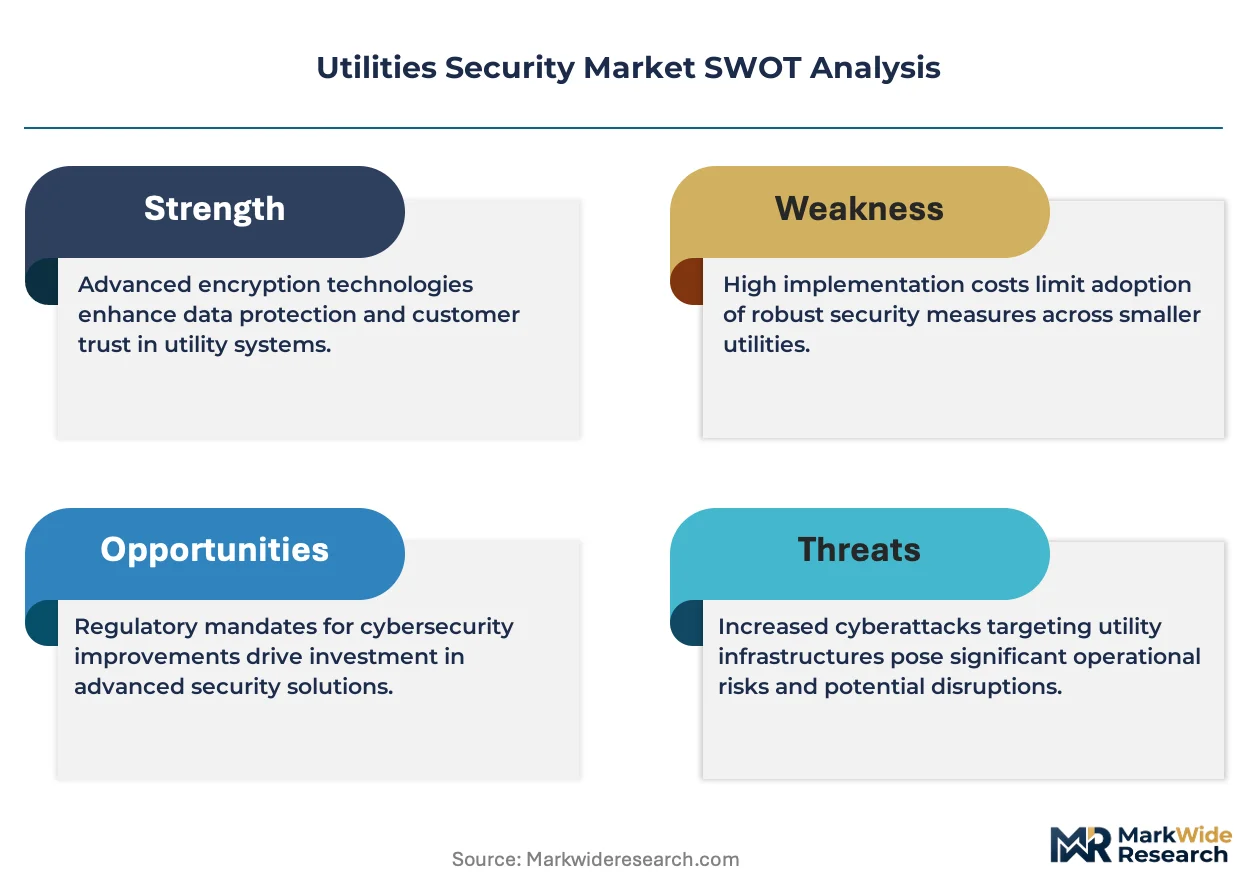
The convergence of operational technology and information technology networks is forcing utilities to rebuild security architectures from the ground up. OT-IT integration exposes legacy SCADA systems to internet-facing threats that these aging platforms were never engineered to withstand.
Growth Catalysts
- NERC CIP enforcement:Mandatory reliability standards in the United States compel electric utilities to invest in compliance-driven security upgrades. Violation penalties now reach millions of dollars per incident.
- Water treatment hardening:Chemical sector security mandates and drinking water protection frameworks are accelerating demand for intrusion detection systems at municipal facilities.
- DNP3 protocol encryption:Native cryptographic extensions for supervisory control networks are displacing plaintext communications across transmission and distribution systems.
Market Restraints
- Semiconductor supply concentration:Specialized industrial security processors depend on fabrication capacity concentrated in Taiwan and South Korea. Geopolitical friction threatens hardware delivery timelines.
- Legacy asset stranding:Decades-old substation equipment lacks computational headroom for modern encryption algorithms. Full replacement cycles extend beyond fifteen years.
- Qualified installer scarcity:Certified technicians capable of integrating IEC 62351-compliant systems command premium wages that inflate project delivery costs.
Strategic Opportunities
- India grid modernization:The country's central electricity authority is mandating smart metering and distribution automation that requires embedded security modules. Domestic manufacturing incentives reduce import dependency.
- Zero-trust architecture adoption:Microsegmentation and continuous verification protocols are converging with IEC 61850 substation automation to create new product categories.
- Cloud-native security operations centers:Managed detection and response services delivered through utility-specific cloud instances bypass capital constraints at smaller municipal water operators.
Industry Challenges
- OT cybersecurity skill gaps:Industrial control system expertise remains scarce relative to enterprise IT security talent. Utilities compete with oil and gas operators for the same limited labor pool.
- Multi-vendor integration complexity:Heterogeneous equipment from different eras and suppliers creates interoperability failures during security overlay deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utilities Security Market |
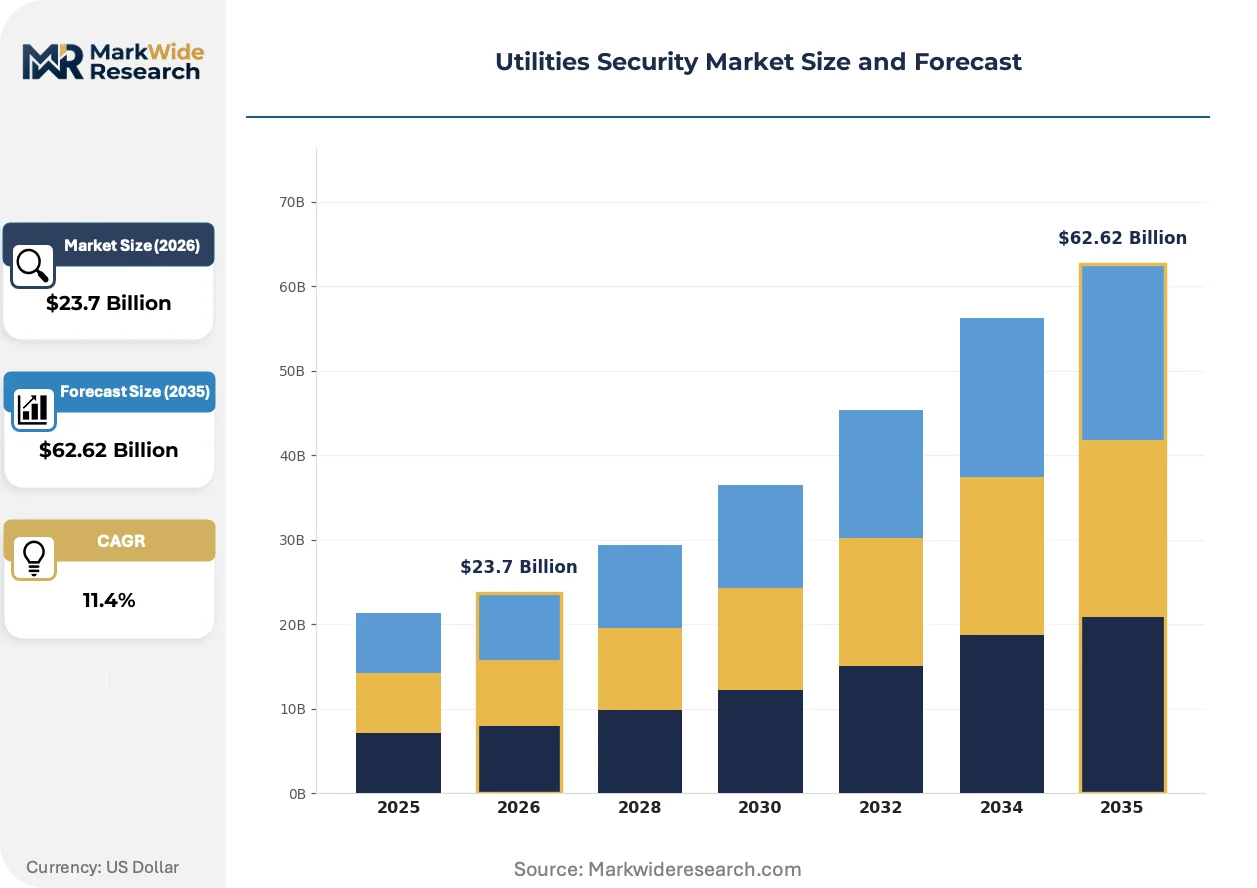
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Security, Cybersecurity, Monitoring Services, Risk Assessment Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: Access Control Systems, Surveillance Cameras, Intrusion Detection, Encryption Technologies End User: Energy Providers, Water Authorities, Waste Management, Communication Companies |
| Companies Covered | Schneider Electric SE, Johnson Controls International PLC, Cisco Systems, Inc., Axis Communications AB, Bosch Security Systems, Inc., Fortinet, Inc., Siemens AG, Nozomi Networks Inc., International Business Machines Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utilities Security Market Emerging Trajectories
Security vendors are racing to embed artificial intelligence directly into edge devices rather than routing all analytics through centralized clouds. This architectural pivot reduces latency for threat response while accommodating bandwidth constraints at remote substations.
Extended detection and response platforms purpose-built for industrial networks are unifying visibility across IT and OT environments. Transmission operators in Germany and the United States are deploying these systems at pace. The technology is unifying previously siloed security operations into single-pane workflows that compress mean-time-to-detection metrics.
The EU Network and Information Security Directive is expanding incident reporting obligations to cover smaller water and energy operators previously exempt from mandatory disclosures. Industrial consequence includes accelerated procurement of logging and forensics infrastructure. Distribution cooperatives across France and Italy are responding by consolidating security monitoring through regional shared-service arrangements.
Utility procurement committees are elevating cybersecurity certification requirements above price in vendor selection criteria. Equipment suppliers without IEC 62443 product certifications are losing bid eligibility at major European transmission operators. China State Grid Corporation exemplifies this behavioral shift through its mandatory security testing protocols for all imported automation hardware.
Utilities Security Market Segmentation
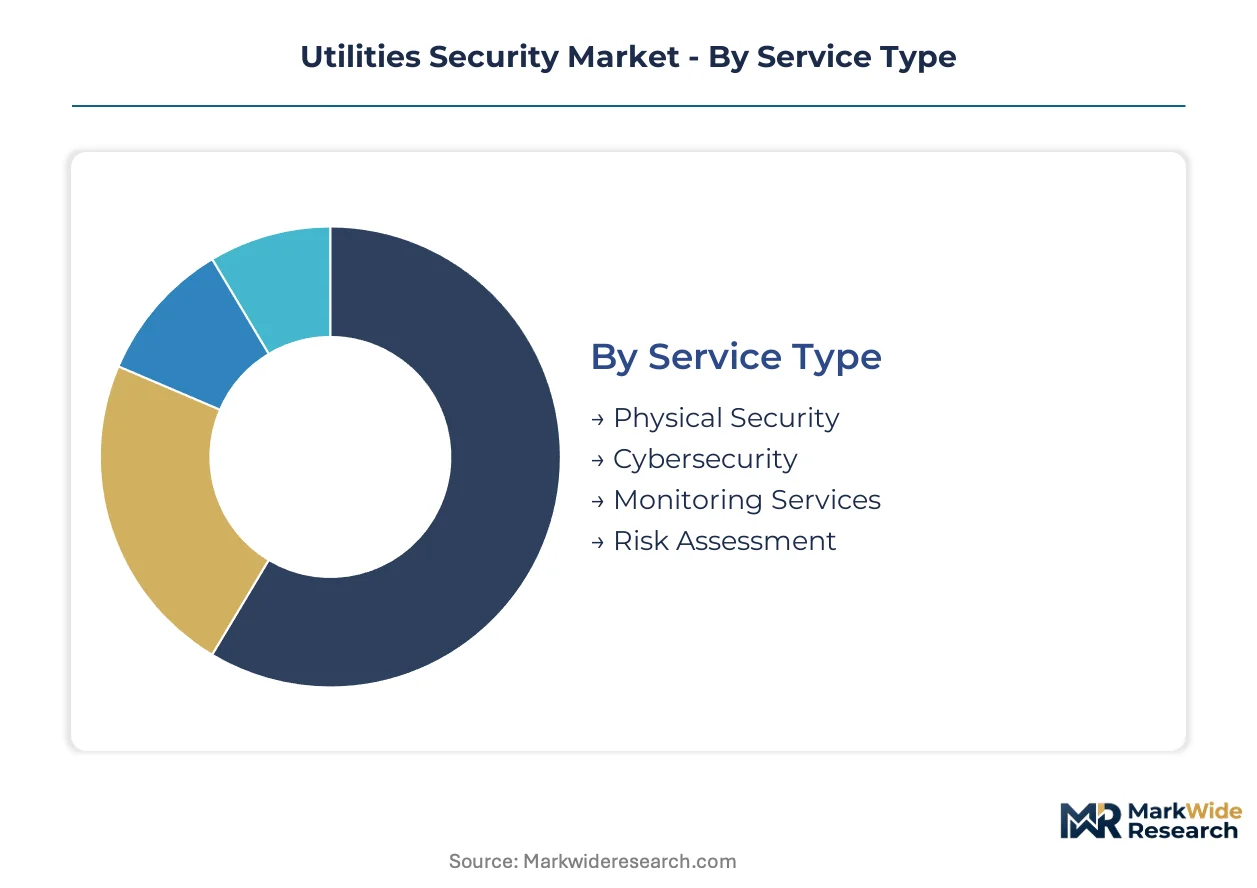
Utilities security procurement diverges sharply between integrated platform buyers and point-solution adopters. Segmentation reveals where capital concentrates versus where operating expenditure models are displacing upfront investment.
Service Type:
Physical security services operate as standalone installations at generation facilities, while cybersecurity and monitoring increasingly embed within broader OT-IT convergence architectures.
- Cybersecurity:Encompasses network intrusion detection, endpoint protection, and secure remote access for SCADA and industrial control systems. Demand concentrates at United States electric utilities facing NERC CIP enforcement deadlines with penalty exposure driving compliance budgets. Cloud-native security operations centers are gaining traction among municipal water operators seeking to bypass capital constraints.
- Physical Security:Includes perimeter access control, video surveillance, and intrusion detection systems deployed at generation and transmission facilities. Procurement clusters at nuclear and hydroelectric sites in Germany and France where regulatory mandates require hardened perimeters against physical sabotage threats.
- Monitoring Services:Delivers continuous threat visibility and incident response through utility-specific security operations centers.
- Risk Assessment:Provides vulnerability scanning, penetration testing, and compliance gap analysis against IEC 62351 and NERC CIP frameworks.
Volume placements concentrate in Cybersecurity; the faster expansion belongs to Monitoring Services.
Deployment Model:
Cost-tier stratification separates capital-intensive on-premises installations from subscription-based alternatives that shift balance-sheet treatment for municipal operators.
- Cloud-Based:Delivers security analytics, threat intelligence, and centralized policy management through utility-specific cloud instances. United States rural electric cooperatives are adopting these models fastest to overcome limited internal security expertise. FERC guidance on cloud computing for critical infrastructure is accelerating procurement timelines.
- Managed Services:Provides fully outsourced security operations including 24/7 monitoring, incident response, and compliance reporting. Water authorities in Italy and France are consolidating through regional shared-service arrangements to meet expanded EU NIS2 incident reporting obligations.
- On-Premises:Maintains all security infrastructure within utility-controlled data centers and substation enclosures.
- Hybrid:Combines on-premises control system protection with cloud-based analytics and threat intelligence feeds.
On-Premises retains the largest installed base; Managed Services is climbing the fastest as smaller operators outsource expertise gaps.
Technology:
Application maturity varies from decades-old surveillance hardware to emerging encryption standards still undergoing protocol certification.
- Encryption Technologies:Encompasses DNP3 Secure Authentication, IEC 62351-compliant cryptographic modules, and TLS implementations for industrial protocols. Transmission operators in Germany and the United States are mandating these upgrades to displace plaintext SCADA communications. Native protocol encryption is displacing external encryption appliances at greenfield substation deployments.
- Intrusion Detection:Deploys network and host-based sensors purpose-built for industrial control system environments. Water treatment facilities across China are accelerating adoption following chemical sector security mandates that require anomaly detection on critical process networks.
- Access Control Systems:Manages physical entry through biometric readers, smart cards, and multi-factor authentication at critical facilities.
- Surveillance Cameras:Provides video monitoring through IP-based and analog systems with varying degrees of analytics integration.
Surveillance Cameras hold the broadest footprint; Encryption Technologies is gaining share fastest from regulatory compliance mandates.
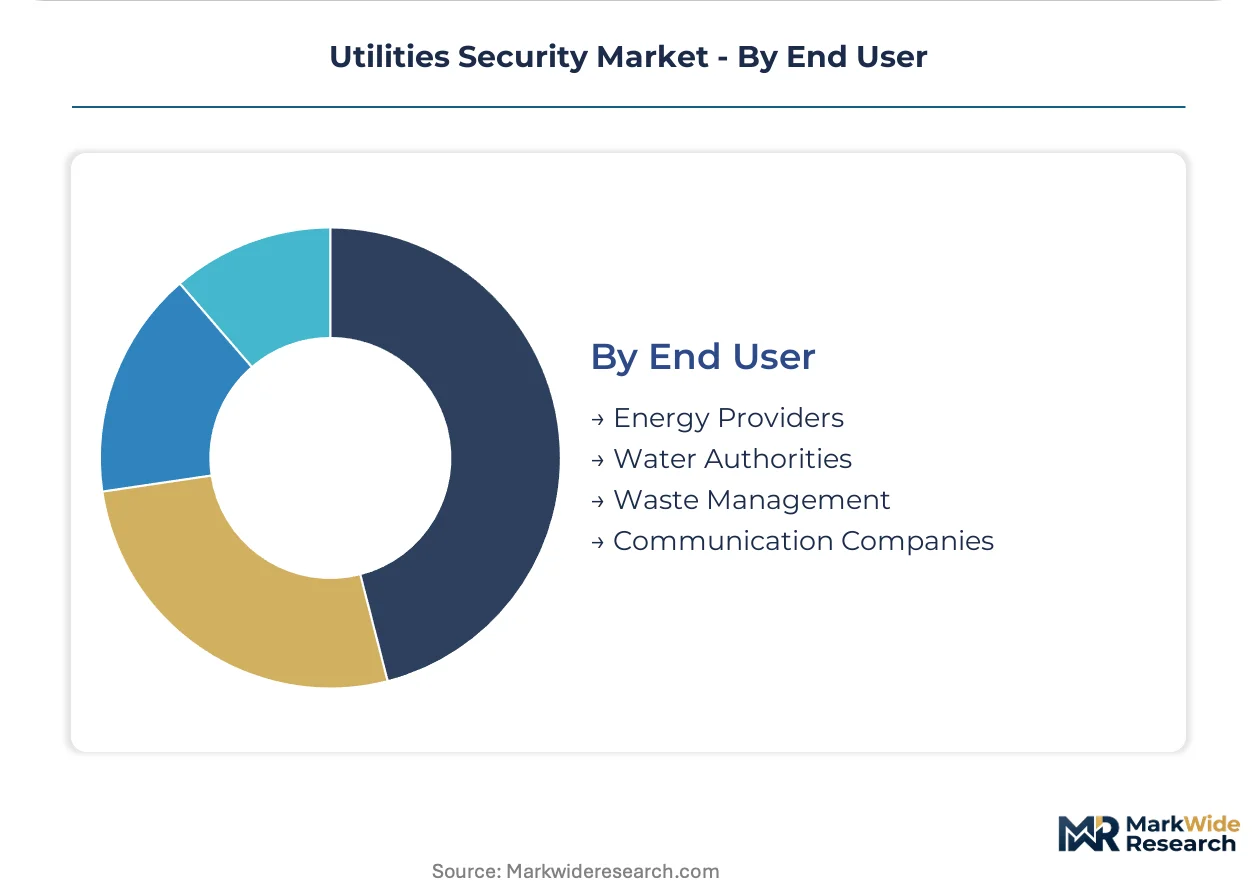
End User:
Customer-type differentiation separates vertically integrated national operators from fragmented municipal and cooperative structures with divergent procurement authority.
- Energy Providers:Encompasses generation companies, transmission system operators, and distribution utilities across regulated and competitive markets. China State Grid Corporation exemplifies centralized procurement through mandatory security testing protocols for all imported automation hardware. United States investor-owned utilities are consolidating vendor relationships to reduce multi-vendor integration complexity.
- Water Authorities:Includes municipal drinking water and wastewater treatment operators subject to chemical facility security regulations. India's central electricity authority mandates are extending to water infrastructure as smart city investments integrate utility networks.
- Waste Management:Covers landfill operations, incineration facilities, and hazardous waste handling sites with physical and environmental monitoring requirements.
- Communication Companies:Encompasses telecommunications infrastructure sharing utility rights-of-way and converging network operations.
Revenue concentration sits with Energy Providers; Water Authorities show the steepest expansion trajectory from hardening mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capacity in China anchors upstream supply chains for industrial security hardware. German precision engineering clusters shape encryption module standards. United States electric cooperatives drive cloud-native deployment models.
United States
FERC enforcement of NERC CIP reliability standards compels investor-owned utilities to accelerate cybersecurity procurement cycles. Violation penalties reaching millions of dollars per incident have shifted compliance budgets toward continuous monitoring infrastructure. Texas and California transmission operators are consolidating vendor relationships to reduce multi-vendor integration failures.
Germany
Transmission system operators mandate IEC 62351-compliant cryptographic upgrades to displace plaintext SCADA communications across legacy substations. The EU Network and Information Security Directive imposes expanded incident reporting obligations on municipal water authorities. Industrial clusters in Bavaria and North Rhine-Westphalia anchor Siemens AG and Schneider Electric SE regional headquarters.
China
State Grid Corporation enforces mandatory security testing protocols for all imported automation hardware, driving domestic substitution in critical infrastructure. Smart city investments integrate utility networks with embedded security modules across provincial grids. Yangtze River Delta manufacturing bases supply encryption processors for distribution automation deployments.
India
The Central Electricity Authority mandates smart metering and distribution automation requiring embedded security modules across state electricity boards. Production-linked incentive schemes reduce import dependency for industrial control components. Maharashtra and Gujarat industrial corridors host domestic manufacturing of substation protection equipment.
France
Distribution cooperatives consolidate security monitoring through regional shared-service arrangements to meet tightened EU NIS2 disclosure timelines. Nuclear facility perimeter hardening drives demand for biometric access control and video analytics. Île-de-France water authorities deploy intrusion detection systems following chemical sector security mandates.
Utilities Security Market Vendor Landscape
Global majors compete with regional champions across integrated platform versus point-solution positioning. The vendor base stratifies into three tiers: diversified industrial conglomerates with energy management heritage, pure-play cybersecurity specialists, and physical security incumbents pivoting toward converged offerings. Consolidation pressure intensifies as utilities reduce supplier counts to simplify OT-IT integration. Strategic moves center on vertical integration into encryption module production and geographic expansion through local certification partnerships.
Within the diversified industrial tier, Schneider Electric SE and Siemens AG exemplify integrated OT-IT security architectures anchored by deep energy management heritage. Nozomi Networks Inc. occupies a specialist position in real-time threat visibility for industrial control networks. These three entities represent distinct competitive archetypes: the full-platform provider, the automation-native cybersecurity layer, and the pure-play industrial visibility specialist.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Johnson Controls International PLC |
| Cisco Systems, Inc. |
| Axis Communications AB |
| Bosch Security Systems, Inc. |
| Fortinet, Inc. |
| Siemens AG |
| Nozomi Networks Inc. |
| International Business Machines Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in industrial cybersecurity services have consolidated regional service capabilities across the United States and Germany, tightening pricing discipline through standardized deployment playbooks while leveraging captive labor pools to compress field service margins.
Pricing Analysis
Warranty and multi-year maintenance bundling separates premium-tier cybersecurity platform providers from unbundled point-solution vendors in competitive tenders. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 62443 certification grade and geographic delivery scope. Cost compression in the economy tier is intensifying because municipal water authorities are consolidating procurement through regional cooperatives. Smaller distribution utilities in rural United States markets exhibit the highest price sensitivity, while national transmission operators in Germany and China prioritize certification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Dubai anchor hub-and-spoke fulfillment patterns for encryption modules and industrial security processors. Manufacturing concentration rests on Taiwan and South Korea for specialized semiconductors, with Germany and the United States supplying precision engineering components for substation protection hardware. Single-source vulnerability in advanced lithography capacity threatens hardware delivery timelines for IEC 62351-compliant systems. Distribution runs through authorized system integrators holding NERC CIP certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FERC enforcement of NERC CIP reliability standards constructs a formidable barrier-to-entry moat for vendors holding certified product portfolios.
For Market Incumbents: Extend platform consolidation roadmaps to absorb point-solution specialists before regional shared-service arrangements lock in municipal water authority procurement. Cloud-native security operations centers represent the primary substitution threat eroding on-premises maintenance revenue. Backward integration into encryption module production secures margin control against semiconductor supply volatility. For New Entrants and Emerging Players: Rural electric cooperatives in the United States present the most penetrable buyer archetype, underserved by legacy vendors focused on investor-owned utility scale. Zero-trust architecture retrofit projects at aging substations offer white-space entry with lower certification overhead than greenfield deployments. Go-to-market through managed security service partnerships bypasses direct sales force buildout requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor industrial automation vendors with stranded OT-IT integration capabilities in European markets facing EU NIS2 compliance deadlines. Long-term viability hinges on captive certification expertise rather than hardware commoditization trajectories. Watch for FERC guidance clarifications on cloud computing eligibility as the inflection signal for subscription revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Product Certification | Mandatory bid eligibility at China State Grid Corporation and major European transmission operators. |
| Cloud-Native SOC Deployment | FERC guidance accelerates procurement timelines among United States rural electric cooperatives. |
| Zero-Trust Architecture Integration | Convergence with IEC 61850 substation automation creates new product category expansion. |
| Regional Shared-Service Consolidation | EU NIS2 incident reporting obligations drive water authority procurement pooling in France and Italy. |
| Domestic Manufacturing Incentives | India PLI schemes reduce import dependency for embedded security module production. |
Methodological Framework
Independent corroboration across utility security procurement officers, OT-IT integration specialists, and regulatory compliance consultants underwrites the qualitative findings. Primary fieldwork encompassed interviews with substation automation engineers, cybersecurity architects at transmission operators, municipal water authority IT directors, and industrial control system vendors. Secondary validation drew from FERC enforcement records, NERC CIP violation filings, EU NIS2 implementation guidance, IEC 62351 certification databases, and customs trade data for encryption module imports. Bottom-up demand modeling triangulated against top-down market sizing across deployment models and end-user segments.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in the cybersecurity services segment. Segmentation dimensions modeled include service type, deployment architecture, technology maturity tier, and end-user procurement authority structure. CAGRs were derived from regression analysis of historical procurement cycles and regulatory compliance deadline clustering. Forecast inputs incorporated NERC CIP enforcement penalty schedules, EU directive implementation timelines, and smart grid investment trajectories by national electricity authorities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply disruptions, geopolitical friction affecting cross-border technology transfers, and potential harmonization gaps between IEC 62351 and emerging zero-trust protocol standards. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
Global Railway Platform Security Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market