
 Middle East and Africa Pipeline Security Market | 2026-2036
Middle East and Africa Pipeline Security Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pipeline Security Market Foresight
Project finance structures with long-term service concessions are tilting competitive dynamics toward vendors capable of bundling hardware with decade-long operational contracts. Honeywell International Inc. leverages its integrated control room software to anchor multi-year monitoring agreements across Saudi downstream corridors. Siemens AG sustains its position through in-house production of distributed acoustic sensing cables, tightening margins for pure-play equipment suppliers. Thales S.A. differentiates by occupying the encrypted communications layer that links field sensors to national command centers.
Pipeline security encompasses the integrated hardware, software, and procedural systems designed to detect intrusion, leakage, fire, and unauthorized access across buried and above-ground hydrocarbon and water conduits, typically incorporating fiber-optic acoustic sensing with spatial resolution below ten meters and real-time thermal anomaly detection. Its primary commercial purpose is preventing product loss, environmental contamination, and operational shutdowns in continuous-flow infrastructure. Surveillance systems dominate current procurement volumes across the region, though leak detection is recording the fastest uptake as operators face stricter environmental liability frameworks. Monitoring services capture the largest recurring revenue pools, while incident response capabilities remain underdeveloped outside South African and Nigerian hubs.
SFDA hazardous material regulations in Saudi Arabia and UAE's civil defense codes mandate redundant perimeter detection for all new hydrocarbon trunk lines, directly expanding the addressable equipment base. Egypt's petroleum ministry has adopted NIS-style cybersecurity addendums for SCADA-linked security networks, forcing upgrades across legacy Suez Canal corridor infrastructure. Stakeholders must weigh the capital efficiency of cloud-architected remote monitoring against sovereign data residency requirements that are hardening across Gulf national oil companies.
Market Dynamics
Project finance structures with long-term service concessions are tilting competitive dynamics toward vendors capable of bundling hardware with decade-long operational contracts across Gulf hydrocarbon corridors.
Growth Catalysts
- SFDA hazardous material directives:Saudi Arabia's Food and Drug Authority mandates redundant perimeter detection for all new hydrocarbon trunk lines, directly expanding equipment procurement volumes for fiber-optic sensing systems.
- Fujairah crude export terminal concentration:The United Arab Emirates' strategic port infrastructure drives concentrated demand for integrated pipeline monitoring at scale unmatched elsewhere in the region.
- Distributed acoustic sensing maturation:Spatial resolution below ten meters now enables pinpoint leak localization, accelerating replacement of legacy pressure-based monitoring in high-consequence areas.
Market Restraints
- Specialized fiber-optic cable supply concentration:Production of sensing-grade optical fibers concentrates among three European and Asian suppliers, exposing procurement timelines to geopolitical friction.
- Scarce integration engineering capacity:The shallow talent pool for SCADA-security convergence in Sub-Saharan Africa extends deployment timelines for multinational operators.
- Sovereign data residency mandates:Gulf national oil companies now require local command center hosting, fragmenting cloud-architected monitoring platforms and raising capital requirements.
Strategic Opportunities
- Egypt's NIS-style cybersecurity addendums:The petroleum ministry's SCADA security upgrades for Suez Canal corridor infrastructure create retrofit demand across legacy pipeline networks.
- Water pipeline security whitespace:Desalination distribution networks in Saudi Arabia and the UAE remain underpenetrated by hydrocarbon-grade perimeter technologies.
- AI-driven predictive maintenance convergence:Machine learning anomaly detection layered atop fiber-optic sensing is virtualizing scheduled inspection cycles into condition-based interventions.
Industry Challenges
- SCADA-legacy system integration complexity:Brownfield pipeline corridors in Nigeria and South Africa require bespoke protocol translation layers that compress vendor margins.
- Multi-jurisdiction certification timelines:Equipment approvals must satisfy UAE civil defense codes, Saudi SFDA requirements, and Egyptian petroleum ministry standards sequentially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pipeline Security Market |
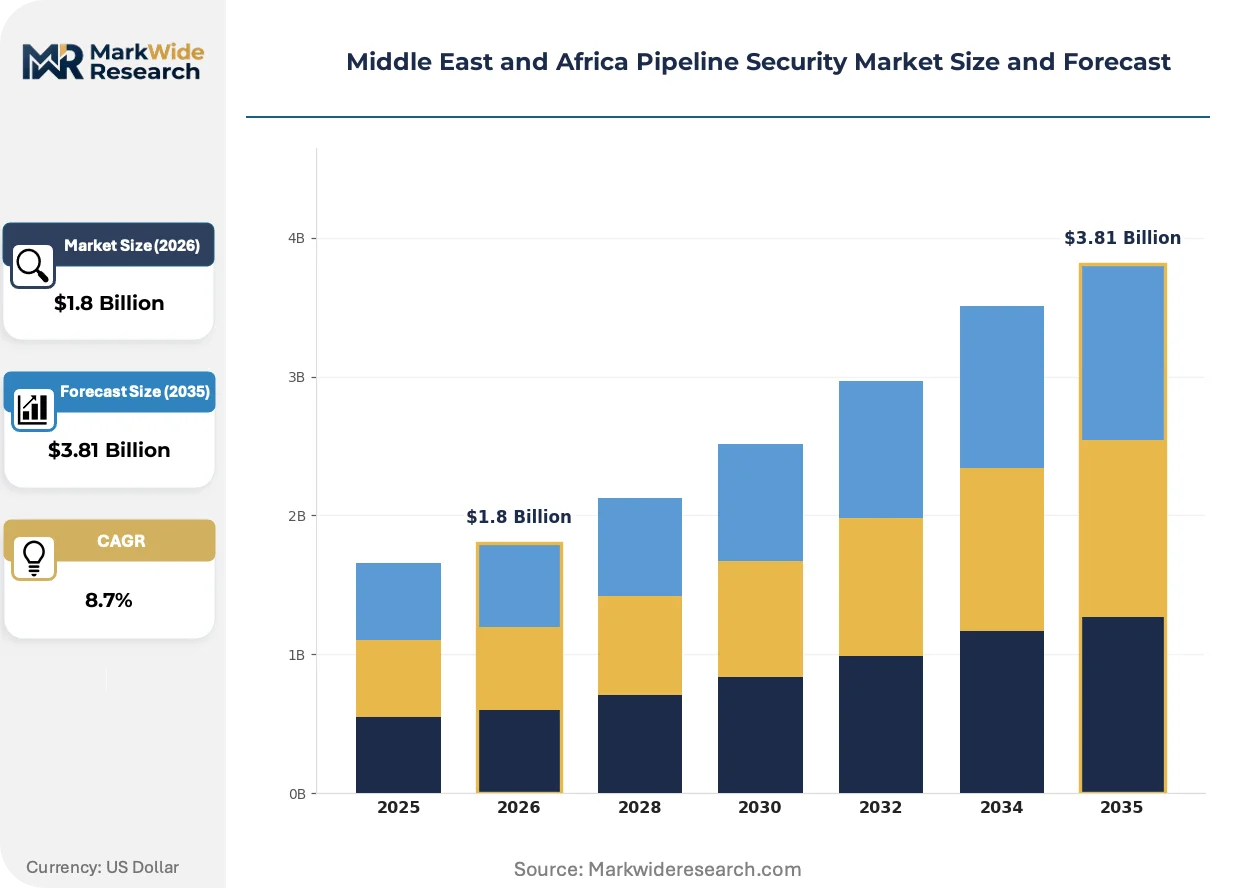
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Systems, Access Control, Fire Detection, Leak Detection Service Type: Monitoring Services, Risk Assessment, Incident Response, Consulting Application: Oil Transportation, Gas Transportation, Water Pipelines, Hazardous Material Pipelines End User: Energy Companies, Government Agencies, Industrial Operators, Environmental Agencies |
| Companies Covered | ABB Ltd., Honeywell International Inc., Siemens AG, GE Grid Solutions SPA, Optasens Ltd., Huawei Technologies Co. Ltd., Thales S.A., BAE Systems Inc., Senstar Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pipeline Security Market Shifts & Advancements
Digital twin architectures and sovereign cloud mandates are recalibrating how pipeline operators procure security infrastructure across the Middle East and Africa.
Fiber-optic distributed acoustic sensing is virtualizing physical patrol requirements across Saudi downstream corridors. Aramco and ADNOC have both specified continuous-wave interrogator systems for new trunk lines, compressing the addressable market for manned surveillance services. The technology's core function—detecting third-party intrusion through vibration pattern analysis—now anchors multi-year monitoring concessions rather than equipment sales.
UAE civil defense codes now mandate thermal anomaly detection redundancy for all above-ground hydrocarbon storage and transfer facilities. This regulatory pressure forces upgrades across Fujairah's existing export terminal infrastructure, with compliance deadlines clustering procurement decisions into compressed windows. The Shah gas field expansion represents the most visible concentration of specification tightening.
Long-term operational contracts are displacing transactional equipment purchases in Abu Dhabi and Riyadh procurement offices. National oil companies now bundle decade-long sensor maintenance, software updates, and incident response into single-vendor agreements. This behavioral shift is most visible in Saudi downstream corridors, where Honeywell and Siemens have anchored integrated control room concessions spanning multiple pipeline systems.
Middle East and Africa Pipeline Security Market Segmentation
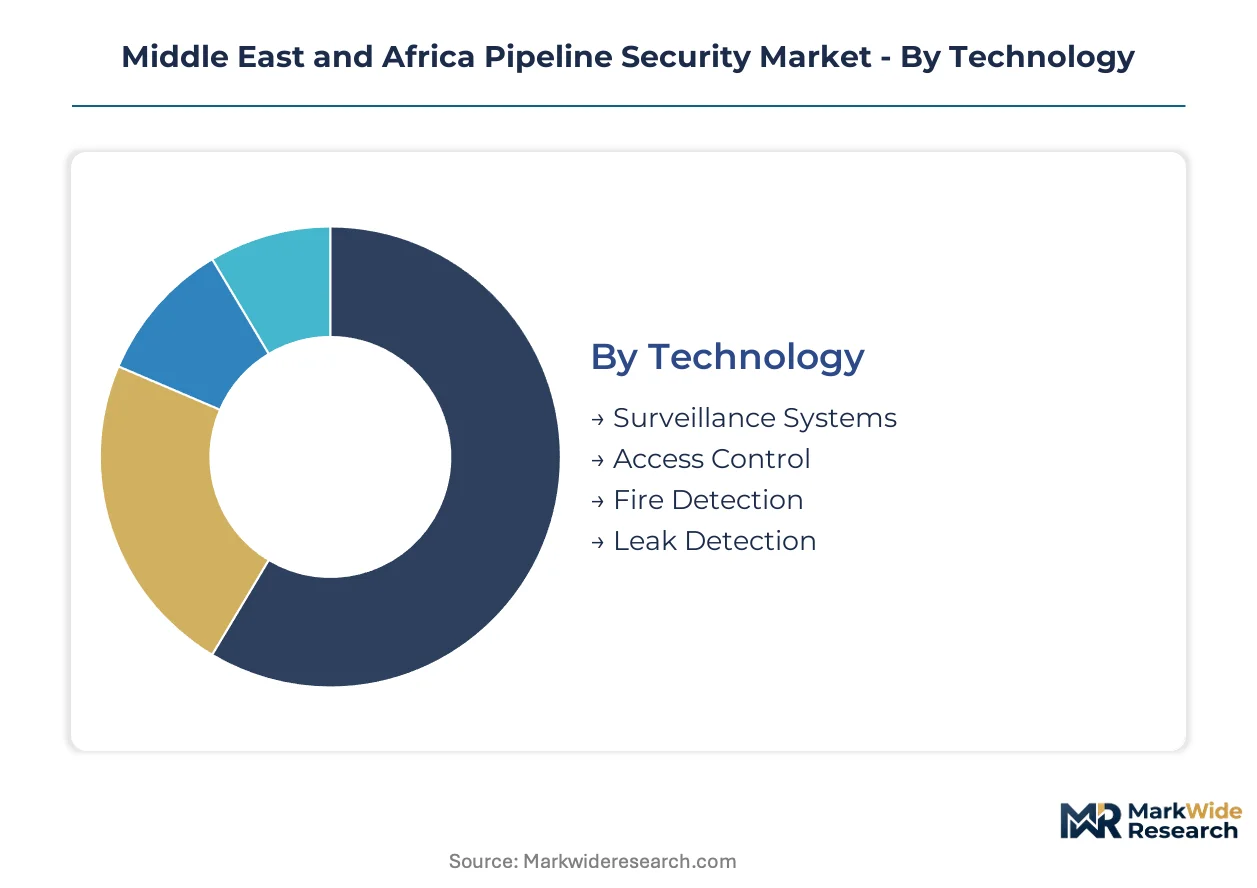
Procurement patterns across Middle East and Africa pipeline security diverge sharply by technology maturity and service intensity. National oil companies now weight total cost of ownership over upfront capital, favoring segments with embedded multi-year operational support.
Technology:
After-sales-service intensity varies dramatically across detection modalities, with fiber-optic systems demanding specialized calibration labor while thermal cameras require routine lens maintenance in desert environments.
- Surveillance Systems:Fiber-optic distributed acoustic sensing and thermal imaging arrays form the backbone of perimeter monitoring across Saudi downstream corridors. Aramco and ADNOC specifications now mandate continuous-wave interrogators with sub-ten-meter spatial resolution, locking vendors into decade-long maintenance concessions.
- Leak Detection:Pressure-point analytics and computational pipeline monitoring are displacing legacy mass-balance methods in high-consequence areas. UAE civil defense codes mandate redundant leak detection for all new hydrocarbon trunk lines, accelerating procurement in Abu Dhabi's Shah gas field expansion.
- Access Control:Biometric perimeter gates and drone-based patrol systems secure above-ground valve stations.
- Fire Detection:Multi-spectral flame detectors address thermal anomaly requirements for Fujairah crude export terminals.
By volume, Surveillance Systems leads. By growth pace, Leak Detection is expanding most quickly.
Service Type:
Margin structures favor recurring revenue streams over one-time consulting engagements, with monitoring services capturing the largest share of vendor cash flows.
- Monitoring Services:Real-time sensor data interpretation and 24/7 control room staffing anchor long-term vendor relationships. Honeywell and Siemens have secured multi-year concessions across Saudi and UAE pipeline networks by bundling hardware with dedicated operational personnel.
- Incident Response:Specialized containment crews and forensic investigation teams remain concentrated in South African and Nigerian hubs. Scarce regional capacity limits expansion into East African pipeline corridors.
- Risk Assessment:Threat modeling and vulnerability audits precede major capital deployments.
- Consulting:Regulatory compliance advisory supports SFDA and UAE civil defense certification processes.
Monitoring Services generates the steadiest revenue streams. Incident Response commands the highest per-engagement fees.
Application:
Application-specific procurement clusters around hydrocarbon infrastructure, though water pipeline security presents underpenetrated whitespace.
- Oil Transportation:Crude trunk lines and refined product corridors drive concentrated demand for integrated perimeter-leak detection systems. Saudi Aramco's East-West Pipeline and UAE's Habshan-Fujairah line represent flagship deployments.
- Gas Transportation:Sour gas and LNG distribution networks require specialized hydrogen sulfide sensing alongside standard intrusion detection. The Shah gas field expansion exemplifies specification tightening for high-pressure sour service.
- Water Pipelines:Desalination distribution networks in Saudi Arabia and the UAE remain underserved by hydrocarbon-grade security technologies.
- Hazardous Material Pipelines:Chemical and ammonia conduits face emerging regulatory scrutiny.
Oil Transportation dominates current procurement volumes. Water Pipelines offers the steepest expansion trajectory as scarcity concerns intensify.
End User:
End-user sophistication determines specification complexity, with national oil companies driving the most demanding technical requirements.
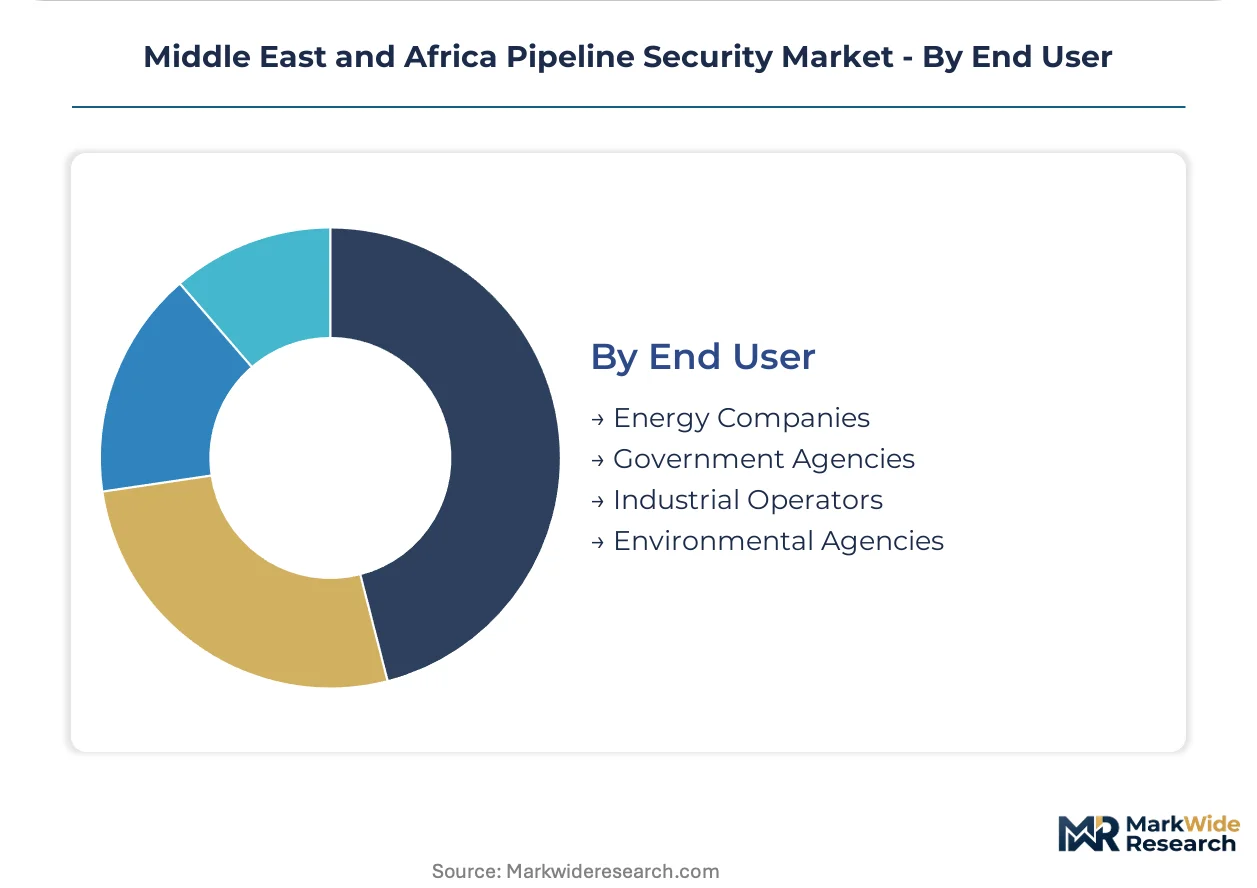
- Energy Companies:Integrated majors and national oil companies anchor demand for enterprise-grade SCADA-integrated security platforms. Aramco, ADNOC, and Egyptian General Petroleum Corporation set procurement standards across the region.
- Government Agencies:Critical infrastructure protection mandates and cross-border pipeline treaties shape sovereign procurement frameworks. Egypt's petroleum ministry cybersecurity addendums illustrate regulatory-driven upgrade cycles.
- Industrial Operators:Refinery and petrochemical complexes require perimeter segmentation for process safety.
- Environmental Agencies:Liability frameworks and spill response protocols influence detection sensitivity specifications.
Energy Companies command the largest contract values. Government Agencies are gaining procurement authority through regulatory mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA hazardous material directives and UAE civil defense codes are reshaping procurement patterns across the Middle East and Africa, with national oil companies tightening technical specifications for new hydrocarbon trunk lines and export terminal infrastructure.
United Arab Emirates
Fujairah's crude export terminals and Abu Dhabi's Shah gas field anchor concentrated demand for fiber-optic perimeter systems. UAE civil defense codes mandate thermal anomaly detection redundancy for above-ground storage facilities, forcing compressed upgrade timelines across existing infrastructure. The Habshan-Fujairah pipeline corridor exemplifies specification tightening for integrated monitoring.
Saudi Arabia
Saudi Aramco's East-West Pipeline and downstream corridors drive enterprise-grade SCADA-integrated security procurement. SFDA mandates redundant perimeter detection for all new hydrocarbon trunk lines, directly expanding equipment volumes for distributed acoustic sensing systems. Riyadh-based procurement offices now favor decade-long operational contracts over transactional hardware purchases.
Egypt
The Suez Canal corridor infrastructure faces retrofit pressure from petroleum ministry cybersecurity addendums modeled on national information security frameworks. Legacy pipeline networks require SCADA-linked security upgrades, creating demand for encrypted communications layers and command center modernization. Cairo's regulatory-driven upgrade cycles contrast with greenfield procurement elsewhere.
South Africa
Specialized incident response crews and forensic investigation teams concentrate in South African hubs, anchoring the region's scarce containment capacity. Sub-Saharan pipeline operators face extended deployment timelines due to shallow SCADA-security convergence talent pools. Johannesburg and Cape Town host the primary vendor engineering support operations.
Nigeria
Brownfield pipeline corridors in the Niger Delta require bespoke protocol translation layers for legacy system integration, compressing vendor margins. Multi-jurisdiction certification requirements complicate equipment approvals for international suppliers. Lagos anchors procurement coordination for multinational operators navigating regulatory fragmentation.
Middle East and Africa Pipeline Security Market Competitive Landscape
On the supply side, the industry is consolidating around vendors capable of bundling hardware with multi-year operational contracts. Three strategic archetypes dominate: integrated industrial conglomerates with control room software ecosystems, specialized sensing equipment manufacturers with in-house cable production, and encrypted communications specialists occupying the data transmission layer. Competitive positioning hinges on securing long-term concessions and backward integration into sensing-grade optical fiber supply.
Among diversified industrial technology providers, Honeywell International Inc., Siemens AG, and Thales S.A. occupy positions reflecting distinct competitive vectors. Honeywell exemplifies the integrated control room archetype, anchoring multi-year monitoring agreements through bundled software and operational personnel. Siemens represents manufacturers with captive distributed acoustic sensing cable production, tightening margins for pure-play equipment vendors. Thales sits within the encrypted communications tier, linking field sensors to national command centers across Gulf national oil company networks.
| Leading Market Players |
|---|
| ABB Ltd. |
| Honeywell International Inc. |
| Siemens AG |
| GE Grid Solutions SPA |
| Optasens Ltd. |
| Huawei Technologies Co. Ltd. |
| Thales S.A. |
| BAE Systems Inc. |
| Senstar Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in European sensing-grade optical fiber production is compressing lead times for Gulf procurement offices and amplifying pricing power among cable suppliers with captive manufacturing. This utilization squeeze forces Middle East pipeline operators into longer-term offtake commitments to secure hardware allocations, embedding cost rigidity into decade-long monitoring concessions.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with UAE civil defense-compliant thermal systems commanding substantial premiums over baseline perimeter hardware. Pricing stratifies across premium, standard, and economy tiers based on after-sales bundling intensity and SCADA integration depth. Cost compression in standard-tier fiber-optic sensing is intensifying because pure-play equipment vendors lack captive cable production. National oil companies show least price sensitivity for encrypted communications layers, while industrial operators in Sub-Saharan Africa face acute budget constraints on upfront hardware.
Supply Chain Analysis
Export-control regimes on distributed acoustic sensing interrogators limit technology flows from European suppliers to Gulf national oil companies, forcing localization partnerships. Sensing-grade optical fiber production concentrates in Germany, Japan, and China, with distributed acoustic sensing cables drawing from specialized coating and cladding inputs. Single-source vulnerability runs through European continuous-wave interrogator manufacturers. Distribution runs through systems integrators with decade-long operational concessions rather than transactional equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shallow talent pool for SCADA-security convergence across Sub-Saharan Africa and the Gulf creates persistent bottlenecks for deployment velocity, making specialized engineering capability the scarce asset that determines competitive outcomes.
For Market Incumbents: Build switching-cost moats through captive fiber-optic cable production and embedded control room software ecosystems. Siemens anchors position through in-house distributed acoustic sensing manufacturing that locks out pure-play equipment rivals. Honeywell reinforces multi-year concessions by bundling operational personnel with hardware refresh cycles. Priority lever rests on securing Shah gas field and Fujairah terminal specifications before compliance deadlines cluster procurement decisions. For New Entrants and Emerging Players: Build out water pipeline security whitespace across Saudi desalination distribution networks and UAE municipal supply infrastructure. This segment remains underpenetrated by hydrocarbon-grade perimeter technologies and lacks incumbent saturation. Target Egypt's Suez Canal corridor retrofit demand where cybersecurity addendums force legacy SCADA upgrades without established vendor relationships. Go-to-market angle emphasizes AI-driven predictive maintenance layered atop standard sensing hardware to virtualize inspection cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across encrypted communications and sovereign cloud infrastructure as Gulf national oil companies mandate local command center hosting. Long-term viability favors vendors with backward integration into sensing-grade optical fiber supply and decade-long operational contract books. Acquisition target archetype: mid-cap specialists with UAE civil defense certification and established relationships with ADNOC or Aramco procurement offices. Signal to watch is clustering of compliance deadlines for thermal anomaly detection redundancy across Fujairah export terminals.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Concession | Decade-long monitoring agreements with Aramco and ADNOC displace transactional equipment sales. |
| Backward Integration into Fiber Production | Captive sensing-grade optical cable manufacturing tightens margins for pure-play equipment competitors. |
| Sovereign Cloud Localization | Local command center hosting mandates fragment cloud-architected platforms across Gulf national oil companies. |
| AI Predictive Maintenance Layer | Machine learning anomaly detection virtualizes scheduled inspection cycles into condition-based interventions. |
| Water Pipeline Security Expansion | Desalination distribution networks in Saudi Arabia and UAE remain underserved by hydrocarbon-grade technologies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across Saudi Aramco procurement divisions, ADNOC technical specifications teams, Siemens AG distributed sensing divisions, and Honeywell International control room integration units. Secondary validation drew from SFDA hazardous material directives, UAE civil defense code amendments, Egyptian petroleum ministry cybersecurity addendums, and SEC filings of listed industrial technology providers. Bottom-up equipment procurement volume estimates were triangulated against top-down national oil company capital expenditure disclosures.
Calibration anchored volume projections to observed concession award patterns across the analysis window, with segmentation modeled across surveillance systems, leak detection, access control, and fire detection technologies. Service intensity dimensions included monitoring services, incident response, risk assessment, and consulting engagements. CAGRs were derived from equipment replacement cycles for legacy pressure-based monitoring and regulatory compliance deadline clustering. Industry-specific inputs incorporated distributed acoustic sensing spatial resolution improvements and thermal anomaly detection mandate adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by European fiber-optic cable suppliers or accelerated AI-driven maintenance virtualization by new entrants would shift outcomes. Material shifts in SFDA enforcement intensity or UAE civil defense code revision timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Tele Protection Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market