
 Global Threat Intelligence Platform Market | 2026-2036
Global Threat Intelligence Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Threat Intelligence Platform Market Foresight
The capital-intensity divergence between cloud-native architectures and legacy on-premises stacks is rotating competitive advantage toward vendors with elastic infrastructure. Palo Alto Networks leverages its integrated Cortex platform to sustain R&D intensity across network and endpoint intelligence layers. CrowdStrike anchors its position through native cloud architecture and real-time indicator ingestion at scale. IBM competes via managed security services and hybrid deployment flexibility for regulated end users.
A threat intelligence platform aggregates, correlates, and disseminates actionable data on malicious actors, attack vectors, and vulnerability indicators using machine-readable formats such as STIX/TAXII and automated indicator sharing protocols. These systems fuse open-source feeds, proprietary telemetry, and dark-web monitoring to enable preemptive defense across enterprise perimeters. Cloud-based deployment is capturing the fastest expansion as financial institutions and telecommunication firms prioritize elastic scalability and reduced capital overhead. Endpoint intelligence and user behavior analytics command concentrated margin pools due to specialized telemetry requirements and higher switching costs. On-premises solutions retain durable demand within government agencies bound by data sovereignty and classified network restrictions.
The U.S. Securities and Exchange Commission now mandates public companies disclose material cybersecurity incidents within four business days, amplifying procurement urgency for real-time threat intelligence. The EU NIS2 Directive extends compliance obligations to critical infrastructure operators across energy, transport, and digital services, while India's CERT-In guidelines impose strict incident reporting timelines for government and financial entities. Stakeholders must monitor how fragmented national certification regimes for threat data handling reshape vendor eligibility and cross-border platform deployment economics.
Market Dynamics
Elastic cloud-native architectures are compressing capital requirements for threat intelligence delivery while fragmenting vendor economics between hyperscale platforms and specialized telemetry providers.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident reporting obligations for energy and transport operators are accelerating procurement cycles for real-time indicator ingestion systems across member states.
- Financial services telemetry expansion:Banks and payment processors are layering fraud detection modules onto existing security stacks, creating sustained demand for behavioral analytics integration.
- STIX/TAXII protocol maturation:Standardized machine-readable threat formats are collapsing integration friction between proprietary feeds and open-source intelligence repositories.
Market Restraints
- Dark-web source concentration:Premium threat feed quality depends on a narrow set of specialized monitoring vendors with limited geographic redundancy.
- Data sovereignty compliance costs:India's CERT-In localization mandates and EU GDPR cross-border transfer restrictions are forcing redundant infrastructure deployment.
- Legacy SIEM substitution pressure:On-premises security information systems retain durable installed bases in classified government networks, slowing full-platform displacement.
Strategic Opportunities
- India sovereign cyber defense scaling:Government and critical infrastructure procurement is concentrating demand for hybrid deployment models with domestic data residency.
- 5G network slicing security:Telecommunication operators are embedding threat intelligence into edge compute nodes, opening specialized endpoint telemetry contracts.
- EU AI Act conformity:Automated decision-making transparency requirements for security algorithms are creating certification services adjacent to platform licensing.
Industry Challenges
- Threat analyst talent scarcity:Shortages of professionals fluent in STIX/TAXII curation and dark-web source verification are constraining feed quality at scale.
- Multi-cloud integration complexity:Enterprises operating across AWS, Azure, and sovereign cloud instances face fragmented indicator correlation across inconsistent APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Threat Intelligence Platform Market |
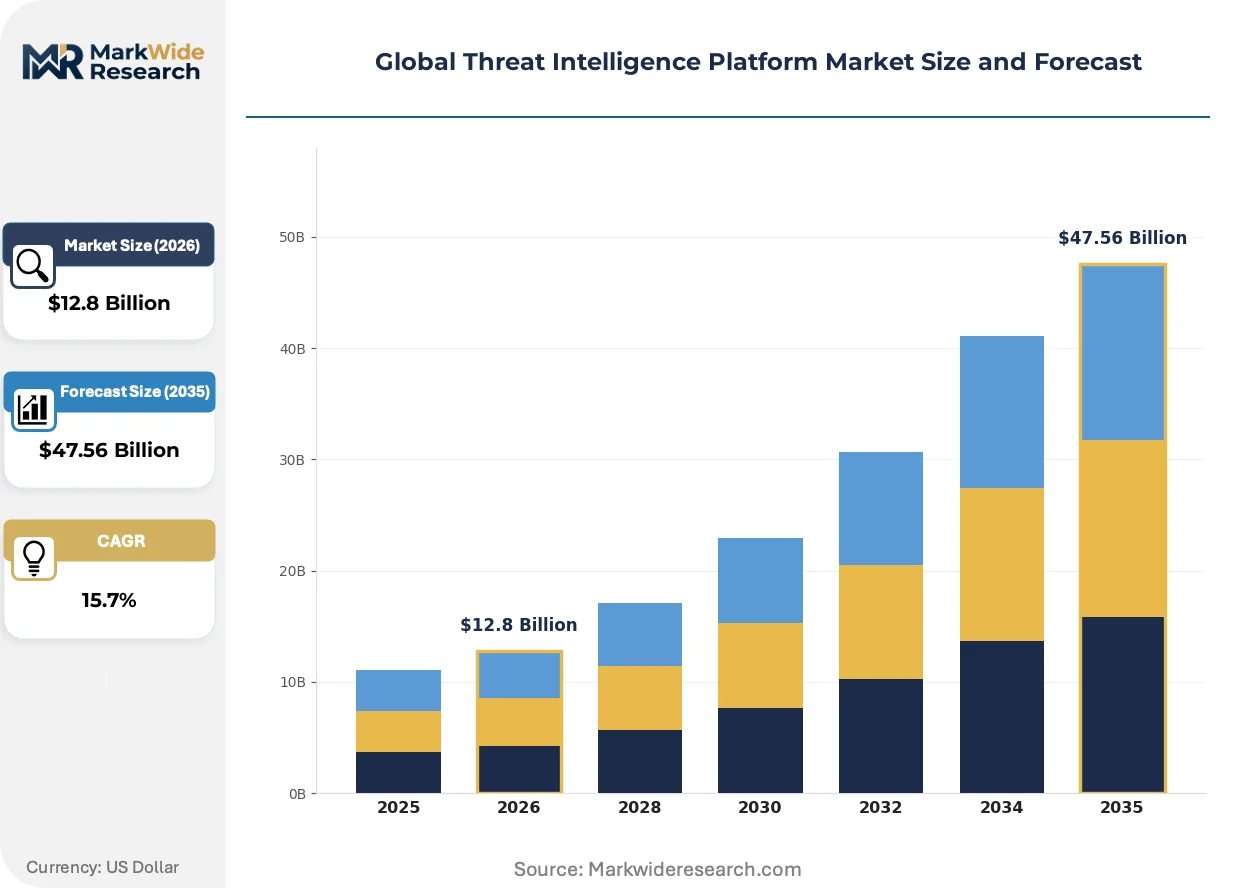
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $47.56 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution Offering: Network Intelligence, Endpoint Intelligence, Application Intelligence, User Behavior Analytics, Cloud Security Use Case: Fraud Detection, Phishing Prevention, Malware Analysis, Vulnerability Management, Incident Response End User: Financial Institutions, Telecommunication Firms, Government Agencies, Technology Providers |
| Companies Covered | Palo Alto Networks, Cisco, Check Point, CrowdStrike, IBM, Recorded Future, Google, Trend Micro, Fortinet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Threat Intelligence Platform Market Shifts & Advancements
Threat intelligence consumption is pivoting from static feed subscriptions toward dynamic, context-enriched indicator services that embed directly into automated response workflows.
Extended detection and response (XDR) architecture is bifurcating platform economics between integrated suite vendors and best-of-breed telemetry specialists. Mid-market enterprises are consolidating vendor relationships around native cloud stacks, compressing standalone threat intelligence pure-plays into niche positioning or acquisition targets. The structural consequence is margin pressure on point-solution providers without adjacent security controls.
The EU AI Act risk classification framework is mandating human oversight for automated threat scoring algorithms used in critical infrastructure. Operators in energy and transport sectors must document decision logic for machine-generated indicators, increasing compliance overhead but creating differentiation for vendors with transparent model governance. German and French regulators are issuing sector-specific guidance faster than harmonized standards can crystallize.
Security procurement at Fortune 500 enterprises is consolidating around outcome-based performance contracts with penalty clauses for false-positive rates. Traditional per-seat licensing is retreating in favor of consumption models tied to validated threat detections. This shift is most visible in United States financial services, where CISOs are unbundling threat intelligence from managed detection services to scrutinize unit economics.
Global Threat Intelligence Platform Market Segmentation
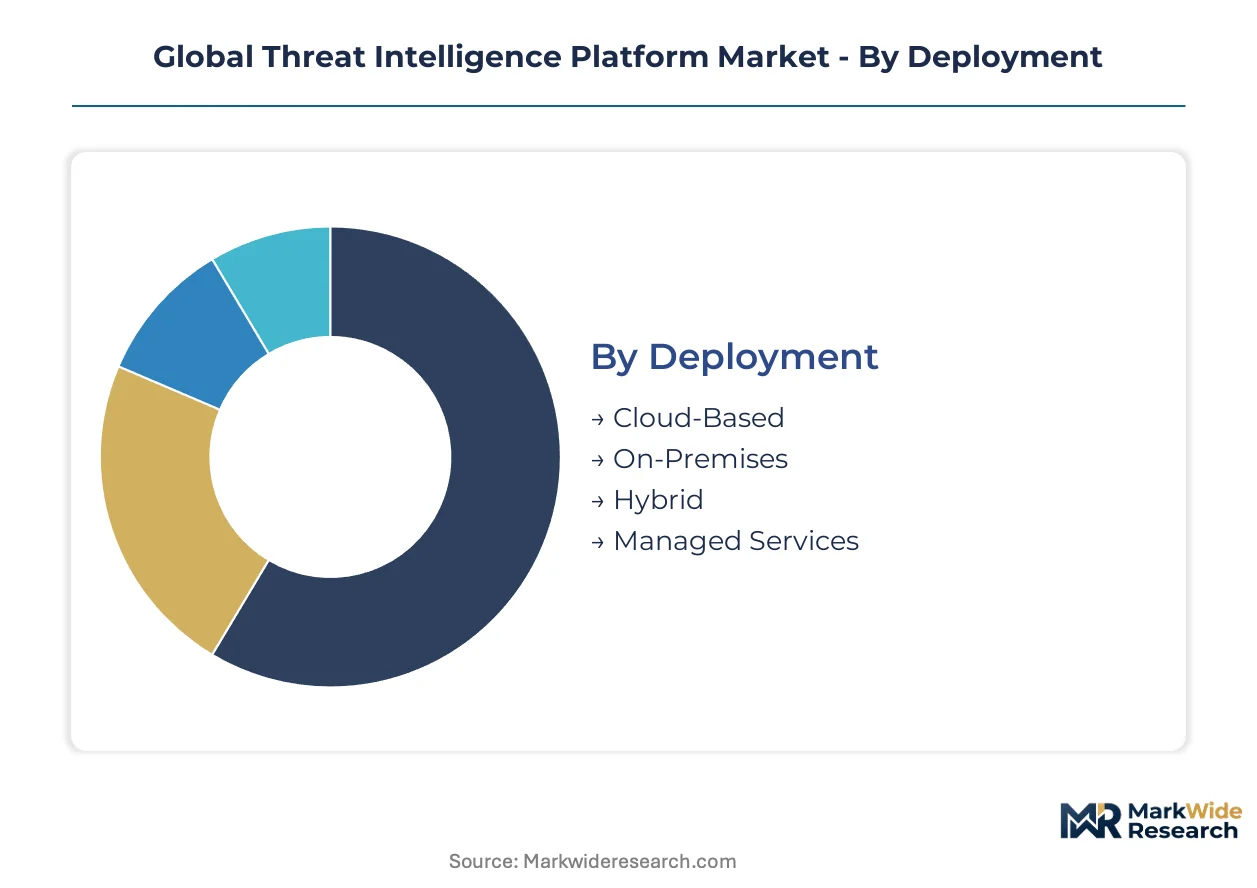
Threat intelligence platform procurement splits sharply across deployment architectures and operational use cases. Vendors must align pricing and integration complexity to distinct buyer capabilities and regulatory constraints.
Deployment:
Cloud-native delivery channels capture expanding procurement from mid-market enterprises seeking elastic capacity without capital commitment.
- Cloud-Based:Multi-tenant architectures enable rapid indicator ingestion and automated STIX/TAXII feed correlation without infrastructure ownership. Financial institutions in the United States and Germany prioritize this model for fraud detection workloads requiring burst scalability during transaction spikes.
- On-Premises:Air-gapped deployments serve classified government networks and critical infrastructure operators bound by data sovereignty mandates. India's CERT-In localization requirements and EU GDPR cross-border restrictions sustain durable demand despite higher total cost of ownership.
- Hybrid:Split architectures partition sensitive telemetry on-premises while leveraging cloud analytics for non-classified indicators. This model attracts regulated industries navigating fragmented compliance regimes.
- Managed Services:Outsourced platform operation transfers staffing burden to vendors with certified threat analysts. Telecommunication firms facing talent scarcity adopt this channel to bypass recruitment bottlenecks.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
Solution Offering:
Margin pools concentrate in telemetry layers requiring specialized sensor deployment and higher switching costs.
- Network Intelligence:Deep packet inspection and traffic flow analysis detect lateral movement and command-and-control communications. Energy sector operators under EU NIS2 Directive obligations deploy these modules for real-time perimeter monitoring.
- Endpoint Intelligence:Agent-based telemetry from workstations and servers enables behavioral anomaly detection with forensic rollback capabilities. This layer commands premium pricing due to kernel-level integration complexity and vendor certification requirements.
- Application Intelligence:Code-layer monitoring identifies vulnerability exploitation in custom software deployments. Technology providers building proprietary platforms represent concentrated demand.
- User Behavior Analytics:Baseline deviation detection flags compromised credentials and insider threats. Banking procurement teams prioritize this capability for phishing prevention and privileged access monitoring.
- Cloud Security:Native integration with AWS, Azure, and sovereign cloud APIs enables workload-aware threat correlation. Multi-cloud enterprises face fragmented indicator correlation across inconsistent interfaces.
Endpoint Intelligence captures the steepest expansion trajectory. Network Intelligence retains the largest revenue base.
Use Case:
Procurement urgency varies with regulatory disclosure timelines and financial exposure to downtime.
- Fraud Detection:Real-time transaction scoring and synthetic identity detection reduce payment processor losses. United States SEC four-day incident disclosure mandates amplify deployment urgency.
- Phishing Prevention:Email gateway integration and credential harvesting site takedown protect human attack surfaces. Financial institutions layer these modules onto existing security stacks.
- Malware Analysis:Sandbox detonation and reverse engineering accelerate threat actor attribution. Government agencies with classified sample libraries drive specialized demand.
- Vulnerability Management:Exploitability scoring and patch prioritization reduce mean-time-to-remediation. Critical infrastructure operators under EU NIS2 scope prioritize this use case.
- Incident Response:Automated playbook execution and forensic evidence preservation compress breach containment windows. Managed security service providers bundle this capability with 24/7 analyst coverage.
Fraud Detection anchors current spending. Incident Response is climbing the fastest as disclosure deadlines tighten.
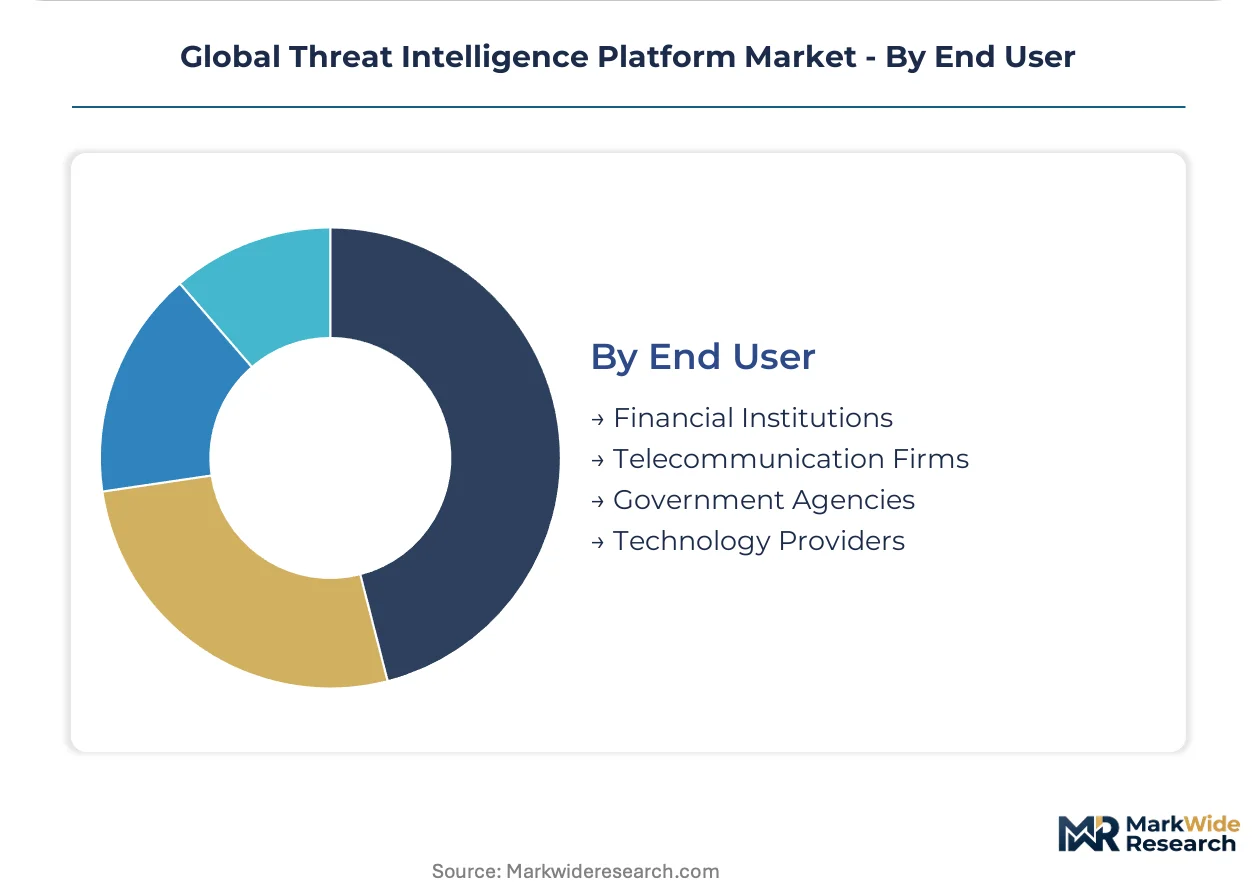
End User:
Buyer sophistication and procurement scale fragment vendor engagement models from self-service portals to dedicated account teams.
- Financial Institutions:Banks, payment processors, and insurance carriers demand behavioral analytics integration and regulatory reporting automation. United States and Indian markets show concentrated procurement velocity.
- Telecommunication Firms:5G network slicing and edge compute expansion create specialized endpoint telemetry requirements. German operators embed threat intelligence directly into subscriber-facing infrastructure.
- Government Agencies:Sovereign cyber defense programs in the United States, Germany, and India concentrate demand for hybrid deployment with domestic data residency. Classified network restrictions sustain on-premises procurement.
- Technology Providers:Cloud hyperscalers and software vendors consume threat feeds for customer-facing security services. These buyers prioritize API-native integration and consumption-based pricing.
Financial Institutions represent the largest addressable spend. Government Agencies are gaining share fastest through sovereign defense program scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in threat intelligence services favor net-importing jurisdictions with stringent data localization mandates. Sovereign cyber defense programs across multiple economies are reshaping cross-border platform deployment economics.
United States
Financial institutions and technology hyperscalers drive concentrated procurement velocity. The SEC's four-day cybersecurity incident disclosure mandate compresses procurement cycles for real-time indicator ingestion systems. Silicon Valley and New York Metro anchor the largest cluster of threat intelligence vendors and enterprise buyers.
Germany
Critical infrastructure operators under EU NIS2 Directive scope prioritize vulnerability management and network intelligence modules. The BSI (Federal Office for Information Security) issues sector-specific guidance faster than harmonized EU standards crystallize. Munich and Frankfurt concentrate telecommunication firm procurement for 5G network slicing security.
India
Government agencies and financial entities scale sovereign cyber defense programs with domestic data residency requirements. CERT-In localization mandates force redundant infrastructure deployment for foreign platform vendors. Bangalore and Mumbai represent the fastest-growing demand clusters for hybrid deployment models.
United Kingdom
Financial services telemetry expansion and managed security service adoption sustain market momentum. The National Cyber Security Centre (NCSC) guidance shapes procurement standards for behavioral analytics integration. London anchors the largest concentration of banking and insurance sector deployments.
Japan
Manufacturing and technology providers prioritize application intelligence for proprietary platform protection. METI (Ministry of Economy, Trade and Industry) guidelines encourage threat information sharing across keiretsu networks. Tokyo and Osaka host concentrated demand from industrial control system operators.
Global Threat Intelligence Platform Market Competitive Landscape
Concentration sits with integrated security suite vendors possessing adjacent cloud-native infrastructure. The vendor base spans three tiers: hyperscale platforms with native telemetry networks, specialized threat feed aggregators with dark-web monitoring capabilities, and managed security service providers bundling analyst coverage. Strategic moves center on portfolio diversification into adjacent detection layers and geographic expansion through localized data residency infrastructure.
Within the integrated platform tier, Palo Alto Networks, CrowdStrike, and IBM exemplify divergent architectural bets. Palo Alto Networks occupies a position anchored in network and endpoint intelligence convergence. CrowdStrike represents the cloud-native vector with real-time indicator ingestion at scale. IBM sits within the hybrid deployment flexibility archetype for regulated end users requiring managed security services.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Cisco |
| Check Point |
| CrowdStrike |
| IBM |
| Recorded Future |
| Trend Micro |
| Fortinet |
| Others |
Supply & Pricing Matrix
EU NIS2 Directive compliance certification gates vendor qualification and stratifies pricing tiers simultaneously, forcing foreign platform providers to absorb redundant infrastructure costs for data residency while domestic operators capture premium positioning through sovereign clearance advantages.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing with consumption tiers tied to validated threat detection volumes. Price differentiation rests on STIX/TAXII feed granularity and dark-web source exclusivity. Cost compression in mid-market cloud tiers is intensifying because hyperscale platforms bundle threat intelligence into adjacent security suites. Government agencies show lowest price sensitivity due to classified network mandates and sole-source procurement authority.
Supply Chain Analysis
The United States and Israel anchor threat feed aggregation and dark-web monitoring capabilities. Platform development draws from specialized telemetry vendors in Germany and India for localized indicator curation. Single-source vulnerability in premium dark-web source concentration creates supply chain risk. Distribution runs through direct enterprise sales for regulated sectors and hyperscaler marketplaces for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed detection and response service layers are expanding faster than standalone platform licensing, creating service-attach economics that favor vendors with embedded analyst coverage and outcome-based performance contracts.
For Market Incumbents: Secure hybrid deployment certification for India's CERT-In and EU GDPR data residency requirements before smaller competitors achieve localized infrastructure. Consolidate dark-web source relationships through exclusive partnerships with specialized monitoring vendors to defend feed quality differentiation. Prioritize API-native integration investments for multi-cloud enterprises operating across AWS, Azure, and sovereign cloud instances. For New Entrants and Emerging Players: Anchor in India's sovereign cyber defense procurement wave by building domestic data center presence and CERT-In compliance pathways ahead of foreign platform restrictions. Target mid-market financial institutions in Germany seeking EU NIS2-compliant vulnerability management modules with transparent algorithmic governance for AI Act conformity. Pursue managed services partnerships with telecommunication firms facing threat analyst talent scarcity. For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape by elevating vendors with documented machine-learning model governance and human oversight capabilities. Long-term viability centers on platform providers with adjacent security controls and native cloud architecture. Watch for CERT-In localization mandate enforcement in India as the inflection signal for geographic expansion urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converges network and endpoint intelligence layers for Palo Alto Networks Cortex ecosystem expansion. |
| Geographic Expansion | Establishes domestic data residency infrastructure for India CERT-In and EU GDPR compliance capture. |
| Acquisition of Specialist Firm | Consolidates dark-web monitoring capabilities from narrow vendor base with limited geographic redundancy. |
| Strategic Partnership | Embeds threat intelligence into German telecommunication 5G network slicing edge compute nodes. |
| Product Launch | Delivers EU AI Act-compliant automated decision transparency modules for critical infrastructure operators. |
Research Methodology
The analysis maps cloud-native deployment architectures, on-premises air-gapped systems, hybrid split models, and managed service channels, each validated through CISO interviews, threat intelligence platform engineers, managed security service procurement leads, and regulatory compliance officers. Primary fieldwork combined with secondary validation from SEC cybersecurity disclosure filings, EU NIS2 implementation guidance, CERT-In localization mandates, and hyperscaler security service capex disclosures. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Consistency checks against external benchmarks validated analytical outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution offering layer, operational use case, and end-user industry vertical. CAGRs derived from elasticity-adjusted adoption curves and regulatory mandate enforcement timelines. Forecast inputs incorporated STIX/TAXII protocol maturation velocity and sovereign cyber defense program budget allocations.
Material uncertainties — regulatory fragmentation in cross-border data transfer regimes, threat actor capability evolution, and talent scarcity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about compliance timeline adherence and technology integration friction. Recalibration cycles align with material shifts in EU AI Act enforcement patterns and India CERT-In mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Perimeter Defense System Market