
 Blast Resistant and Bulletproof Buildings Market | 2026-2036
Blast Resistant and Bulletproof Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Blast Resistant and Bulletproof Buildings Market Insights
Project finance and operational leasing for hardened infrastructure is reshaping competitive entry in blast resistant and bulletproof buildings. Satellite Shelters leverages modular lease-to-own structures to anchor recurring revenue streams. MineARC Systems specializes in integrated life-safety systems that differentiate its offering from panel-only suppliers. Total Security Solutions competes through turnkey design-build delivery that compresses procurement cycles for government clients.
Blast resistant and bulletproof buildings are engineered structures designed to withstand explosive overpressure, ballistic impact, or forced entry through reinforced concrete cores, laminated glass assemblies rated to specific threat levels, and steel-composite panel systems. These facilities serve military, diplomatic, financial, and critical infrastructure operators requiring continuous operations under physical attack scenarios. Military installations and government facilities command the largest share of current procurement, while data centers represent the fastest-growing building type as operators harden against physical sabotage. Modular units and prefabricated panels are gaining share as installation methods because factory-controlled fabrication reduces site vulnerability and accelerates deployment timelines.
The US Department of Homeland Security SAFETY Act, Underwriters Laboratories ballistic standards, and NATO STANAG blast criteria collectively define product qualification thresholds that determine market access. Saudi Arabia's General Authority for Military Industries and India's Bureau of Indian Standards are developing localized certification regimes that will fragment compliance requirements for multinational suppliers. Stakeholders must monitor whether regional certification divergence creates captive supply zones or whether mutual recognition agreements emerge to preserve cross-border procurement flexibility.
Market Dynamics
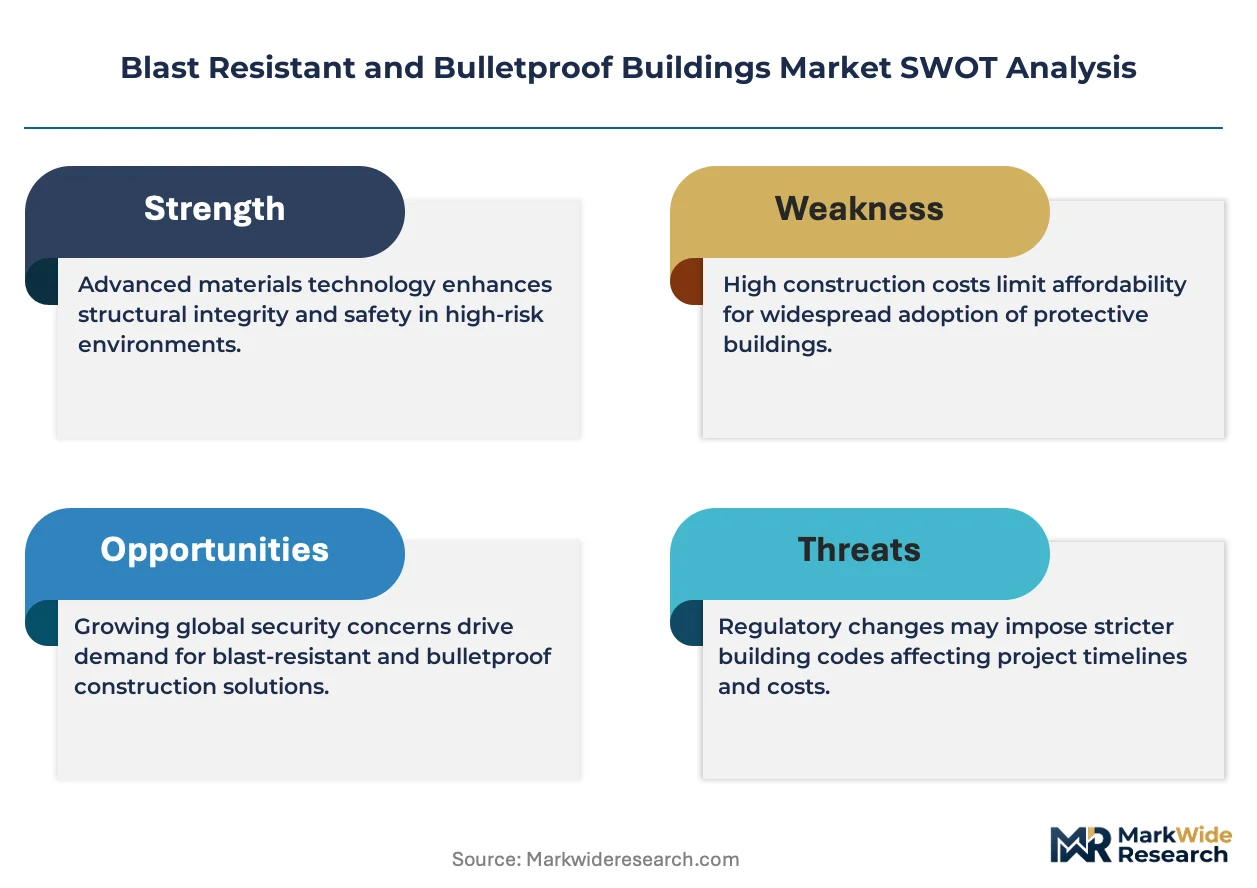
Project finance restructuring is concentrating procurement authority in sovereign wealth funds and defense ministries, compressing vendor qualification timelines while elevating certification requirements.
Growth Catalysts
- SAFETY Act certification mandates:US Department of Homeland Security tightening is forcing facility operators to upgrade perimeter hardening, expanding qualified supplier pools.
- Data center physical security:Hyperscale operators in Northern Virginia and Frankfurt are mandating blast-resistant enclosures for critical power infrastructure.
- Neom corridor development:Saudi Arabia's linear city construction is generating concentrated demand for integrated life-safety structures.
Market Restraints
- Steel-composite input volatility:Specialized ballistic-grade laminates face supply concentration among Japanese and South Korean metallurgical suppliers.
- Fragmented certification regimes:India's Bureau of Indian Standards developing localized blast criteria is creating parallel compliance tracks.
- Technical thickness limitations:Laminated glass assemblies above UL Level 8 face manufacturing yield constraints.
Strategic Opportunities
- UAE critical infrastructure:Dubai's financial district expansion lacks hardened facility stock relative to transaction volume.
- Modular lease-to-own structures:Satellite deployment models are penetrating diplomatic compound procurement.
- Green building integration:EU Green Deal energy-performance mandates are converging with security hardening specifications.
Industry Challenges
- Blast engineering talent scarcity:Computational fluid dynamics modeling for overpressure simulation requires specialized training pipelines.
- Legacy system integration:Retrofitting existing government facilities with composite panel systems demands structural reinforcement coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blast Resistant and Bulletproof Buildings Market |
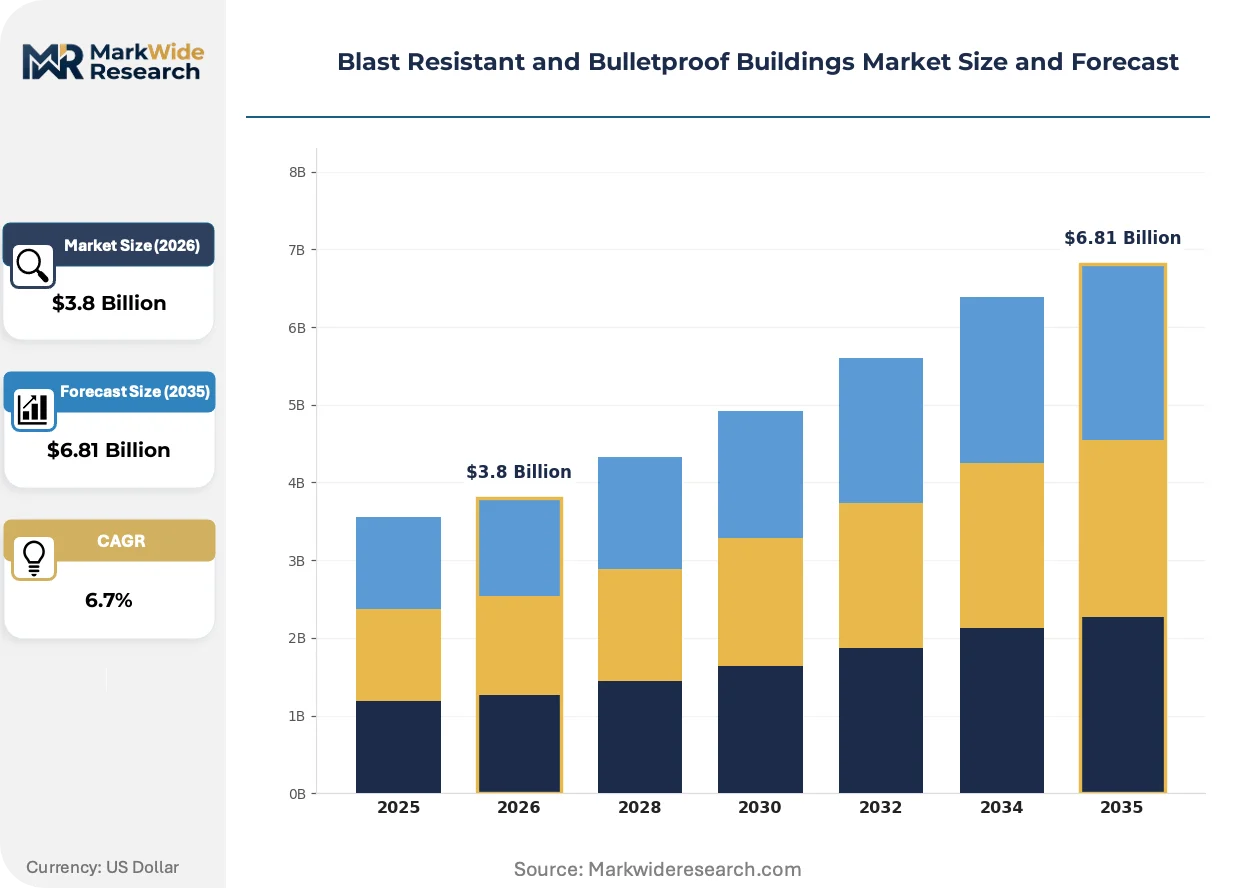
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Reinforced Concrete, Laminated Glass, Steel Panels, Composite Fabric, Polycarbonate, Kevlar Building Type: Commercial Structures, Government Facilities, Educational Institutions, Military Installations, Financial Centers, Data Centers Protection Level: Low Blast, High Blast, Ballistic Level I, Ballistic Level IV, Explosive Resistance, Forced Entry Resistance Installation Method: New Construction, Retrofitting, Modular Units, Prefabricated Panels |
| Companies Covered | Hunter Buildings, RedGuard Specialist Services, Satellite Shelters, MineARC Systems, Parkline, Inc., Total Security Solutions, The Armortex Group, Inc., Insulgard Security Products, Protective Structures, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blast Resistant and Bulletproof Buildings Market Trends and Innovations
Material science advances and procurement model disruption are compressing traditional specification cycles while elevating performance thresholds.
Ultra-high-performance concrete (UHPC) with steel fiber reinforcement is achieving equivalent blast resistance at reduced wall thickness. Data center operators in Ashburn and Loudoun County are specifying UHPC cores for new construction. Monolithic pour techniques is rendering obsolete multi-layer composite panel assemblies in vertical construction.
The EU's CSRD disclosure requirements are mandating embodied carbon reporting for security infrastructure procurement. Facility owners must now document lifecycle environmental impact alongside ballistic ratings. German federal police facilities and Dutch diplomatic compounds are piloting integrated sustainability-security specifications.
Buyers are consolidating vendor relationships around turnkey design-build contracts rather than fragmented material procurement. Government facility managers in Riyadh and Abu Dhabi are compressing vendor panels to single-source accountability. Saudi Arabia's General Authority for Military Industries is accelerating this consolidation through pre-qualified contractor registries.
Blast Resistant and Bulletproof Buildings Market Segmentation
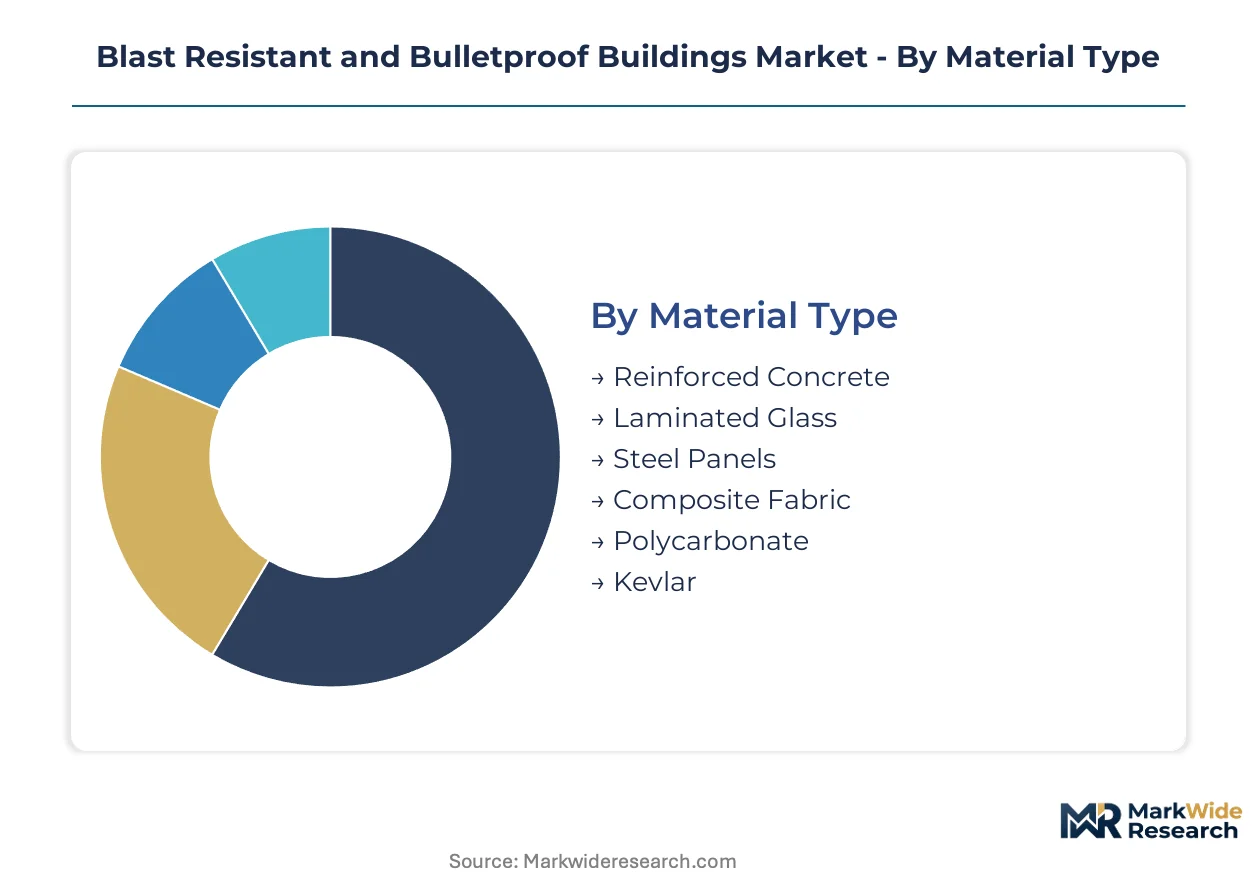
Segmentation in blast resistant and bulletproof buildings determines procurement pathways, certification requirements, and lifecycle service intensity. Material selection drives engineering complexity while installation method shapes project finance structures and vendor relationship models.
Material Type:
After-sales service intensity varies sharply across material categories, with laminated glass and composite systems demanding specialized inspection protocols and replacement logistics that reinforced concrete simply does not require.
- Reinforced Concrete:Ultra-high-performance concrete with steel fiber reinforcement achieves equivalent blast resistance at reduced wall thickness. Data center operators in Ashburn and Loudoun County specify UHPC cores for new construction, displacing multi-layer composite panel assemblies in vertical builds.
- Laminated Glass:Multi-ply assemblies rated to UL ballistic standards face manufacturing yield constraints above Level 8 thickness thresholds. Saudi Arabia's Neom corridor procurement is concentrating demand for large-format laminated glass facades in diplomatic and financial facilities.
- Steel Panels:Ballistic-grade steel-composite laminates concentrate supply among Japanese and South Korean metallurgical suppliers, creating input volatility exposure for fabricators.
- Composite Fabric:Flexible blast curtains and deployable shielding systems serve temporary protection scenarios in military forward operating bases.
- Polycarbonate:Transparent armor applications in financial centers and government facilities balance visibility with forced-entry resistance.
- Kevlar:Aramid fiber reinforcement in composite panels delivers lightweight ballistic protection for modular unit applications.
Reinforced concrete holds the largest share; momentum sits with laminated glass as architectural integration demands intensify.
Building Type:
Cost tier stratification separates military-grade hardening specifications from commercial facility budgets, with data centers occupying a premium tier that commands integrated life-safety system bundling.
- Military Installations:NATO STANAG blast criteria define minimum overpressure survival thresholds for command and control facilities. Procurement authority concentrates in defense ministries and sovereign wealth funds across Saudi Arabia and the UAE.
- Data Centers:Hyperscale operators in Northern Virginia and Frankfurt mandate blast-resistant enclosures for critical power infrastructure. Physical sabotage hardening is climbing the fastest among building types as operators address concentrated risk exposure.
- Government Facilities:US Department of Homeland Security SAFETY Act certification mandates are forcing facility operators to upgrade perimeter hardening, expanding qualified supplier pools.
- Financial Centers:Dubai's financial district expansion lacks hardened facility stock relative to transaction volume, creating supply gaps.
- Commercial Structures:Corporate headquarters and high-value asset facilities drive demand for discrete ballistic protection integration.
- Educational Institutions:Campus safety initiatives in the US are generating retrofitting demand for entry control points and safe room construction.
Military installations dominate current procurement value; data centers are expanding most quickly as physical security mandates proliferate.
Protection Level:
Volume concentration sits at the intersection of Ballistic Level IV and High Blast specifications, where government and critical infrastructure procurement overlaps.
- Ballistic Level IV:Armor-piercing rifle protection represents the threshold for high-risk diplomatic and military applications. India's Bureau of Indian Standards is developing localized blast criteria that will create parallel compliance tracks for Level IV systems.
- High Blast:Explosive overpressure resistance exceeding 10 psi serves command facilities and data center infrastructure. Neom corridor development is generating concentrated demand for integrated life-safety structures at this specification tier.
- Low Blast:Standard overpressure protection for commercial and educational facilities balances cost against credible threat scenarios.
- Ballistic Level I:Small arms protection for entry control points and screening areas in government and financial facilities.
- Explosive Resistance:Specialized hardening against vehicle-borne and package explosive threats in high-profile targets.
- Forced Entry Resistance:Delay-rated barriers protecting against manual and powered tool attacks on secure compartments.
Ballistic Level IV holds the largest share; momentum sits with High Blast as data center operators harden against physical sabotage.
Installation Method:
Customer type segmentation separates greenfield developers with new construction timelines from legacy facility managers facing retrofitting constraints and operational continuity requirements.
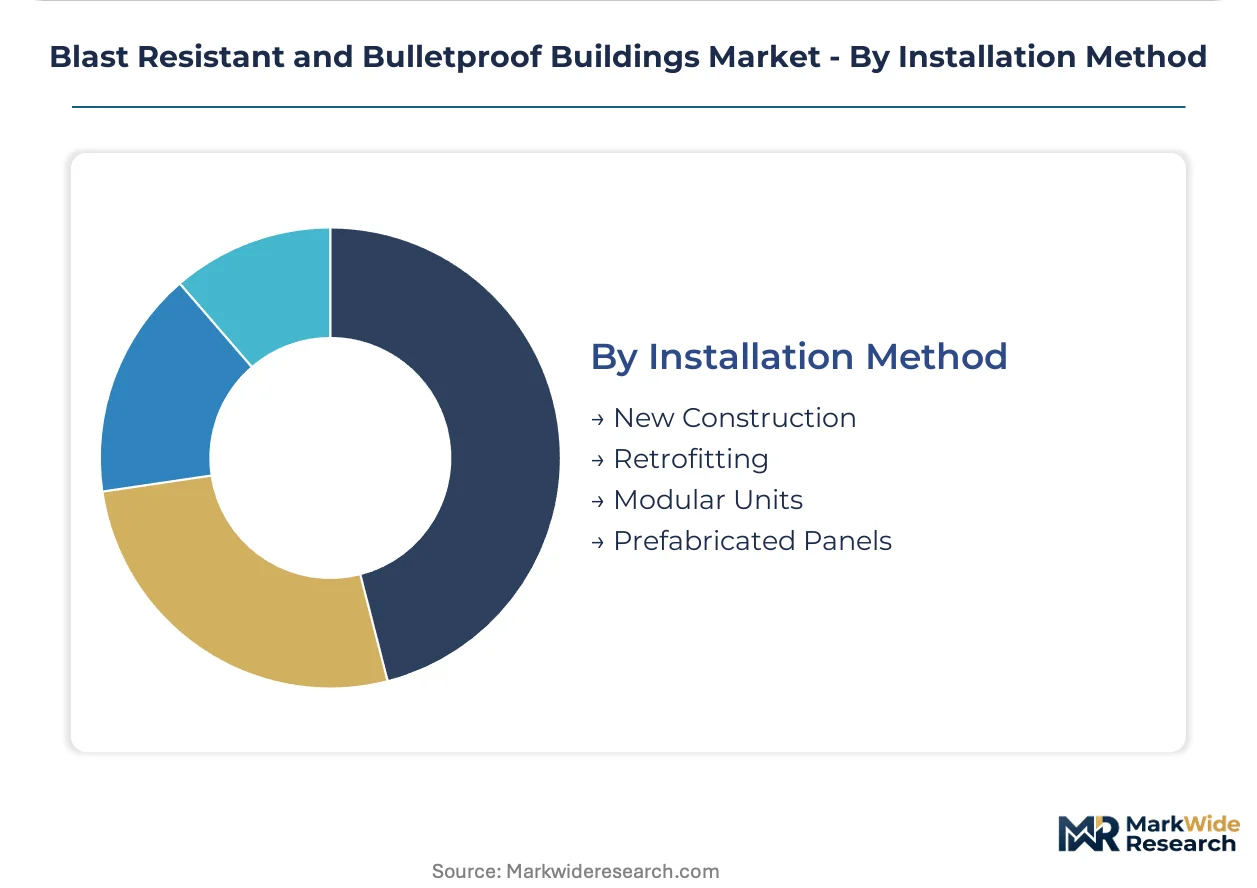
- Modular Units:Factory-controlled fabrication reduces site vulnerability and accelerates deployment timelines. Satellite deployment models are penetrating diplomatic compound procurement through lease-to-own structures.
- New Construction:Integrated design-build delivery compresses procurement cycles for government clients in Riyadh and Abu Dhabi. Saudi Arabia's General Authority for Military Industries is accelerating vendor consolidation through pre-qualified contractor registries.
- Prefabricated Panels:Steel-composite panel systems enable rapid assembly with reduced on-site welding and cutting.
- Retrofitting:Legacy system integration demands structural reinforcement coordination and phased construction to maintain facility operations.
New construction holds the largest share; momentum sits with modular units as procurement authority concentrates in sovereign wealth funds demanding speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Homeland Security's SAFETY Act certification mandates are tightening product qualification thresholds and redirecting procurement flows toward qualified suppliers. Sovereign wealth funds in Saudi Arabia and the UAE are consolidating vendor relationships around pre-qualified contractor registries. India's Bureau of Indian Standards is developing localized blast criteria that will fragment compliance requirements for multinational suppliers.
United States
Hyperscale data center operators in Northern Virginia mandate blast-resistant enclosures for critical power infrastructure. The US Department of Homeland Security's SAFETY Act certification requirements are forcing facility operators to upgrade perimeter hardening. Ashburn and Loudoun County clusters anchor demand for ultra-high-performance concrete cores in new construction.
Saudi Arabia
The General Authority for Military Industries is accelerating vendor consolidation through pre-qualified contractor registries. Neom corridor development generates concentrated demand for integrated life-safety structures at high blast specification tiers. Riyadh's government facility procurement is compressing vendor qualification timelines while elevating certification requirements.
Germany
Federal police facilities pilot integrated sustainability-security specifications under EU CSRD disclosure mandates. The EU Green Deal energy-performance requirements are converging with security hardening specifications for procurement. Frankfurt's hyperscale data center cluster mandates physical sabotage hardening for critical infrastructure.
India
The Bureau of Indian Standards is developing localized blast criteria that will create parallel compliance tracks for Level IV ballistic systems. Campus safety initiatives generate retrofitting demand for entry control points and safe room construction. Maharashtra and Delhi-NCR industrial corridors concentrate procurement for government and commercial hardening projects.
United Arab Emirates
Dubai's financial district expansion lacks hardened facility stock relative to transaction volume, creating supply gaps. The central bank and financial regulator are elevating physical security requirements for critical infrastructure operators. Abu Dhabi's sovereign wealth fund procurement is compressing vendor panels to single-source accountability.
Blast Resistant and Bulletproof Buildings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. Consolidation pressures intensify as government facility managers compress vendor panels to single-source accountability. Three archetypes dominate: modular lease-to-own providers, integrated life-safety system specialists, and turnkey design-build contractors. Strategic moves center on pre-qualified contractor registry positioning and backward integration into specialized metallurgical inputs.
Among North American modular providers, Satellite Shelters represents the lease-to-own archetype penetrating diplomatic compound procurement. MineARC Systems exemplifies the integrated life-safety specialist tier with factory-controlled fabrication capabilities. Total Security Solutions anchors the turnkey design-build vector compressing procurement cycles for government clients.
| Leading Market Players |
|---|
| Hunter Buildings |
| RedGuard Specialist Services |
| Satellite Shelters |
| MineARC Systems |
| Parkline, Inc. |
| Total Security Solutions |
| The Armortex Group, Inc. |
| Insulgard Security Products |
| Protective Structures, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Japanese and South Korean metallurgical supply concentration for ballistic-grade laminates determines both tiered pricing spreads across UL certification levels and supply chain vulnerability to input volatility. This single-source dependency compresses margins for fabricators while elevating premiums for qualified suppliers with captive metallurgical relationships.
Pricing Analysis
Certification level under UL ballistic standards and NATO STANAG blast criteria creates the primary spread between premium and standard tiers. Project-based contracting dominates, with price differentiation driven by threat-level rating and after-sales service bundling for laminated glass inspection protocols. Cost compression in standard-tier composite panels is intensifying as Indian Bureau of Indian Standards localization fragments procurement pools. Government facility operators show lowest price sensitivity due to SAFETY Act compliance mandates, while educational retrofitting buyers face acute budget constraints.
Supply Chain Analysis
Tariff exposure between Japanese metallurgical suppliers and North American fabricators dominates supply chain risk calculus. Ballistic-grade steel-composite laminates and ultra-high-performance concrete additives draw from concentrated production in Japan, South Korea, and Germany. Single-source vulnerability for specialized aramid fiber reinforcement feeds from limited Kevlar production capacity. Distribution runs through pre-qualified contractor registries in Saudi Arabia and turnkey design-build channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are entering an upswing phase as sovereign wealth funds accelerate hardened infrastructure deployment across Middle Eastern corridor developments.
For Market Incumbents: Insulate margin structures through backward integration into Japanese and South Korean metallurgical supply relationships. Pre-position inventory ahead of Bureau of Indian Standards localization deadlines to capture stranded demand from multinational suppliers facing compliance recertification costs. Lock in multi-year offtake agreements with Neom corridor developers before vendor panel consolidation completes. For New Entrants and Emerging Players: Dubai's financial district expansion offers the most penetrable white-space target, with hardened facility stock lagging transaction volume growth. Campus safety retrofitting in Indian educational institutions presents a second entry vector with lower certification barriers than military-grade procurement. Pursue modular lease-to-own structures to bypass capital-intensive fabrication requirements and anchor recurring revenue streams. For Investors and Strategic Acquirers: SAFETY Act certification tightening reshapes the acquisition landscape toward qualified suppliers with established Homeland Security vendor relationships. Long-term viability centers on integrated life-safety system capabilities rather than panel-only fabrication. Monitor India's Bureau of Indian Standards mutual recognition negotiations as the signal for whether regional certification divergence creates captive supply zones or preserves cross-border procurement flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-qualified Contractor Registry Positioning | Saudi Arabia's General Authority for Military Industries compresses vendor panels to single-source accountability. |
| Backward Integration into Metallurgical Inputs | Captive supply of Japanese ballistic-grade laminates insulates margin compression from spot market volatility. |
| Modular Lease-to-Own Structure Deployment | Satellite deployment models penetrate diplomatic compound procurement with accelerated deployment timelines. |
| Integrated Life-Safety System Bundling | Data center operators in Ashburn mandate blast-resistant enclosures with factory-controlled fabrication. |
| EU Green Deal Compliance Integration | German federal police facilities pilot sustainability-security specifications under CSRD disclosure mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense ministry procurement officers, data center facility managers, blast engineering consultants, and composite panel fabricators. Secondary validation drew from US Department of Homeland Security SAFETY Act certifications, NATO STANAG technical documentation, Saudi General Authority for Military Industries procurement registries, and Bureau of Indian Standards draft blast criteria. Bottom-up project pipeline analysis triangulated against top-down sovereign wealth fund infrastructure allocation disclosures.
Calibration anchored volume projections to observed procurement cycles across military installations, government facilities, and hyperscale data center developments. Segmentation modeling spanned material type, building type, protection level, and installation method dimensions across the analysis window. CAGRs derived from weighted average of historical defense procurement patterns and forward-projected critical infrastructure hardening mandates. Industry-specific inputs incorporated Neom corridor construction timelines and Northern Virginia data center cluster expansion permits.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed fabricators or accelerated Indian localization would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Middle East Commercial Security Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
North America Tank Protection Market