
 Global Hazardous Area Equipment Market | 2026-2036
Global Hazardous Area Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hazardous Area Equipment Market Analysis
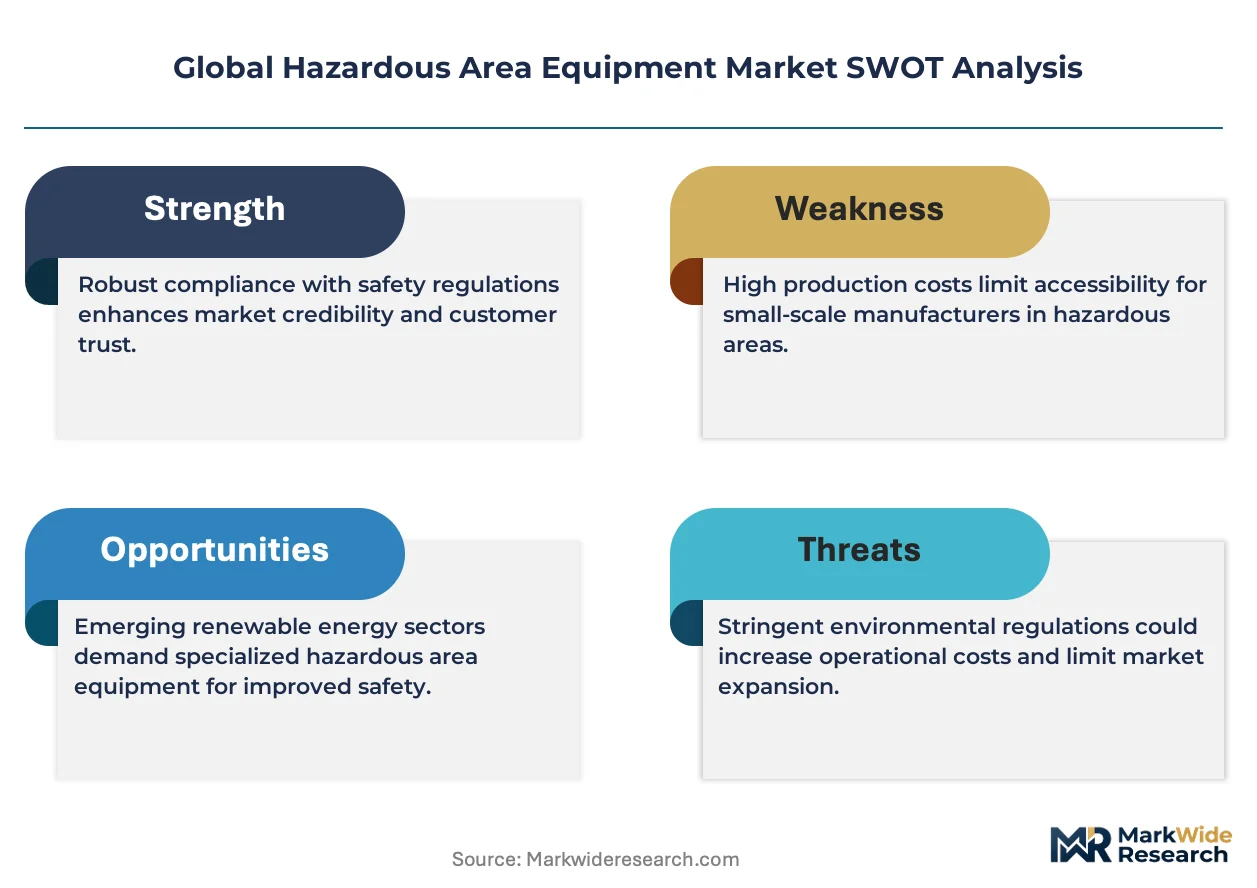
Asset-light leasing and project finance models is fragmenting competitive dynamics across hazardous area equipment procurement. ABB Ltd leverages its IECEx-certified manufacturing footprint across Europe and Asia. Siemens AG sustains R&D intensity in flameproof motor control systems. Emerson Electric Co anchors its position through integrated safety instrumented systems for upstream oil platforms.
Hazardous area equipment comprises electrical and mechanical apparatus engineered for operation in atmospheres where explosive gases, vapors, mists, or combustible dusts may be present, with enclosures typically rated IP66 or higher and surface temperatures constrained below auto-ignition thresholds of surrounding substances. The primary purpose is eliminating ignition sources while maintaining process control and personnel safety in classified zones. Flameproof technology dominates capital expenditure in offshore and refining settings due to its tolerance of internal explosions without transmitting flame to external atmospheres. Intrinsic safety leads growth in pharmaceutical cleanrooms and laboratory automation where low-power instrumentation demands minimal energy containment. Control systems concentrate margin pools through software-integrated safety logic that commands premium pricing over standalone hardware.
IECEx certification from the IEC System for Certification to Standards Relating to Equipment for Use in Explosive Atmospheres shapes product design and international market access by providing a single global conformity assessment framework. ATEX directives from the European Union and OSHA Process Safety Management standards in the United States enforce mandatory equipment marking, zone classification, and inspection protocols that drive replacement cycles and compliance spending. Stakeholders must monitor evolving hydrogen economy regulations as green hydrogen production facilities introduce new explosive atmosphere classifications demanding adapted equipment standards.
Market Dynamics
Capital allocation in hazardous area equipment pivots on IECEx certification harmonization, which compresses cross-border approval timelines and reconfigures manufacturing footprints toward multi-standard production hubs.
Growth Catalysts
- Offshore platform electrification:Deepwater operators in the United States Gulf Coast are replacing pneumatic controls with electric actuators to reduce methane venting, triggering replacement cycles across flameproof switchgear and motor starters.
- REACH chemical registration:The European Union's substance evaluation protocols are accelerating equipment upgrades in German and Dutch chemical clusters as legacy sealing materials face compliance sunsets.
- Intrinsic safety instrumentation:Pharmaceutical manufacturers in Switzerland and Singapore are adopting low-power sensor networks for sterile processing environments, expanding addressable equipment categories beyond traditional heavy industry.
Market Restraints
- Stainless steel input volatility:Enclosure fabrication depends on nickel-alloy grades whose price swings compress margin visibility for European fabricators serving North Sea projects.
- Foundry concentration:Sand-casting capacity for explosion-proof housings clusters in Indian and Chinese industrial zones, creating single-source vulnerability for tier-one assembly plants.
- ATEX Notified Body bottlenecks:Certification queue lengths at EU-accredited assessment bodies extend project commissioning timelines, particularly for customized control panel configurations.
Strategic Opportunities
- Green hydrogen electrolyzer buildout:Saudi Arabia's NEOM and Australia's Pilbara projects are defining new Zone 2 classification parameters for alkaline and PEM cell housings, opening equipment specification windows ahead of codified standards.
- WirelessHART convergence:Integration of ISA100.11a protocols with legacy 4-20mA infrastructure enables predictive maintenance deployments in Norwegian offshore assets without full cable replacement.
- OSHA Process Safety Management audits:US refinery enforcement intensity is creating aftermarket inspection and recertification service demand that equipment OEMs can capture through captive service arms.
Industry Challenges
- IECEx 02 personnel competency:Qualified inspection engineer scarcity in Brazilian and Mexican industrial corridors delays commissioning and voids manufacturer warranty conditions.
- Legacy DCS integration:Safety instrumented system upgrades in Japanese petrochemical complexes require custom gateway development to bridge 1980s-era Honeywell and Yokogawa architectures with modern Ethernet-APL field devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hazardous Area Equipment Market |
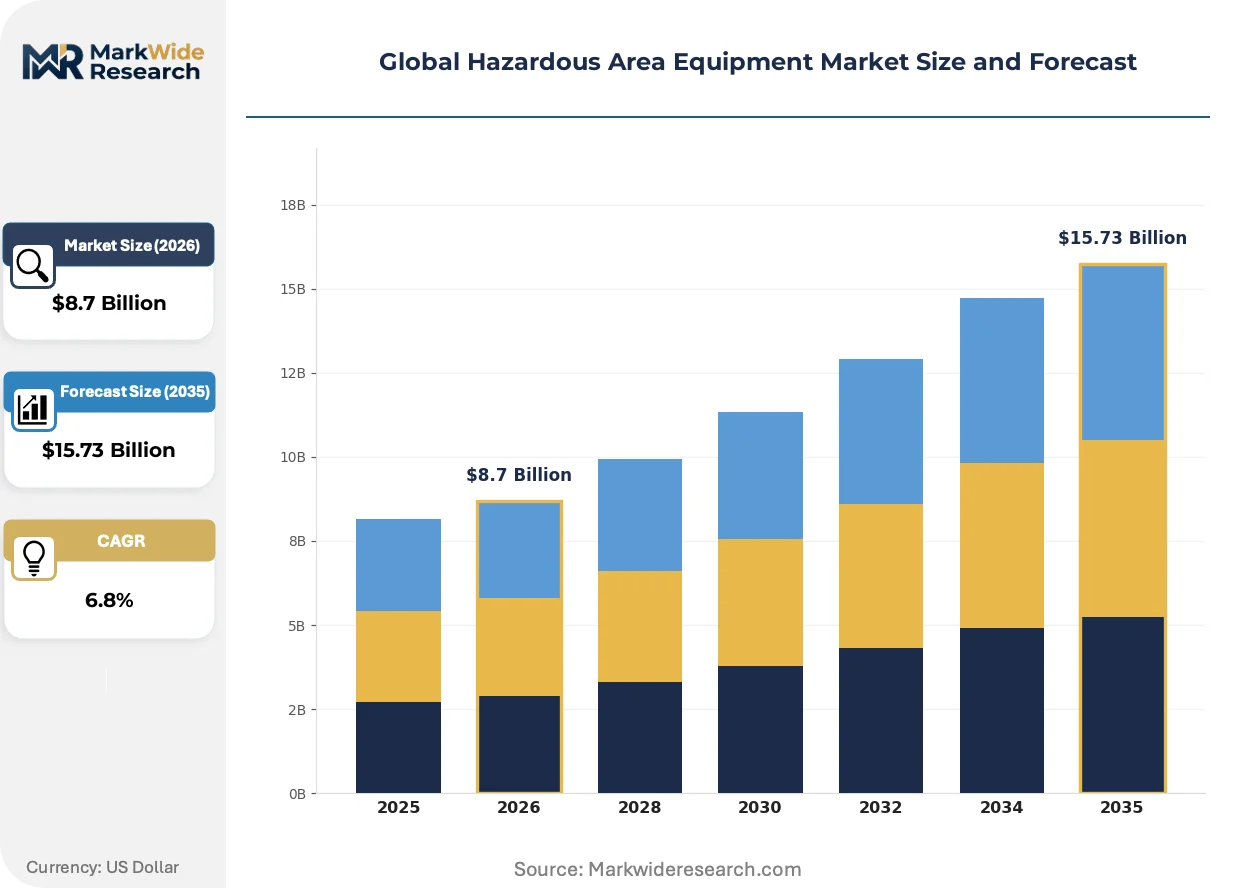
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
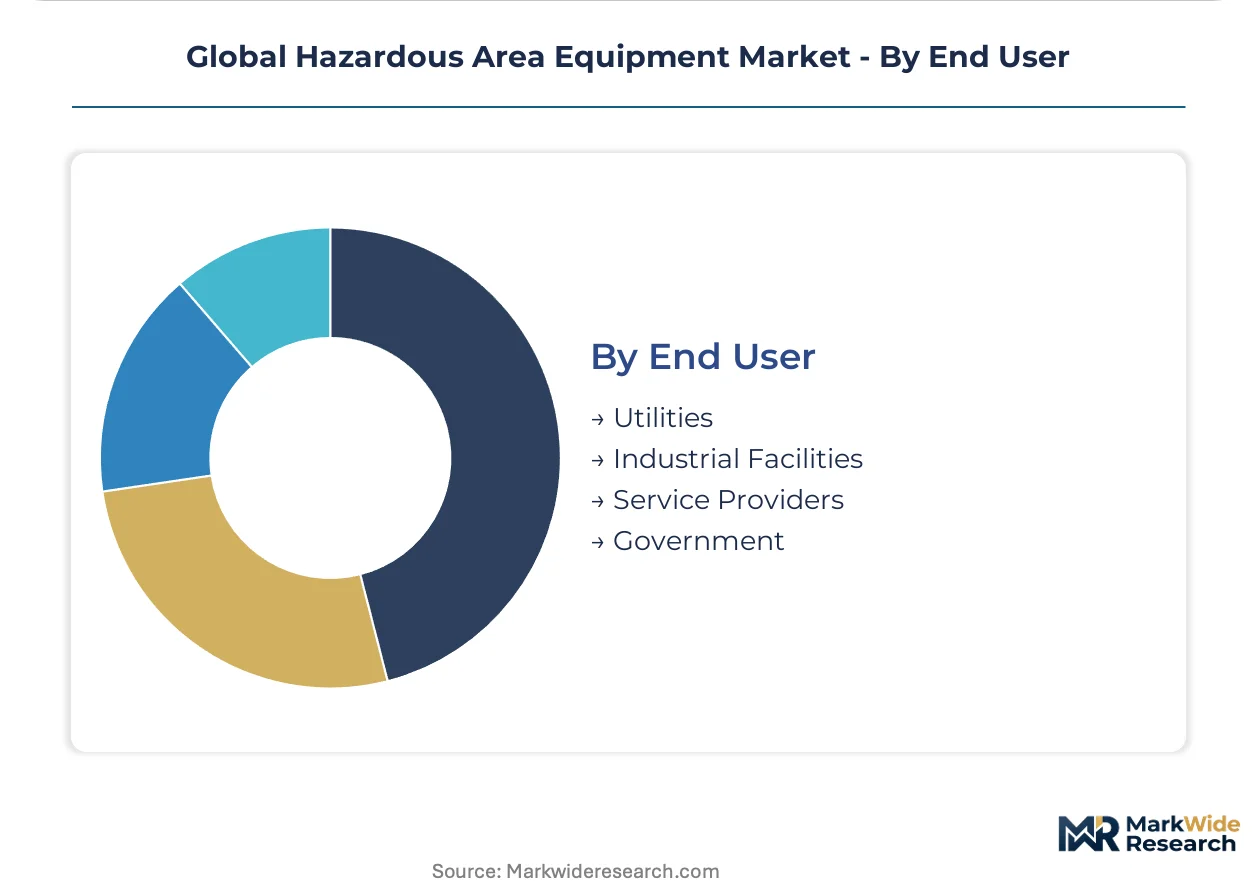
| Segmentation | Product Type: Lighting, Control Systems, Sensors, Disconnect Switches Technology: Intrinsic Safety, Flameproof, Increased Safety, Non-Incendive Application: Oil & Gas, Chemical Processing, Mining, Pharmaceutical End User: Utilities, Industrial Facilities, Service Providers, Government |
| Companies Covered | ABB Ltd, Siemens AG, Eaton Corporation, Honeywell International Inc, Rockwell Automation, Emerson Electric Co, Patlite Corporation, R. STAHL AG, WERMA Signaltechnik GmbH + Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hazardous Area Equipment Market Emerging Trajectories
Equipment architecture is compressing toward unified communication backbones that collapse the traditional separation between process control and safety systems into single-cable infrastructures.
Flameproof enclosure design is migrating from cast aluminum toward engineered polymer composites with metallic mesh Faraday shielding. Offshore platform operators in Norway and the UK North Sea are piloting these lightweight housings for topside instrumentation to reduce structural load and installation labor. The shift is compressing total installed cost curves while testing long-term UV and salt-spray durability against decades of aluminum field history.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based cooling media is forcing recertification of pressurized enclosure air-conditioning units used in Middle Eastern petrochemical facilities. Equipment vendors are redesigning thermal management around CO2 or hydrocarbon refrigerants, with German TÜV and DEKRA Notified Bodies establishing new test protocols. This regulatory vector most acutely affects analyzer shelter and control room HVAC suppliers serving Abu Dhabi and Qatar expansion projects.
Asset operators are unbundling aftermarket service from original equipment procurement, driving independent inspection contractors to capture recurring revenue streams previously held by manufacturers. Singapore's Jurong Island cluster and Rotterdam's Port Industrial Complex exhibit the most advanced disintermediation, with facility owners directly contracting Ex-certified maintenance specialists for turnaround planning and equipment fitness-for-service assessments.
Global Hazardous Area Equipment Market Segmentation
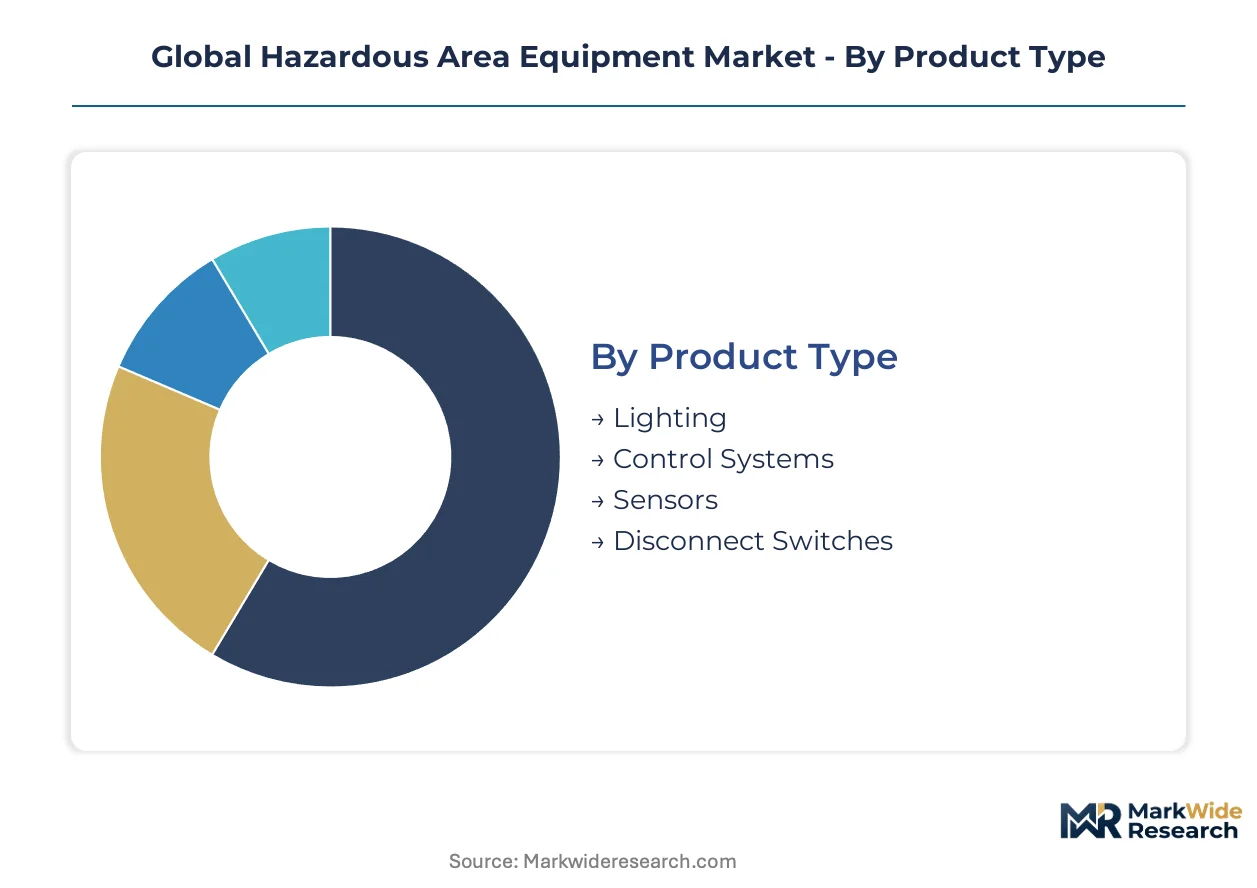
Segmentation in hazardous area equipment reveals how replacement cycles, certification complexity, and end-use risk profiles create divergent margin structures across product categories. Understanding these fault lines helps suppliers calibrate inventory, service attach rates, and R&D allocation against actual revenue velocity rather than aggregate market size.
Product Type:
Replacement cycles vary dramatically across product categories, with consumable components turning over fastest while capital-intensive systems endure decades.
- Lighting:LED fixture retrofits in United States Gulf Coast refineries are compressing replacement intervals from seven years to three as lumen degradation triggers proactive swaps. Norwegian offshore platforms are driving specification toward integrated emergency lighting with battery backup, tightening vendor qualification requirements.
- Control Systems:These integrated safety instrumented systems command the longest sales cycles and highest service attach rates. German chemical clusters along the Rhine are consolidating distributed control architectures into single-cable Ethernet-APL backbones, forcing legacy migration projects.
- Sensors:Pressure and temperature transmitters with WirelessHART capability are gaining share fastest in Singapore's Jurong Island process plants.
- Disconnect Switches:Heavy-duty isolation equipment for motor circuits sees concentrated demand from Australian mining operations facing mandatory arc-flash compliance upgrades.
Control Systems dominates installed base. Sensors is where expansion concentrates.
Technology:
Cost tiers stratify sharply across protection methodologies, with premium containment technologies commanding multiples over simplified approaches.
- Flameproof:Cast or fabricated enclosures withstand internal explosions without transmitting flame to external atmospheres. Deepwater platforms off Brazil's Santos Basin specify these for switchgear and motor starters where maintenance access is restricted and failure consequences are catastrophic.
- Intrinsic Safety:Energy-limiting designs restrict available power below ignition thresholds through galvanic isolation and zener barriers. Swiss pharmaceutical manufacturers in Basel are deploying these for sterile processing sensor networks where explosive solvents coexist with cleanroom requirements.
- Increased Safety:Enhanced construction techniques prevent arcs and sparks in normal operation without containing internal explosions. UAE petrochemical expansions in Ruwais are specifying these for terminal boxes and junction enclosures in Zone 2 areas.
- Non-Incendive:Simplified protection for Division 2/Zone 2 locations where hazardous concentrations are unlikely. United States utility substations are adopting these for remote monitoring equipment to reduce certification costs.
Flameproof anchors heavy-industry procurement budgets. Intrinsic Safety is climbing the fastest as pharmaceutical and laboratory automation expands addressable equipment categories.
Application:
Customer maturity and regulatory enforcement intensity create divergent purchasing behaviors across end-use sectors.
- Oil & Gas:Upstream, midstream, and downstream operations spanning offshore platforms, pipelines, and refineries. Saudi Aramco's Marjan and Berri expansion projects are driving specification of Zone 1-rated equipment for gas compression trains.
- Chemical Processing:Petrochemical, specialty chemical, and agrochemical production facilities. Rotterdam's Port Industrial Complex is accelerating equipment upgrades as ECHA substance evaluations sunset legacy sealing elastomers.
- Mining:Underground and surface extraction operations with combustible dust hazards. Australian coal operations in Queensland are retrofitting continuous miner monitoring systems following recent methane ignition incidents.
- Pharmaceutical:API synthesis, formulation, and packaging with solvent vapor exposure. Singapore's Tuas biomedical manufacturing hub is defining new equipment standards for potent compound containment combined with explosion protection.
Oil & Gas commands the largest historical procurement volumes. Pharmaceutical is expanding most quickly as sterile processing automation penetrates laboratory and manufacturing environments.
End User:
Procurement authority and technical sophistication fragment across buyer categories, with implications for sales channel design and service bundling.
- Industrial Facilities:Owner-operators of process plants with captive engineering staff. BASF's Ludwigshafen complex maintains dedicated Ex-equipment specification teams that bypass distributors for direct OEM relationships.
- Utilities:Electricity, gas, and water infrastructure operators with standardized procurement frameworks. Tokyo Electric Power Company is consolidating hazardous area specifications across nuclear decommissioning and conventional generation assets.
- Service Providers:Engineering, procurement, and construction contractors with project-based demand. Technip Energies and McDermott International specify equipment packages for lump-sum turnkey contracts across Middle Eastern and Southeast Asian projects.
- Government:Defense, space, and strategic reserve facilities with specialized security requirements. India's Defence Research and Development Organisation is qualifying indigenous explosion-proof equipment for missile propellant handling.
Industrial Facilities retain the deepest installed base relationships. Service Providers are capturing specification influence as lump-sum contracting expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in hazardous area equipment tilt toward net-importing industrial clusters as fabrication capacity concentrates in India and China while specification authority rests with end-users in the United States and Germany.
United States
OSHA Process Safety Management enforcement intensifies across Texas and Louisiana refineries, driving replacement demand for flameproof switchgear. The Gulf Coast petrochemical corridor anchors procurement volumes as operators electrify offshore platforms. Houston-based engineering contractors specify Zone 1-rated equipment for shale gas compression facilities.
Germany
ECHA substance evaluations under REACH accelerate equipment upgrades in Ludwigshafen and Leverkusen chemical complexes. German TÜV and DEKRA Notified Bodies shape global certification protocols for pressurized enclosures. The Rhine-Ruhr industrial cluster demands redesigned thermal management as EU F-Gas Regulation phases down hydrofluorocarbon cooling media.
China
GB standards alignment with IECEx frameworks streamlines export approvals for Zhejiang and Jiangsu enclosure fabricators. The country's national standards body accelerates certification reciprocity for equipment serving Middle Eastern petrochemical projects. Yangtze River Delta foundries supply sand-cast explosion-proof housings to tier-one assembly plants worldwide.
Saudi Arabia
Saudi Aramco's Marjan and Berri expansion projects define new Zone 2 classification parameters for gas compression trains. The national petroleum regulator coordinates equipment specifications with IECEx protocols for offshore platform electrification. Ruwais petrochemical complexes drive demand for increased safety terminal boxes in Zone 2 areas.
Singapore
Tuas biomedical manufacturing hub establishes equipment standards for potent compound containment combined with explosion protection. Jurong Island process plants adopt WirelessHART pressure and temperature transmitters fastest in Southeast Asia. The national workplace safety regulator mandates Ex-certified maintenance specialists for turnaround planning.
Global Hazardous Area Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in enclosure fabrication and signaling devices. The vendor base organizes into three tiers: diversified electrical conglomerates with captive certification infrastructure, mid-scale specialists focused on single protection methodologies, and regional fabricators serving project-specific procurement. Consolidation pressure concentrates among European enclosure specialists as Asian foundries capture upstream margin. Competitive moves center on IECEx multi-standard manufacturing hub establishment and aftermarket service unbundling to capture inspection revenue.
Among diversified electrical conglomerates, ABB Ltd and Siemens AG occupy positions spanning integrated safety systems through component supply. R. STAHL AG exemplifies the protection-technology specialist archetype with concentrated expertise in explosion-proof enclosures. These three entities represent distinct strategic postures: the full-platform integrator, the diversified industrial electrics provider, and the focused hazardous area specialist.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Eaton Corporation |
| Honeywell International Inc |
| Rockwell Automation |
| Emerson Electric Co |
| Patlite Corporation |
| R. STAHL AG |
| WERMA Signaltechnik GmbH + Co. KG |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta foundries wield outsized leverage over global enclosure pricing as sand-casting capacity for explosion-proof housings concentrates in Zhejiang and Jiangsu provinces. This geographic chokepoint transmits nickel-alloy volatility directly into European fabricator margins while amplifying bargaining power for tier-one assembly plants sourcing at volume.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with IECEx certification grade and after-sales service bundling as the primary differentiation drivers. Cost compression in economy-tier flameproof enclosures is intensifying because Indian and Chinese foundries are expanding sand-casting output. EPC contractors lump-sum contracting oil and gas projects exhibit the highest price sensitivity, while owner-operators with captive engineering staff prioritize certification reliability over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement negotiations as tier-one OEMs deploy supply-chain finance facilities to offset working capital pressure. Sand-cast aluminum enclosures draw from Yangtze River Delta foundries, nickel-alloy grades from Indonesian smelters, and engineered polymer composites from German compounders. Single-source vulnerability in sand-casting capacity creates acute exposure to logistics chokepoints through Shanghai port congestion. Distribution runs through authorized distributors serving project-based EPC contractors and direct OEM relationships with industrial facility owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified IECEx 02 inspection engineers represent the critical bottleneck constraining market expansion, with scarcity most acute in Brazilian and Mexican industrial corridors where commissioning delays void manufacturer warranties.
For Market Incumbents: Harden certification infrastructure by expanding IECEx multi-standard manufacturing hubs into India and Southeast Asia to deflect margin pressure from European foundry dependence. Deepen captive aftermarket service arms to recapture inspection revenue streams now migrating to independent Ex-certified contractors. Prioritize personnel competency training partnerships with Brazilian and Mexican technical institutes to preempt warranty exposure. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical sterile processing automation where intrinsic safety instrumentation demand outpaces incumbent R&D investment. Target Singapore's Tuas biomedical manufacturing hub and Swiss Basel chemical clusters where cleanroom explosion protection standards remain underdefined. Pursue WirelessHART sensor network integration as the go-to-market angle, bridging legacy 4-20mA infrastructure without full cable replacement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors protection-technology specialists with concentrated explosion-proof enclosure expertise over diversified electrical conglomerates. Long-term viability hinges on IECEx certification reciprocity expansion and green hydrogen electrolyzer standard codification. Watch Saudi Aramco's NEOM and Australia's Pilbara project equipment specifications as the signal for alkaline and PEM cell housing classification parameters crystallizing into addressable demand.| Strategic Initiative | Industry Significance |
|---|---|
| IECEx Multi-Standard Hub Establishment | Compresses cross-border approval timelines for ABB and Siemens serving Middle Eastern petrochemical expansions. |
| Captive Aftermarket Service Expansion | Recaptures inspection revenue streams migrating to independent contractors on Singapore's Jurong Island. |
| Engineered Polymer Composite R&D | Reduces structural load for Norwegian offshore platform operators piloting lightweight flameproof housings. |
| WirelessHART Protocol Integration | Enables predictive maintenance deployments in North Sea assets without full cable replacement cycles. |
| Green Hydrogen Equipment Pre-Standardization | Positions vendors ahead of codified Zone 2 classifications for Saudi NEOM and Australian Pilbara electrolyzer projects. |
Methodological Framework
A spread of perspectives from plant maintenance directors, OEM procurement teams, aftermarket service heads, and EPC contractor specification engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against IECEx certification databases, OSHA enforcement records, ECHA substance evaluation registries, and customs trade flows for explosion-proof enclosure imports. Bottom-up equipment shipment tallies triangulated against top-down petrochemical and pharmaceutical capital expenditure disclosures.
Demand-supply balance modeling across the analysis window integrated protection technology type, end-use sector risk classification, and regional regulatory enforcement intensity as core segmentation dimensions. CAGRs were derived from replacement cycle analysis, green hydrogen project pipeline tracking, and WirelessHART adoption curve benchmarking. Forecast inputs included stainless steel price volatility indices and ATEX Notified Body certification queue length trends.
Stress conditions across nickel-alloy input costs, IECEx 02 personnel availability, and green hydrogen standard codification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification harmonization progress and offshore platform electrification rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Middle East Commercial Security Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market