
 Hostel Market | 2026-2036
Hostel Market Size, Share, and Industry Trends Forecast 2026-2036
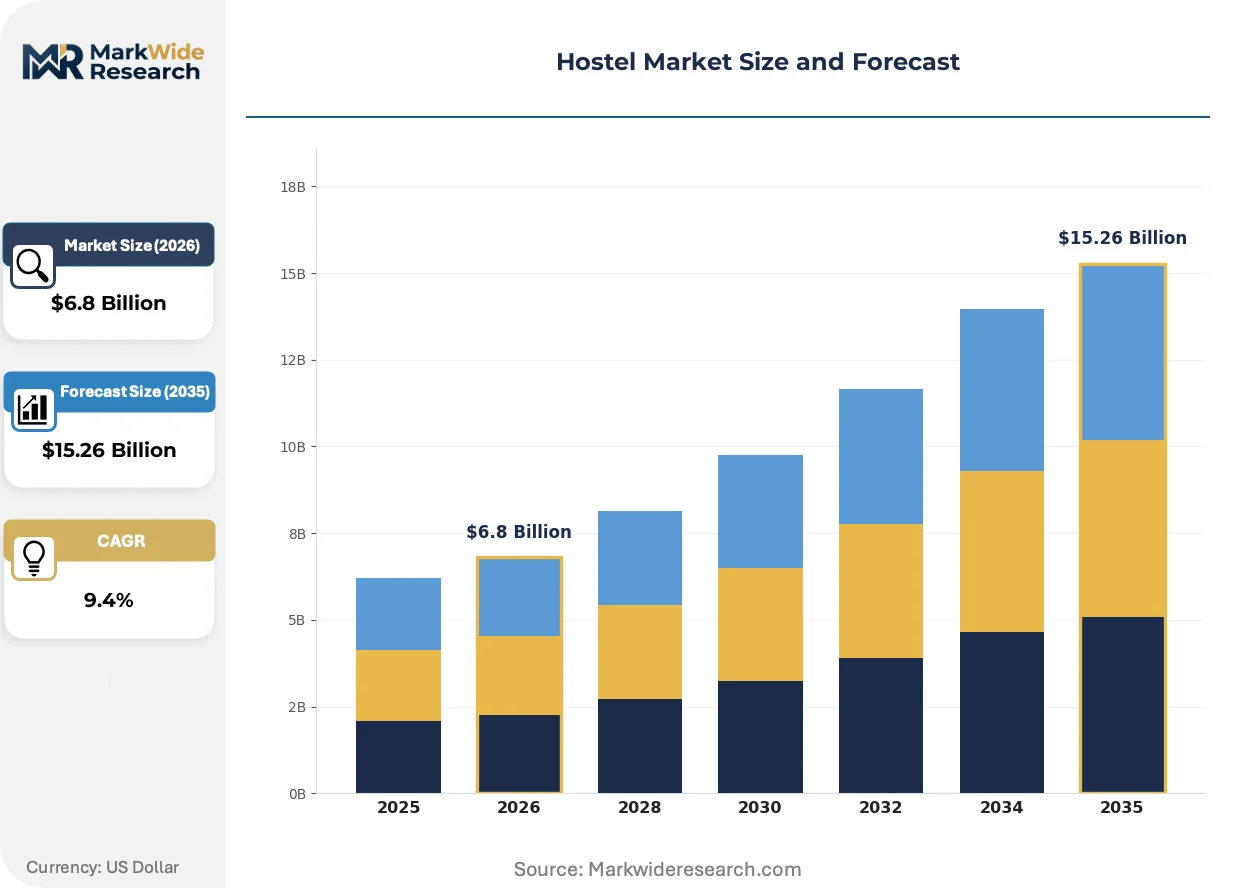
Hostel Market Outlook
Upmarket hostel tiers with boutique design standards and en-suite amenities is reorganizing competitive dynamics across the sector. Selina Hostels leverages integrated co-working spaces to anchor its appeal among digital nomads in Latin American and European urban centers. Meininger Hotels sustains a hybrid hotel-hostel format that dominates city-center locations with standardized service levels. Generator Hostels differentiates through design-led interiors and curated social programming that commands premium rates in gateway cities.
A hostel constitutes a shared lodging facility offering dormitory-style beds, communal living spaces, and self-catering kitchens at price points below conventional hotels, typically operating with staff-to-guest ratios under 1:15 and bed densities exceeding 4 per room. Its primary commercial purpose centers on maximizing occupancy through high-turnover, low-margin economics while cultivating community-oriented environments that extend average length of stay. Shared dorms retain the largest volume share across the accommodation type dimension, though private rooms capture disproportionate margin pools as operators blend hostel social architecture with hotel privacy expectations. The digital nomad segment within target demographics posts the steepest growth trajectory, driven by month-long stays and co-working amenity bundles that transform hostels into hybrid hospitality-workspace assets.
The EU Green Deal and national building efficiency codes in Germany and France mandate energy retrofit timelines that elevate capital requirements for older hostel stock, while GDPR compliance shapes direct booking platform architecture across European operators. Health Canada guidelines and local fire safety ordinances in Toronto and Vancouver impose occupancy density ceilings that constrain dormitory expansion in North American urban cores. Stakeholders must weigh regulatory compliance timelines against renovation cycles when allocating capital across aging property portfolios.
Market Dynamics
Remote management platforms are compressing operational labor costs while elevating capital requirements for property technology infrastructure across the hostel sector. This structural shift favors scaled operators with centralized revenue management capabilities over fragmented independent properties.
Growth Catalysts
- EU Green Deal retrofit mandates:Germany and France impose building efficiency timelines that accelerate property modernization and extend asset lifecycles for compliant operators.
- Digital nomad visa proliferation:Portugal, Spain, and Costa Rica introduce extended-stay permits that directly expand addressable demand for month-long hostel bookings.
- Southeast Asian urban tourism corridors:Vietnam, Thailand, and Indonesia concentrate new property development where infrastructure investment outpaces supply growth.
Market Restraints
- GDPR compliance architecture:European direct booking platforms face mandatory data governance investments that elevate fixed technology costs.
- Fire safety density ceilings:Toronto and Vancouver ordinances cap dormitory occupancy expansion in core urban locations.
- Hotel chain downmarket entry:Economy hotel brands introduce competitive price points with private room inventory that substitutes for hostel private room revenue pools.
Strategic Opportunities
- Co-working amenity bundling:Month-long stays with integrated workspace access transform hostel economics through reduced guest acquisition costs.
- Indonesia secondary city penetration:Yogyakarta and Bandung exhibit supply gaps relative to inbound volume growth from regional tourism.
- Health Canada guideline harmonization:National standards development creates pathway for standardized operational protocols across provincial jurisdictions.
Industry Challenges
- Revenue management talent scarcity:Dynamic pricing algorithm operation requires specialized hospitality-analytics skills unavailable in traditional hostel management pipelines.
- Legacy property management system integration:Older inventory lacks API connectivity for centralized platform deployment without parallel hardware replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hostel Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Shared Dorms, Private Rooms, Capsule Rooms, Luxury Hostels Service Model: Self-Service, Full-Service, Part-Time Staff, Remote Management Target Demographic: Backpackers, Students, Digital Nomads, Budget Travelers Booking Channel: Online Travel Agents, Direct Booking, Mobile Apps, Travel Agencies |
| Companies Covered | Selina Hostels, Meininger Hotels, Hostelling International (HI), Wombat's Hostels, The Youth Hostels Association (YHA), a&o Hotels and Hostels GmbH, St Christopher's Inns, Safestay Hotels & Hostels, Generator Hostels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hostel Market Strategic Shifts
Operational technology deployment is fragmenting competitive advantage sources across the hostel sector. Properties now differentiate through integrated service ecosystems rather than location or price alone.
Smart access control systems incorporating mobile key distribution and automated check-in terminals are miniaturizing front-desk labor requirements. Mid-scale hostel chains in Germany and the Netherlands deploy these systems fastest, compressing staff-to-guest ratios below 1:20 while maintaining service quality metrics.
GDPR enforcement actions by CNIL in France and similar national regulators across the EU are mandating explicit consent architectures for guest data processing. Direct booking platforms now absorb compliance engineering costs previously externalized to online travel agencies, shifting channel economics toward owned-digital capture.
Extended-stay procurement patterns among remote workers are displacing traditional nightly booking behavior in urban hostel clusters. Lisbon, Mexico City, and Medellín properties report month-long stay concentrations above 40% of bed-nights, forcing operational redesign around laundry, food service, and community programming cadences.
Hostel Market Segmentation
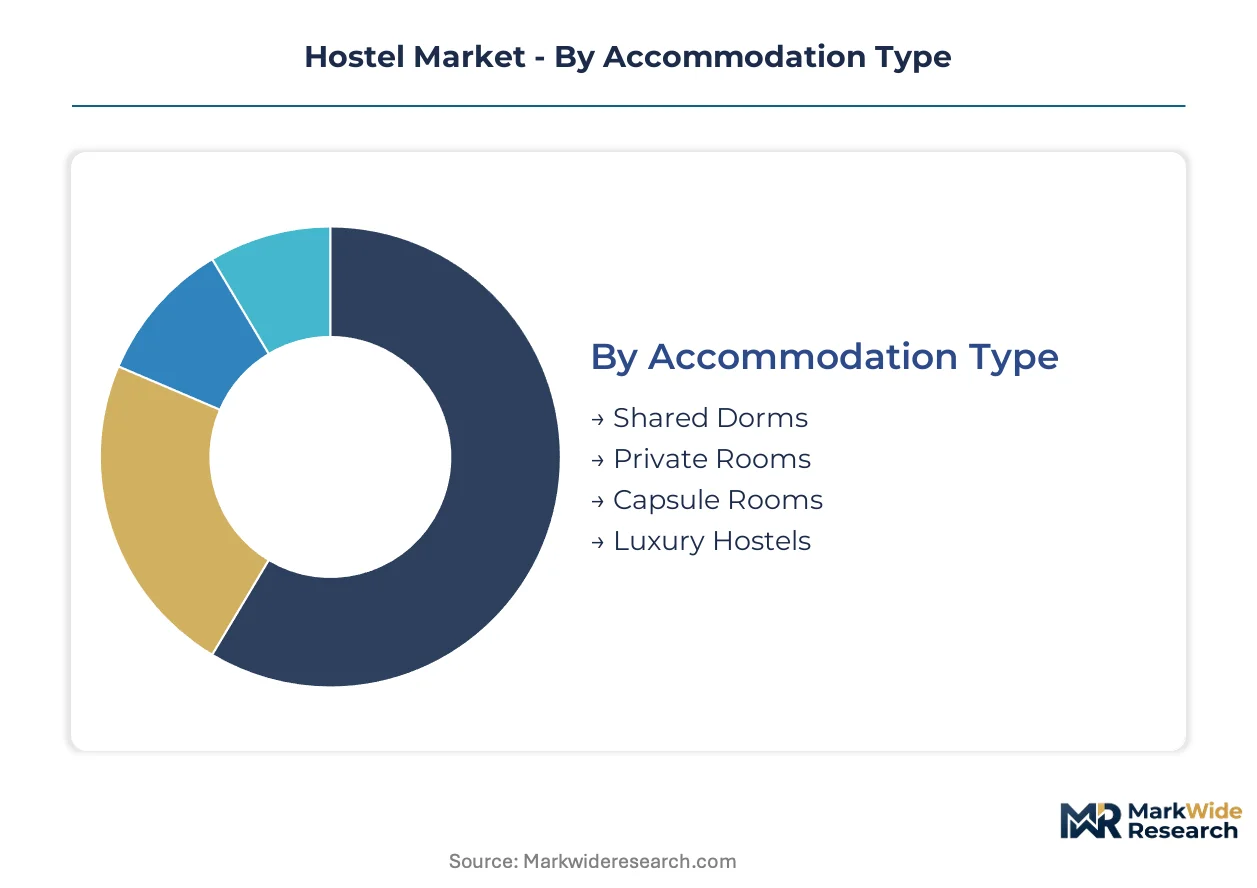
Hostel operators configure property portfolios across four distinct dimensions that determine capital intensity, labor models, and guest acquisition economics. Each segmentation axis carries divergent margin profiles and operational complexity thresholds that shape competitive positioning.
Accommodation Type:
Shared dorms anchor domestic demand in established European corridors, while private rooms and luxury tiers increasingly serve export-led bookings from North American and Asian source markets.
- Shared Dorms:Multi-bed configurations with bunk arrangements maximize bed density and turnover velocity. Demand concentrates in Southeast Asian urban corridors—Bangkok, Ho Chi Minh City, and Jakarta—where infrastructure investment outpaces supply growth and budget travelers extend average length of stay.
- Private Rooms:En-suite configurations with hostel social architecture command premium rates above dormitory tiers. European city-center properties in Lisbon and Berlin report disproportionate margin capture as remote workers blend privacy expectations with community access.
- Capsule Rooms:Pod-based sleeping modules with integrated ventilation and lighting systems optimize spatial efficiency in high-land-cost Japanese and South Korean markets.
- Luxury Hostels:Boutique design standards with hotel-grade amenities attract affluent experiential travelers in gateway cities.
Shared dorms commands the established base. The steepest expansion runs through private rooms.
Service Model:
Cost tier stratification separates capital-light remote operations from labor-intensive full-service formats, with implications for scalability and geographic reach.
- Self-Service:Automated check-in terminals and mobile key distribution compress staff-to-guest ratios below 1:25. German and Dutch mid-scale chains deploy these systems fastest, reducing labor cost exposure in high-wage markets.
- Full-Service:24-hour front desk, concierge programming, and curated social events elevate operational overhead. Demand concentrates in Latin American urban centers where labor cost differentials sustain service intensity without margin erosion.
- Part-Time Staff:Hybrid staffing models with daytime coverage and automated night access balance service presence with cost control.
- Remote Management:Centralized revenue management and virtual front-desk operations favor scaled operators with technology infrastructure over fragmented independents.
Full-service retains the volume anchor in emerging markets. Remote management is gaining share fastest in developed economies.
Target Demographic:
Application-driven segmentation distinguishes transient leisure demand from extended-stay professional segments with divergent amenity requirements and booking patterns.
- Digital Nomads:Month-long stays with co-working amenity bundles transform hostel economics through reduced guest acquisition costs. Lisbon, Mexico City, and Medellín properties report concentrations above 40% of bed-nights from this segment.
- Budget Travelers:Price-sensitive leisure demand with short booking windows and high platform dependency. Southeast Asian corridors in Vietnam, Thailand, and Indonesia drive fastest-expanding volume for this segment.
- Backpackers:Traditional multi-night dormitory stays with emphasis on social programming and communal spaces.
- Students:Seasonal demand clusters around academic calendars and gap-year travel patterns in European and Australian markets.
Budget travelers anchor current volume. Digital nomads are climbing the fastest as visa regimes expand.
Booking Channel:
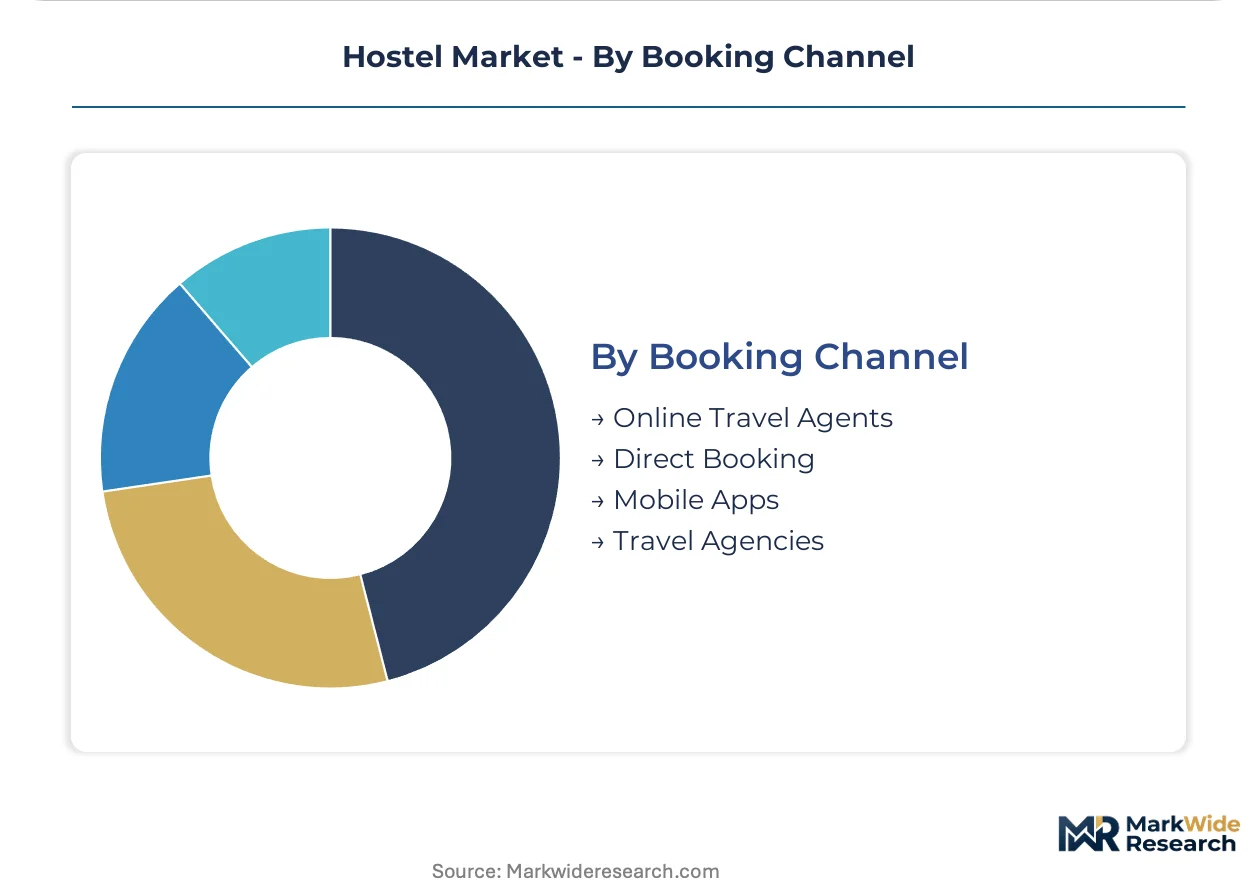
Customer-type differentiation separates platform-dependent transient bookers from direct-relationship extended-stay guests with implications for commission economics and data ownership.
- Direct Booking:Owned-platform reservations capture guest data and eliminate OTA commission burdens. GDPR compliance investments by CNIL-mandated French operators and parallel EU regulators elevate fixed technology costs for direct-channel infrastructure.
- Online Travel Agents:Aggregator platforms dominate transient leisure acquisition with 15-25% commission structures. Volume concentrates where hostel brand recognition remains underdeveloped.
- Mobile Apps:Native application bookings with push-notification engagement target younger demographic segments.
- Travel Agencies:B2B wholesale channels serve group bookings and institutional travel contracts in select markets.
Online travel agents retain the volume base. Direct booking is expanding most quickly as operators absorb compliance engineering costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Property development concentrates in Southeast Asian urban corridors where infrastructure investment outpaces lodging supply growth. Vietnam, Thailand, and Indonesia anchor new hostel construction pipelines as remote management platforms compress operational labor costs across these markets.
Vietnam
Ho Chi Minh City and Hanoi drive demand through domestic tourism expansion and inbound volume from regional source markets. The Ministry of Construction issues building efficiency guidelines that elevate capital requirements for new developments. Da Nang's coastal tourism corridor attracts boutique hostel investments targeting extended-stay digital nomads.
Thailand
Bangkok's urban tourism infrastructure supports high-turnover dormitory operations with bed densities exceeding regional averages. The Tourism Authority of Thailand coordinates with local fire safety regulators on occupancy density standards for historic district properties. Chiang Mai's co-working ecosystem anchors month-long stay concentrations above 30% of bed-nights.
Indonesia
Jakarta and Bali concentrate international booking volume while Yogyakarta exhibits supply gaps relative to inbound growth. The national investment coordinating board streamlines hospitality licensing for foreign-operated properties. Bandung's secondary city status attracts development capital seeking lower land costs than primary metros.
Germany
Berlin and Munich sustain hybrid hotel-hostel formats with standardized service levels in city-center locations. The EU Green Deal mandates energy retrofit timelines that accelerate modernization of older hostel stock. Hamburg's port tourism corridor supports design-led properties with curated social programming.
Portugal
Lisbon posts the steepest digital nomad segment growth among European capitals with month-long stay concentrations exceeding 40% of bed-nights. The national digital nomad visa program directly expands addressable demand for extended-stay bookings. Porto emerges as a secondary hub with lower operational costs and comparable co-working infrastructure density.
Hostel Market Competitive Environment
Concentration sits with scaled operators possessing centralized revenue management capabilities and technology infrastructure. Fragmented independent properties face displacement as remote management platforms elevate capital requirements beyond their reach. Three archetypes dominate: design-led lifestyle brands, hybrid hotel-hostel formats, and membership-based nonprofit networks. Competitive moves center on co-working amenity bundling and geographic expansion into secondary cities with supply gaps.
Within the design-led lifestyle tier, Generator Hostels exemplifies properties commanding premium rates through curated social programming in gateway cities. Selina Hostels anchors the integrated co-working segment with Latin American and European urban presence. Meininger Hotels occupies a position in the hybrid format space with standardized service levels dominating city-center locations. These three operators represent divergent strategic paths for capturing digital nomad and budget traveler segments.
| Leading Market Players |
|---|
| Selina Hostels |
| Meininger Hotels |
| Hostelling International (HI) |
| Wombat's Hostels |
| The Youth Hostels Association (YHA) |
| a&o Hotels and Hostels GmbH |
| St Christopher's Inns |
| Safestay Hotels & Hostels |
| Generator Hostels |
| Others |
Value Chain & Pricing Dynamics
Ninety-day property technology procurement cycles compress capital deployment timelines while amplifying pricing power for scaled operators with centralized purchasing leverage over fragmented independents. This lead-time compression rewards hostel chains that pre-negotiate bulk amenity contracts and lock in maintenance service rates across multi-property portfolios.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European hostel stock, separating energy-retrofitted properties with compliant building envelopes from legacy inventory facing accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels reflects amenity bundling intensity rather than bed configuration alone, with co-working access commanding rate premiums in Lisbon and Berlin. Cost compression in economy tiers intensifies because hotel chain downmarket entry erodes private-room rate floors. Budget travelers exhibit highest price sensitivity through platform-dependent booking behavior, while digital nomads accept elevated rates for month-long stay guarantees.
Supply Chain Analysis
Strategic stockpiling of smart access hardware and automated check-in terminals dominates procurement strategy as German and Dutch chains accelerate remote management deployment. Manufacturing concentrates in China, Vietnam, and Taiwan for IoT-enabled lock systems and mobile key infrastructure. Component dependencies include semiconductor chips for access control, cloud computing bandwidth for centralized platforms, and sustainable building materials for EU retrofit compliance. Single-source vulnerability concentrates in proprietary software licensing for revenue management algorithms. Distribution runs through hospitality technology integrators serving scaled operators with turnkey deployment packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Co-working amenity bundles represent the fastest-expanding recurring-revenue layer, outpacing bed-night economics as digital nomad visa proliferation extends average length of stay. This service-attach opportunity transforms capital-light hostel operations into hybrid hospitality-workspace assets with reduced guest acquisition costs.
For Market Incumbents: Secure centralized revenue management capabilities through proprietary algorithm development or exclusive vendor partnerships, defending against remote management platform displacement that favors scaled operators over fragmented independents. Consolidate position by acquiring secondary-city properties in Yogyakarta and Bandung where supply gaps persist relative to inbound tourism growth. For New Entrants and Emerging Players: GDPR compliance fast-track through pre-built consent architectures offers entry pathway into European direct-booking channels where legacy properties absorb elevated fixed technology costs. Target Indonesia's secondary cities with hybrid self-service models, penetrating Bandung's lower land-cost environment before primary metro saturation intensifies. Pursue digital nomad segment acquisition through co-working space partnerships rather than standalone property development. For Investors and Strategic Acquirers: Carve-out targets emerge from independent hostel networks lacking API-enabled property management systems, presenting technology-overlay acquisition opportunities. Long-term viability centers on operators with demonstrated month-long stay concentrations above thirty percent of bed-nights and established co-working infrastructure. Monitor digital nomad visa issuance volumes as inflection indicator for extended-stay demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Co-working Amenity Bundling | Transforms hostel economics through reduced guest acquisition costs in Lisbon and Mexico City corridors. |
| Remote Management Platform Deployment | Compresses staff-to-guest ratios below 1:20 while elevating capital requirements for scaled operators. |
| EU Green Deal Retrofit Compliance | Extends asset lifecycles for German and French properties facing mandated energy efficiency timelines. |
| Secondary City Geographic Expansion | Captures supply gaps in Yogyakarta and Bandung relative to regional tourism volume growth. |
| Direct Booking Platform Investment | Absorbs GDPR compliance engineering costs previously externalized to online travel agency channels. |
Study Parameters
The analysis maps accommodation type tiers, service model configurations, target demographic segments, and booking channel economics, each validated through property development executives, revenue management specialists, co-working space operators, and hospitality technology vendors. Primary fieldwork combined structured interviews with secondary validation against tourism authority statistics, building permit databases, digital nomad visa issuance records, and EU regulatory filings. Bottom-up property-level economics triangulated against top-down market sizing from lodging supply assessments and inbound tourism volume data.
Consistency checks validated volume and value outputs against external benchmarks including tourism infrastructure investment disclosures, hospitality employment statistics, and co-working space expansion announcements. Segmentation dimensions modeled encompass accommodation configuration, service intensity, guest demographic profile, and reservation channel preference alongside geographic regulatory cluster differentiation. CAGRs were derived from trend extrapolation anchored in visa policy trajectories and remote work adoption patterns. Forecast inputs incorporated property technology deployment rates and extended-stay booking concentration shifts.
Underlying assumptions cover digital nomad visa program continuity, EU retrofit timeline adherence, and Southeast Asian infrastructure investment pacing, with deviation risk concentrated in fire safety regulatory tightening and hotel chain downmarket acceleration. Revision becomes warranted when month-long stay concentrations cross threshold levels that trigger operational redesign requirements or when OTA commission structures shift materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Sweden Hospitality Market
Accommodation
Russia Online Accommodation Market
Accommodation
Capsule Hotels Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
In-Flight Catering Services Market
Accommodation
Casino Hotel Market
Accommodation
Austria Hospitality Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
Romania Hospitality Market
Accommodation
France Hospitality Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Croatia Hospitality Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
India Student Accommodation Market
Accommodation
UAE Hospitality Market