
 Germany Student Accommodation Market | 2026-2036
Germany Student Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Student Accommodation Market Analysis
Subscription-based amenity bundles is shifting how German student housing generates recurring revenue beyond base rent. GSA leverages its pan-European platform to standardize service tiers across multiple university cities. Smartments Student anchors its portfolio in purpose-built micro-apartments with integrated coworking lounges. Youniq differentiates through flexible lease terms that align with semester calendars rather than calendar-year contracts.
Germany student accommodation comprises purpose-built residential assets designed for enrolled learners, typically featuring furnished units, shared study facilities, and lease terms synchronized with academic semesters. These properties range from 12-square-meter single studios to 25-square-meter shared clusters, with energy performance certificates mandated for all new construction. Student halls and studio apartments lead the type segmentation, with studio units commanding premium rents due to privacy premiums. The facility-type split shows private providers capturing development momentum as universities divest direct ownership, while co-living spaces represent the fastest-growing category by bed count.
KfW promotional loans and Germany's Building Energy Act shape capital allocation toward low-carbon retrofits of existing stock. Municipal zoning in Berlin, Munich, and Hamburg restricts conversion of residential units to short-term lets, preserving student housing supply. Stakeholders must monitor how federal rent brake regulations interact with university expansion timelines in high-enrollment corridors.
Market Dynamics
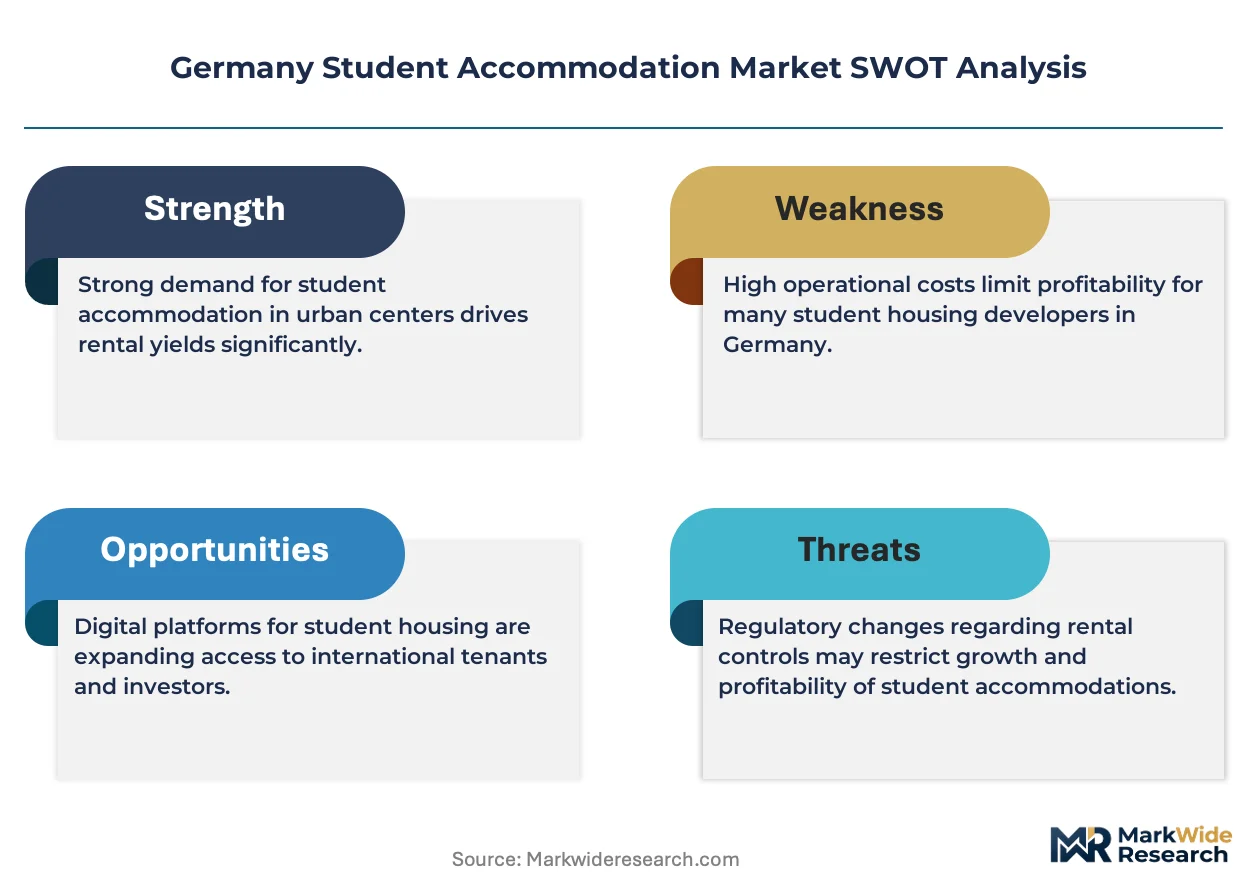
KfW promotional loans and Germany's Building Energy Act are redirecting capital flows toward low-carbon retrofits of existing student housing stock, while municipal zoning restrictions in enrollment hotspots preserve supply for long-term academic leases.
Growth Catalysts
- University enrollment expansion:Rising student numbers in Berlin, Munich, and Hamburg outpace available bed supply, creating sustained absorption pressure for new purpose-built developments.
- KfW funding programs:Subsidized financing for energy-efficient building retrofits lowers capital costs for developers upgrading aging student housing portfolios.
- International student mobility:Learners from India and China generate concentrated booking volumes during peak intake periods, stabilizing occupancy rates.
Market Restraints
- Construction cost inflation:Elevated steel and concrete input prices compress development margins on new-build student accommodation projects.
- Municipal zoning density caps:Berlin's strict height and floor-area-ratio limits restrict vertical expansion of student housing in core university corridors.
- Substitution from private flatshares:Informal shared apartments in peripheral districts compete on price with formal purpose-built stock.
Strategic Opportunities
- Co-living format expansion:Shared cluster configurations with integrated study lounges capture premium rents from postgraduate and international cohorts.
- Smart building technology convergence:IoT-enabled energy management systems paired with automated access control reduce operational overhead.
- Semester-aligned lease innovation:Flexible tenancies matching academic calendars rather than calendar-year contracts reduce void periods.
Industry Challenges
- Skilled trades shortage:Germany's constrained pipeline of certified HVAC and electrical technicians delays retrofit timelines on existing stock.
- Energy certificate compliance:Meeting Building Energy Act efficiency standards requires capital-intensive envelope upgrades on pre-2000 properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Student Accommodation Market |
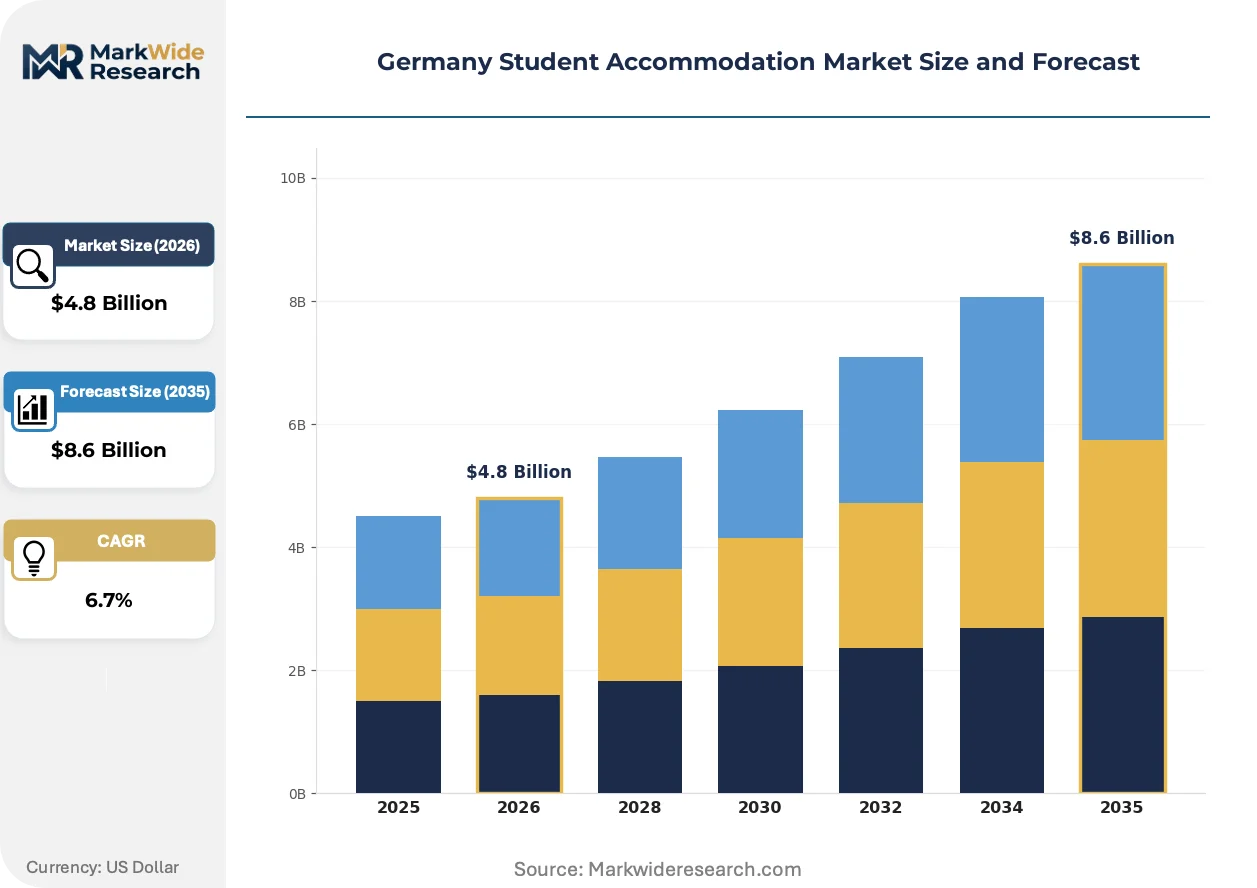
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Student Halls, Shared Apartments, Studio Apartments, Homestays Pricing Model: Fixed Rent, Flexible Rent, All-Inclusive, Tiered Pricing Facility Type: Private Providers, University-Owned, Managed Housing, Co-Living Spaces End User: Domestic Students, International Students, Exchange Students, Graduate Students |
| Companies Covered | GSA (Global Student Accommodation), Smartments Student, Uninest Student Residences, Aviva Investors, Staytoo, The FIZZ (International Campus), Youniq, Ardian, Basecamp Student, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Student Accommodation Market Emerging Trajectories
Digital amenity platforms and sustainability certification are reshaping competitive differentiation in German student housing, while procurement models shift toward subscription-based service bundles.
Smart building management systems are expanding into German student accommodation operations. These platforms integrate automated climate control, predictive maintenance alerts, and resident-facing mobile apps. Mid-scale operators in Hamburg and Frankfurt are piloting these tools to reduce on-site staffing ratios. The technology is expanding into lease pricing structures, with providers capturing efficiency gains through dynamic utility billing.
Germany's Building Energy Act mandates progressive efficiency standards for residential retrofit projects, including student housing stock. The regulation requires minimum thermal performance thresholds for facade and window replacements. Developers in Bavaria and Baden-Württemberg are accelerating envelope upgrade schedules to secure KfW promotional loan eligibility before stricter tiers activate.
Subscription amenity bundling is displacing à-la-carte service pricing in urban student housing markets. Operators package high-speed connectivity, gym access, and cleaning services into monthly fees above base rent. This model concentrates in Berlin and Munich where international students demonstrate willingness to pay for convenience aggregation.
Germany Student Accommodation Market Segmentation
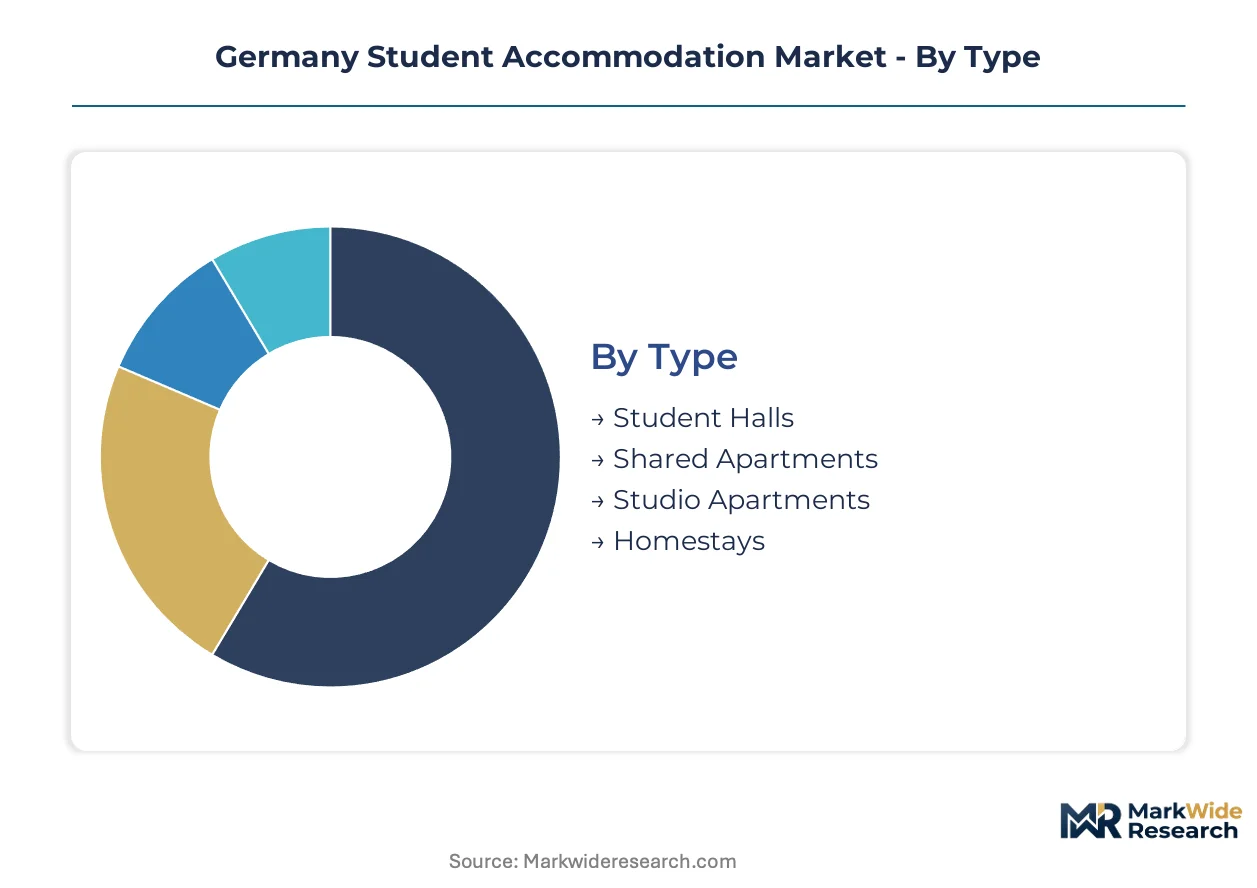
Germany's student accommodation market fragments across operational models, pricing structures, and user profiles. Each segment carries distinct capital intensity, occupancy patterns, and regulatory exposure that shape provider strategies.
Type:
Volume concentrates in shared configurations while privacy premiums drive studio economics.
- Student Halls:Purpose-built blocks with centralized amenities and shared kitchens dominate university-adjacent supply. Berlin and Munich operators stack these assets near U-Bahn corridors to capture enrollment expansion. KfW retrofit funding flows disproportionately toward this segment's aging stock.
- Studio Apartments:Self-contained units with private kitchenettes and bathrooms command rent premiums from international postgraduates. Munich's Technical University corridor shows concentrated absorption of this format. Privacy premiums offset higher per-square-meter construction costs.
- Shared Apartments:Multi-bedroom configurations with communal living spaces attract price-sensitive domestic undergraduates. Hamburg's Schanzenviertel district clusters informal supply competing with formal operators.
- Homestays:Private residence placements with local families serve short-term exchange cohorts. Smaller cities like Heidelberg and Freiburg maintain networked placement services for this segment.
Today's leader: Student Halls. Tomorrow's challenger: Studio Apartments.
Pricing Model:
Cost tier stratification separates budget-conscious domestic enrollment from convenience-seeking international demand.
- Fixed Rent:Standard calendar-year contracts with predetermined monthly payments dominate traditional student halls. Bavarian operators favor this structure for cash flow predictability amid construction cost inflation.
- All-Inclusive:Bundled utilities, internet, and amenity access into single monthly fees attract Indian and Chinese students unfamiliar with German utility billing. Berlin providers report 15-20% premiums over base rent for this convenience layer.
- Flexible Rent:Semester-aligned tenancies with prorated move-in/move-out dates reduce void periods. Youniq and similar operators deploy this structure to match academic calendars.
- Tiered Pricing:Three-level differentiation across premium, standard, and economy room grades segments demand by willingness-to-pay. Munich operators apply this most aggressively near elite universities.
Fixed Rent anchors current revenue. All-Inclusive models gain fastest among international cohorts.
Facility Type:
Ownership structure determines capital access, regulatory burden, and portfolio agility.
- Private Providers:Institutional investors and specialized REITs deploy development capital into purpose-built stock. GSA's pan-European platform exemplifies this segment's standardization capabilities across German university cities.
- Co-Living Spaces:Shared cluster configurations with integrated study lounges and event programming capture postgraduate demand. This format expands most quickly by bed count in Hamburg and Frankfurt.
- Managed Housing:Third-party operators lease university-owned assets under management contracts. This structure spreads in North Rhine-Westphalia where public universities retain ownership.
- University-Owned:Direct institutional provision declines as German universities divest operational housing assets to focus on academic missions. Remaining stock concentrates in smaller East German cities.
Private Providers control development momentum. Co-Living Spaces climb fastest in premium urban corridors.
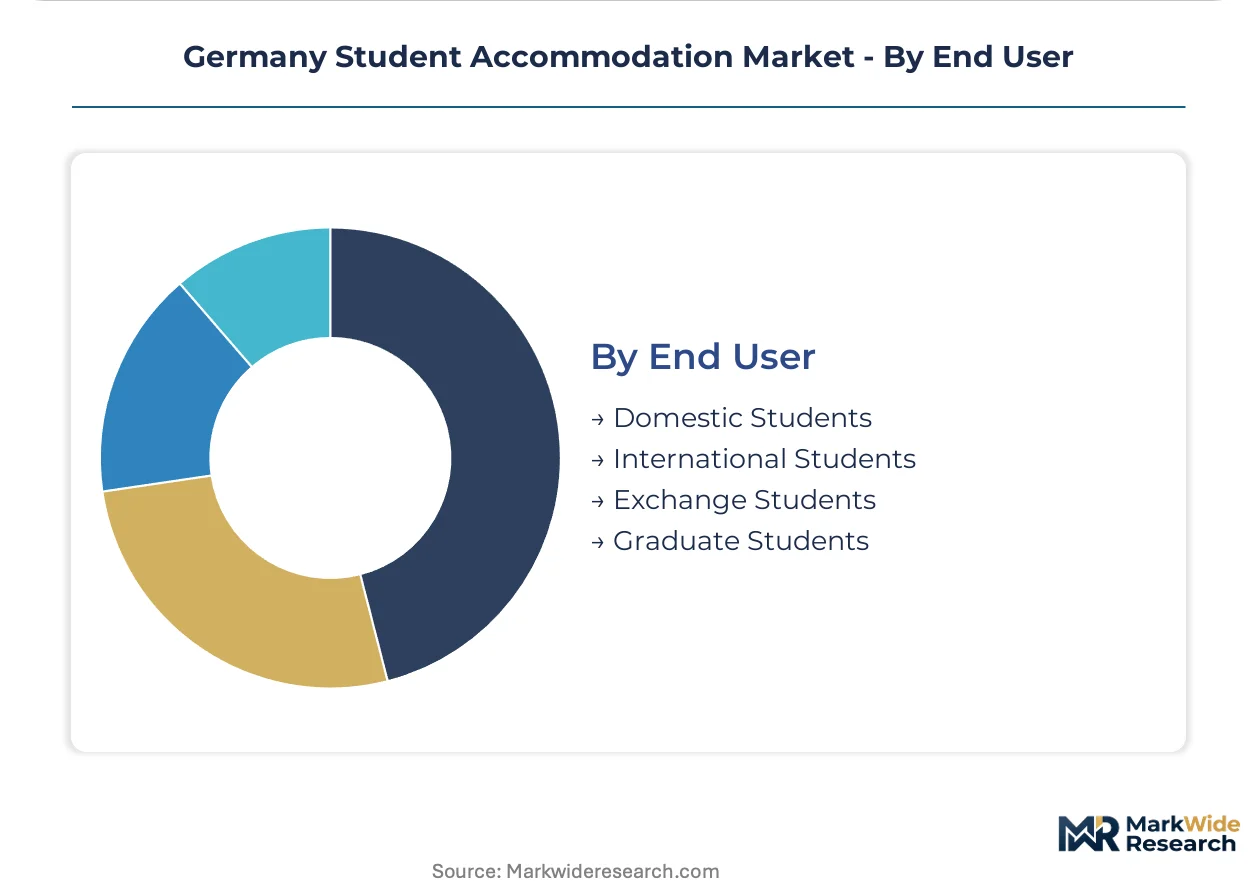
End User:
Customer type segmentation aligns lease structures, amenity bundles, and marketing channels with enrollment patterns.
- International Students:Indian and Chinese learners generate peak booking volumes during September and March intake windows. This cohort drives all-inclusive pricing adoption and English-language service platforms.
- Domestic Students:German nationals with established local networks favor shared apartments and price-sensitive configurations. This segment shows higher price elasticity and longer decision timelines.
- Graduate Students:Master's and doctoral candidates prioritize studio privacy and proximity to research facilities. Munich and Berlin technical universities concentrate this demand.
- Exchange Students:Short-term semester visitors from partner universities fill transitional capacity in managed housing. Peak demand aligns with bilateral agreement cycles.
International Students stabilize occupancy. Graduate Students expand fastest as postgraduate enrollment rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in purpose-built student bed delivery, while both markets grapple with municipal zoning constraints that limit vertical expansion near university clusters.
Bavaria
Technical University Munich and Ludwig Maximilian University drive concentrated demand for studio configurations in the state capital. KfW promotional loans accelerate envelope retrofits of aging student halls in Ingolstadt and Regensburg. Developers concentrate new supply along U-Bahn corridors in Munich's Maxvorstadt district, where land scarcity pushes construction toward micro-apartment formats.
North Rhine-Westphalia
Ruhr University Bochum and University of Cologne generate steady absorption for shared cluster housing among domestic undergraduates. The state's municipal housing associations retain ownership of substantial student housing stock, contracting third-party operators under management agreements. Aachen's proximity to RWTH Aachen University sustains developer interest despite strict heritage preservation codes limiting facade modifications.
Baden-Württemberg
Karlsruhe Institute of Technology and University of Stuttgart anchor demand for graduate-focused studio supply with integrated coworking amenities. The state's Building Energy Act compliance timeline pressures pre-2000 stock owners to accelerate thermal upgrades before stricter efficiency tiers activate. Heidelberg maintains networked homestay placement services for short-term exchange cohorts from partner universities.
Berlin-Brandenburg
Humboldt University and Free University Berlin enrollment expansion outpaces bed supply in the capital's core districts. Federal rent brake regulations interact with university expansion timelines, constraining rent growth on regulated units while exempt new-build stock captures market rates. Potsdam's film school and University of Potsdam cluster generates secondary demand in Brandenburg's capital.
Hamburg
University of Hamburg and HafenCity University Hamburg concentrate demand in the Schanzenviertel and Altona districts. Municipal zoning restricts conversion of residential units to short-term lets, preserving supply for long-term academic leases. Co-living operators pilot shared cluster configurations with integrated study lounges in the HafenCity redevelopment zone.
Germany Student Accommodation Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional investors controlling development momentum while specialized operators capture operational premiums. The market structure consolidates around pan-European platforms with standardized service tiers, mid-scale regional specialists with flexible lease innovations, and university-affiliated managers with captive demand pipelines. Dominant competitive moves include portfolio diversification across multiple German university cities and strategic partnerships with municipal housing associations for management contracts.
Among pan-European platforms, GSA exemplifies the standardized service tier archetype across multiple university cities, while Smartments Student anchors the purpose-built micro-apartment format with integrated amenities. Youniq occupies a position within the flexible lease innovation segment, aligning tenancy structures with academic calendars rather than calendar-year contracts.
| Leading Market Players |
|---|
| GSA (Global Student Accommodation) |
| Smartments Student |
| Uninest Student Residences |
| Aviva Investors |
| Staytoo |
| The FIZZ (International Campus) |
| Youniq |
| Ardian |
| Basecamp Student |
| Others |
Supply Flow & Price Mechanics
International student cohorts from India and China drive absorption of all-inclusive pricing bundles that wrap utilities, connectivity, and amenity access into single monthly fees, forcing operators to restructure procurement around subscription-service aggregators and compress base rent competitiveness in Berlin and Munich corridors.
Pricing Analysis
Capacity additions in Hamburg and Frankfurt are reshaping price floors for shared cluster configurations as co-living operators expand bed counts. Three-tier pricing structure across premium, standard, and economy levels segments demand by privacy preference and proximity to university cores. Pricing pressure stems from informal flatshare competition in peripheral districts, with domestic undergraduates showing highest price elasticity while international postgraduates absorb privacy premiums.
Supply Chain Analysis
Construction input supply rests on German steel and concrete producers, Polish timber framers, and Chinese-manufactured smart building components. Energy-efficient glazing, HVAC systems, and IoT access control hardware feed from specialized industrial clusters. Single-source vulnerability concentrates in semiconductor-dependent smart building systems. Distribution runs through general contractors with university-housing specialization, then direct to developer-operators or municipal housing associations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's student accommodation market functions as a geographic-arbitrage play between KfW-subsidized retrofit economics in Bavaria and Baden-Württemberg versus unregulated new-build rent capture in Berlin-Brandenburg's exempt stock.
For Market Incumbents: Cement portfolio resilience through accelerated envelope retrofits securing KfW promotional loan eligibility before stricter Building Energy Act tiers activate. Deepen backward integration into smart building technology procurement to offset skilled trades shortages delaying HVAC and electrical upgrade timelines.
For New Entrants and Emerging Players: Begin with semester-aligned lease structures in North Rhine-Westphalia's managed housing segment, where municipal housing associations contract third-party operators under asset-light management agreements. Target Aachen and Bochum corridors where heritage preservation codes limit incumbent expansion flexibility.
For Investors and Strategic Acquirers: Asymmetric upside sits with pan-European platforms possessing standardized service tier capabilities across multiple German university cities. Long-term viability hinges on regulatory rent brake exemption eligibility for new-build stock. Watch federal Building Energy Act tier activation schedules as inflection indicator for retrofit capital deployment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| KfW Retrofit Acceleration | Secures subsidized financing for thermal envelope upgrades ahead of stricter efficiency mandates. |
| Smart Building Technology Integration | Reduces on-site staffing ratios through IoT-enabled climate control and predictive maintenance systems. |
| Semester-Aligned Lease Innovation | Matches tenancy structures to academic calendars, reducing void periods between enrollment cycles. |
| Co-Living Format Expansion | Captures premium rents from postgraduate and international cohorts in Hamburg and Frankfurt corridors. |
| Municipal Housing Association Partnership | Unlocks management contracts for university-adjacent stock in North Rhine-Westphalia's public ownership clusters. |
Methodological Framework
Multiple input streams — structured interviews with student housing operators, asset managers at institutional investors, municipal housing association procurement officers, and university international office administrators — were reconciled against KfW funding program disclosures, municipal zoning records, federal rent brake regulatory filings, and university enrollment statistics. Bottom-up bed-count modeling across operator portfolios triangulated with top-down construction permit analysis.
Historical absorption patterns were cross-referenced against panel input from development executives to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include facility type, pricing model, end-user nationality, and regional regulatory framework. CAGRs were derived from enrollment expansion trajectories, KfW funding allocation trends, and construction cost inflation curves specific to residential retrofit activity.
Caveats apply where federal rent brake expansion, Building Energy Act tier acceleration, or international student visa policy shifts could materially shift the outlook. Forecasts reflect modeling assumptions around enrollment growth, construction cost stabilization, and KfW program continuity. A small set of named triggers — skilled trades availability, steel price volatility, and municipal zoning liberalization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
UK Student Accommodation Market
Accommodation
Canada Hospitality Market
Accommodation
Japan Online Accommodation Market
Accommodation
UAE Hospitality Market
Accommodation
Romania Hospitality Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Hotel Market
Accommodation
In-Flight Catering Services Market
Accommodation
Russia Online Accommodation Market
Accommodation
Europe Student Accommodation Market
Accommodation
United States Online Accommodation Market
Accommodation
France Online Accommodation Market
Accommodation
Switzerland Hospitality Market
Accommodation
United Kingdom Hospitality Market