
 Online Travel Agencies Market | 2026-2036
Online Travel Agencies Market Size, Share, and Industry Trends Forecast 2026-2036
Online Travel Agencies Market Outlook
GDPR is broadening the cost-of-entry calculus for new platforms seeking European customer bases. Booking Holdings leverages proprietary supply contracts to sustain rate parity advantages across multiple continents. Expedia Group anchors its position through technology leadership in corporate travel management systems. Trip.com Group dominates outbound Chinese tourism through integrated destination services and visa-processing capabilities.
An online travel agency constitutes a digital intermediary platform that aggregates inventory from airlines, hotels, car rental fleets, and tour operators, then distributes confirmed bookings through algorithmic search-and-rank interfaces with dynamic pricing engines. Its primary commercial purpose is reducing search friction and transaction costs between fragmented travel suppliers and dispersed consumers. Flight booking and hotel reservation segments command the largest revenue pools, though vacation packages capture expanding margin as bundling complexity creates pricing opacity. Mobile apps represent the fastest-growing distribution channel, displacing desktop websites as the default booking interface across all customer types.
The EU AI Act will soon classify automated recommendation engines used by booking platforms as high-risk systems, mandating transparency in personalized pricing. The US FTC scrutinizes drip pricing and hidden fee disclosures across OTA checkout flows, pressuring revenue model redesign. India's Digital Personal Data Protection Act imposes consent-layer requirements that complicate retargeting campaigns. Stakeholders must monitor which regulatory jurisdiction achieves extraterritorial enforcement primacy first.
Market Dynamics
Mobile-first booking interfaces are compressing customer acquisition costs while fragmenting loyalty across multiple platforms simultaneously.
Growth Catalysts
- GDPR compliance architecture:European data-localization mandates force platform investments in regional server infrastructure, creating defensible moats for incumbents with capital reserves.
- Visa-processing integration:Outbound tourism corridors from China require embedded consular services, pulling platform development toward destination-service bundling.
- Algorithmic dynamic pricing:Machine learning engines now adjust fares in sub-second intervals, capturing revenue leakage that static pricing models previously surrendered.
Market Restraints
- Rate parity enforcement:Contractual clauses with hotel chains prevent undercutting direct-booking channels, capping margin expansion for intermediary platforms.
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominate hosting for major OTAs, creating single-point vulnerability in data-center regions.
- Payment processor fees:Cross-border transaction costs consume 2-4 percent of booking value, compressing net revenue per transaction in emerging markets.
Strategic Opportunities
- Corporate travel management systems:Unbundled expense-reporting integrations create stickiness among SME procurement departments seeking consolidated billing.
- India's Digital Personal Data Protection Act:Consent-layer requirements favor platforms with pre-built privacy infrastructure, disadvantaging late entrants.
- Voice-activated booking interfaces:Smart speaker penetration in US and UK households opens channel diversification beyond screen-based search.
Industry Challenges
- Machine-learning engineer scarcity:Recommendation algorithm development requires specialized talent pools concentrated in San Francisco, London, and Singapore.
- Legacy property management system integration:Mid-tier hotel chains operate on decades-old software architectures that resist real-time inventory API connections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Travel Agencies Market |
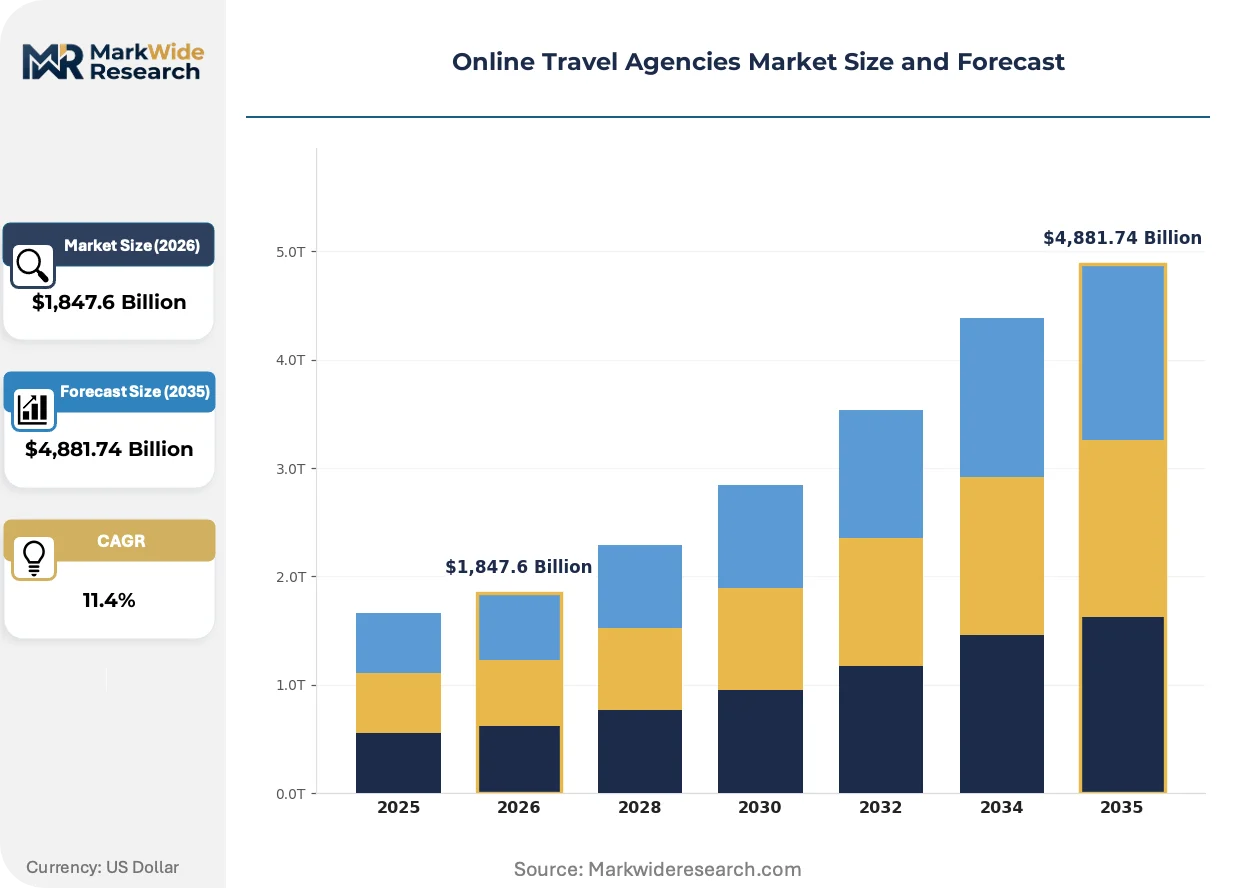
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $4,881.74 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Flight Booking, Hotel Reservation, Car Rental, Vacation Packages Customer Type: Leisure Travelers, Business Travelers, Family Groups, Solo Travelers Distribution Channel: Mobile Apps, Websites, Affiliate Sites, Social Media Price Tier: Budget, Mid-Range, Luxury, Discounted |
| Companies Covered | Airbnb, Tripadvisor, Booking Holdings, Tongcheng Travel, eDreams ODIGEO, Expedia Group, MakeMyTrip, Despegar, Trip.com Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Travel Agencies Market Strategic Shifts
Platform architecture is pivoting toward embedded finance and generative search interfaces that collapse the traditional discovery-to-booking funnel into single-session transactions.
Generative AI is modularizing the trip-planning workflow. Large language models now synthesize multi-destination itineraries from natural-language prompts, bypassing traditional search-filter interfaces. Leisure travelers under 35 are adopting these tools fastest, with adoption curves compressing from years to quarters. This technology is modularizing the role of human travel agents into exception-handling rather than search curation.
The EU AI Act will classify automated pricing engines as high-risk systems requiring algorithmic transparency disclosures. Industrial consequence includes mandatory documentation of training data provenance and decision logic for personalized fare quotes. European OTA technical teams are responding by building audit-trail infrastructure that logs every price-adjustment variable in real time.
Subscription-based loyalty programs are displacing points-based accrual systems as the primary retention mechanism. Frequent travelers now pay upfront for guaranteed discounts and perks rather than accumulating redeemable balances. This shift is most visible in US and UK markets where airline co-branded credit cards previously dominated travel rewards psychology.
Online Travel Agencies Market Segmentation
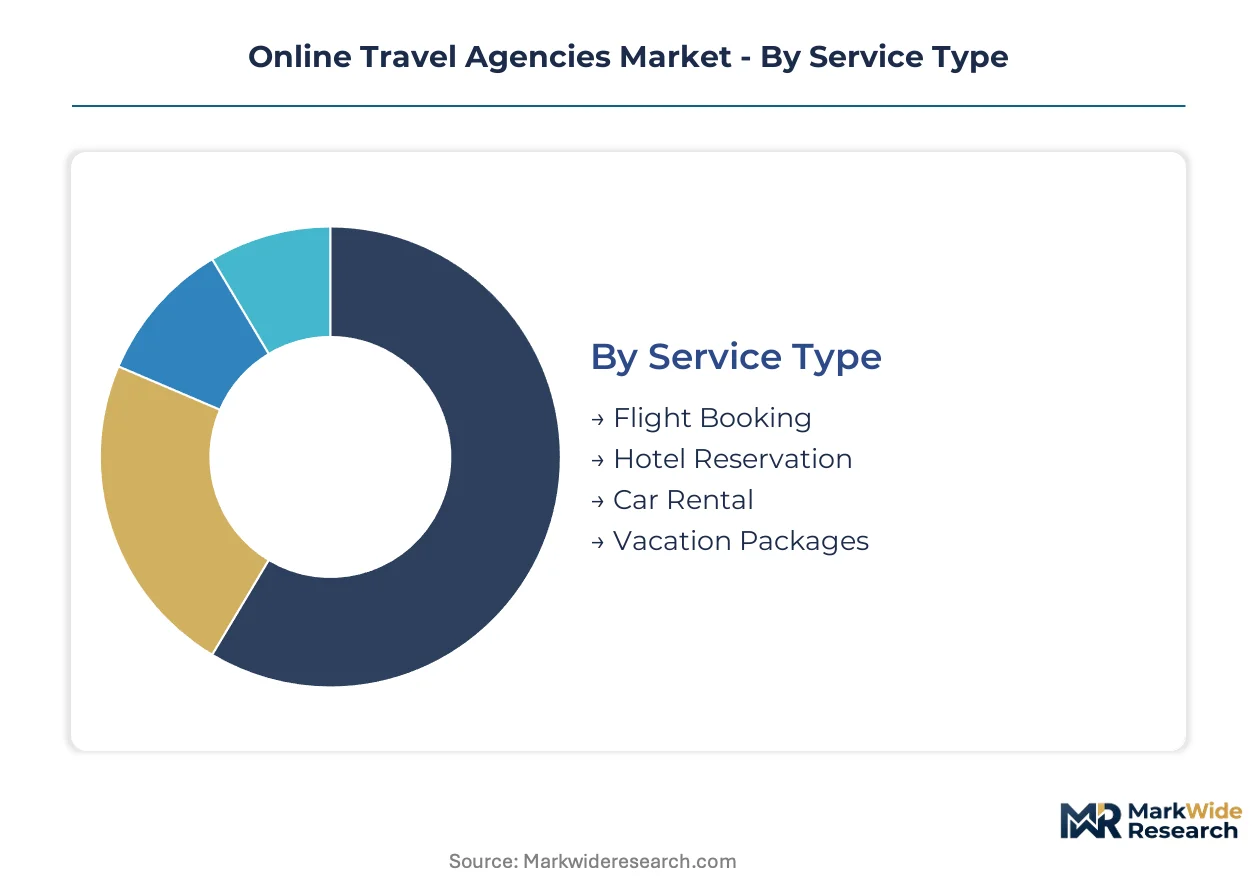
Segmentation in the Online Travel Agencies Market reveals distinct profit pools and acquisition strategies. Flight and hotel bookings generate recurring transaction density, while emerging channels like mobile apps reshape customer lifetime value calculations. Understanding these splits enables targeted technology investment and partnership prioritization.
Service Type:
Volume concentrates in high-frequency, low-margin transactions while premium bundles capture disproportionate profit contribution.
- Flight Booking:Airline inventory aggregation through global distribution systems dominates transaction counts. Corporate travel corridors between London, New York, and Singapore sustain the highest booking velocity, though metasearch engines compress commission rates on domestic routes.
- Hotel Reservation:Property-level contracting creates rate parity enforcement challenges across direct-booking channels. Resort destinations in Thailand and Mexico generate the strongest margin per room-night through package bundling and cancellation penalty structures.
- Car Rental:Fleet utilization algorithms optimize pickup location profitability at airports versus city centers. Integration with ride-hailing APIs in Dubai and São Paulo displaces traditional rental demand for short urban trips.
- Vacation Packages:Dynamic bundling of flights, hotels, and experiences creates pricing opacity that protects margin. Multi-destination European itineraries show the steepest expansion trajectory as travelers seek consolidated itinerary management.
Today's leader: Flight Booking. Tomorrow's challenger: Vacation Packages.
Customer Type:
Application context determines platform stickiness and payment method preferences across booking interfaces.
- Leisure Travelers:Price-sensitive demand concentrates in mobile app sessions with high abandonment rates at checkout. European GDPR consent flows and India's Digital Personal Data Protection Act compliance requirements lengthen booking funnels for this segment.
- Business Travelers:Expense management system integration creates switching costs through corporate policy enforcement. SME procurement departments in Germany and Japan prioritize consolidated billing over lowest-fare search.
- Family Groups:Multi-passenger booking complexity favors platforms with seat-selection and meal-preference workflows. Long-haul routes to Orlando and Bali show highest concentration for this segment.
- Solo Travelers:Flexible date search and single-supplement waivers drive platform selection. Hostel inventory aggregation in Lisbon and Barcelona captures this demand most effectively.
Leisure Travelers currently anchor volume. Business Travelers command the strongest retention economics.
Distribution Channel:
Channel economics diverge sharply between owned-platform conversion and third-party acquisition costs.
- Mobile Apps:Push notification re-engagement reduces customer acquisition expense versus paid search. Biometric payment authentication in South Korea and India accelerates one-tap booking completion rates.
- Websites:Desktop sessions retain higher average booking values for complex multi-city itineraries. Corporate travel management system portals route through browser-based interfaces for policy compliance auditing.
- Affiliate Sites:Metasearch engines extract referral fees without inventory risk, compressing OTA margins on price-transparent routes. Google Flights and Skyscanner dominate this layer in North American and European markets.
- Social Media:Influencer-driven destination discovery converts through embedded booking widgets. TikTok Shop travel partnerships in Southeast Asia demonstrate emerging commerce integration.
Mobile Apps own the growth curve. Social Media represents the experimental frontier.
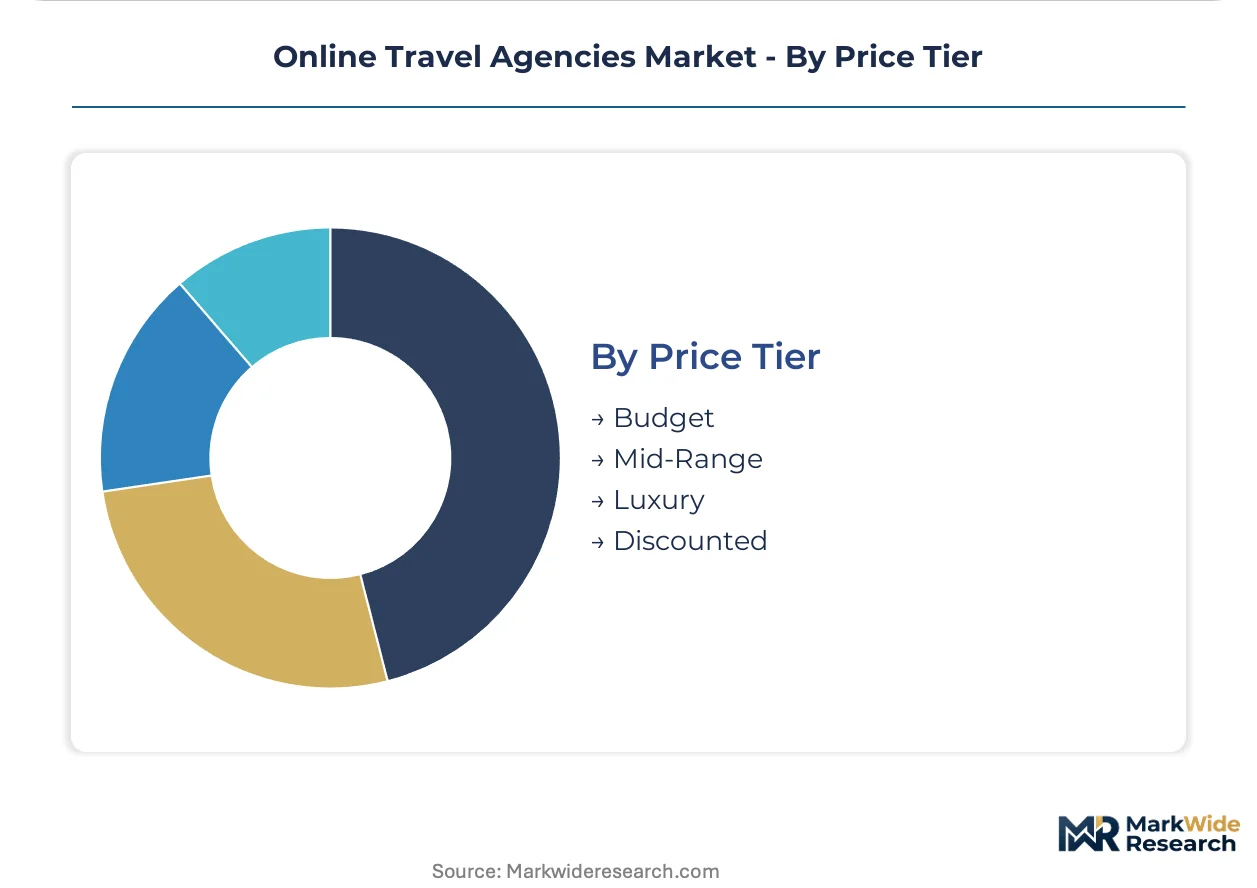
Price Tier:
Margin structure inverts across tiers as service intensity and cancellation flexibility vary.
- Budget:Ultra-low-cost carrier inventory and hostel aggregation target price-maximizing search behavior. Ancillary fee disclosure requirements under US FTC scrutiny complicate headline fare presentation.
- Mid-Range:Full-service airline economy and three-star hotel contracts balance volume and commission sustainability. This tier captures the largest absolute booking count across Chinese domestic tourism.
- Luxury:Suite inventory and business-class cabins generate commission rates multiples above economy. Concierge service attachment in Maldives and French Polynesia extends revenue per trip.
- Discounted:Flash sale and opaque inventory (hidden hotel name until booking) clears distressed supply. Last-minute mobile bookings in metropolitan corridors show highest conversion for this tier.
Mid-Range sustains platform economics. Luxury delivers the strongest profit per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent for algorithmic pricing and mobile platform development clusters in San Francisco, London, and Singapore, anchoring innovation capacity for the sector.
United States
Leisure travel demand concentrates in sunbelt retirement corridors and coastal metropolitan business centers. The FTC enforces drip-pricing disclosure standards that reshape checkout flow design. Seattle hosts cloud infrastructure operations that underpin real-time inventory systems for major platforms.
China
Outbound tourism recovery and domestic short-haul mobility drive platform transaction velocity. The national data-localization framework mandates in-country server architecture for consumer information. Shanghai and Beijing anchor headquarters operations for integrated destination-service providers.
Germany
Corporate travel procurement through SME expense management systems sustains B2B booking volumes. GDPR and the EU AI Act impose algorithmic transparency requirements on dynamic pricing engines. Berlin clusters startup development for voice-activated booking interfaces.
India
Mobile-first leisure adoption and domestic aviation expansion create addressable user bases in tier-two cities. The Digital Personal Data Protection Act mandates consent-layer architecture for retargeting campaigns. Bangalore concentrates engineering operations for biometric payment authentication systems.
United Kingdom
Subscription-based loyalty program adoption and smart speaker penetration reshape customer retention economics. The Competition and Markets Authority scrutinizes rate parity clauses in hotel supply contracts. London anchors fintech partnerships for embedded travel insurance and payment processing.
Online Travel Agencies Market Competitive Environment
The competitive structure tilts toward integrated platform conglomerates with multi-brand portfolios spanning leisure and corporate segments. Three archetypes dominate: global inventory aggregators with proprietary supply contracts, regional specialists with embedded visa and destination services, and mobile-native challengers with social commerce integration. Consolidation through strategic acquisitions and technology licensing partnerships constitute the primary competitive moves, with incumbents acquiring niche booking engines to fill portfolio gaps.
Among China-based integrated platforms, Trip.com Group and Tongcheng Travel exemplify the regional specialist archetype with embedded consular and destination-service capabilities. Booking Holdings and Expedia Group occupy positions within the global aggregator tier, leveraging multi-brand structures across price segments. These entities represent the dominant competitive anchors against which specialized challengers define market entry strategies.
| Leading Market Players |
|---|
| Airbnb |
| Tripadvisor |
| Booking Holdings |
| Tongcheng Travel |
| eDreams ODIGEO |
| Expedia Group |
| MakeMyTrip |
| Despegar |
| Trip.com Group |
| Others |
Value Chain & Pricing Dynamics
Luxury-to-budget service divergence compresses margin structures at the economy tier while inflating commission capture at the premium end, with inventory aggregation costs and cloud infrastructure fees reshaping both pricing floors and supplier contract terms across the Online Travel Agencies Market.
Pricing Analysis
Bundled vacation packages versus unbundled flight-only bookings create the central pricing architecture. Three-tier pricing structure across premium, standard, and economy levels captures divergent willingness-to-pay, with dynamic pricing engines adjusting fares in sub-second intervals. Cost compression in the budget tier intensifies because metasearch transparency eliminates pricing opacity, while luxury travelers show the least price sensitivity due to concierge service attachment.
Supply Chain Analysis
Regional distribution centers in Ireland, Singapore, and Virginia anchor the hub-and-spoke warehouse layer for server infrastructure and data localization compliance. Platform operations draw from airline global distribution systems, property management system APIs, and payment processor networks. Single-source vulnerability concentrates in AWS, Azure, and Google Cloud hosting clusters. Distribution runs through mobile app stores, corporate travel portals, and metasearch referral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the Online Travel Agencies Market rests on algorithmic pricing sophistication and subscription loyalty program adoption, with cloud infrastructure consolidation and payment processor fee compression offering parallel cost-down pathways.
For Market Incumbents: Hedge against rate parity erosion by deepening proprietary supply contracts with resort chains in Thailand and Mexico. Invest in visa-processing integration capabilities for outbound Chinese tourism corridors. Machine-learning engineer scarcity in San Francisco and London threatens algorithmic pricing leadership. For New Entrants and Emerging Players: Voice-activated booking interfaces offer a technology-first wedge into smart speaker-enabled households in the US and UK. Target SME corporate travel management systems in Germany and Japan where expense-reporting integration creates switching costs. Pursue embedded finance partnerships for travel insurance bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where mobile-native challengers with social commerce integration lack scale to compete against multi-brand conglomerates. Five-to-ten-year viability favors platforms with regional data-localization infrastructure and biometric payment authentication capabilities. Monitor India's Digital Personal Data Protection Act enforcement as an inflection indicator for retargeting campaign economics.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Trip Planning Integration | Large language models collapse discovery-to-booking funnels into single-session transactions for leisure travelers under 35. |
| Biometric Payment Authentication Rollout | Fingerprint and facial recognition in South Korea and India accelerates one-tap mobile booking completion rates. |
| Subscription Loyalty Program Launch | Upfront fee structures displace points-based accrual in US and UK markets where airline co-branded cards dominated. |
| Regional Data Center Expansion | GDPR and China's data-localization mandates force in-country server investments that create capital moats. |
| Embedded Travel Insurance Partnership | Fintech integration in London extends revenue per trip through real-time policy issuance at checkout. |
Study Parameters
Direct dialogue with platform engineering directors, airline revenue management executives, hotel chain distribution heads, and corporate travel procurement officers grounded the qualitative foundation. Secondary validation drew from SEC 10-K filings, EU AI Act regulatory texts, airline GDS performance disclosures, and mobile app store analytics. Bottom-up transaction modeling and top-down market sizing triangulated volume estimates.
Segment-level outputs across the analysis window reflect service type, customer archetype, distribution channel, and price tier dimensions. CAGRs emerged from regression against mobile adoption curves, outbound tourism recovery patterns, and cloud infrastructure capex cycles. Visa-processing integration penetration and voice-activated search adoption served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement and continued mobile-first booking migration; deviation in extraterritorial data protection rulings or cloud provider market concentration would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market