
 Asia-Pacific Travel Accommodation Market | 2026-2036
Asia-Pacific Travel Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Travel Accommodation Market Insights
REACH is restructuring compliance costs for European-headquartered chains with Asia-Pacific portfolios, forcing property-level chemical management and supplier due diligence that smaller local operators rarely match. Marriott International leverages its proprietary loyalty platform to sustain direct booking share against online travel agency commissions. Jin Jiang International Holdings anchors its competitive position through state-backed access to prime Chinese real estate and domestic tourism policy alignment. OYO Rooms competes on asset-light franchise density across India's tier-two and tier-three urban corridors.
Asia-Pacific travel accommodation encompasses commercial lodging facilities providing temporary overnight stays, typically incorporating guest room inventory management systems, housekeeping protocols, and ancillary food-and-beverage or conference infrastructure designed to serve transient populations. Properties range from full-service establishments with integrated spas and event spaces to limited-service formats optimized for cost-efficient turnover and standardized cleanliness benchmarks. Hotels dominate current revenue across the region, though vacation rentals capture disproportionate growth in coastal leisure corridors where platform-enabled inventory unlocks underutilized residential supply. Luxury and boutique segments concentrate margin pools in gateway cities, while budget and mid-range categories absorb volume from price-sensitive domestic tourists and young solo travelers.
Japan's METI enforces hotel building standards and energy efficiency codes that shape renovation cycles in Tokyo, Osaka, and Fukuoka. China's SAMR monitors platform pricing transparency and anti-competitive clauses between online travel agencies and accommodation providers. Australia's TGA does not regulate accommodations directly, but state-level consumer protection frameworks govern cancellation terms and refund obligations. Stakeholders must weigh regulatory fragmentation against the scale advantages of unified technology stacks and brand standards spanning multiple national jurisdictions.
Market Dynamics
Chinese domestic tourism policy alignment and EU Green Deal extraterritorial disclosure mandates are forcing property-level capital deployment across multinational portfolios. Regional operators must now balance state-backed real estate access against carbon intensity retrofitting timelines.
Growth Catalysts
- Regional Revitalization Campaigns:Japan's METI-backed secondary city development redirects inbound and domestic demand toward lower-density destinations beyond Tokyo and Osaka.
- Middle-Class Mobility Expansion:Rising discretionary spending among Chinese households generates sustained booking volume across mid-range and budget property tiers.
- Platform-Enabled Inventory:Vacation rental platforms unlock underutilized residential supply in coastal leisure corridors, capturing disproportionate growth relative to traditional hotel stock.
Market Restraints
- REACH Compliance Burden:European-headquartered chains face property-level chemical management costs that asset-light local operators rarely match.
- Energy Efficiency Retrofit Requirements:Japan's METI building codes mandate renovation cycles that compress free cash flow for aging urban properties.
- Platform Pricing Transparency Mandates:China's SAMR monitoring of online travel agency clauses limits rate parity enforcement and direct booking incentives.
Strategic Opportunities
- Tier-Two Urban Corridors:India's tier-two and tier-three cities present franchise density expansion potential with limited incumbent competition.
- Loyalty Platform Convergence:Integration of proprietary booking engines with ancillary travel services captures direct channel share against commission-based intermediaries.
- Dual Carbon Goal Alignment:China's MEE disclosure frameworks reward early retrofitting with preferential financing access for compliant properties.
Industry Challenges
- Fragmented Regulatory Jurisdiction:Stakeholders must maintain separate compliance protocols across Australia's state-level consumer protection frameworks, Japan's METI codes, and China's SAMR pricing rules.
- Legacy Property Management System Integration:Unified technology stack deployment across multi-jurisdictional portfolios encounters interoperability friction with established housekeeping and inventory protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Travel Accommodation Market |
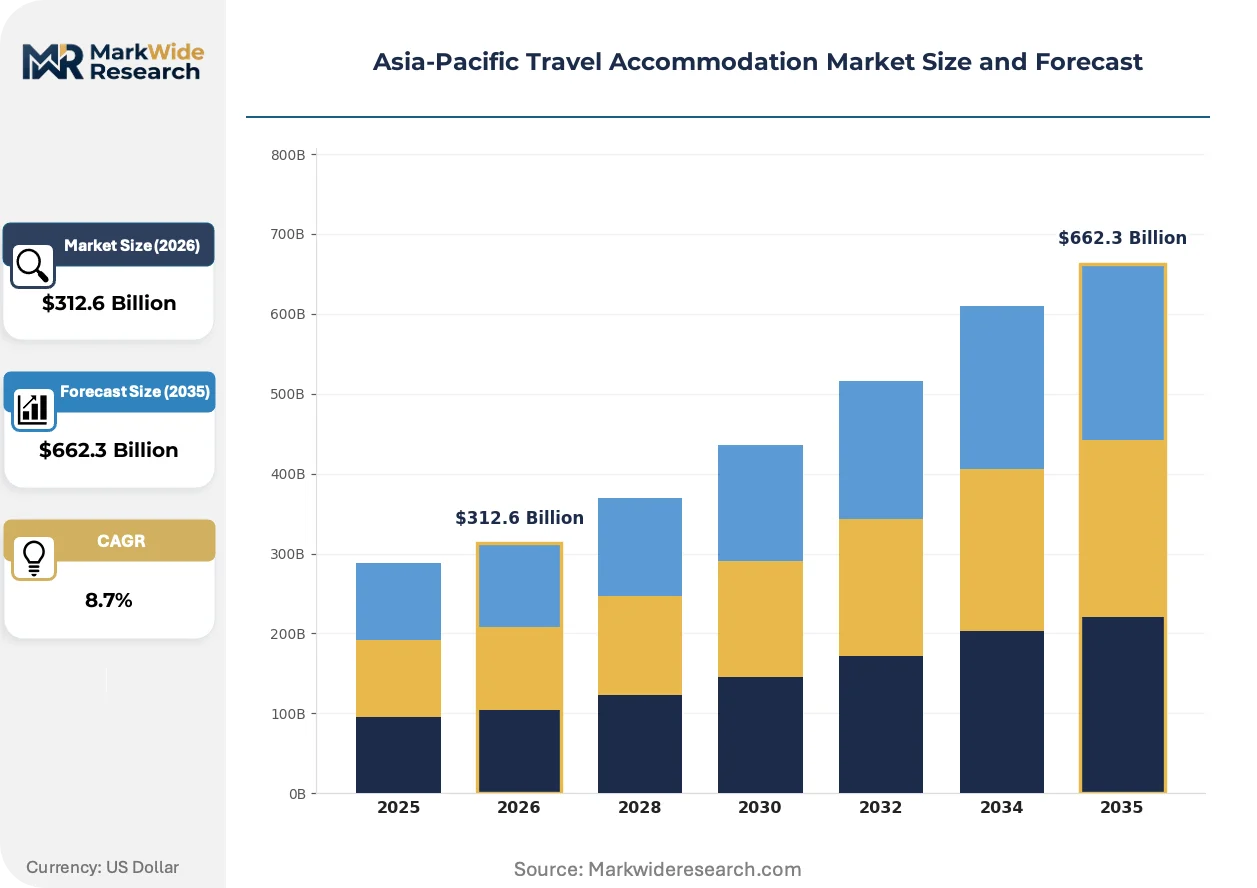
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Hotels, Hostels, Vacation Rentals, Bed & Breakfast Service Quality: Luxury, Mid-Range, Budget, Boutique Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Wholesalers Target Customer: Business Travelers, Leisure Tourists, Families, Solo Travelers |
| Companies Covered | Marriott International, Hilton Worldwide Holdings, InterContinental Hotels Group, Accor, Hyatt Hotels Corporation, Shangri-La Hotels and Resorts, Minor Hotels, OYO Rooms, Jin Jiang International Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Travel Accommodation Market Trends and Innovations
Property-level technology deployment and sustainability disclosure automation are compressing operational cost structures while reshaping guest-facing service models. These shifts concentrate competitive advantage among operators with capital deployment capacity.
Smart room management systems is automating climate control, lighting, and housekeeping dispatch across limited-service formats. Mid-range chains in South Korea and Thailand are deploying these systems at scale to reduce labor intensity. The technology is automating front-desk workflows and compressing night-staffing requirements.
EU Green Deal extraterritorial sustainability disclosure requirements are mandating carbon intensity reporting for European-headquartered chains operating across Asia-Pacific portfolios. Properties must now install sub-metering infrastructure and supplier due diligence protocols. Full-service establishments in gateway cities face the steepest compliance timelines and retrofitting capital demands.
Direct booking preference among domestic tourists is displacing online travel agency dependency for repeat-stay segments. Loyalty-integrated mobile applications capture reservation share from commission-charging intermediaries. This behavioral shift is most visible in China's domestic tourism corridors where platform fatigue and data privacy concerns accelerate platform switching.
Asia-Pacific Travel Accommodation Market Segmentation
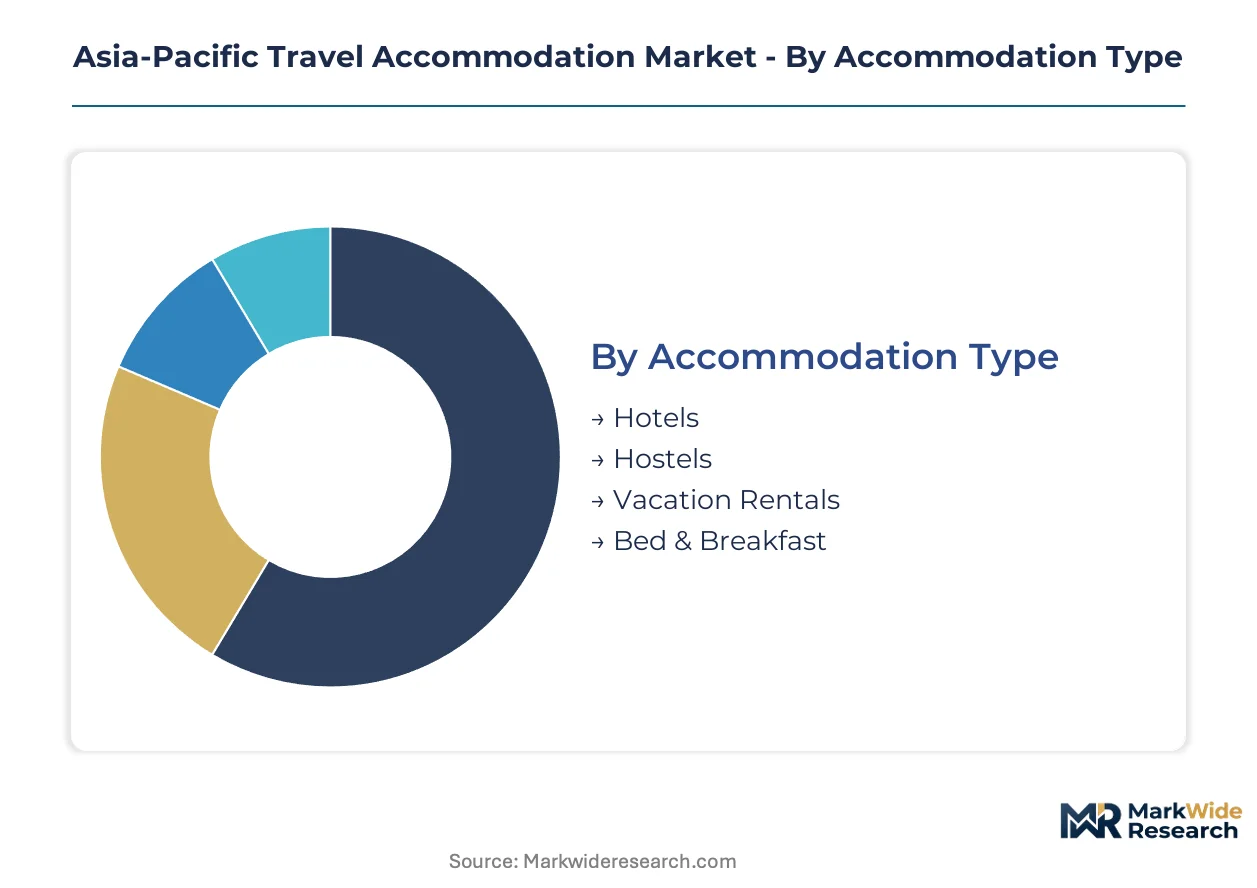
Segmentation in Asia-Pacific travel accommodation reveals divergent capital intensity and margin profiles across property formats. Operators must align portfolio composition with regional demand concentrations in Chinese domestic corridors, Japanese secondary cities, and India's tier-two urban expansion zones.
Accommodation Type:
Hotels command the volume base while vacation rentals capture the steepest expansion trajectory across coastal leisure corridors.
- Hotels:Full-service and limited-service formats integrate guest room inventory systems, housekeeping protocols, and ancillary food-and-beverage infrastructure. Demand concentrates in Tokyo, Osaka, and Shanghai business districts where corporate travel budgets sustain rate premiums. Japan's METI building codes compress renovation cycles for aging urban stock.
- Vacation Rentals:Platform-enabled residential supply unlocks underutilized coastal and mountain inventory without new construction capital. Growth clusters in Thailand's island provinces and Australia's Gold Coast where leisure tourists prioritize space and kitchen facilities over standardized hotel service.
- Hostels:Bunk-bed density models serve price-sensitive solo travelers and young backpackers in gateway city centers. Seoul and Bangkok maintain the densest concentration of branded hostel networks.
- Bed & Breakfast:Owner-operated properties with limited room counts cater to cultural immersion seekers in Japan's regional revitalization zones. Domestic tourists drive occupancy in Kyoto's temple districts and Hokkaido's rural corridors.
Mature deployment sits with Hotels. Newer deployment is concentrated in Vacation Rentals.
Service Quality:
Cost tier stratification separates capital-heavy full-service establishments from asset-light limited-service formats.
- Luxury:Full-service properties with integrated spas, event spaces, and concierge infrastructure command rate premiums in gateway cities. Shanghai's Pudong and Singapore's Marina Bay concentrate international brand flagships where corporate entertainment budgets and high-net-worth leisure demand intersect.
- Mid-Range:Limited-service formats with standardized cleanliness benchmarks and compressed staffing models absorb volume from Chinese domestic tourists. Jin Jiang International Holdings anchors this tier through state-backed real estate access.
- Budget:Cost-efficient turnover models with automated check-in and minimal amenity provision target price-sensitive segments. OYO Rooms competes on franchise density across India's tier-two and tier-three urban corridors.
- Boutique:Design-forward independent properties with localized aesthetic differentiation capture margin pools in cultural destination markets. Kyoto's machiya conversions and Bali's architect-designed villas exemplify this segment.
Margin concentration sits with Luxury. Volume expansion is concentrated in Mid-Range.
Booking Channel:
Customer type and repeat-stay behavior determine channel preference and commission cost exposure.
- Online Travel Agencies:Platform intermediaries aggregate inventory visibility against commission charges typically ranging in the mid-teens percentage. China's SAMR monitors pricing transparency and anti-competitive clauses between platforms and accommodation providers.
- Direct Booking:Proprietary loyalty platforms capture reservation share from commission-based intermediaries. Marriott International sustains direct channel preference through integrated mobile applications and points redemption programs.
- Travel Agents:Human intermediaries retain relevance for complex multi-city itineraries and corporate account management. Japanese inbound tour operators book blocks for international group arrivals.
- Wholesalers:Bulk inventory purchasers package accommodation with air transport for charter and cruise markets. Australia's inbound tour wholesalers dominate Pacific island resort distribution.
Commission burden sits with Online Travel Agencies. Margin recovery is concentrated in Direct Booking.
Target Customer:
Application-based segmentation aligns amenity provisioning with trip purpose and party composition.
- Business Travelers:Corporate account demand concentrates in full-service properties with meeting infrastructure and express laundry. Tokyo's Shinagawa and Shanghai's Hongqiao districts cluster business-oriented inventory near transport hubs.
- Leisure Tourists:Discretionary vacation demand drives seasonal rate volatility and extended-stay packaging in coastal and mountain destinations. Thailand's Phuket and Indonesia's Bali absorb the bulk of regional leisure volume.
- Families:Multi-room requirements and child-friendly amenities prioritize vacation rentals and resort properties with pool and activity infrastructure. Australia's Gold Coast and Japan's Okinawa maintain dedicated family-oriented inventory.
- Solo Travelers:Single-occupancy demand with safety and social interaction priorities sustains hostel density and capsule hotel formats in urban Japan and South Korea.
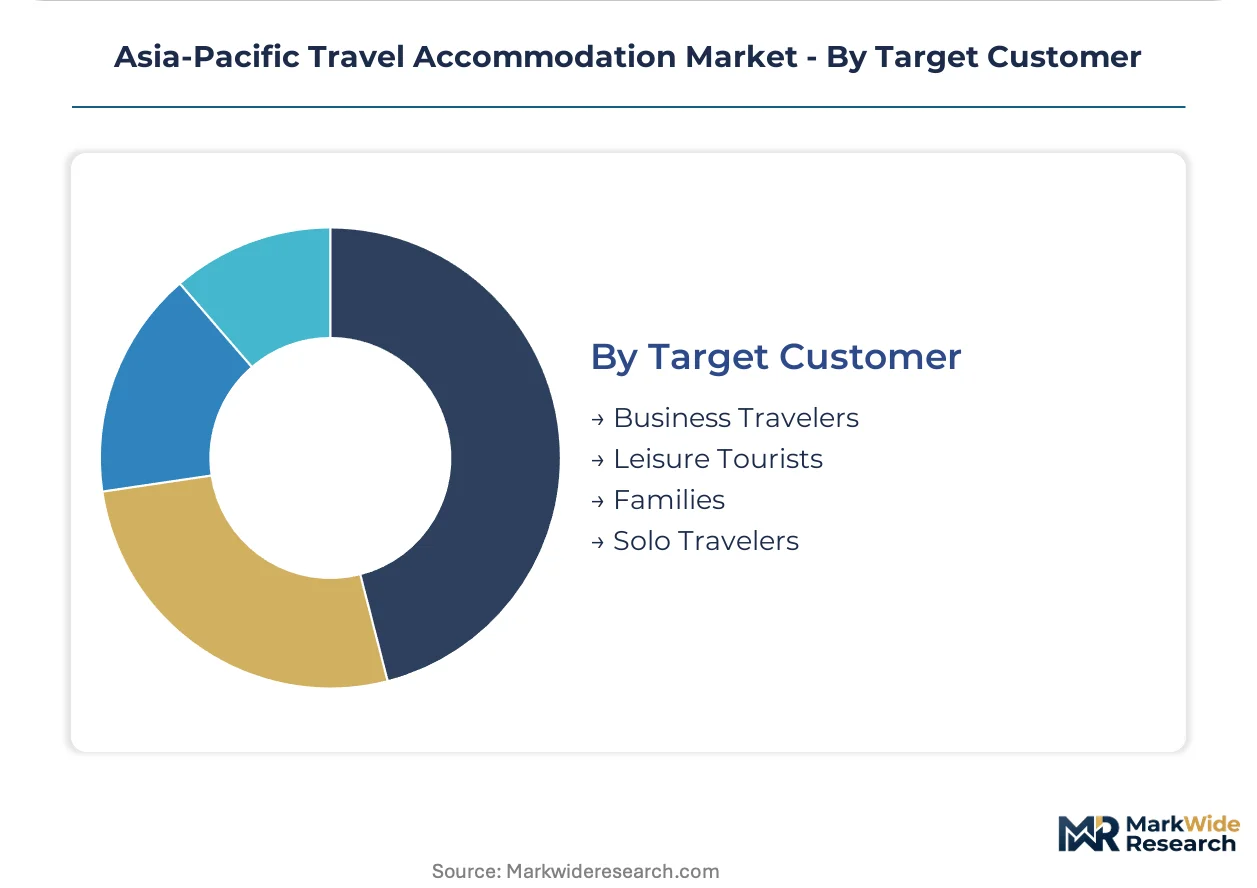
Rate stability sits with Business Travelers. Volume expansion is concentrated in Leisure Tourists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives and duty-free shopping zones concentrate luxury hotel investment along the island's southern coast. These special-economic-zone benefits redirect domestic leisure demand from outbound destinations toward domestic coastal corridors.
China
Domestic tourism policy alignment and middle-class mobility expansion drive booking volume across mid-range and budget tiers. SAMR monitors platform pricing transparency and anti-competitive clauses between online travel agencies and accommodation providers. Shanghai's Pudong and Beijing's Chaoyang districts cluster international brand flagships where corporate entertainment budgets sustain rate premiums.
Japan
Regional revitalization campaigns redirect inbound and domestic demand toward lower-density destinations beyond Tokyo and Osaka. METI enforces hotel building standards and energy efficiency codes that compress renovation cycles for aging urban stock. Fukuoka and Sapporo absorb diverted leisure traffic through government-backed infrastructure subsidies.
India
Tier-two and tier-three urban corridors present franchise density expansion potential with limited incumbent competition. State-level consumer protection frameworks govern cancellation terms and refund obligations across Maharashtra, Karnataka, and Telangana. Jaipur and Lucknow corridors anchor asset-light budget network penetration.
Australia
Coastal leisure corridors unlock underutilized residential supply through platform-enabled vacation rental inventory. State-level consumer protection frameworks in New South Wales and Queensland govern cancellation terms and refund obligations. Gold Coast and Cairns concentrate family-oriented resort infrastructure.
South Korea
Smart room management systems automate climate control and housekeeping dispatch across limited-service formats. MFDS-equivalent national standards shape hospitality technology procurement protocols. Seoul's Gangnam and Busan's Haeundae districts deploy automated front-desk workflows at scale.
Asia-Pacific Travel Accommodation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service quality segments. Market structure concentrates margin pools among international brand flagships in gateway cities while fragmenting across budget franchise networks in secondary corridors. Three archetypes dominate: state-backed real estate conglomerates, proprietary loyalty platform operators, and asset-light franchise aggregators. Competitive moves center on direct booking engine integration and carbon intensity retrofitting timelines.
Among diversified hospitality conglomerates, Marriott International and Hilton Worldwide Holdings occupy positions anchored by proprietary loyalty platforms. Jin Jiang International Holdings exemplifies the state-backed real estate access archetype. OYO Rooms sits within the asset-light franchise density model across India's tier-two urban corridors.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide Holdings |
| InterContinental Hotels Group |
| Accor |
| Hyatt Hotels Corporation |
| Shangri-La Hotels and Resorts |
| Minor Hotels |
| OYO Rooms |
| Jin Jiang International Holdings |
| Others |
Pricing and Supply Chain Analysis
Smart room management system deployment across South Korean and Thai limited-service properties simultaneously compresses labor costs and concentrates procurement power among technology-integrated chains. This automation transition rewards operators with capital deployment capacity while fragmenting pricing power across legacy properties lacking standardized infrastructure.
Pricing Analysis
Short lead-time inventory commands rate premiums in Japan's secondary city corridors where government-backed regional revitalization campaigns divert demand from saturated Tokyo-Osaka axes. Three-tier pricing structure across luxury, mid-range, and budget levels stratifies by service intensity and loyalty platform integration. Pricing pressure stems from China's SAMR platform transparency mandates limiting rate parity enforcement. Budget franchise networks exhibit highest price sensitivity; luxury gateway properties maintain rate resilience through corporate entertainment budgets.
Supply Chain Analysis
Certification gating through Japan's METI building codes and China's MEE disclosure frameworks restricts supplier pools to compliant equipment vendors. China, South Korea, and Japan anchor manufacturing concentration for hospitality technology components. Property-level technology stacks draw from semiconductor inputs, HVAC subsystems, and cloud infrastructure services. Single-source vulnerability concentrates in proprietary loyalty platform software. Distribution runs through direct manufacturer relationships for large chains and regional distributors for independent properties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where EU Green Deal extraterritorial disclosure requirements erect barrier-to-entry moats favoring capitalized multinational chains over asset-light local operators.
For Market Incumbents: Anchor competitive position through accelerated carbon intensity retrofitting timelines that outpace regulatory minimums. Defend against OYO Rooms-style franchise density expansion by locking prime Chinese real estate through Jin Jiang-aligned state partnerships. Prioritize proprietary loyalty platform integration to capture direct booking share from commission-charging intermediaries.
For New Entrants and Emerging Players: Capture white-space in India's tier-two and tier-three urban corridors where incumbent brand presence remains thin. Target vacation rental platform enablement in Thailand's island provinces and Australia's Gold Coast where residential supply conversion outpaces new hotel construction. Pursue asset-light franchise aggregation with localized operational support rather than capital-heavy property ownership.
For Investors and Strategic Acquirers: Exit pathways concentrate in loyalty platform-enabled mid-range chains with demonstrated direct booking conversion. Long-term viability favors operators with state-backed real estate access and early compliance positioning against tightening METI and MEE codes. Watch for inflection in China's domestic tourism policy alignment as signal for mid-range volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Intensity Retrofitting | EU Green Deal compliance unlocks preferential financing access through China's MEE frameworks. |
| Loyalty Platform Integration | Marriott-style proprietary booking engines capture direct channel share from OTAs. |
| Tier-Two Franchise Density | OYO Rooms model penetrates India's underserved urban corridors with limited incumbent competition. |
| Smart Room Technology Deployment | South Korean automation adoption compresses labor intensity across limited-service formats. |
| Regional Revitalization Alignment | Japan's METI-backed secondary city campaigns redirect leisure demand from saturated gateway markets. |
Research Methodology
Independent corroboration across hospitality technology vendors, property development executives, and online travel agency pricing strategists underwrites the qualitative findings. Primary fieldwork engaged hotel operations directors, franchise development leads, sustainability compliance officers, and regional tourism board planners. Secondary validation drew from METI building code filings, SAMR regulatory circulars, EU Green Deal technical guidance, and hospitality chain SEC disclosures. Bottom-up property inventory analysis triangulates against top-down tourism arrival statistics.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation modeling incorporates accommodation type, service quality tier, booking channel, and target customer archetype dimensions. CAGRs derive from fitted trend analysis calibrated to historical booking velocity and forward-looking supply pipeline data. Forecast inputs include domestic tourism policy trajectory, platform regulatory enforcement intensity, and energy efficiency code implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese middle-class mobility trends and EU sustainability disclosure enforcement reach. Model assumptions reflect current regulatory frameworks without anticipating unannounced policy shifts. A model refresh is warranted upon material change in Japan's regional revitalization subsidy allocation or China's SAMR platform governance stance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Alternative Accommodation Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
China Tourism and Hotel Market
Accommodation
Germany Student Accommodation Market
Accommodation
Movie Theaters Market
Accommodation
US Student Accommodation Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
Capsule Hotels Market
Accommodation
Japan Online Accommodation Market
Accommodation
Austria Hospitality Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Europe Student Accommodation Market
Accommodation
Romania Hospitality Market
Accommodation
Hostel Market
Accommodation
France Online Accommodation Market