
 Global Travel Accommodation Market | 2026-2036
Global Travel Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Travel Accommodation Market Foresight
Online travel agency distribution is rewriting how inventory reaches guests, collapsing traditional intermediation layers. Marriott International leverages its Bonvoy loyalty ecosystem to sustain direct booking volumes against aggregator commissions. Airbnb anchors alternative supply in urban centers, competing with standardized hotel tiers through host-network scale. Wyndham Hotels & Resorts dominates economy-segment franchising, extending its footprint across secondary markets with asset-light expansion.
Travel accommodation encompasses commercial lodging facilities offering temporary overnight stays, ranging from single-room bed-and-breakfast operations to multi-tower integrated resorts with food-and-beverage, conference, and wellness infrastructure. Properties typically operate on per-night pricing models with yield-management systems adjusting rates dynamically against occupancy forecasts, serving tourists, business visitors, and event attendees. Hotels retain the largest revenue pool across accommodation types, though apartments capture extended-stay demand from remote workers seeking kitchen-equipped stays. Online travel agencies represent the fastest-growing booking channel, displacing legacy travel agent intermediation as mobile-first booking penetration deepens.
The EU Green Deal's CSRD disclosure rules and ESG benchmarking frameworks pressure European operators to certify energy performance and waste reduction. The US FTC scrutinizes drip pricing and hidden resort fee disclosures, reshaping rate transparency obligations for cross-border booking platforms. China's SAMR enforces consumer protection standards on domestic online travel agencies, influencing how multinational platforms structure local partnerships. Stakeholders must monitor regulatory divergence between carbon-accounting jurisdictions and pricing-transparency regimes to align compliance investment with market access priorities.
Market Dynamics
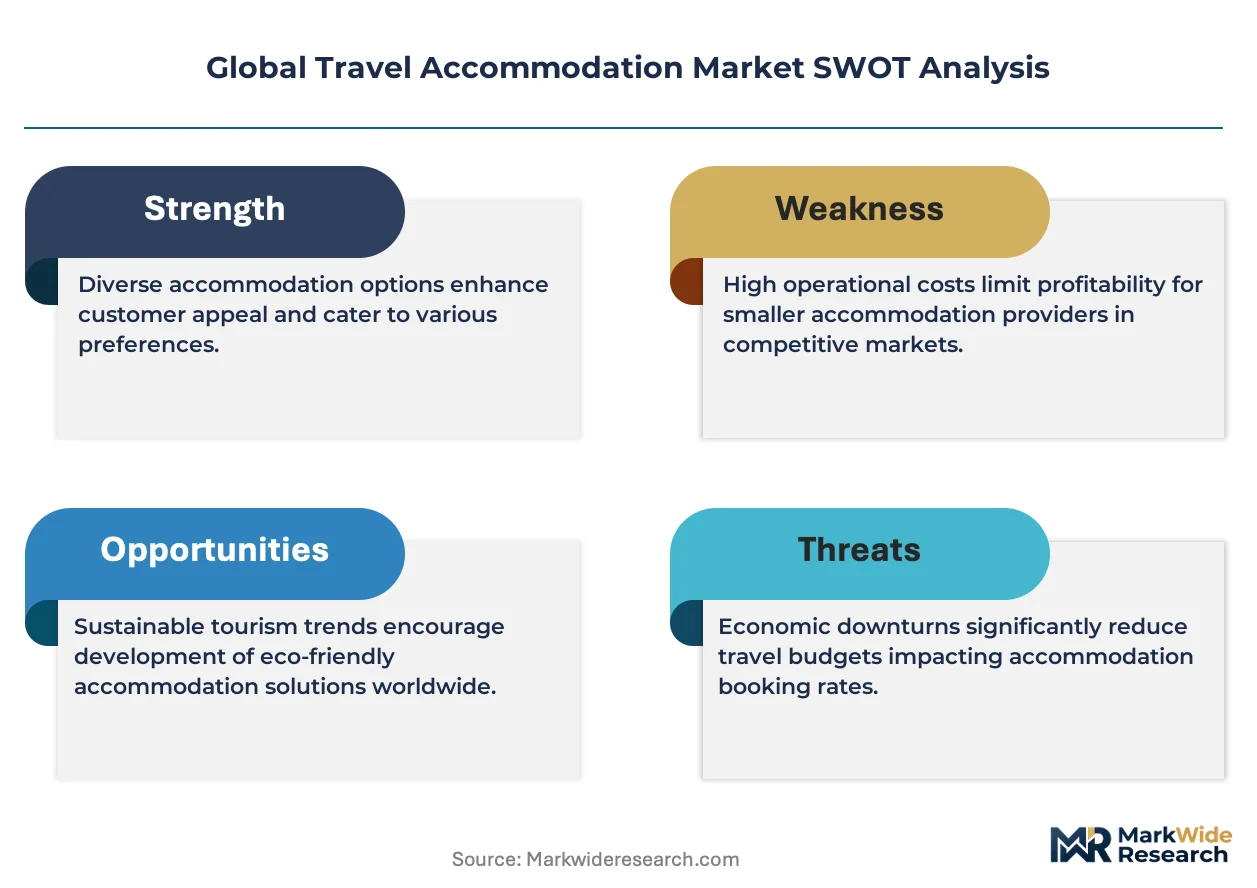
Online travel agency platforms compress booking margins while EU Green Deal CSRD disclosure rules force property-level energy audits and waste-tracking investments across European portfolios.
Growth Catalysts
- Bleisure Travel Normalization:Hybrid work arrangements extend business trips into leisure stays, driving extended-night bookings at coastal and urban properties.
- CSRD Reporting Mandates:EU Green Deal sustainability disclosure requirements accelerate green building certifications among European hotel operators seeking ESG-aligned capital.
- Southeast Asia Inventory Expansion:Thailand, Indonesia, and Vietnam authorize coastal development permits, adding resort capacity to capture intra-regional tourism flows.
Market Restraints
- Labor Cost Escalation:Housekeeping and front-desk wage pressures in the US and EU compress operating margins at midscale properties.
- Aggregator Commission Burden:Online travel agency take rates of 15-25% erode net revenue per available room for independent operators.
- Seasonal Demand Volatility:Resort-dependent markets in the Mediterranean and Caribbean face occupancy swings that strain fixed-cost structures.
Strategic Opportunities
- Extended-Stay Apartment Conversion:Remote worker demand for kitchen-equipped monthly rentals opens repositioning opportunities for underperforming urban hotel assets.
- Direct Booking Infrastructure:Loyalty program investments and mobile app development reduce platform dependency for branded chains.
- Green Certification Premium Capture:LEED and BREEAM-certified properties command rate premiums from corporate travel managers with net-zero procurement mandates.
Industry Challenges
- Legacy Property Management System Integration:Decades-old on-premise software architectures resist cloud-based channel manager and revenue management system connectivity.
- Hidden Fee Disclosure Compliance:US FTC drip-pricing investigations require reengineering of rate display logic across booking engines and call center scripts.
- Workforce Retention:Frontline hospitality roles face elevated turnover, forcing continuous recruitment and training investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Travel Accommodation Market |
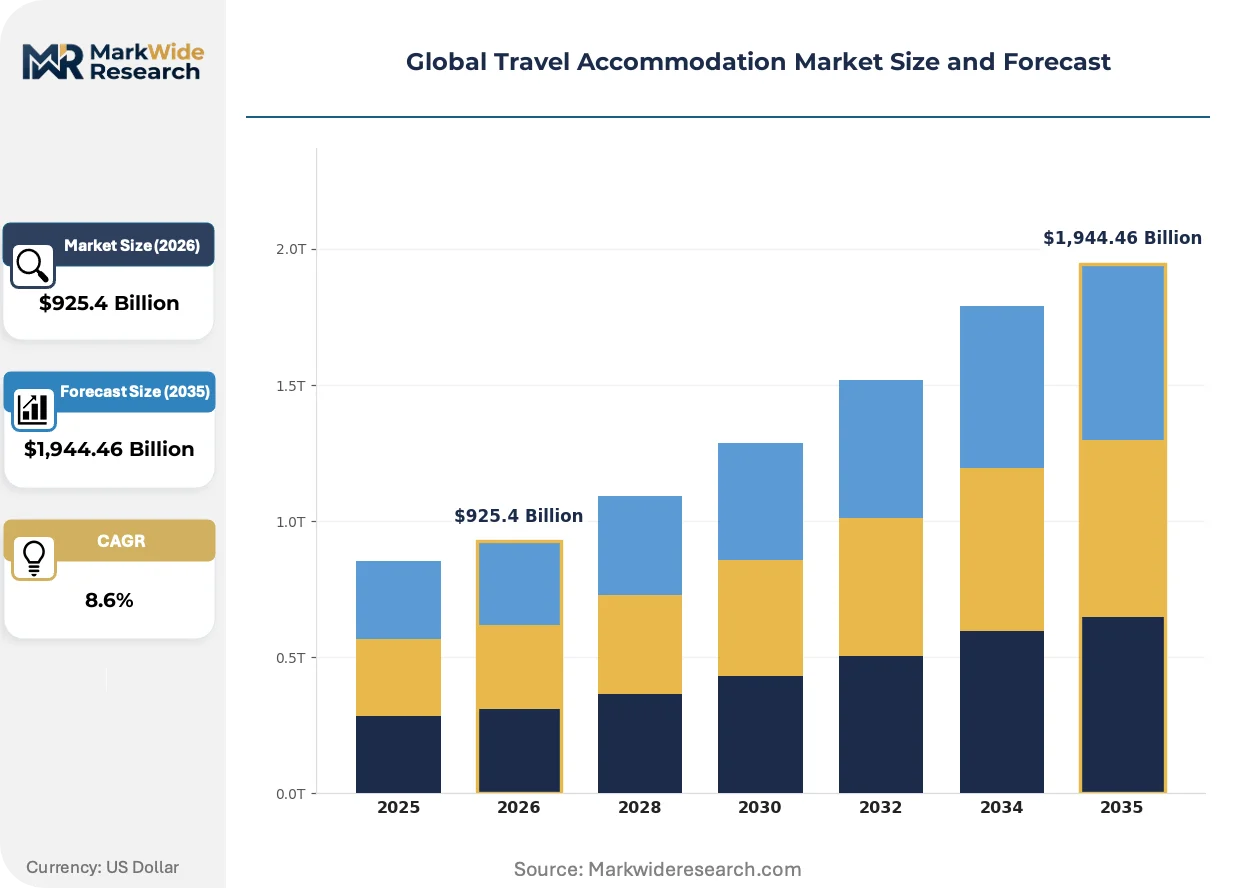
| Market Size in 2026 | $925.4 Billion |
| Market Size in 2035 | $1,944.46 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Hotels, Hostels, Apartments, Resorts Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Mobile Apps Customer Segment: Leisure Travelers, Business Travelers, Group Travelers, Backpackers Service Type: Self-Catering, Full Board, Bed & Breakfast, All-Inclusive |
| Companies Covered | Marriott International, Hilton Worldwide Holdings, IHG Hotels & Resorts, Hyatt Hotels Corporation, Accor, Airbnb, Wyndham Hotels & Resorts, Radisson Hotel Group, Four Seasons Hotels and Resorts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Travel Accommodation Market Shifts & Advancements
Property technology stacks are compressing guest-facing touchpoints while sustainability certification becomes a booking-filter criterion. Distribution channels fragment as platforms and direct channels compete for loyalty.
Contactless check-in and mobile key technology is migrating from luxury-tier installations to economy and midscale properties. Independent operators and franchisees adopt white-label app solutions to match branded chain capabilities. This technology compression eliminates front-desk staffing minimums and enables 24-hour arrival flexibility without night-audit labor costs.
EU Green Deal CSRD disclosure rules force granular energy and waste reporting from 2024 implementation timelines. European operators must install submetering infrastructure and establish supplier emission data collection. Properties in Germany, France, and the Netherlands face the steepest compliance curves as national transpositions add building-specific audit requirements.
Corporate travel managers now filter booking platforms by property-level sustainability certifications. Third-party aggregators respond by displaying eco-labels prominently, while hotel chains embed carbon footprint estimates into confirmation emails. This procurement preference shift concentrates volume toward certified inventory in Nordic and Benelux markets where corporate travel policies enforce strict ESG criteria.
Global Travel Accommodation Market Segmentation
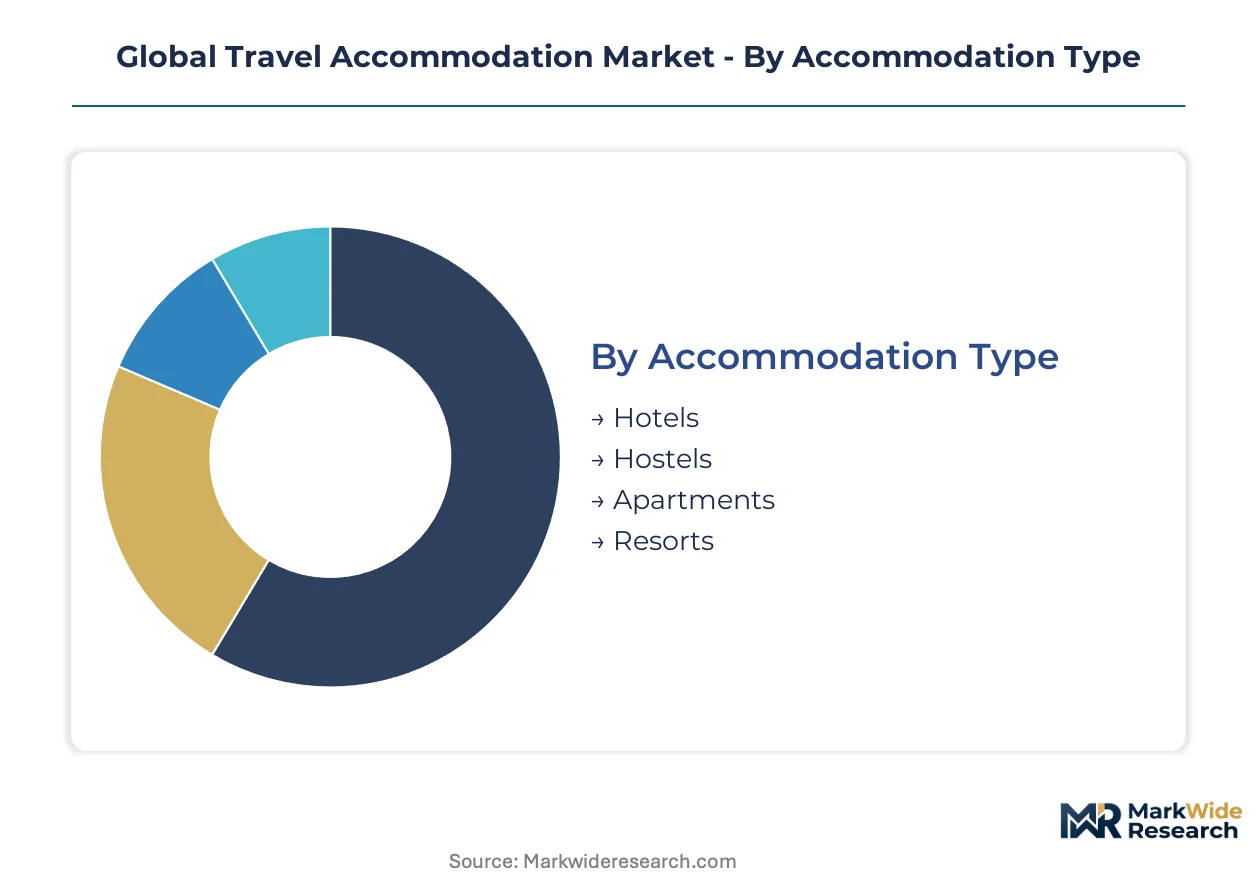
Segmentation in travel accommodation reveals how distinct traveler needs, booking behaviors, and service expectations fragment demand across property types and channels. Operators optimize yield management, distribution spend, and amenity provisioning differently for each slice. Understanding these divisions exposes where margin compression concentrates and where premium capture remains viable.
Accommodation Type:
After-sales service intensity varies sharply across accommodation types, with full-service hotels maintaining 24-hour concierge and maintenance operations while self-catering apartments shift service burden to digital troubleshooting platforms.
- Hotels:Multi-room properties with standardized room configurations, on-site food and beverage operations, and dedicated housekeeping staff. Demand concentrates in Germany, France, and the United Kingdom where corporate travel managers negotiate volume rates for business districts. Operating leverage from fixed staffing costs creates margin pressure during occupancy troughs.
- Apartments:Kitchen-equipped units offering extended-stay functionality with weekly or monthly pricing structures. Remote workers in Lisbon, Barcelona, and Mexico City drive demand for residential-style stays with workspace amenities. Furnishing depreciation and utility pass-through complexity distinguish the cost structure from nightly-rental models.
- Hostels:Shared-room inventory targeting price-sensitive solo travelers with minimal private space and communal facilities. Bunk-bed density maximizes revenue per square meter in urban cores.
- Resorts:Integrated properties combining accommodation with recreation, wellness, and entertainment infrastructure on contiguous land parcels. Coastal Thailand and Indonesian archipelago developments capture intra-regional leisure flows.
By volume, hotels lead. By growth pace, apartments are expanding most quickly.
Booking Channel:
Cost tier separation between channels determines net revenue per booking, with direct reservations avoiding 15-25% aggregator commissions but requiring heavier customer acquisition spend through loyalty programs and search engine marketing.
- Online Travel Agencies:Third-party platforms aggregating inventory across multiple properties with review systems and price comparison tools. Commission structures and visibility algorithms shape operator participation economics.
- Direct Booking:Reservations completed through property websites, call centers, or walk-in arrivals without intermediary involvement. Branded chains in the United States and United Kingdom invest in mobile app development and member-exclusive rates to shift share from aggregators.
- Travel Agents:Human intermediaries providing consultation and itinerary packaging, now concentrated in corporate travel management and complex multi-destination leisure planning. Legacy brick-and-mortar networks in Japan and Germany retain niche presence for senior traveler segments.
- Mobile Apps:Smartphone-native booking interfaces with push-notification pricing and instant confirmation. Penetration deepest in Southeast Asian markets where smartphone-first internet access dominates.
By transaction volume, online travel agencies dominate. By margin retention, direct booking delivers superior economics.
Customer Segment:
Application context—leisure versus business versus group coordination—drives divergent amenity requirements, cancellation flexibility demands, and length-of-stay patterns across the same physical inventory.
- Leisure Travelers:Discretionary trip planners booking around school holidays, seasonal weather, and destination events. Price sensitivity peaks in family multi-room bookings where alternative destination substitution remains viable.
- Business Travelers:Corporate-funded stays with negotiated rate agreements, loyalty program enrollment, and proximity requirements to conference venues or client offices. Weeknight concentration in financial district properties creates utilization challenges for weekend revenue management.
- Group Travelers:Coordinated bookings for weddings, conferences, or tour operations requiring block room holds and catering coordination. Cancellation terms and attrition clauses dominate contract negotiations.
- Backpackers:Ultra-price-sensitive long-duration travelers prioritizing location and social atmosphere over room specifications. Dormitory inventory and communal kitchens match budget constraints.
By absolute room nights, leisure travelers lead. By rate per night and cancellation policy strictness, business travelers command premium positioning.
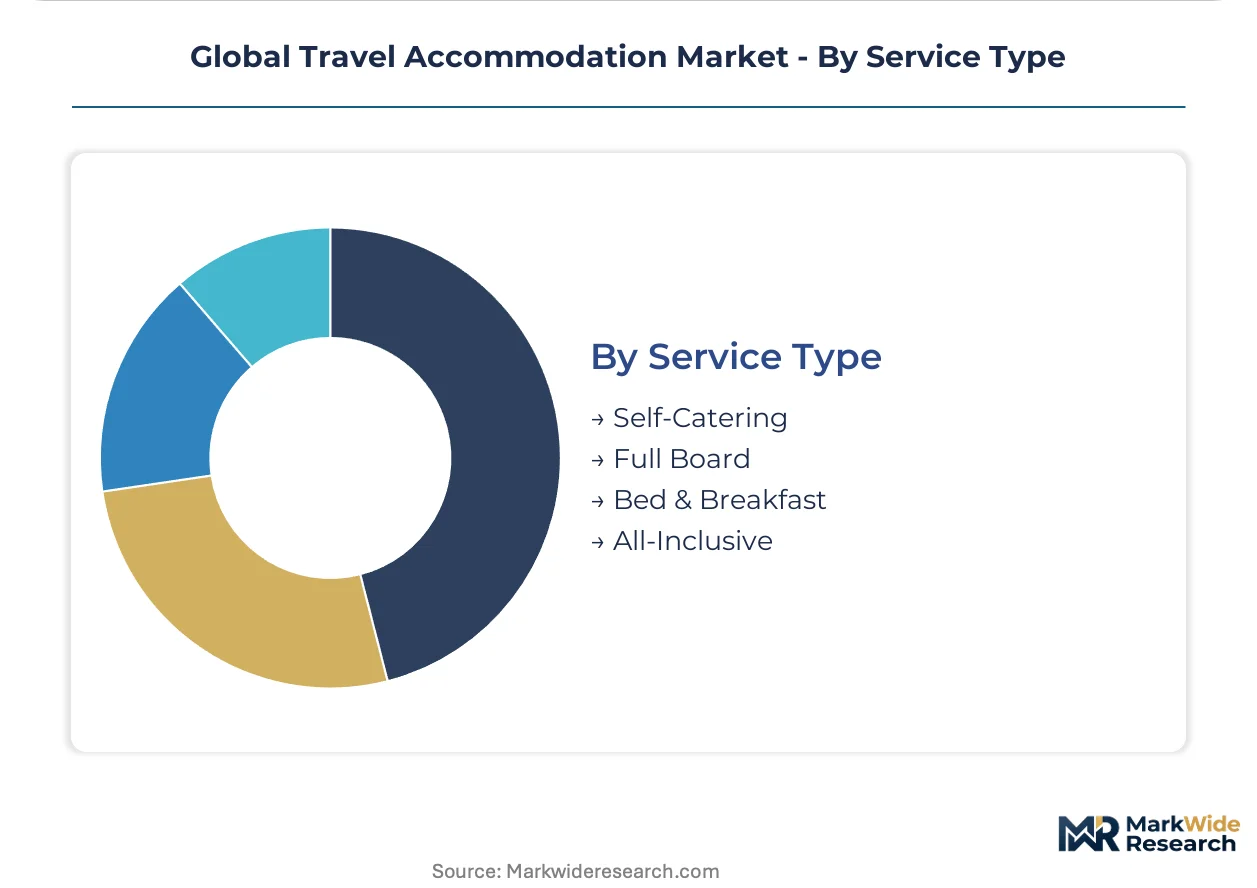
Service Type:
Margin structure varies with meal inclusion depth, with all-inclusive packages capturing guest spend upfront while self-catering shifts food revenue to external retailers.
- Self-Catering:Accommodation with equipped kitchen facilities and no meal provision, common in apartments and vacation rentals. Grocery retail and restaurant spending occurs off-property.
- Bed & Breakfast:Limited meal inclusion typically covering morning provision only, characteristic of small-scale independent properties and guesthouse operations.
- Full Board:Three-meal daily inclusion with set-menu or buffet service, standard in institutional settings like retreat centers and training facilities.
- All-Inclusive:Comprehensive packaging of accommodation, meals, beverages, and activities with single upfront pricing. Resort properties in the Caribbean and Mediterranean deploy this model to maximize guest capture and minimize external spend leakage.
By property count, bed and breakfast operations lead. By revenue per available room, all-inclusive properties achieve the steepest expansion trajectory through ancillary capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC enforces drip-pricing transparency mandates across the United States, reshaping how American booking platforms display total rates. This regulatory anchor influences cross-border platform operations worldwide.
United States
Bleisure travel normalization and remote-work flexibility drive extended-night bookings in coastal California and urban Texas corridors. The FTC's hidden-fee disclosure investigations force reengineering of rate display logic across booking engines. Miami and Austin clusters concentrate luxury and extended-stay inventory expansion targeting hybrid professionals.
Germany
Corporate travel manager procurement with net-zero mandates concentrates volume in ESG-certified properties across Frankfurt and Munich business districts. The EU Green Deal's CSRD disclosure rules accelerate building-specific energy audits and submetering infrastructure investments. Berlin-Brandenburg and Bavaria lead green certification adoption among midscale and upscale portfolios.
China
Domestic tourism recovery and intra-regional leisure flows sustain resort development in Hainan and Yunnan provinces. SAMR consumer protection standards enforce platform transparency requirements on domestic online travel agencies. The Yangtze River Delta and Pearl River Delta urban clusters anchor mobile-first booking penetration and apartment inventory growth.
Thailand
Intra-regional tourism from Southeast Asian source markets drives coastal resort permit authorizations in Phuket and Krabi. National tourism board sustainability certification programs align with EU Green Deal disclosure expectations for European inbound segments. Bangkok's urban core competes with coastal inventory through boutique hotel conversions and extended-stay apartment repositioning.
United Kingdom
Corporate travel policy ESG criteria filter booking platform selections toward certified inventory in London and Manchester financial districts. Post-Brexit regulatory divergence from EU CSRD timelines creates compliance investment uncertainty for cross-border operators. The Southeast England corridor concentrates loyalty program infrastructure and direct-booking mobile app development among branded chains.
Global Travel Accommodation Market Competitive Landscape
Branded hotel chains and alternative accommodation platforms split the market between standardized service tiers and host-network scale economies. Consolidation concentrates among multinational hospitality groups with loyalty ecosystems, while fragmentation persists in independent and boutique segments. Two strategic archetypes dominate: asset-light franchisors leveraging brand equity without property ownership, and platform aggregators capturing booking volume through review systems and price comparison tools. Competitive moves center on direct-booking infrastructure investments and sustainability certification differentiation.
Within the branded-chain tier, Marriott International and Hilton Worldwide Holdings exemplify loyalty-program-driven direct booking strategies. Airbnb occupies a distinct position as the anchor alternative-supply platform competing through host-network density rather than property ownership. Wyndham Hotels & Resorts represents the economy-segment franchising archetype with secondary-market footprint extension. These three entities collectively illustrate how scale, platform architecture, and segment positioning fragment competitive dynamics across the accommodation spectrum.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide Holdings |
| IHG Hotels & Resorts |
| Hyatt Hotels Corporation |
| Accor |
| Airbnb |
| Wyndham Hotels & Resorts |
| Radisson Hotel Group |
| Four Seasons Hotels and Resorts |
| Others |
Supply & Pricing Matrix
Linens and housekeeping supply manufacturing concentrates in China and Bangladesh, compressing procurement costs for economy-tier operators while premium properties absorb branded amenity premiums from European suppliers. This upstream concentration funnels margin downstream toward properties with direct booking infrastructure that bypasses aggregator commission layers.
Pricing Analysis
Urban coastal properties in California command nightly rate premiums over comparable inventory in Texas secondary markets, reflecting location-driven price spreads. Three-tier pricing structure across luxury, midscale, and economy levels segments demand by amenity depth and loyalty program access. Pricing pressure stems from online travel agency commission burdens of 15-25% that erode net revenue per available room. Leisure travelers exhibit highest price sensitivity, while corporate travel managers with negotiated rate agreements demonstrate lowest elasticity.
Supply Chain Analysis
Extended payment terms from textile and furniture suppliers anchor working capital structures for independent operators with limited balance sheet capacity. Manufacturing concentrates in China, Vietnam, and Turkey for soft goods and case goods respectively. Property technology hardware draws from Taiwanese semiconductor supply chains and South Korean display manufacturers. Single-source vulnerability runs through cloud-based property management system providers with concentrated market share. Distribution runs through hospitality-specific procurement consortia and direct manufacturer relationships for branded chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where ancillary revenue streams from food and beverage, spa services, and loyalty program co-branding expand faster than base room rate growth.
For Market Incumbents: Pre-empt aggregator platform encroachment by accelerating direct booking mobile app development and member-exclusive rate structures. Defensive consolidation moves include acquiring independent boutique properties in Southeast Asia's resort corridors and investing in LEED certification infrastructure to capture corporate travel manager procurement filters. The threat of commission rate escalation from online travel agencies demands channel control investment.
For New Entrants and Emerging Players: Establish a beachhead in extended-stay apartment conversions targeting remote worker demand in Lisbon, Barcelona, and Mexico City urban cores. White-space targets include underperforming hotel asset repositioning with kitchen-equipped units and workspace amenities. The most penetrable segment comprises hybrid professionals seeking monthly rental structures. A go-to-market angle leveraging sustainability certification as a booking-filter criterion aligns with EU Green Deal procurement mandates.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed economy hotel franchisors with secondary-market footprint concentration. Long-term viability across a 5-10 year window hinges on asset-light expansion scalability and loyalty program ecosystem depth. Acquisition target archetypes include regional boutique chains with ESG-certified inventory in Nordic and Benelux markets. The signal to watch is corporate travel policy ESG criteria adoption rates as an inflection indicator for certified property demand concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Loyalty Program Ecosystem Expansion | Marriott's Bonvoy architecture demonstrates direct booking volume retention against aggregator platforms. |
| Green Certification Infrastructure Investment | LEED and BREEAM-certified properties capture rate premiums from EU corporate travel managers. |
| Extended-Stay Asset Repositioning | Kitchen-equipped conversions in Lisbon and Barcelona target remote worker monthly rental demand. |
| Direct Booking Mobile App Development | Branded chains in the United States shift share from online travel agencies through member-exclusive rates. |
| Southeast Asia Resort Corridor Expansion | Thailand and Indonesia coastal permit authorizations capture intra-regional tourism flows from Asian source markets. |
Research Methodology
Cross-validation between property-level operational data and online travel agency commission disclosures anchors the qualitative findings. Primary interviews with revenue management directors, franchise development executives, corporate travel procurement managers, and sustainability certification consultants combined with secondary validation from hospitality industry association filings, SEC 10-K disclosures, EU CSRD implementation guidance, and national tourism board statistics. Bottom-up property inventory counts and top-down macroeconomic tourism flow estimates complete the triangulation.
Calibration against historical booking channel shifts and occupancy volatility patterns shaped the analytical framework across the modeling period. Segmentation dimensions include accommodation type, booking channel, customer segment, and service inclusion depth. CAGRs were derived from demand driver elasticity modeling and supply pipeline authorization tracking. Forecast inputs incorporate bleisure travel normalization rates and EU Green Deal compliance investment schedules.
Stress conditions across labor cost escalation, aggregator commission rate adjustments, and seasonal demand volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hybrid work permanence and sustainability procurement mandate adoption. Macroeconomic recession, regulatory divergence from EU CSRD timelines, or technological disruption in property management systems would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Airport Sleeping Pods Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
Canada Hospitality Market
Accommodation
Hostel Market
Accommodation
Hotel Market
Accommodation
Airport Lounges Market
Accommodation
France Casino Tourism Market
Accommodation
Capsule Hotels Market
Accommodation
Russia Online Accommodation Market
Accommodation
Underwater Hotels Market
Accommodation
France Online Accommodation Market
Accommodation
Glamping Market
Accommodation
Japan Hospitality Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
Movie Theaters Market
Accommodation
Hong Kong Hospitality Industry Market