
 Europe Online Travel Market | 2026-2036
Europe Online Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Online Travel Market Analysis
Direct booking channels between hotels and consumers is tilting as property management systems lower switching costs for independent operators. Booking.com dominates inventory breadth across European urban centers. GetYourGuide specializes in curated activity marketplaces that bypass traditional tour operator markups. Airbnb navigates regulatory fragmentation across municipal short-term rental regimes while sustaining host acquisition in coastal and alpine destinations.
Europe online travel encompasses digital platforms that aggregate, compare, and transact transportation, accommodation, and experiential inventory through proprietary algorithms and API-connected supplier networks. These systems process real-time availability, dynamic pricing, and multi-currency settlement to reduce search friction and transaction costs for cross-border movement. The distribution channel dimension reveals Online Travel Agencies capturing the deepest margin pools through bundled commissions and loyalty program lock-in, while meta-search engines occupy high-traffic, low-conversion positions upstream. The service type split shows accommodation retaining the largest transaction value per booking, though activities represents the fastest-growing attachment rate as travelers seek experiential differentiation.
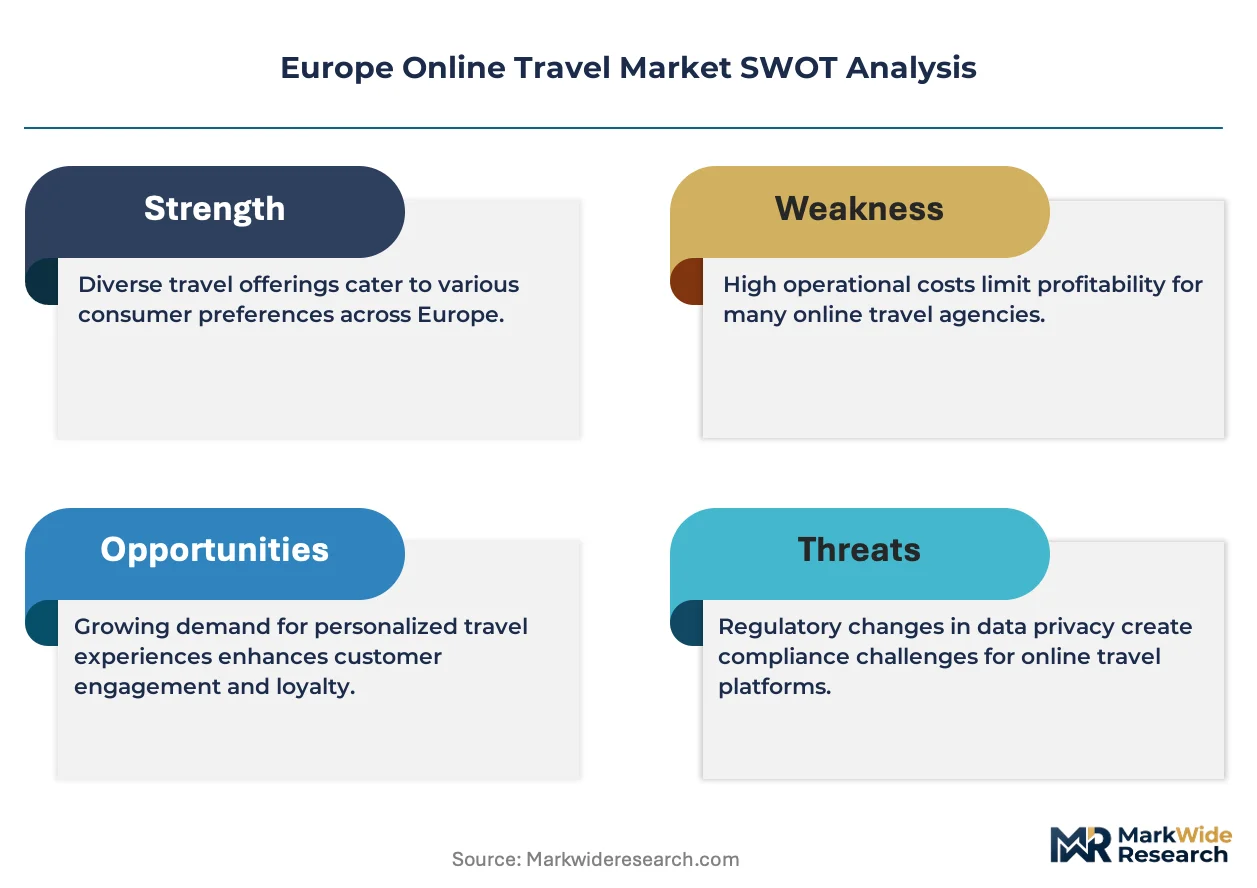
The EU Digital Services Act, national implementations of the Package Travel Directive, and GDPR compliance frameworks collectively raise operational costs for intermediaries while mandating algorithmic transparency in ranking and pricing display. The European Commission's ongoing scrutiny of most-favored-nation clauses in platform-hotel contracts reshapes how inventory parity terms distribute negotiating power between suppliers and aggregators. Stakeholders must monitor whether emerging AI-driven personalization engines trigger fresh regulatory attention under the EU AI Act's risk classification framework.
Market Dynamics
The EU Digital Services Act and national implementations of the Package Travel Directive are forcing intermediaries to restructure algorithmic ranking transparency and pricing display mechanisms. Independent property management systems erode traditional OTA lock-in by lowering switching costs for hoteliers.
Growth Catalysts
- GDPR-compliant personalization engines:Machine learning systems that process consent-managed traveler data enable predictive itinerary construction without violating privacy frameworks.
- Mediterranean leisure corridor concentration:Spain, Italy, and Greece generate disproportionate transaction velocity through seasonal demand clustering in coastal and island destinations.
- API-connected supplier networks:Real-time inventory synchronization between property management systems and distribution platforms compresses booking friction and cancellation latency.
Market Restraints
- Most-favored-nation clause scrutiny:The European Commission's ongoing antitrust investigations into platform-hotel parity agreements create contractual uncertainty for inventory distribution terms.
- Municipal short-term rental fragmentation:Barcelona, Paris, and Amsterdam impose divergent registration caps and occupancy limits that complicate host acquisition strategies.
- Payment settlement complexity:Multi-currency hedging requirements and PSD2 strong customer authentication protocols elevate operational overhead for cross-border transactions.
Strategic Opportunities
- Experiential inventory attachment:Curated activity marketplaces bypass traditional tour operator markups by connecting travelers directly with local experience providers.
- Alpine destination host expansion:Underpenetrated ski and hiking corridors in Austria, Switzerland, and Slovenia offer supply-side growth vectors beyond saturated coastal markets.
- EU AI Act risk classification alignment:Early compliance with algorithmic transparency mandates for recommendation systems creates defensive positioning against future enforcement waves.
Industry Challenges
- Algorithmic auditing talent scarcity:Shortage of technologists capable of interpreting explainability requirements under the EU AI Act's high-risk system classifications.
- Legacy PMS integration friction:Independent hoteliers operating outdated property management systems face data migration complexity when connecting to modern distribution APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Online Travel Market |
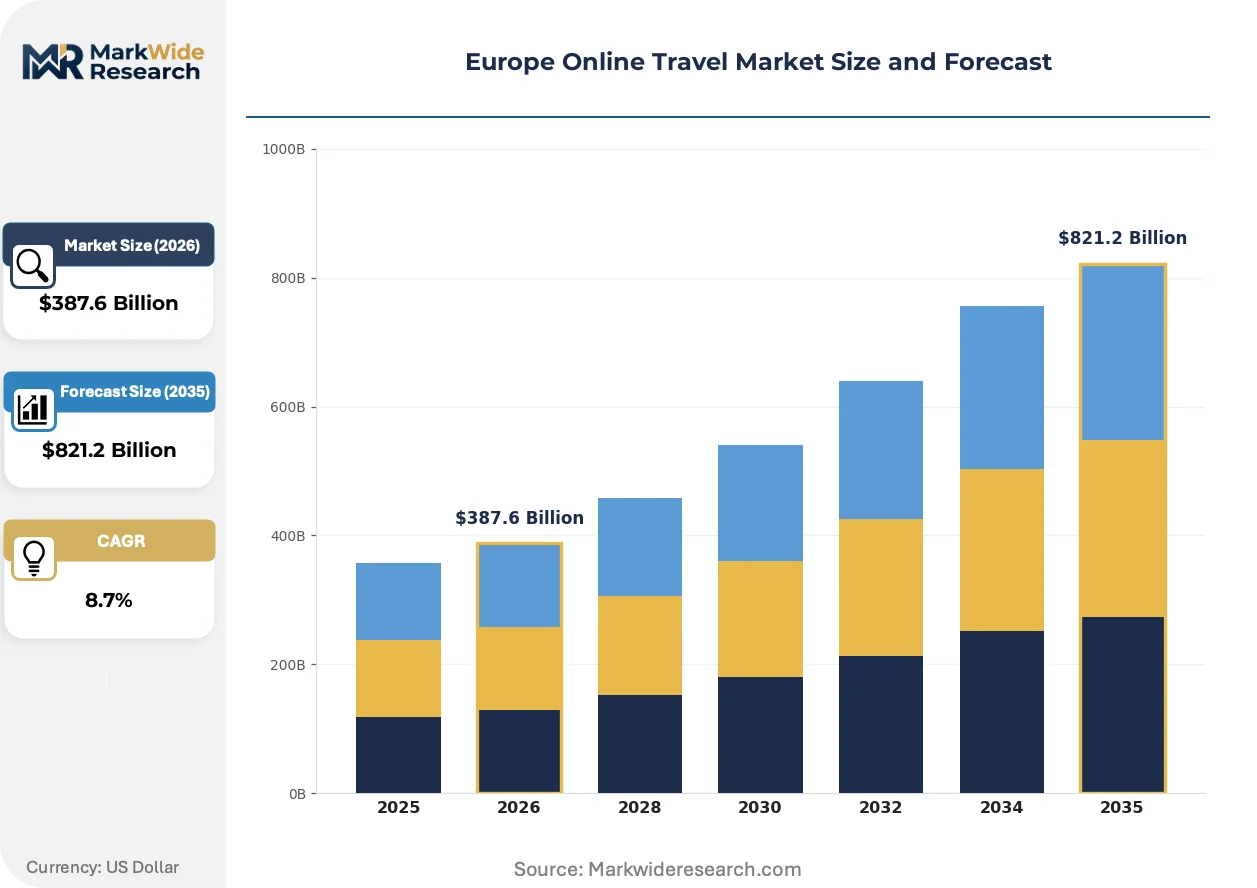
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Transportation, Activities, Food Services Price Tier: Luxury, Mid-Range, Economy, Budget Distribution Channel: Online Travel Agencies, Direct Booking, Meta-Search Engines, Traditional Agencies Customer Type: Leisure Travelers, Business Travelers, Families, Solo Travelers |
| Companies Covered | GetYourGuide, Agoda, Booking.com, HRS, KAYAK, Expedia, Airbnb, LateRooms, Tripadvisor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Online Travel Market Emerging Trajectories
Generative AI and real-time inventory APIs are compressing the traditional travel planning cycle from weeks to hours. Platform economics tilt toward suppliers with direct channel capabilities.
Dynamic bundling algorithms is collapsing the separation between accommodation, transport, and activity booking windows. Independent travelers in the Mediterranean corridor adopt these tools fastest. The structural consequence is margin compression for standalone OTA segments that cannot attach experiential inventory.
The EU Digital Services Act mandates algorithmic transparency in ranking and pricing display. Intermediaries must now disclose parameters influencing search results. Urban hotel inventory in France and Germany faces the steepest compliance recalibration as national regulators draft implementing decrees.
Travelers increasingly construct itineraries through conversational interfaces rather than sequential search-and-compare workflows. Meta-search engines lose upstream traffic to integrated planning tools. This behavioral pivot concentrates in Nordic markets where digital service adoption rates lead continental averages.
Europe Online Travel Market Segmentation
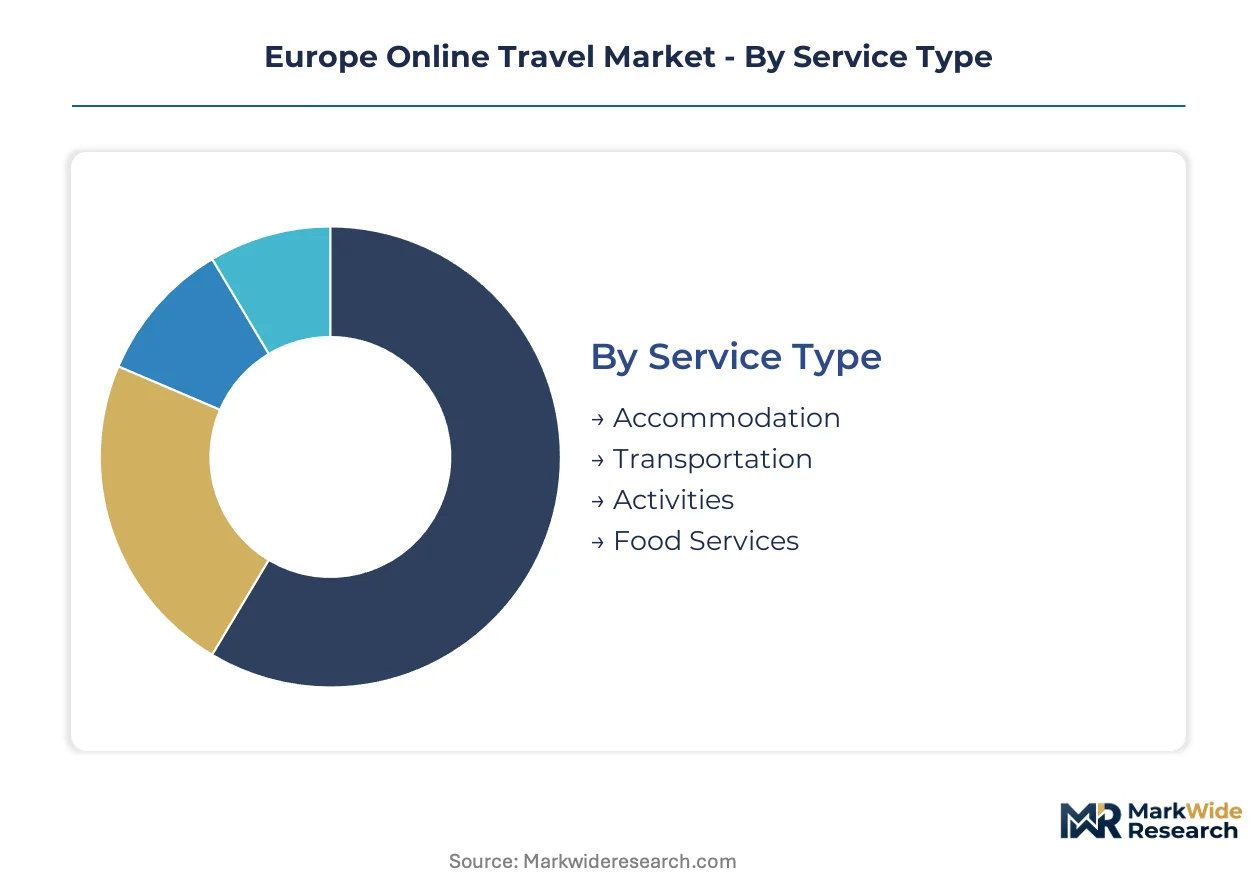
Segmentation reveals how digital intermediaries capture value across distinct transaction profiles. Service type and distribution channel configurations determine margin capture, while price tier and customer type shape inventory procurement strategies.
Service Type:
Mature accommodation platforms coexist with emerging experiential marketplaces across the Mediterranean corridor.
- Accommodation:Digital platforms aggregate hotel, short-term rental, and alternative lodging inventory through real-time availability APIs. Transaction concentration in Spain, Italy, and Greece coastal destinations drives commission pool depth, though municipal registration caps in Barcelona and Paris constrain supply expansion.
- Activities:Curated experience marketplaces connect travelers directly with local operators, bypassing traditional tour intermediaries. Demand clusters in island and alpine destinations where travelers seek experiential differentiation beyond standard accommodation packages.
- Transportation:Rail, aviation, and ground transport booking modules integrate into multi-modal itinerary builders through carrier API connections.
- Food Services:Restaurant reservations and culinary experiences attach to accommodation bookings as secondary revenue streams.
Accommodation retains volume leadership; activities holds the steepest expansion curve.
Price Tier:
Cost stratification mirrors supplier negotiation power and commission elasticity across urban and leisure corridors.
- Luxury:High-commission inventory from boutique properties and premium hotel groups commands preferential placement in algorithmic rankings. GDPR-compliant personalization engines drive predictive recommendations for high-value Mediterranean villa and alpine chalet segments.
- Mid-Range:Urban hotel inventory in France and Germany dominates this tier, where EU Digital Services Act transparency mandates reshape pricing display mechanics.
- Economy:Standardized chain properties compete on price parity across OTA and direct channels.
- Budget:Hostel and basic lodging aggregators target price-sensitive solo travelers and young leisure segments.
Mid-Range captures the broadest transaction base; Luxury delivers the highest commission yield per booking.
Distribution Channel:
Channel configuration determines data ownership and customer relationship depth.
- Online Travel Agencies:Proprietary algorithms process real-time inventory and dynamic pricing across multi-supplier networks. Booking.com and similar platforms capture deepest margin pools through bundled commissions and loyalty lock-in, though most-favored-nation clause scrutiny by the European Commission creates contractual uncertainty.
- Direct Booking:Property management system integration enables hotels to bypass intermediary commissions. Independent operators in Austria and Switzerland leverage lower switching costs to reclaim customer relationships.
- Meta-Search Engines:High-traffic, low-conversion positioning upstream of transaction completion faces pressure from conversational planning interfaces.
- Traditional Agencies:Legacy operators retain corporate and complex itinerary segments requiring human curation.
Online Travel Agencies maintain transaction dominance; Direct Booking gains share fastest as PMS integration friction declines.
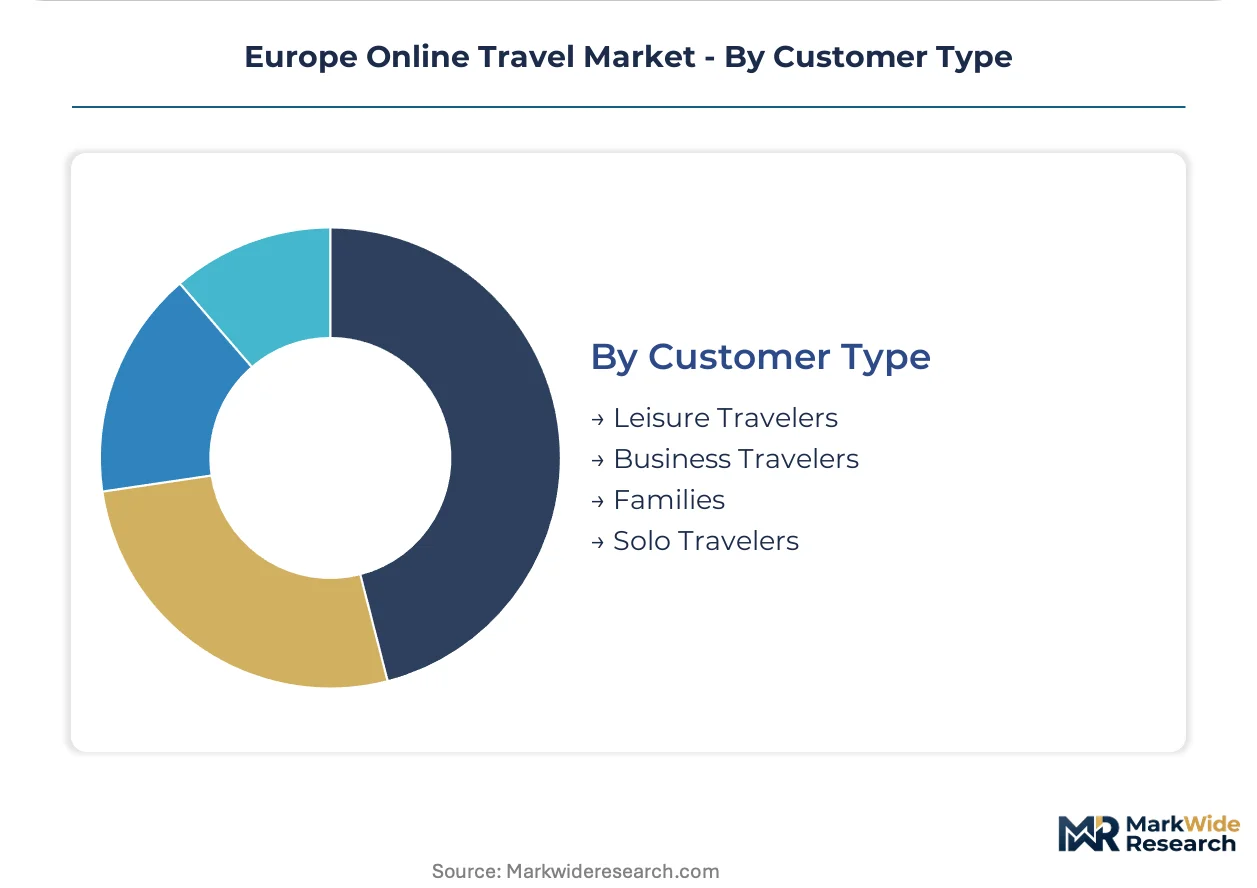
Customer Type:
Behavioral segmentation shapes inventory curation and attachment rate strategies.
- Leisure Travelers:Independent travelers drive platform traffic across Mediterranean corridors, constructing itineraries through mobile interfaces rather than sequential search workflows. Nordic markets lead in conversational booking tool adoption.
- Business Travelers:Corporate policy compliance and expense management integration requirements distinguish this segment from leisure procurement patterns.
- Families:Multi-room bookings and activity bundling generate higher average transaction values in coastal Spain and Greek island destinations.
- Solo Travelers:Price sensitivity and experience-seeking behavior concentrate demand in budget accommodation and curated activity marketplaces.
Leisure Travelers generate the highest absolute transaction volume; Solo Travelers show the strongest activity attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and British urban centers extract higher commission yields per transaction than Mediterranean leisure corridors, reversing traditional assumptions about pricing power in European online travel distribution.
Spain
Coastal demand clustering in Barcelona and the Balearic Islands drives transaction velocity for short-term rental platforms. Municipal registration caps in Barcelona constrain host acquisition strategies under local short-term rental ordinances. The Costa del Sol corridor generates concentrated booking activity during peak summer windows.
Italy
Rome and Milan urban hotel inventory faces steep EU Digital Services Act compliance recalibration as national regulators draft implementing decrees. The Package Travel Directive's national implementation reshapes cancellation and pricing display mechanics for intermediaries. Tuscany and Amalfi Coast villa segments attract premium commission structures.
Germany
Business traveler procurement patterns distinguish corporate policy compliance segments from leisure demand in Frankfurt and Munich. The EU Digital Services Act mandates algorithmic transparency in ranking and pricing display for platforms operating across federal jurisdictions. Berlin's independent hotel sector leverages property management system integration to reclaim direct booking relationships.
France
Paris municipal authorities impose divergent registration caps and occupancy limits that complicate host acquisition for short-term rental platforms. The CNIL enforces GDPR-compliant personalization engine standards for predictive itinerary construction. Lyon and Nice hotel markets experience pricing display restructuring under national consumer protection code implementations.
Greece
Island destination demand concentrates transaction value in the Cyclades and Ionian corridors during compressed seasonal windows. National consumer protection frameworks align with EU Package Travel Directive requirements for intermediary liability. Athens urban inventory competes with coastal properties for platform algorithmic placement priority.
Europe Online Travel Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented supply niches. The market structure consolidates around three dominant inventory aggregation platforms with broad geographic coverage, while experiential and niche accommodation specialists occupy defensible vertical positions. Two strategic archetypes predominate: full-stack intermediaries bundling transport, lodging, and activities; and curated marketplace operators connecting travelers directly with local experience providers. Competitive moves center on API-connected supplier network expansion and GDPR-compliant personalization engine deployment.
Within the full-stack intermediary tier, Booking.com and Expedia occupy positions defined by inventory breadth and multi-supplier network density. GetYourGuide exemplifies the curated marketplace archetype, anchoring the experiential inventory segment through direct local operator relationships. These three entities represent the competitive spectrum from horizontal aggregation to vertical specialization in European online travel distribution.
| Leading Market Players |
|---|
| GetYourGuide |
| Agoda |
| Booking.com |
| HRS |
| KAYAK |
| Expedia |
| Airbnb |
| LateRooms |
| Tripadvisor |
| Others |
Supply Flow & Price Mechanics
Mediterranean ferry corridor cost volatility compresses margin pools for experiential inventory aggregators while amplifying price differentiation between dynamically bundled packages and standalone accommodation bookings. Supply concentration in Spanish and Greek island destinations feeds this pricing asymmetry as platforms negotiate commission structures against fragmented local operator networks.
Pricing Analysis
The customization-premium spread between configured experiential packages and standard accommodation-only bookings widens as travelers demand itinerary personalization. Three-tier pricing structure across premium villa segments, mid-range urban hotels, and economy hostel inventory reflects commission elasticity and supplier negotiation power. Pricing pressure stems from direct booking channel expansion enabled by property management system integration. Leisure travelers in Mediterranean corridors exhibit highest price sensitivity; corporate procurement segments in German urban centers show lowest.
Supply Chain Analysis
Tariff exposure between UK and EU jurisdictions dominates supply chain risk calculus for cross-border platform operations post-Brexit. Inventory sourcing concentrates in Spain, Italy, and Greece for experiential operators; Germany and France anchor business travel procurement systems. Cloud infrastructure and payment processing APIs constitute critical input dependencies alongside local operator relationship networks. Single-source vulnerability sits with dominant property management system providers. Distribution runs through API-connected supplier networks linking fragmented accommodation inventory to aggregation platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics fragmentation creates white-space opportunities as independent travelers abandon sequential search workflows for conversational planning interfaces. Demand-side shift toward experiential differentiation fragments inventory procurement across specialized activity marketplaces.
For Market Incumbents: Harden algorithmic transparency compliance under EU Digital Services Act mandates before enforcement waves intensify. Consolidate API-connected supplier network density in underpenetrated Alpine corridors to offset Mediterranean seasonality concentration. Vertical integration into property management systems offers defensive positioning against direct booking channel erosion.
For New Entrants and Emerging Players: Pursue curated marketplace positioning in Slovenia and Austrian alpine destinations where experiential inventory remains fragmented. Target solo traveler segments showing strongest activity attachment rates with mobile-first conversational interfaces. Go-to-market leverage rests on direct local operator relationships bypassing traditional tour intermediary markups.
For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape for algorithmic personalization engine capabilities. Long-term viability favors platforms with defensive compliance positioning and experiential inventory attachment infrastructure. Acquisition target archetype: vertically specialized activity marketplaces with direct local operator networks. Signal to monitor: European Commission enforcement actions on most-favored-nation clause investigations.
| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Personalization Engine Deployment | Machine learning systems processing consent-managed traveler data enable predictive itinerary construction under privacy frameworks. |
| API-Connected Supplier Network Expansion | Real-time inventory synchronization compresses booking friction between property management systems and distribution platforms. |
| Alpine Destination Host Acquisition | Underpenetrated ski and hiking corridors in Austria and Switzerland offer supply-side growth beyond saturated coastal markets. |
| Algorithmic Transparency Compliance Investment | Early alignment with EU Digital Services Act ranking disclosure mandates creates defensive positioning against enforcement. |
| Experiential Inventory Attachment Capability | Curated activity marketplaces bypass traditional tour operator markups by connecting travelers directly with local providers. |
Methodological Framework
A standing panel of platform product managers, hotel revenue directors, local experience operators, and regulatory compliance officers provided ongoing calibration against operating reality. Primary interviews combined with secondary validation from EU Digital Services Act implementation trackers, GDPR enforcement databases, property management system integration documentation, and Mediterranean tourism board statistics. Bottom-up transaction modeling triangulated against top-down market sizing across service type and distribution channel dimensions.
Scenario-bracketing framed projections across the analysis window with sensitivity testing for regulatory enforcement timing and technology adoption curves. Segmentation modeling incorporated service type, price tier, distribution channel, and customer behavioral archetype dimensions. CAGRs derived from trend extrapolation of transaction velocity data and supplier network expansion rates. Forecast inputs included seasonal demand clustering patterns and municipal short-term rental ordinance evolution.
Sensitivities concentrate around European Commission antitrust enforcement intensity and AI Act implementation timeline uncertainty. Forecasts reflect documented assumptions regarding traveler behavioral persistence and regulatory compliance cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market