
 Airport Sleeping Pods Market | 2026-2036
Airport Sleeping Pods Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Sleeping Pods Market Intelligence
Pay-per-use booking software is recalibrating how airport sleeping pods generate revenue, shifting capital expenditure models toward recurring service income. Minute Suites leverages proprietary reservation platforms to control premium lounge-adjacent real estate in North American hubs. GoSleep anchors its position through compact fold-flat designs optimized for dense gate-area deployment. Sleepbox differentiates via modular architecture that allows rapid reconfiguration between single-occupancy and paired layouts.
Airport sleeping pods are enclosed, climate-controlled rest units typically spanning 3-7 square meters, constructed from fire-rated composites with integrated ventilation, lighting, and charging infrastructure, designed to provide short-duration sleep or privacy within terminal environments. Premium pods and luxury suites command the highest margin pools due to attached concierge services and extended-stay pricing flexibility, while economy pods and standalone units represent the volume frontier as secondary airports seek low-capex entry points. Modular systems are gaining traction among operators prioritizing relocation flexibility across seasonal route shifts.
FAA terminal design guidelines and OSHA indoor air quality standards shape pod ventilation and egress requirements in the United States, while EU Green Deal energy benchmarks push manufacturers toward heat-recovery climate systems and recyclable interior panels. The EU AI Act's biometric provisions will influence access-control technology choices for automated entry systems. Stakeholders must monitor how evolving fire-safety certifications and accessibility mandates in multiple jurisdictions affect product development timelines and airport procurement criteria.
Market Dynamics
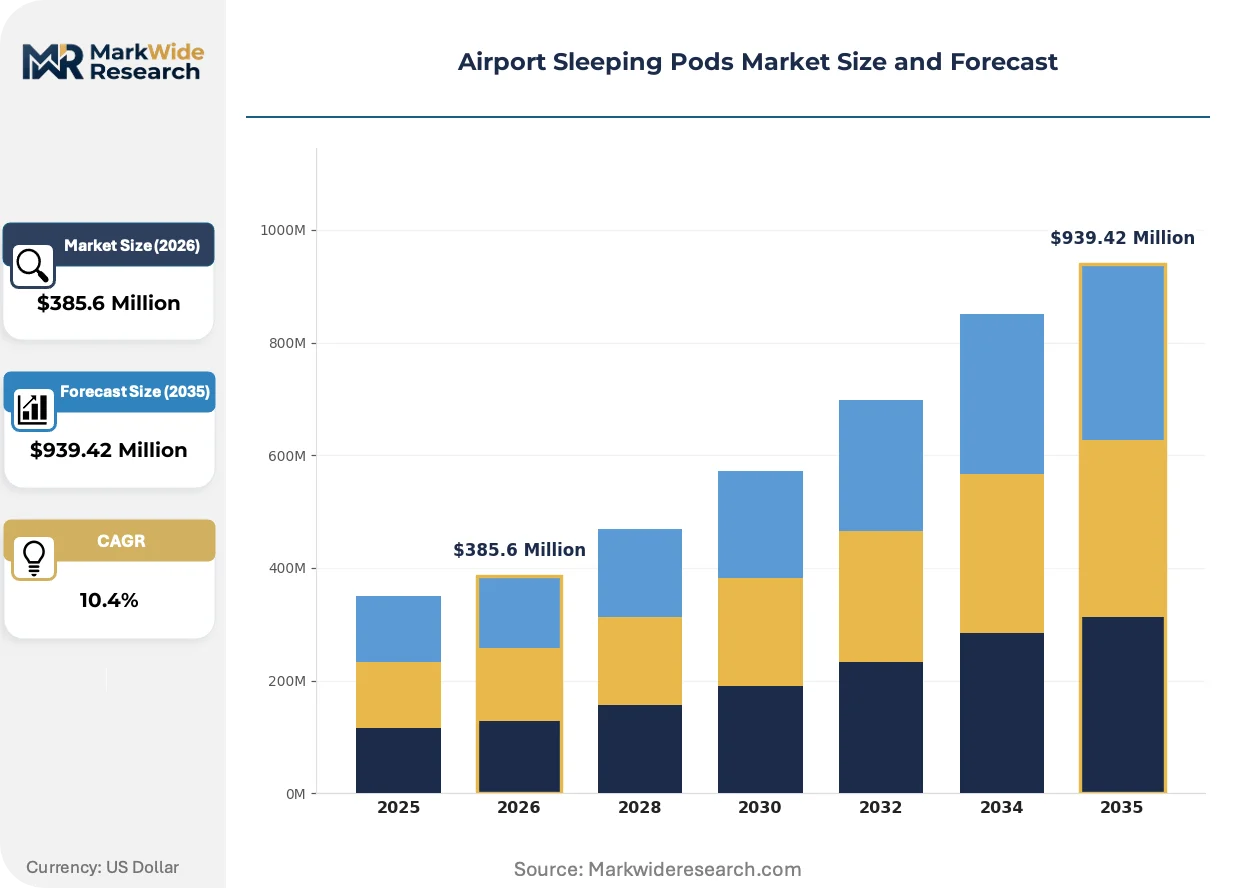
Pay-per-use software platforms are restructuring airport sleeping pod economics, converting fixed capital investments into recurring revenue streams while compressing operator payback periods from years to months.
Growth Catalysts
- EU Green Deal energy mandates:Heat-recovery HVAC systems and recyclable composite panels now command procurement preference across European hubs, creating technology differentiation for compliant manufacturers.
- Transit passenger volume concentration:Dallas Fort Worth International and Hartsfield-Jackson Atlanta anchor the largest installed bases in the United States, validating hub-and-spoke deployment models for secondary airports.
- Modular architecture adoption:Rapid reconfiguration between single-occupancy and paired layouts allows operators to flex capacity across seasonal route shifts without terminal reconstruction.
Market Restraints
- Fire-rated composite input volatility:Specialized phenolic resins and aviation-grade laminates face supply concentration among Asian chemical processors, exposing manufacturers to freight cost swings.
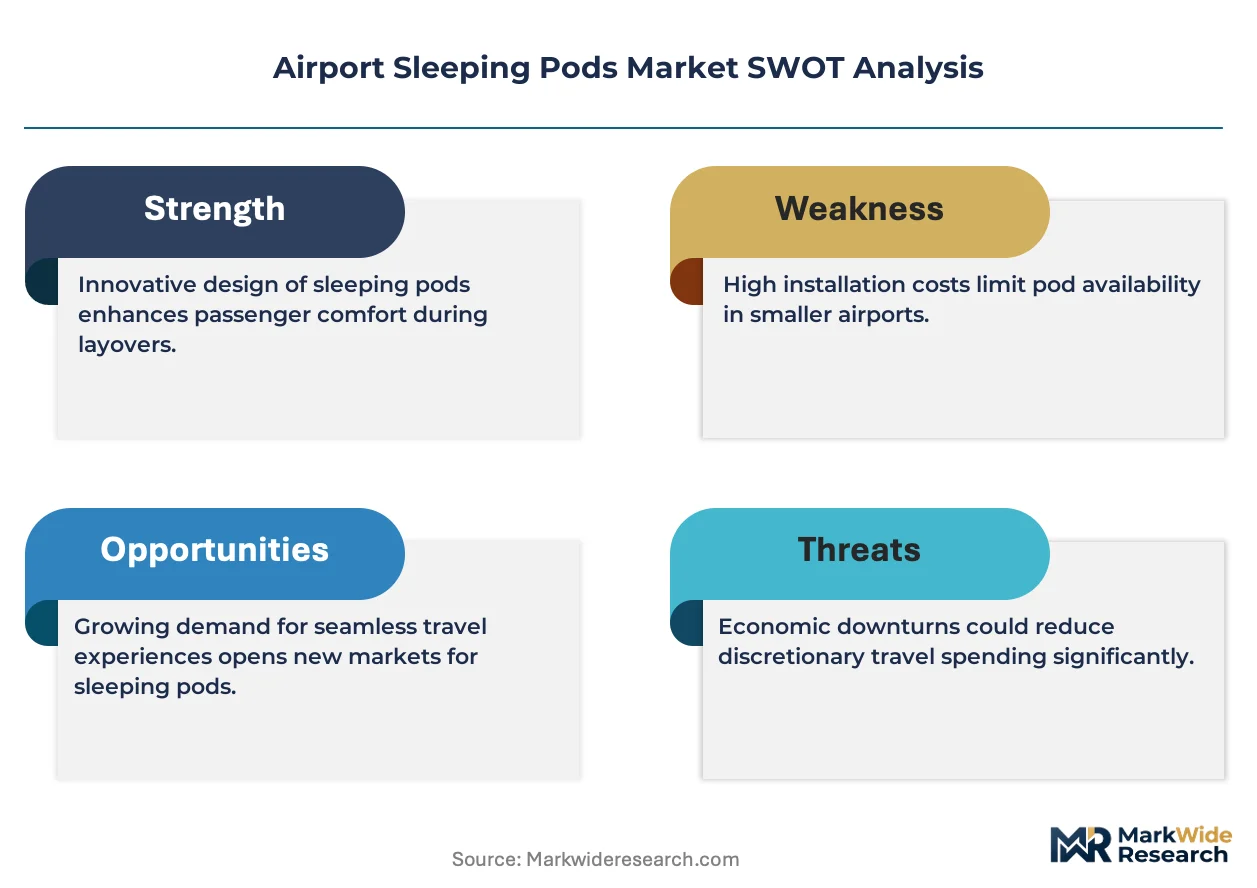
- FAA terminal design compliance friction:Egress pathway requirements and ventilation specifications extend product development timelines by 8-14 months for US market entry.
- Extended-stay hotel substitution:Airport-adjacent properties with shuttle services capture price-sensitive layover demand above four hours, compressing pod addressable windows.
Strategic Opportunities
- Secondary airport penetration in India:Greenfield terminals under the country's airport privatization program lack legacy lounge infrastructure, creating first-mover installation potential.
- Biometric access convergence:Facial recognition entry systems integrated with airline passenger data streams eliminate check-in friction and enable seamless billing.
- Concierge service unbundling:Premium pods attach wake-up calls, meal delivery, and flight monitoring as separately priced modules, expanding margin pools beyond base rental.
Industry Challenges
- Aviation-certified electrician scarcity:Installation teams must hold FAA-approved airfield credentials, constraining deployment velocity during hub expansion windows.
- OSHA indoor air quality recertification:Three-year ventilation system audits require operational downtime that conflicts with 24/7 terminal operating models.
- Legacy terminal power infrastructure:Pre-2010 gate areas lack sufficient electrical capacity for pod HVAC loads without utility upgrade negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Sleeping Pods Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $939.42 Million |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Pods, Premium Pods, Luxury Suites, Economy Pods Deployment: Standalone Units, Integrated Lounges, Modular Systems, On-Demand Rentals Use Case: Long-Haul Travelers, Transit Passengers, Airport Staff, Business Commuters End User: International Airports, Domestic Terminals, Private Airports, Executive Terminals |
| Companies Covered | Minute Suites, MetroNaps, GoSleep, ZzzleepandGo, SnoozeCube, Sleepbox, YOTELAir, Sleep 'n Fly, Napcabs GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Sleeping Pods Market Strategic Shifts & Innovations
Software-defined service models are displacing hardware-centric ownership structures across airport sleeping pod operations, embedding dynamic pricing and predictive maintenance into core value propositions.
Heat-recovery ventilation technology is unifying climate control and energy efficiency in compact pod designs. European operators under EU Green Deal benchmarks adopt these systems fastest. The technology is unifying manufacturer R&D roadmaps around single-solution platforms rather than regional product variants.
REACH chemical compliance deadlines are eliminating halogenated flame retardants from interior composites. Manufacturers reformulate panel substrates to maintain aviation fire certifications. Economy pod segments face the steepest cost adjustment as they compete on material efficiency.
Airlines now bundle pod access into premium fare tiers rather than operating standalone booking channels. This disintermediates direct-to-consumer reservation platforms. The shift concentrates most visibly in North American hub carriers seeking loyalty program differentiation.
Airport Sleeping Pods Market Segmentation
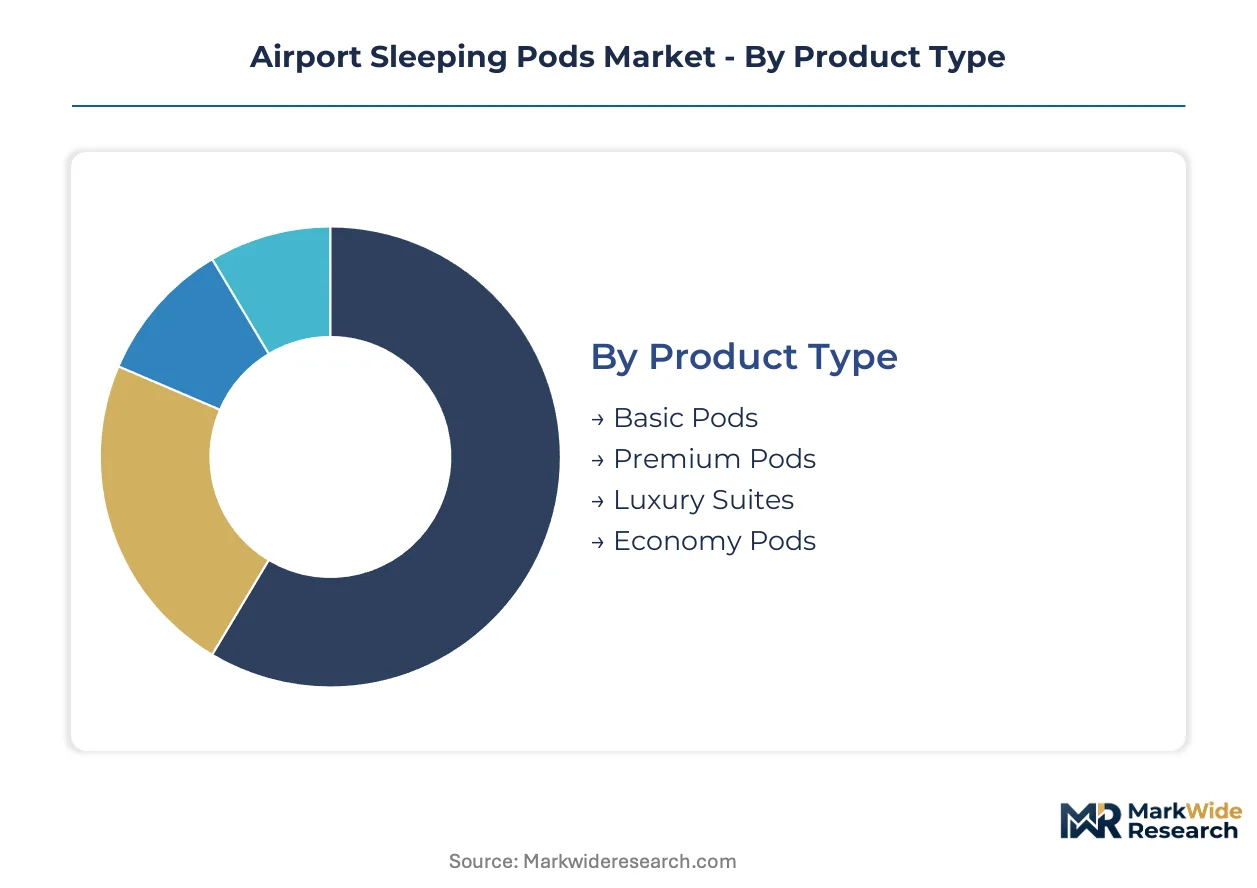
Airport sleeping pod segmentation reveals distinct technology-performance tiers that command different procurement budgets and operational footprints. Product architecture, deployment flexibility, and passenger dwell-time economics determine which configurations airports prioritize during terminal renovations.
Product Type:
Construction materials and climate-control sophistication separate the four product tiers, with fire-rated composites and HVAC efficiency serving as the primary specification axes.
- Premium Pods:These units integrate concierge service interfaces, adjustable lighting zones, and noise-dampening wall assemblies rated to 40dB. Demand concentrates in Dallas Fort Worth International and Hartsfield-Jackson Atlanta, where hub carriers bundle access into loyalty program tiers.
- Luxury Suites:Expansive 6-7 square meter footprints accommodate luggage storage, private wash facilities, and extended-stay pricing modules. International airports in the United States deploy these adjacent to flagship lounges to capture high-yield layover traffic.
- Basic Pods:Compact fold-flat designs optimize gate-area density with minimal power draw.
- Economy Pods:Standardized shell-and-bunk configurations target secondary airports seeking low-capex entry points.
Mature deployment sits with Luxury Suites. Newer deployment is concentrated in Economy Pods.
Deployment:
Capital commitment duration and relocation flexibility define operator preferences, with payback period sensitivity driving divergence between hub and secondary airport choices.
- Modular Systems:Rapid-reconfiguration architecture permits seasonal capacity shifts between single-occupancy and paired layouts without terminal reconstruction. European operators under EU Green Deal mandates favor these for heat-recovery HVAC compatibility and panel recyclability.
- Integrated Lounges:Permanent build-outs adjacent to premium passenger facilities capture the highest revenue per square meter. United States hub airports anchor the largest installed bases, validating hub-and-spoke deployment economics.
- Standalone Units:Plug-and-play electrical connections enable deployment in pre-2010 gate areas lacking utility capacity for full HVAC loads.
- On-Demand Rentals:Mobile pod fleets serve temporary demand surges during irregular operations.
Integrated Lounges dominate revenue concentration. Modular Systems are gaining share fastest as operators prioritize relocation flexibility across seasonal route shifts.
Use Case:
Dwell-time windows and price elasticity separate passenger segments, with layover duration determining willingness to pay for privacy and climate control.
- Transit Passengers:Passengers with 4-8 hour connections drive volume across major hubs. These travelers prioritize location convenience over amenity depth, accepting compact footprints for gate-proximate access.
- Long-Haul Travelers:Jet-lag recovery demand supports premium pricing for extended-stay configurations with horizontal sleeping surfaces and circadian lighting.
- Airport Staff:Shift workers and crew members utilize economy-tier pods during mandatory rest periods between duty cycles.
- Business Commuters:Same-day return travelers purchase short-duration privacy for video calls and document preparation.
Long-Haul Travelers established early adoption patterns. Transit Passengers now anchor volume expansion as hub connectivity increases.
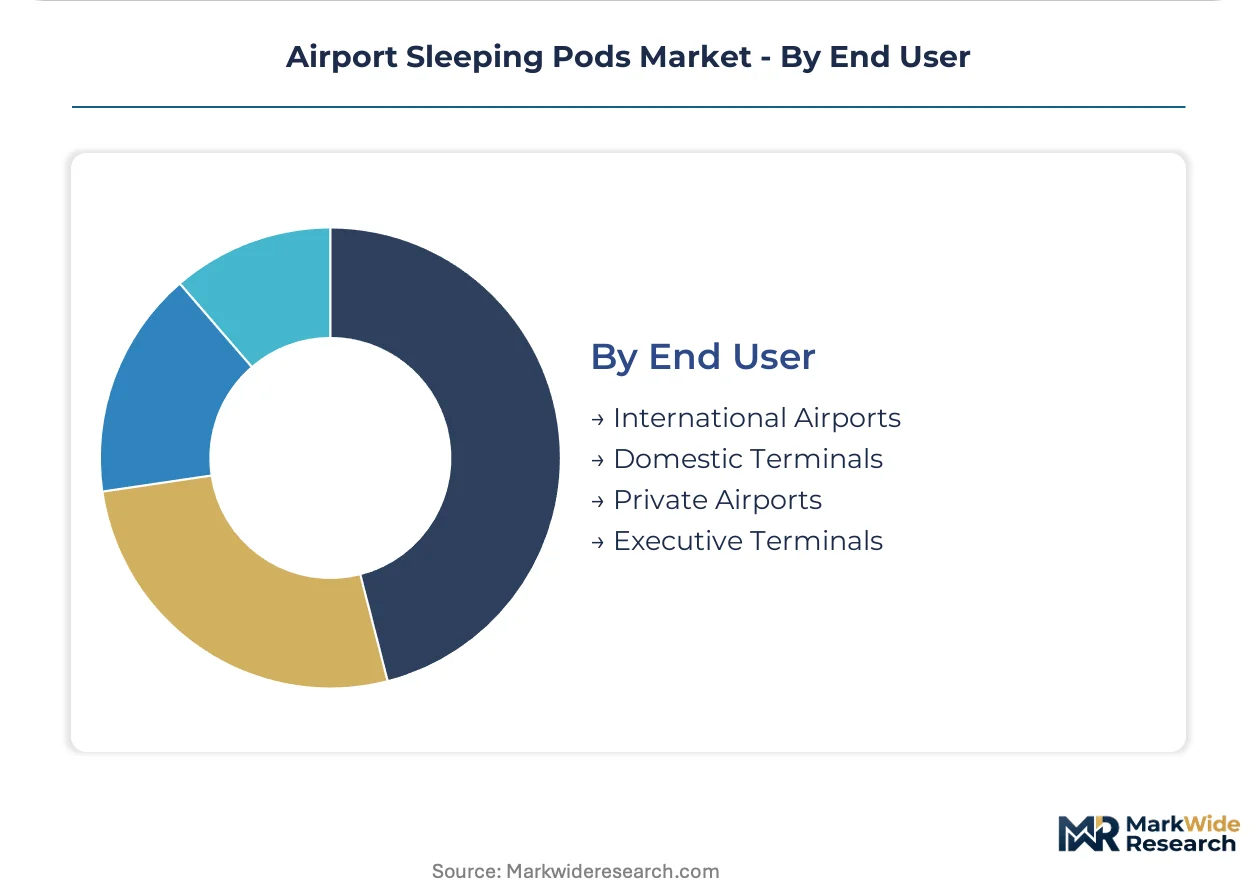
End User:
Procurement authority and capital allocation timelines vary sharply across airport ownership structures, with privatization status influencing technology upgrade cycles.
- International Airports:These facilities command the largest procurement budgets and longest planning horizons. FAA terminal design guidelines and OSHA indoor air quality standards shape ventilation and egress specifications for US-based installations.
- Domestic Terminals:Higher flight frequency and shorter average layovers compress pod utilization windows, favoring rapid-turnover economy configurations.
- Private Airports:Owner-operator structures enable faster procurement decisions without municipal approval cycles.
- Executive Terminals:Fixed-base operator control permits customized amenity packages for corporate aviation clients.
International Airports concentrate legacy installed base. Domestic Terminals represent the steepest expansion trajectory as secondary hubs add connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of fire-rated composites and HVAC systems concentrates in China and Germany, while pod deployment and service revenue concentrate in the United States and European hub airports. This production-consumption divide shapes trade flows and technology transfer patterns across the industry.
United States
Dallas Fort Worth International and Hartsfield-Jackson Atlanta anchor the largest installed pod bases worldwide, validating hub-and-spoke economics for transit passenger capture. FAA terminal design guidelines and OSHA indoor air quality standards govern ventilation and egress specifications, extending product development timelines by 8-14 months. Chicago O'Hare and Denver International are expanding modular installations to capture seasonal route shifts.
Germany
Frankfurt and Munich airports drive premium pod adoption under EU Green Deal energy mandates favoring heat-recovery HVAC systems. REACH chemical compliance deadlines eliminate halogenated flame retardants from interior composites, forcing panel substrate reformulation. Bavaria-based manufacturers supply recyclable composite panels to European hub operators.
China
Beijing Capital and Shanghai Pudong are deploying economy-tier pods for domestic transit growth, with MIIT standards guiding electrical safety certification. The country's dual carbon goals push manufacturers toward low-power climate systems. Yangtze River Delta fabricators dominate phenolic resin and aviation-grade laminate production for global supply.
United Arab Emirates
Dubai International anchors luxury suite deployment adjacent to flagship lounges, capturing high-yield layover traffic from long-haul connections. MOHAP and local aviation regulators coordinate fire-safety certifications with international standards. Abu Dhabi is expanding integrated lounge-adjacent installations for premium carrier partnerships.
India
Greenfield terminals under the country's airport privatization program lack legacy lounge infrastructure, creating first-mover installation potential in Mumbai and Delhi. BIS electrical safety standards and CEA power infrastructure guidelines shape procurement specifications. Maharashtra and Karnataka are seeing initial modular pod deployments in secondary city airports.
Airport Sleeping Pods Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the airport sleeping pod landscape. The market structures around three tiers: integrated lounge operators with permanent real estate, modular system specialists prioritizing relocation flexibility, and economy pod fabricators competing on material efficiency. Strategic moves concentrate on M&A for reservation platform control and capacity expansion into secondary airport channels.
Among North American reservation-platform operators, Minute Suites and GoSleep exemplify divergent archetypes—one controlling premium lounge-adjacent real estate through proprietary booking systems, the other optimizing compact fold-flat designs for dense gate-area deployment. Sleepbox represents the modular architecture specialists, its rapid-reconfiguration systems permitting seasonal capacity shifts without terminal reconstruction. These three anchors illustrate how software-defined service models, hardware miniaturization, and deployment flexibility are separating winners from commodity competitors.
| Leading Market Players |
|---|
| Minute Suites |
| MetroNaps |
| GoSleep |
| ZzzleepandGo |
| SnoozeCube |
| Sleepbox |
| YOTELAir |
| Sleep 'n Fly |
| Napcabs GmbH |
| Others |
Cost & Logistics Intelligence
Hub airport procurement committees concentrate buying power for premium pod installations, forcing manufacturers toward contract-based long-term offtake agreements that lock in volume commitments against certification-grade pricing tiers. This buyer concentration enables three-tier pricing structure across premium, standard, and economy levels, with EU Green Deal compliance costs passed through to European operators.
Pricing Analysis
Margin tightening in economy pods reflects REACH chemical compliance deadlines eliminating halogenated flame retardants, forcing panel substrate reformulation that erodes material efficiency advantages. Price differentiation hinges on fire certification tier—aviation-grade phenolic resins command premiums over industrial laminates—and after-sales service bundling including ventilation system audits. Pricing pressure intensifies in basic pod segments as secondary airports in India and China negotiate low-capex entry points. Transit passengers demonstrate lowest price sensitivity, prioritizing gate-proximate location over amenity depth, while airport staff utilization drives volume at compressed rates.
Supply Chain Analysis
Freight cost volatility from Asian chemical processors exposes manufacturers to margin compression, as specialized phenolic resins and aviation-grade laminates draw from concentrated Yangtze River Delta production. Raw material dependencies center on fire-rated composite substrates, heat-recovery HVAC components, and biometric access hardware. Supply chain risk manifests in single-source vulnerability for FAA-certified electrical assemblies, constraining deployment velocity during hub expansion windows. Distribution runs through direct airport authority contracts and airline partnership channels, with reservation platform operators controlling premium lounge-adjacent real estate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation-certified electrician scarcity props pricing for installation services, creating supply-constrained conditions that favor incumbent capacity holders and extend payback periods for new market entrants.
For Market Incumbents: Deepen backward integration into phenolic resin and composite panel production to offset Asian chemical processor concentration risk. Secure captive supply of fire-rated laminates before REACH compliance deadlines force reformulation cost spikes. Expand modular system manufacturing footprint in Germany to capture EU Green Deal procurement preference for heat-recovery HVAC compatibility. For New Entrants and Emerging Players: Launch via on-demand rental fleets serving irregular operations at secondary airports lacking utility capacity for permanent installations. Target greenfield terminals in India's privatization program where legacy lounge infrastructure gaps create first-mover potential. Pursue biometric access convergence partnerships with airline passenger data streams to eliminate check-in friction. For Investors and Strategic Acquirers: The window for entry favors reservation platform operators with proprietary booking systems controlling premium real estate. Long-term viability rests on software-defined service models converting capital expenditure into recurring revenue. Watch for airline bundling announcements disintermediating direct-to-consumer channels as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Manufacturing | Captive supply of fire-rated panels insulates against REACH reformulation cost spikes and Asian processor concentration. |
| Biometric Access Platform Development | Facial recognition entry systems integrated with airline passenger data eliminate check-in friction and enable seamless billing. |
| Modular System Manufacturing Expansion | Rapid-reconfiguration architecture permits seasonal capacity shifts without terminal reconstruction, capturing EU Green Deal preference. |
| Reservation Platform Acquisition | Proprietary booking systems control premium lounge-adjacent real estate and convert fixed capital into recurring service income. |
| Concierge Service Module Unbundling | Wake-up calls, meal delivery, and flight monitoring as separately priced modules expand margin pools beyond base rental rates. |
Research Approach
Document review covered FAA terminal design guidelines, EU Green Deal energy mandates, REACH chemical compliance frameworks, and OSHA indoor air quality standards, complemented by interviews with airport procurement directors, pod manufacturer R&D heads, airline loyalty program executives, and aviation-certified installation contractors. Secondary validation drew from customs trade data, SEC filings of listed airport service providers, and aviation authority certification databases. Bottom-up pod deployment counts across Dallas Fort Worth International, Hartsfield-Jackson Atlanta, Frankfurt, and Dubai International were triangulated against top-down market sizing from terminal renovation expenditure tracking.
Installed base projections and revenue forecasts across the analysis window were generated through segmentation modeling by product tier, deployment architecture, and passenger use case. CAGRs were derived from hub connectivity growth trajectories, seasonal route shift patterns, and secondary airport privatization timelines. Industry-specific inputs included transit passenger volume concentration at major hubs, EU Green Deal implementation schedules, and fire-safety certification processing durations.
Regulatory timeline acceleration, composite input cost volatility, and airline partnership consolidation are the dominant revision risks that could compress or extend forecast outputs. Stakeholders should weight assumptions against their own operating context and procurement authority structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Europe Camping and Caravanning Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
India Online Accommodation Market
Accommodation
UAE Hospitality Market
Accommodation
Capsule Hotels Market
Accommodation
United States Online Accommodation Market
Accommodation
Sweden Hospitality Market
Accommodation
Underwater Hotels Market
Accommodation
France Online Accommodation Market
Accommodation
Europe Student Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Youth Summer Camp Market
Accommodation
India Student Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Russia Online Accommodation Market