
 China Tourism and Hotel Market | 2026-2036
China Tourism and Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
China Tourism and Hotel Market Insights
Asset-light franchising and management-contract expansion is reshaping capital deployment across China's hotel sector, lowering barriers for regional operators to scale room inventory without property ownership. Jin Jiang International leverages its state-backed heritage to anchor premium positioning in gateway cities. Huazhu Group sustains mid-tier dominance through standardized smart-room rollouts. Atour Lifestyle Holdings differentiates via lifestyle-brand segmentation targeting young professionals.
China tourism and hotel services encompass accommodation provisioning, travel intermediation, and experience curation across branded properties, alternative lodging, and digital booking infrastructure, with operational parameters governed by star-rating classifications, fire-safety GB standards, and public-security registration protocols. The primary commercial purpose centers on monetizing temporary lodging and ancillary services to domestic and inbound travelers. Luxury hotels command outsized margin pools in Beijing and Shanghai, while budget properties dominate room-count expansion in inland provinces. Online travel agencies capture disproportionate booking-value share as mobile-app penetration deepens among leisure travelers. Boutique hotels represent the fastest-growing service-type segment as experiential positioning displaces conventional amenity competition.
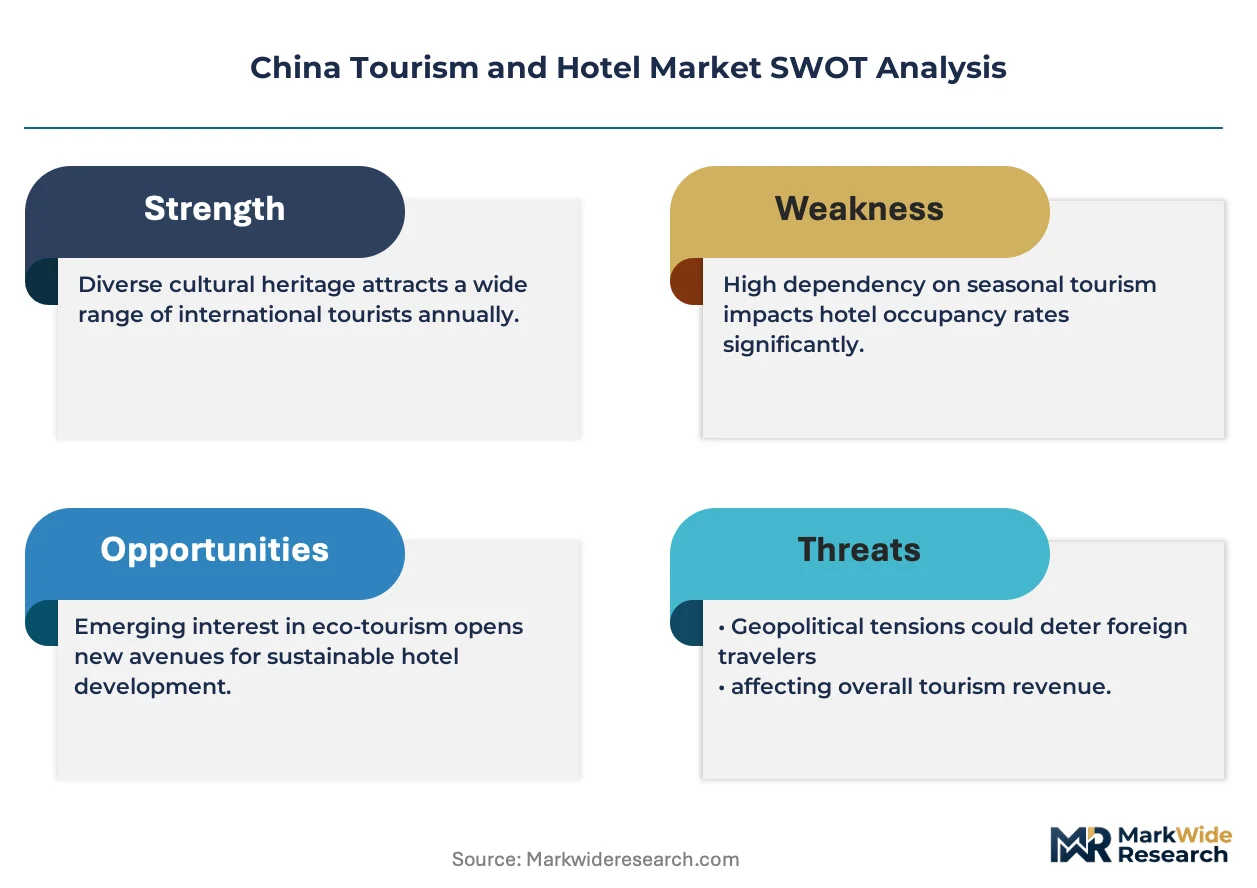
SAMR enforces consumer-protection and pricing-transparency rules across digital booking channels, while MEE implements dual carbon goals that mandate energy-efficiency retrofits in hospitality assets. GB standards for fire safety and public health shape property-design specifications and operating-license eligibility. Stakeholders must monitor regulatory calibration between tourism stimulus and sustainability enforcement to anticipate capital-commitment timing.
Market Dynamics
Dual carbon goals under MEE oversight are forcing hotel operators into energy-efficiency retrofits, while asset-light franchising collapses traditional capital barriers for regional scaling.
Growth Catalysts
- Domestic leisure travel from tier-two city households:Rising disposable incomes in inland provinces are creating sustained demand for mid-tier accommodation outside traditional gateway markets.
- MEE dual carbon mandates:Energy-efficiency retrofit requirements are accelerating property modernization and unlocking green financing channels for compliant operators.
- Smart-room technology deployment:IoT-enabled guestroom automation is reducing labor costs and enabling dynamic pricing capabilities across mid-scale portfolios.
Market Restraints
- Labor cost escalation in coastal provinces:Frontline hospitality wages in Shanghai and Guangdong are compressing operating margins for full-service properties.
- Supply concentration in Greater Bay Area construction:Hotel development materials and specialized contractors cluster disproportionately in Guangdong, creating bottlenecks for inland projects.
- Technical limitations in legacy property retrofit:Pre-2010 building stock faces structural constraints implementing MEE-mandated HVAC and envelope upgrades.
Strategic Opportunities
- Underpenetrated cultural tourism corridors:Silk Road heritage destinations in Gansu and Xinjiang offer first-mover positioning for experiential lodging concepts.
- SAMR digital pricing transparency rules:Regulatory clarity on online travel agency commission structures is creating direct-booking incentives for branded properties.
- Convergence of wellness programming and accommodation:Integration of traditional Chinese medicine services with hotel operations is opening premium rate positioning in tier-one recovery markets.
Industry Challenges
- Certification timeline compression for GB fire-safety compliance:Local fire bureau inspection backlogs are delaying opening schedules for new properties in high-growth provinces.
- Integration complexity with legacy property management systems:Mid-tier operators struggle to unify fragmented technology stacks across acquired or franchised assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Tourism and Hotel Market |
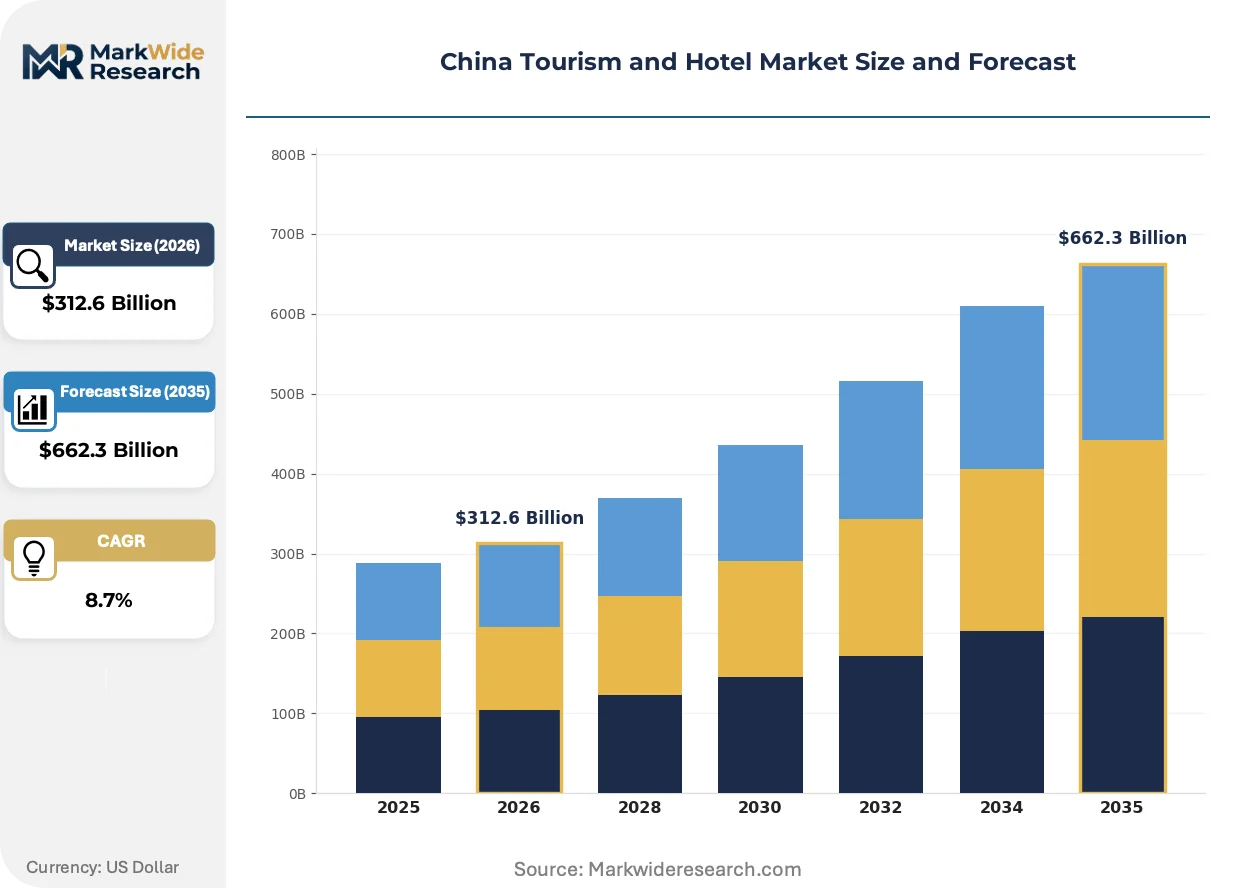
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Hotels, Budget Hotels, Boutique Hotels, Vacation Rentals Customer Type: Business Travelers, Leisure Travelers, Family Groups, Solo Travelers Booking Channel: Online Travel Agencies, Direct Booking, Mobile Apps, Travel Agents Experience Type: Cultural Tours, Adventure Activities, Culinary Experiences, Wellness Retreats |
| Companies Covered | BTG Hotels, Dossen International, Jin Jiang International, Plateno Group, Atour Lifestyle Holdings, Huazhu Group, GreenTree Hospitality, Trip.com (Ctrip), H World Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Tourism and Hotel Market Trends and Innovations
Technology deployment and regulatory calibration are compressing traditional operational models while redirecting capital toward experiential and sustainable positioning.
Facial recognition check-in systems integrated with public-security registration protocols are collapsing front-desk staffing requirements at mid-scale properties. Huazhu Group and regional chains are deploying these systems across tier-two city portfolios. The technology is collapsing the traditional trade-off between security compliance and labor efficiency.
GB standards for fire safety and public health are tightening enforcement timelines under SAMR coordination with provincial tourism bureaus. Properties must now complete multi-system upgrades before license renewal. Full-service hotels in Beijing and Shanghai face the steepest compliance costs and shortest implementation windows.
Young professionals are prioritizing lifestyle-brand differentiation over conventional star-rating hierarchies when selecting accommodation. Atour Lifestyle Holdings and comparable positioned operators are capturing this segment through co-working integrations and localized design programming. This behavioral pivot is most visible in Shenzhen and Hangzhou technology corridor demand patterns.
China Tourism and Hotel Market Segmentation
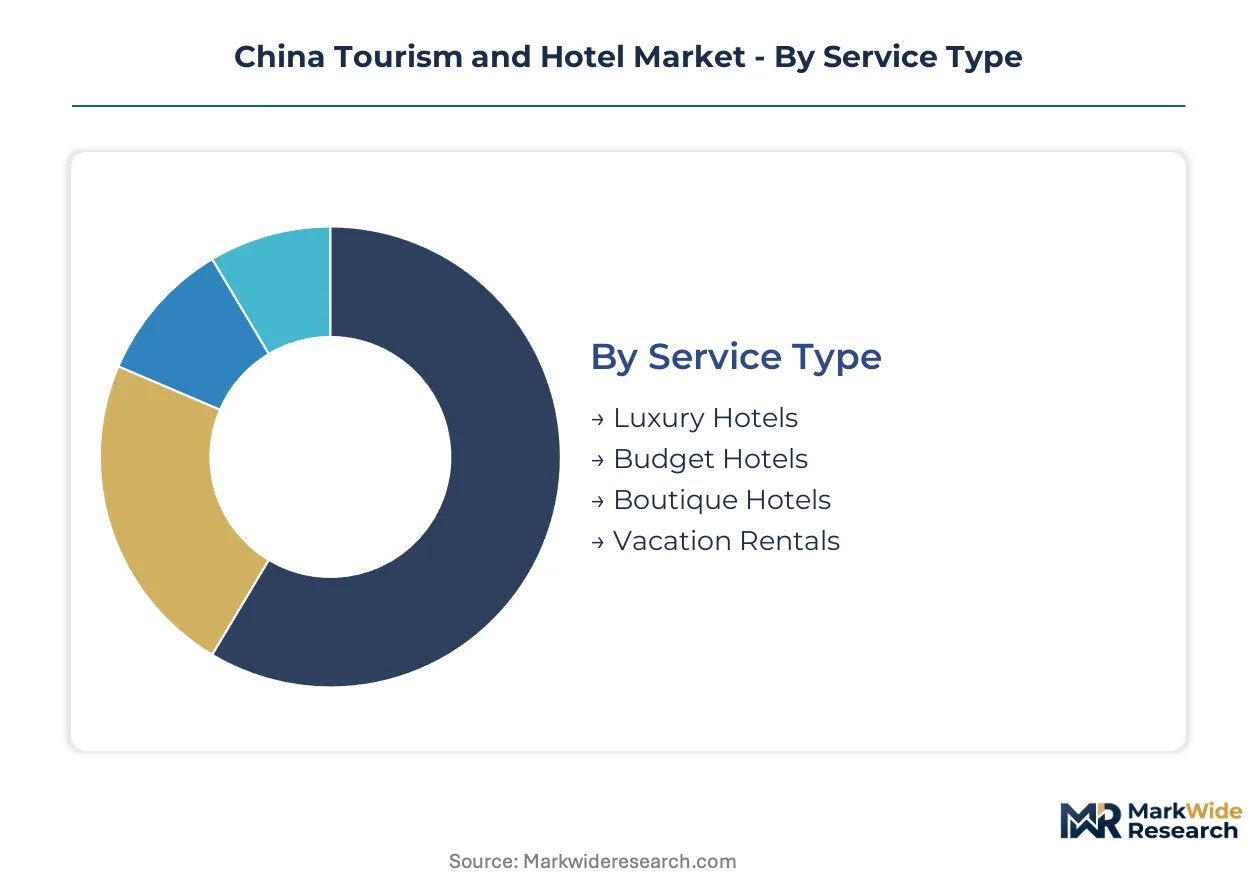
China's tourism and hotel market fragments across four distinct category axes that shape capital allocation and operational strategy. Service type and customer type determine property positioning and amenity investment, while booking channel and experience type govern distribution economics and rate architecture.
Service Type:
Use-case spectrum spans state protocol accommodation to backpacker hostels, with each tier demanding differentiated asset intensity and labor models.
- Luxury Hotels:Full-service properties with concierge, spa, and fine-dining infrastructure targeting premium rate realization in Beijing and Shanghai gateway markets. MEE dual carbon mandates are forcing HVAC retrofits that compress margins for pre-2010 assets in these high-cost jurisdictions.
- Boutique Hotels:Design-forward properties under 150 rooms emphasizing localized aesthetics and experiential programming over standardized amenities. Demand concentrates in Shenzhen and Hangzhou technology corridors where young professionals prioritize lifestyle differentiation over star ratings.
- Budget Hotels:Limited-service properties with stripped amenity sets and centralized back-office functions enabling volume-driven economics. Huazhu Group's standardized smart-room rollouts dominate this tier across tier-two city expansion corridors.
- Vacation Rentals:Alternative lodging inventory ranging from serviced apartments to short-term residential lets, regulated under SAMR consumer-protection frameworks for digital booking transparency.
The dominant share belongs to Budget Hotels, while Boutique Hotels is closing the gap fastest.
Customer Type:
Cost tier stratification separates corporate account negotiation from discretionary leisure spend patterns.
- Leisure Travelers:Discretionary demand from tier-two city households with rising disposable incomes, driving mid-tier property expansion in inland provinces beyond traditional gateway markets. Domestic leisure travel from these geographies forms the core demand pillar for new room inventory deployment.
- Business Travelers:Corporate account demand concentrated in Greater Bay Area manufacturing and technology headquarters, with negotiated rate structures and loyalty program dependencies. Labor cost escalation in Guangdong and Shanghai is compressing operating margins for full-service properties serving this segment.
- Family Groups:Multi-generational travel parties requiring connecting rooms, child amenities, and proximity to cultural attractions. Demand clusters around Silk Road heritage destinations where experiential lodging concepts remain underpenetrated.
- Solo Travelers:Individual mobility driven by young professional demographics seeking social programming and co-working integrations in urban lifestyle properties.
Leisure Travelers commands the dominant share, with Business Travelers recovering most rapidly in tier-one corporate corridors.
Booking Channel:
Volume concentration in mobile-first distribution is redirecting commission economics and direct-booking investment priorities.
- Online Travel Agencies:Platform intermediaries capturing disproportionate booking-value share through mobile-app penetration among leisure travelers. SAMR pricing-transparency rules are recalibrating commission structures and creating direct-booking incentives for branded properties.
- Mobile Apps:Native application interfaces enabling push-notification pricing and loyalty-program integration, with facial recognition check-in collapsing front-desk staffing requirements at mid-scale properties.
- Direct Booking:Proprietary channel strategies leveraging brand equity to bypass platform commissions, most developed among Jin Jiang International's premium gateway city portfolio.
- Travel Agents:Traditional intermediaries retaining relevance for corporate account management and inbound international group coordination.
Online Travel Agencies retains dominant share, though Mobile Apps is climbing the fastest as IoT-enabled property management deepens platform integration.
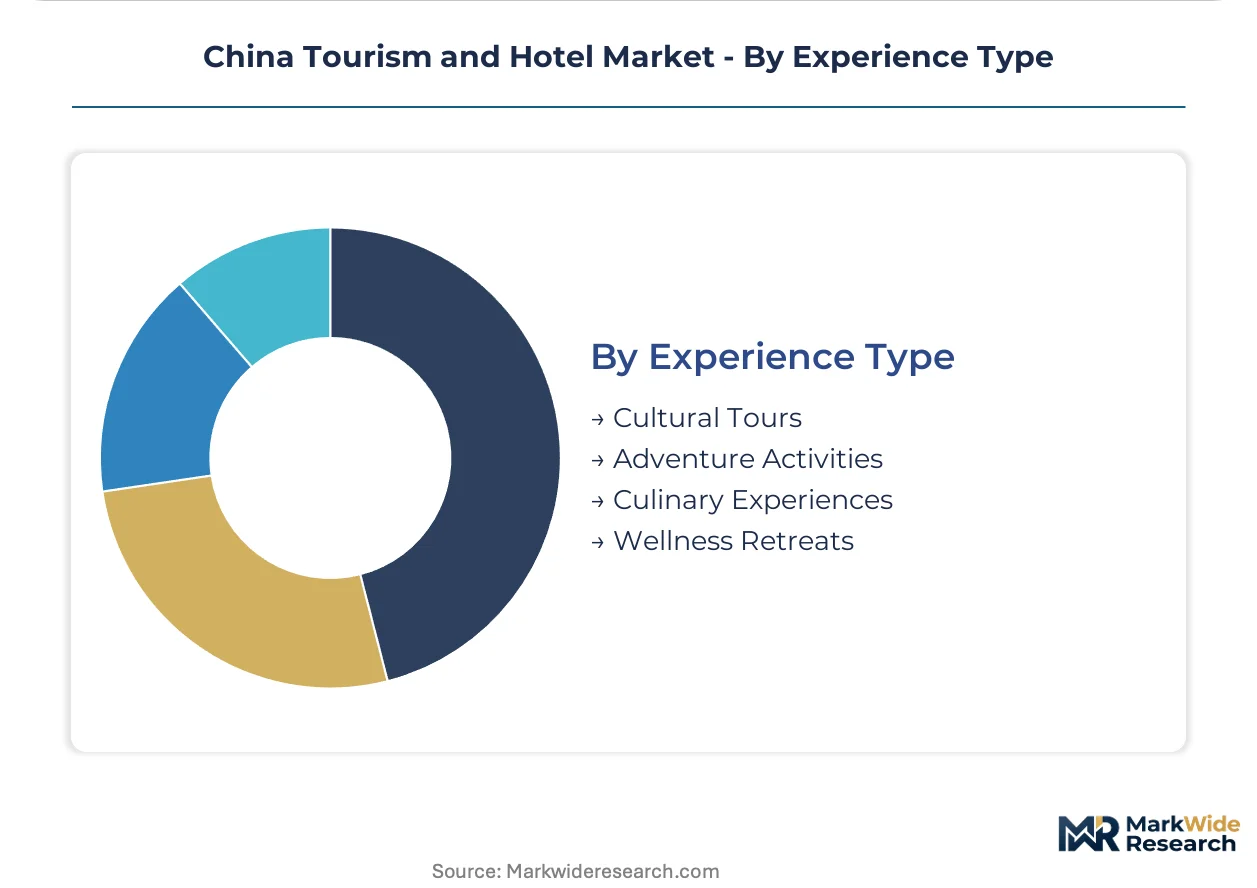
Experience Type:
Margin tier separation between high-touch programming and self-directed activity selection.
- Cultural Tours:Heritage-site programming and guided interpretation services integrated with accommodation packages. Demand concentrates in Gansu and Xinjiang Silk Road corridors where first-mover experiential lodging concepts face limited competition.
- Wellness Retreats:Traditional Chinese medicine services converging with hotel operations to open premium rate positioning in tier-one recovery markets. Integration of TCM diagnostics and treatment protocols is differentiating properties in Beijing and Shanghai.
- Culinary Experiences:Destination dining and cooking-class programming leveraging regional cuisine differentiation, particularly in Guangdong's Greater Bay Area cluster.
- Adventure Activities:Outdoor recreation packaging from hiking to water sports, concentrated in southwestern provinces with natural asset endowments.
Cultural Tours holds dominant share, while Wellness Retreats is gaining share fastest through convergence with premium accommodation positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial tourism stimulus programs and MEE carbon retrofit mandates are redirecting hotel investment toward tier-two city corridors and heritage destination clusters. Regional performance diverges sharply between saturated gateway markets and emerging inland leisure corridors.
Guangdong Province
Greater Bay Area integration drives cross-border leisure demand between Guangzhou, Shenzhen, Hong Kong, and Macau. SAMR pricing-transparency enforcement targets online travel agency commission structures in this corridor. Hotel development materials and specialized contractors concentrate disproportionately in Guangdong, creating supply bottlenecks for projects elsewhere.
Beijing-Tianjin-Hebei
State protocol accommodation demand and MICE activity anchor luxury property performance in the capital cluster. GB fire-safety compliance timelines compress under coordinated SAMR and provincial tourism bureau enforcement. Full-service hotels face steepest retrofit costs and shortest implementation windows for MEE-mandated HVAC upgrades.
Yangtze River Delta
Shanghai's financial services sector and Hangzhou's technology corridor generate sustained business travel demand. Labor cost escalation in frontline hospitality roles compresses operating margins for full-service properties. Smart-room technology deployment accelerates across mid-scale portfolios as IoT-enabled automation reduces staffing requirements.
Sichuan-Chongqing
Domestic leisure travel from rising disposable-income households drives mid-tier property expansion in this western hub. Provincial tourism bureaus coordinate with SAMR on consumer-protection rule implementation for digital booking channels. Chengdu anchors experiential lodging concept trials targeting young professional demographics.
Gansu and Xinjiang
Silk Road heritage destinations offer first-mover positioning for cultural tourism corridor development. Local fire bureau inspection backlogs delay opening schedules for new properties in these high-growth provinces. Boutique operators target underpenetrated experiential lodging gaps where conventional amenity competition remains limited.
China Tourism and Hotel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. State-backed heritage groups anchor premium positioning in gateway cities while asset-light franchisors scale room inventory without property ownership. Two strategic archetypes dominate: vertically integrated hospitality conglomerates and technology-enabled platform operators. Competitive moves concentrate on management-contract expansion and smart-room technology licensing.
Among state-affiliated hospitality groups, Jin Jiang International occupies a position exemplifying premium gateway-city anchoring. Huazhu Group and Atour Lifestyle Holdings represent contrasting archetypes within the mid-tier and lifestyle-brand vectors respectively. These three entities illustrate the spectrum from heritage-backed consolidation to experiential differentiation targeting young professional demographics.
| Leading Market Players |
|---|
| BTG Hotels |
| Dossen International |
| Jin Jiang International |
| Plateno Group |
| Atour Lifestyle Holdings |
| Huazhu Group |
| GreenTree Hospitality |
| Trip.com (Ctrip) |
| H World Group |
| Others |
Pricing and Supply Chain Analysis
MEE dual carbon retrofit mandates operating as a regulatory chokepoint determine both pricing tier spreads and supply chain shape across China's hotel sector, forcing capital allocation toward compliant suppliers while compressing margins for legacy assets unable to absorb green technology premiums.
Pricing Analysis
Star-rating classification creates the primary spread between luxury full-service properties and limited-service budget tiers, with MEE-mandated HVAC and envelope upgrades adding a secondary green-certification premium that operators in Beijing and Shanghai struggle to pass through to rate-sensitive corporate accounts. Pricing pressure stems from labor cost escalation in Guangdong and Shanghai frontline hospitality roles, compressing operating margins for full-service properties serving business travelers. Leisure travelers from tier-two city households demonstrate highest price sensitivity, while wellness-integrated lifestyle properties targeting young professionals in Shenzhen and Hangzhou command lowest elasticity.
Supply Chain Analysis
Hotel development materials and specialized contractors concentrate disproportionately in Guangdong Province, creating geographic dependency for projects across Gansu, Xinjiang, and Sichuan-Chongqing corridors where inland construction faces procurement bottlenecks. Smart-room IoT components and energy-efficient HVAC systems feed from manufacturing clusters in the Yangtze River Delta, while fire-safety GB standard certification equipment sources from Beijing-Tianjin-Hebei industrial bases. Single-source vulnerability concentrates in Greater Bay Area contractor networks for specialized MEE-compliant retrofit work. Distribution runs through provincial tourism bureau licensing channels that gate property opening timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's tourism and hotel market represents a high-growth disruption as facial recognition check-in systems collapse traditional front-desk staffing models and MEE carbon mandates force asset obsolescence cycles faster than historical replacement rates.
For Market Incumbents: Pre-empt margin compression from labor cost escalation by accelerating smart-room technology deployment across tier-two city portfolios before regional competitors achieve scale. Consolidate management-contract pipelines in underpenetrated Silk Road heritage corridors to anchor first-mover positioning against lifestyle-brand entrants targeting young professionals.
For New Entrants and Emerging Players: Pursue experiential lodging concept development in Gansu and Xinjiang cultural tourism corridors where conventional amenity competition remains limited and local fire bureau inspection backlogs delay incumbent property openings. Target direct-booking channel investment to capture SAMR-mandated commission transparency benefits as online travel agency pricing rules recalibrate distribution economics.
For Investors and Strategic Acquirers: Asset-light franchising platforms with proven management-contract scalability in tier-two expansion corridors offer the strongest long-term viability framing through the next property cycle. Monitor MEE enforcement timeline compression as the critical signal for capital-commitment timing, with HVAC retrofit deadline acceleration indicating distressed acquisition opportunities in pre-2010 Beijing and Shanghai luxury assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Room Technology Licensing | Huazhu Group's standardized IoT rollouts reduce labor costs and enable dynamic pricing across mid-scale portfolios. |
| Management-Contract Expansion | Jin Jiang International leverages state-backed heritage to anchor premium positioning without property ownership capital. |
| Green Financing Channel Access | MEE-compliant operators unlock preferential capital for energy-efficiency retrofits mandated under dual carbon goals. |
| Direct-Booking Platform Investment | SAMR pricing-transparency rules create commission savings for branded properties bypassing online travel agencies. |
| Experiential Lodging Concept Development | Atour Lifestyle Holdings captures young professional demand through co-working integrations in technology corridors. |
Research Methodology
A spread of perspectives from hotel operations executives, provincial tourism bureau officials, property development contractors, and online travel agency platform managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SAMR regulatory filings, MEE enforcement circulars, GB standards documentation, and provincial tourism stimulus program disclosures. Bottom-up property inventory counts and top-down macroeconomic demand indicators were triangulated to anchor segmentation splits.
Demand-supply balance dynamics across the projection horizon were modeled through price elasticity estimates for leisure versus business traveler segments, retrofit cost absorption curves for pre-2010 building stock, and smart-room technology deployment penetration rates. Segmentation dimensions included service type, customer type, booking channel, and experience type, with regional regulatory framework heterogeneity treated as a cross-cutting analytical layer. CAGRs were derived from trend extrapolation of room inventory expansion patterns and average daily rate movements, calibrated against disposable income growth projections for tier-two city households.
Sensitivities concentrate around MEE enforcement timeline acceleration, SAMR digital pricing rule implementation delays, and Greater Bay Area construction material cost volatility. Cross-checking against provincial tourism bureau investment pipeline disclosures and hospitality sector green financing uptake metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
France Casino Tourism Market
Accommodation
India Student Accommodation Market
Accommodation
Russia Online Accommodation Market
Accommodation
India Online Accommodation Market
Accommodation
Hotel Market
Accommodation
Croatia Hospitality Market
Accommodation
Movie Theaters Market
Accommodation
Europe Online Accommodation Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Sweden Hospitality Market
Accommodation
Europe Student Accommodation Market
Accommodation
France Online Accommodation Market
Accommodation
Hostel Market
Accommodation
Glamping Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
Austria Hospitality Market