
 Airport Lounges Market | 2026-2036
Airport Lounges Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Lounges Market Outlook
The EU Green Deal is restructuring carbon accounting expectations for airport infrastructure operators, forcing lounge providers to retrofit existing spaces with energy-efficient HVAC and low-emission catering supply chains. Plaza Premium Group leverages its independent lounge network to anchor presence in high-traffic Asian and Middle Eastern hubs where airline consolidation has reduced proprietary lounge counts. American Express Centurion Lounges differentiates through captive F&B programming and interior design investments that sustain premium pricing power against membership competitors. DreamFolks competes as a technology aggregator, connecting regional lounge operators to bank-issued card programs across India and Southeast Asia.
An airport lounge constitutes a commercially operated waiting facility located beyond security checkpoints, typically offering seating density below 1.5 passengers per square meter, climate-controlled environments, and hospitality services calibrated to dwell times exceeding ninety minutes. These spaces function as revenue generators through direct membership fees, airline subsidies, or credit card issuer reimbursements, while simultaneously reducing gate-area congestion and improving passenger satisfaction metrics for host airports. Airline Lounges retain the largest share of dedicated floor space globally, though Independent Lounges are expanding fastest where airport privatization has opened concession tenders to non-carrier operators. Business Travelers generate the highest per-visit ancillary spend on premium food and spa services, while Pay-Per-Use access methods are capturing price-sensitive segments that traditional annual memberships excluded.
The Federal Aviation Administration maintains operational safety standards for lounge construction within sterile airport areas, while the European Union Aviation Safety Agency coordinates fire suppression and evacuation protocols across member state facilities. China's Civil Aviation Administration implements capacity quotas that restrict lounge expansion at congested tier-one airports, directly constraining supply growth in Beijing and Shanghai. India's Directorate General of Civil Aviation has issued revised aerodrome licensing requirements affecting lounge operator eligibility at privatized terminals. Stakeholders must monitor evolving biometric data governance from national privacy regulators as facial recognition entry systems proliferate across lounge networks.
Market Dynamics
Biometric boarding systems are compressing dwell times and forcing lounge operators to monetize shorter windows through frictionless entry and predictive service allocation rather than traditional ninety-minute hospitality cycles.
Growth Catalysts
- Premium Credit Card Penetration:Bank-issued card programs in the United States and United Arab Emirates now bundle lounge access as a standard retention mechanism, expanding the addressable passenger base beyond frequent flyers.
- EU Green Deal Compliance:Carbon accounting mandates are retrofitting existing lounge infrastructure with energy-efficient HVAC and low-emission catering supply chains, creating upgrade-driven construction activity.
- Airport Privatization:Concession tenders at privatized terminals in India and Southeast Asia are opening proprietary airline lounge spaces to independent operators, accelerating network expansion.
Market Restraints
- Capacity Quotas:China's Civil Aviation Administration restricts lounge expansion at congested tier-one airports, directly constraining supply growth in Beijing and Shanghai.
- Real Estate Cost Escalation:Sterile-area construction premiums at super-connector hubs inflate per-square-meter buildout costs beyond independent operator viability thresholds.
- Biometric Data Governance:National privacy regulators in the European Union and India are imposing consent and retention protocols that complicate facial recognition entry system deployment.
Strategic Opportunities
- Pay-Per-Use Penetration:Price-sensitive passenger segments excluded from annual memberships represent untapped volume in secondary Indian and Southeast Asian airports.
- Spa and Wellness Integration:Ancillary service unbundling is capturing business traveler willingness to pay for premium food and wellness treatments beyond base access fees.
- Digital Credential Convergence:Mobile wallet integration with airline apps and bank platforms is eliminating physical card friction and enabling impulse access purchases.
Industry Challenges
- Legacy System Integration:Biometric entry systems must interface with heterogeneous airport security infrastructure, creating deployment delays and interoperability failures.
- Skilled Hospitality Labor Scarcity:Premium F&B programming and personalized service delivery require trained staff that congested aviation labor markets cannot supply at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Lounges Market |
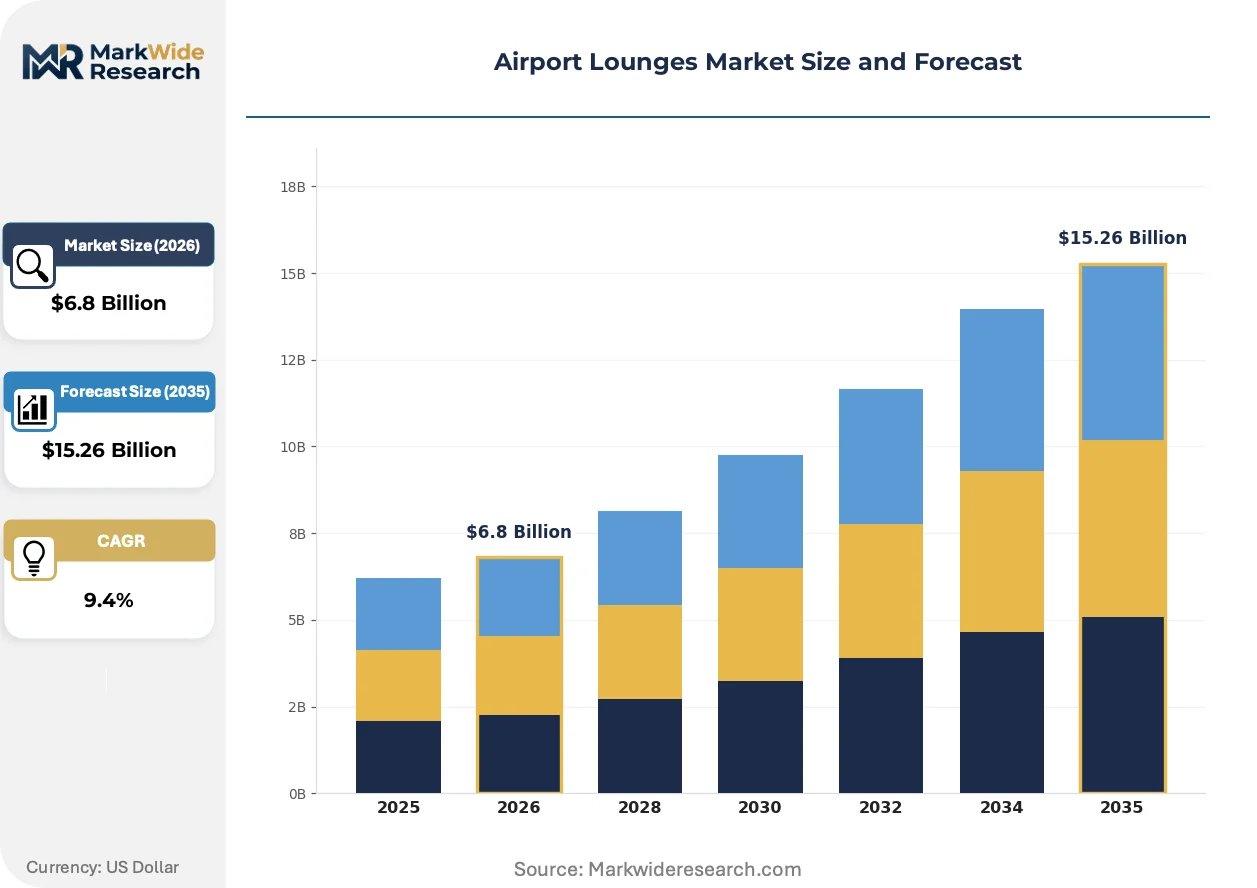
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Priority Pass, LoungeKey, Airline Lounges, Independent Lounges Customer Type: Frequent Flyers, Business Travelers, Families, Tourists Access Method: Membership, Pay-Per-Use, Airline Ticket, Package Deals Amenities Offered: Food & Beverage, Wi-Fi, Showers, Sleeping Pods |
| Companies Covered | Plaza Premium Group, United Airlines, American Airlines, Delta Air Lines, Qantas Airways Limited, Cathay Pacific Airways Limited, Lufthansa, American Express Centurion Lounges, DreamFolks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Lounges Market Strategic Shifts
Digital access credentials and predictive analytics are compressing the traditional lounge business model from extended dwell hospitality toward transactional, data-optimized service delivery.
Facial recognition entry systems are converging with mobile credentialing platforms to eliminate physical card presentation and queue formation at lounge reception desks. Major hub airports in the United States and United Arab Emirates are deploying these systems at scale. The technology is converging with dynamic capacity management algorithms that adjust staffing and food preparation based on real-time flight delay data.
The EU Green Deal is mandating embodied carbon disclosures for airport infrastructure renovations, forcing lounge operators to document supply chain emissions from catering through furniture procurement. The European Union Aviation Safety Agency is coordinating fire suppression retrofit standards that affect lounge layout flexibility. Independent operators in Frankfurt and Amsterdam are responding by sourcing regional food suppliers to reduce transport emissions and meet disclosure thresholds.
Business travelers are fragmenting their loyalty across multiple card programs rather than consolidating with single airline status, creating demand for aggregator platforms that unify access credentials. This pattern is displacing proprietary airline membership as the dominant access channel. The shift is most visible in India, where DreamFolks and competing aggregators are connecting regional lounge networks to bank-issued card portfolios.
Airport Lounges Market Segmentation
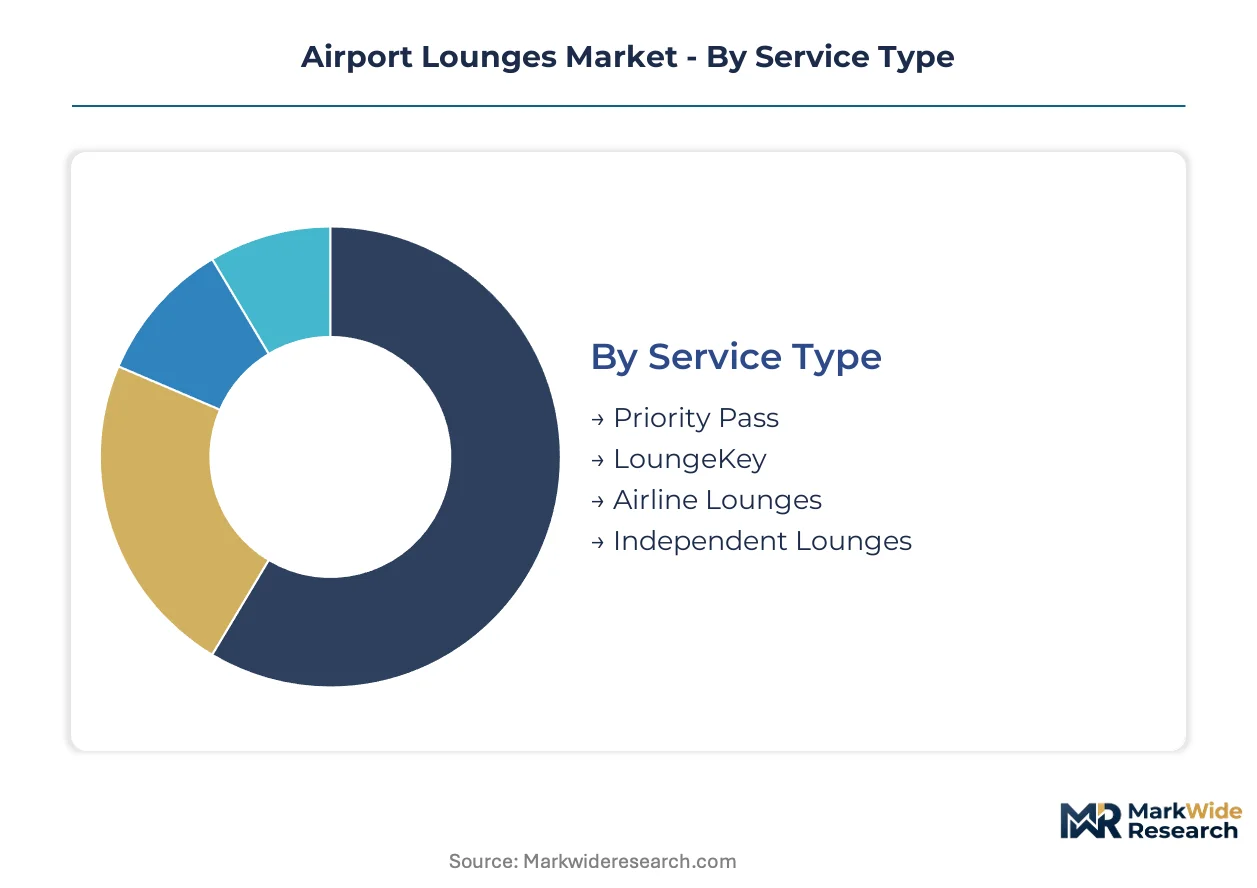
Airport lounge operators calibrate service tiers to distinct passenger profiles, access economics, and dwell-time requirements. Segmentation determines capital allocation across biometric entry systems, F&B programming, and real estate commitments at congested hubs.
Service Type:
Lounge network expansion cycles through retrofitting legacy airline-owned spaces and greenfield independent builds as airport privatization accelerates concession turnover.
- Airline Lounges:Proprietary facilities operated by legacy carriers with dedicated floor space exceeding 500 square meters at super-connector hubs. United States and United Arab Emirates anchor demand as American Express and major carriers defend retention through captive lounge investments.
- Independent Lounges:Third-party operators bidding on concession tenders at privatized terminals, typically occupying 200-400 square meter footprints with flexible branding. India and Southeast Asia concentrate expansion where airline consolidation has reduced proprietary lounge counts.
- Priority Pass:Aggregator network granting access to multiple independent and airline-affiliated locations through single membership credentials.
- LoungeKey:Bank-issued card partnership program enabling complimentary entry at partner facilities across high-traffic Asian and Middle Eastern hubs.
Airline Lounges sits at the top of the volume ranking, with Independent Lounges climbing the fastest.
Customer Type:
Passenger spend patterns diverge sharply between time-sensitive corporate accounts and price-conscious leisure segments, forcing operators to unbundle ancillary services.
- Business Travelers:Passengers with dwell times exceeding ninety minutes who generate the highest per-visit ancillary spend on premium food and spa services. United States and China concentrate this segment at financial and technology industry hubs.
- Families:Multi-passenger groups requiring dedicated children's zones and flexible seating configurations during extended layovers.
- Frequent Flyers:Status-holding passengers accessing lounges through airline loyalty tiers rather than paid membership.
- Tourists:Price-sensitive leisure travelers captured through impulse pay-per-use purchases at secondary airports.
Business Travelers command the highest margin per visit, with Families expanding most quickly as lounge operators retrofit spaces for multi-generational accommodation.
Access Method:
Digital credential convergence is displacing physical card presentation, compressing entry friction and enabling real-time capacity management.
- Membership:Annual fee-based programs with unlimited access rights, historically the dominant channel for frequent flyers. United States premium credit card penetration has expanded this base beyond traditional airline loyalty.
- Pay-Per-Use:Single-entry purchases booked through mobile applications, capturing price-sensitive segments excluded from annual commitments. India and Southeast Asia represent untapped volume in secondary airports.
- Airline Ticket:Complimentary access bundled with premium cabin fares or elite status tiers.
- Package Deals:Bundled access sold through online travel agencies and tour operators for leisure passenger segments.
Membership retains the largest installed base, with Pay-Per-Use gaining share fastest as mobile wallet integration removes friction from impulse purchases.
Amenities Offered:
EU Green Deal mandates are forcing upgrades to low-emission catering supply chains and energy-efficient infrastructure across all amenity categories.
- Food & Beverage:Climate-controlled preparation areas with seating density below 1.5 passengers per square meter and regional sourcing protocols to meet carbon disclosure thresholds. Frankfurt and Amsterdam operators are retrofitting supply chains.
- Showers:Water-efficient fixtures and premium toiletries targeting business travelers with tight connection windows.
- Wi-Fi:High-bandwidth connectivity infrastructure supporting video conferencing and streaming across dwell-time compression scenarios.
- Sleeping Pods:Compact rest units for passengers facing extended delays, requiring fire suppression retrofit standards coordinated by EASA.
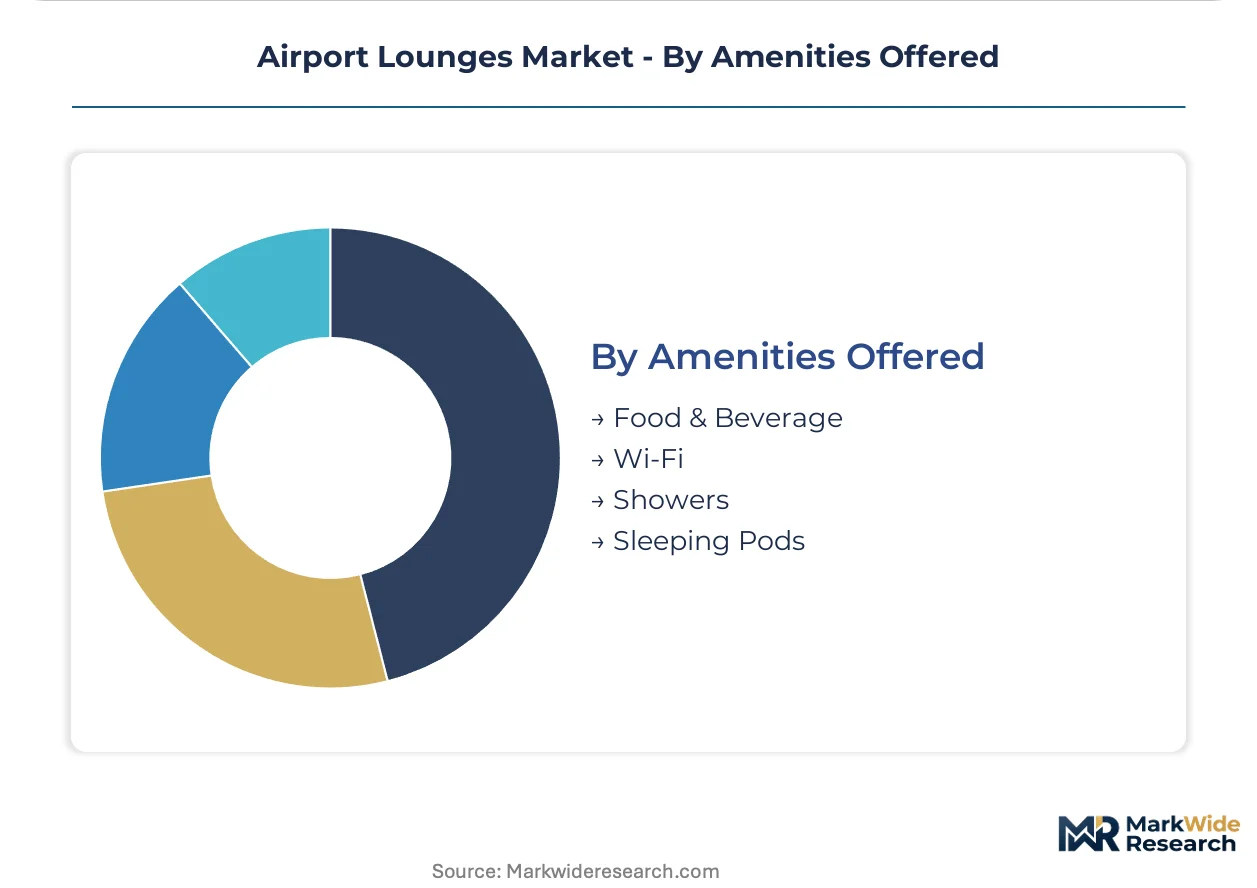
Food & Beverage dominates capital allocation, with Sleeping Pods expanding most quickly as biometric boarding systems compress traditional hospitality cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation hospitality talent clusters in the United States, China, and the United Arab Emirates anchor lounge network expansion. Premium credit card issuers in these markets deploy specialized workforce pools to manage biometric entry systems and captive F&B programming. Regulatory frameworks in each jurisdiction shape real estate access and carbon compliance obligations.
United States
Premium credit card penetration and business traveler density drive lounge construction at super-connector hubs. The Federal Aviation Administration maintains operational safety standards for sterile-area construction and fire suppression protocols. Dallas-Fort Worth and Atlanta anchor the highest lounge density, with American Express Centurion Lounges defending retention through interior design investments.
China
Super-connector airports in Beijing and Shanghai concentrate demand, though capacity quotas restrict expansion at congested tier-one facilities. The Civil Aviation Administration implements lounge space restrictions that directly constrain supply growth. Guangzhou Baiyun International Airport hosts independent operators retrofitting legacy airline spaces as consolidation reduces proprietary lounge counts.
United Arab Emirates
Dubai International Airport and Abu Dhabi International Airport anchor the highest lounge density per passenger globally. MOHAP coordinates health and safety standards for hospitality operations within sterile areas. Emirates and Etihad defend market position through captive lounge investments, while independent operators bid on concession tenders at expanding terminals.
India
Privatized terminals in Delhi, Mumbai, and Bangalore open concession opportunities to independent operators as airline consolidation reduces proprietary lounge counts. The Directorate General of Civil Aviation has issued revised aerodrome licensing requirements affecting lounge operator eligibility. DreamFolks exemplifies the technology aggregator model connecting regional networks to bank-issued card programs.
Germany
Frankfurt and Amsterdam anchor EU Green Deal compliance efforts, with operators retrofitting supply chains to meet embodied carbon disclosure thresholds. EASA coordinates fire suppression and evacuation protocols affecting lounge layout flexibility. Lufthansa maintains proprietary lounge dominance while independent operators source regional food suppliers to reduce transport emissions.
Airport Lounges Market Competitive Environment
Capital-heavy airline operators compete with asset-light independent lounge networks and technology aggregators. The market structure tiers across proprietary carrier facilities, concession-based third-party operators, and membership platform intermediaries. Strategic archetypes include network defenders consolidating hub presence, geographic expanders bidding on privatized terminal tenders, and technology integrators unifying access credentials across heterogeneous lounge portfolios. Dominant competitive moves center on M&A to secure concession rights and strategic partnerships with credit card issuers to lock in membership volumes.
Within the independent operator tier, Plaza Premium Group exemplifies the geographic expansion archetype through its presence in high-traffic Asian and Middle Eastern hubs. DreamFolks occupies a position representing technology aggregation, connecting regional lounge operators to bank-issued card programs across India and Southeast Asia. Among legacy carrier-based networks, United Airlines, American Airlines, and Delta Air Lines anchor the network defender archetype through captive investments at super-connector hubs. These three company groupings illustrate the competitive tension between asset ownership, concession flexibility, and platform intermediation reshaping market structure.
| Leading Market Players |
|---|
| Plaza Premium Group |
| United Airlines |
| American Airlines |
| Delta Air Lines |
| Qantas Airways Limited |
| Cathay Pacific Airways Limited |
| Lufthansa |
| American Express Centurion Lounges |
| DreamFolks |
| Others |
Value Chain & Pricing Dynamics
Biometric entry system deployment is simultaneously compressing operational labor costs and concentrating procurement power among technology-integrated lounge operators capable of justifying upfront capital outlays. This dual shift rewards scaled networks with captive F&B programming while squeezing independent operators dependent on third-party service contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors revenue architecture, with differentiation driven by dwell-time guarantees and F&B quality tiers. Price differentiation stems from brand premium commanded by American Express Centurion Lounges and geographic delivery cost inflation at super-connector hubs. Cost compression in the independent lounge tier is intensifying because credit card issuer reimbursement rates are tightening. Tourists and impulse pay-per-use buyers exhibit highest price sensitivity, while business travelers with corporate accounts show minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with premium F&B suppliers concentrated in the United States, United Arab Emirates, and Germany. Lounge construction draws from specialized HVAC contractors, biometric hardware vendors, and regional furniture fabricators. Tariff exposure on European-sourced fire suppression equipment complicates EASA compliance timelines. Distribution runs through airport concession management companies that control sterile-area access rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Airport Lounges Market functions as a stable compounder underpinned by premium credit card penetration that locks in recurring membership volumes regardless of airline cycle volatility.
For Market Incumbents: To counter independent lounge encroachment at privatized terminals, legacy carriers should deepen captive F&B programming investments and secure long-term concession renewals at Dallas-Fort Worth and Atlanta. Backward integration into regional food sourcing will satisfy EU Green Deal disclosure thresholds while defending margin position. For New Entrants and Emerging Players: Capture pay-per-use volume at secondary Indian airports where DreamFolks has established bank-card aggregator relationships but lounge density remains below saturation. Target Delhi and Bangalore privatized terminals with technology-light, modular buildouts that minimize biometric system capital requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among independent operators with underutilized concession rights at tier-two Asian hubs. Long-term viability rests on lounge network density that sustains credit card issuer partnership renewals. Monitor biometric data governance rulings from European and Indian privacy regulators as the critical inflection signal for technology deployment cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Entry System Deployment | Facial recognition integration at Dubai International Airport eliminates queue friction and reduces reception staffing. |
| Regional Food Supply Chain Integration | Frankfurt operators sourcing within 150-kilometer radius meet EU Green Deal embodied carbon disclosure mandates. |
| Credit Card Issuer Partnership Lock-In | American Express Centurion Lounge expansion at Atlanta secures captive membership volume against Priority Pass erosion. |
| Pay-Per-Use Mobile Platform Launch | DreamFolks connects regional Indian lounges to impulse purchase behavior via bank-app integration. |
| Concession Tender Pre-Positioning | Plaza Premium Group bids on Beijing Daxing expansion slots ahead of Civil Aviation Administration capacity quota relaxation. |
Study Parameters
Direct dialogue with lounge operations directors, credit card partnership managers, airport concession procurement officers, and biometric technology vendors grounded qualitative assessment. Secondary validation drew from FAA operational safety bulletins, EASA fire suppression standards, Civil Aviation Administration capacity directives, and SEC filings from publicly traded hospitality operators. Bottom-up lounge count modeling triangulated against top-down credit card membership penetration estimates.
Segment-level projections across service type, customer profile, access method, and amenity category generated volume and value outputs over the projection horizon. CAGRs were derived from fitted growth curves incorporating premium credit card issuance trends, airport privatization timelines, and regulatory capacity constraints. Industry-specific inputs included tier-one airport congestion indices and bank-issued lounge access benefit attach rates.
Regulatory capacity quota adjustments, biometric data governance rulings, and credit card issuer reimbursement rate negotiations are the dominant revision risks to modeled trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Russia Online Accommodation Market
Accommodation
Sweden Hospitality Market
Accommodation
Germany Student Accommodation Market
Accommodation
Underwater Hotels Market
Accommodation
Hostel Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Capsule Hotels Market
Accommodation
US Student Accommodation Market
Accommodation
Canada Hospitality Market
Accommodation
Croatia Hospitality Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
Japan Online Accommodation Market
Accommodation
Global Travel Accommodation Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
China Online Accommodation Market
Accommodation
France Casino Tourism Market