
 Capsule Hotels Market | 2026-2036
Capsule Hotels Market Size, Share, and Industry Trends Forecast 2026-2036
Capsule Hotels Market Analysis
Subscription-based loyalty and membership access is hardening into a core revenue layer for capsule hotel operators. First Cabin HD Co. Ltd. leverages its tiered cabin formats to capture repeat corporate clientele across Japanese transit hubs. Nine Hours sustains a minimalist, automated check-in model that reduces labor overhead while maximizing nightly turnover. Pangea Pod Hotel differentiates through social programming and shared lounge concepts aimed at younger travelers in Canadian and Asian markets.
Capsule hotels are compact, modular sleeping accommodations typically measuring 1-2 meters in width and length, constructed from reinforced plastic or fiberglass shells stacked in high-density configurations, designed to provide low-cost overnight lodging in space-constrained urban environments. Budget and mid-range type segments dominate volume, while boutique capsule concepts command higher nightly rates through curated design and premium amenities. Urban facility types anchor the installed base, though airport and transit-adjacent locations are expanding fastest as layover tourism and bleisure travel patterns intensify.
Japan's Ministry of Health, Labour and Welfare enforces strict fire safety and sanitation standards that dictate capsule dimensions, ventilation requirements, and emergency egress protocols, raising compliance costs for new entrants. Singapore's Urban Redevelopment Authority and Building and Construction Authority jointly regulate micro-lodging density within commercial zones, shaping where operators can cluster properties. Stakeholders must monitor how municipal zoning boards in dense Asian cities recalibrate permitting for compact hospitality formats as housing shortages and tourism pressures converge.
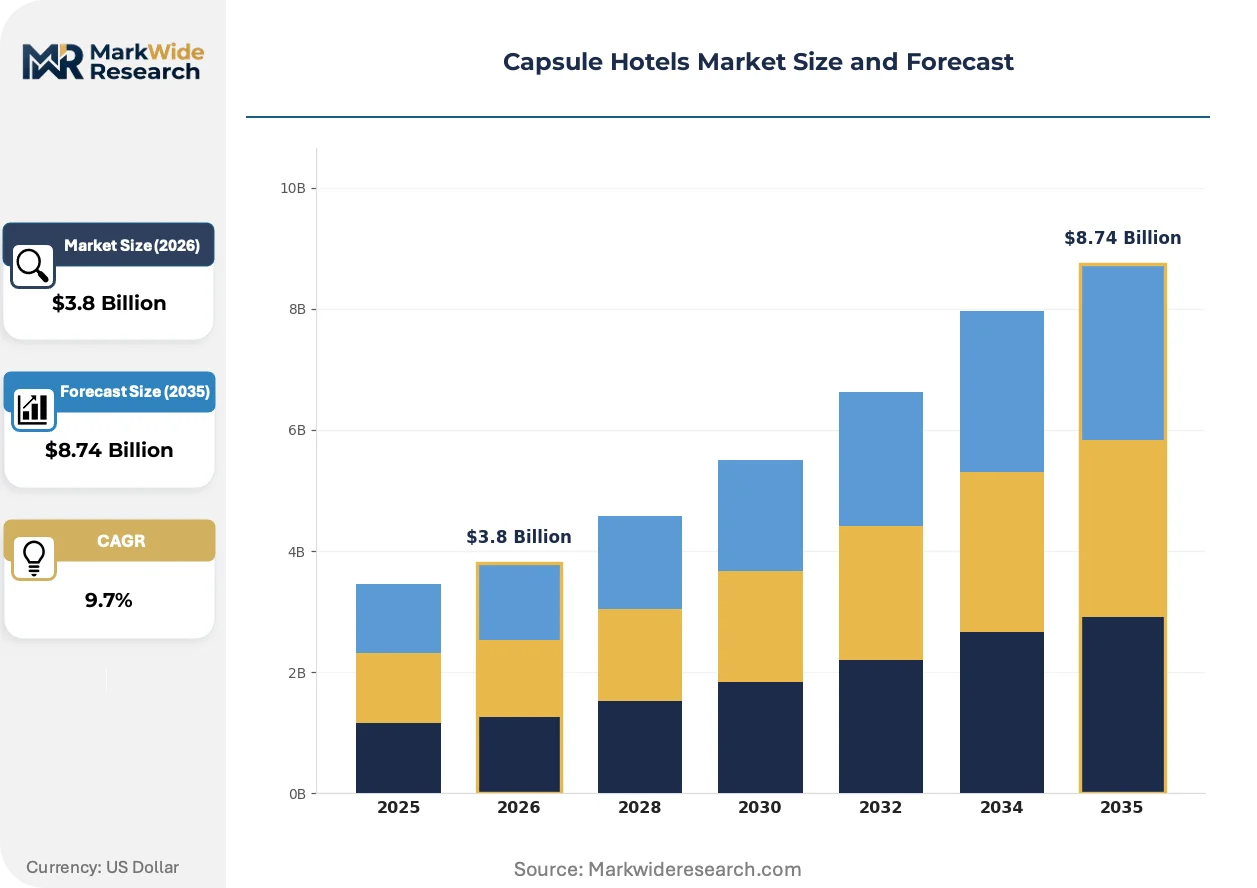
Market Dynamics
Urban densification across Asia-Pacific transit corridors is compressing land availability while bleisure travel patterns fragment traditional hotel demand, forcing operators to optimize square-meter yield through modular, high-turnover lodging formats.
Growth Catalysts
- Japan's Fire Service Act amendments:Tightened evacuation protocols for compact lodging have professionalized construction standards, filtering out informal operators and elevating consumer trust in licensed capsule properties.
- Layover tourism infrastructure:Airport-adjacent capsule clusters in Singapore and Tokyo capture transit passengers seeking sleep pods between long-haul connections, converting dead time into revenue.
- Fiberglass-reinforced plastic shells:Advances in modular manufacturing reduce on-site construction duration, enabling faster property launches in high-rent commercial zones.
Market Restraints
- Ventilation system costs:Japan's Ministry of Health, Labour and Welfare mandates mechanical air exchange rates that add 15-20% to fit-out expenses, squeezing operator margins in budget segments.
- Supplier concentration in Osaka:Three domestic manufacturers dominate capsule shell production, creating bottleneck risk for expansion-minded operators seeking standardized components.
- Micro-apartment substitution:Tokyo's expanding furnished rental market offers comparable nightly rates with private bathrooms, diverting solo travelers from shared-facility capsule formats.
Strategic Opportunities
- Singapore's Urban Redevelopment Authority zoning recalibration:Pending commercial-mixed-use reforms may permit capsule density in heritage districts currently restricted to traditional hotels.
- Subscription loyalty platforms:Corporate travel managers seek bulk-purchase agreements for transit-hub sleeping pods, creating recurring revenue streams distinct from volatile leisure bookings.
- IoT-integrated sleep optimization:Convergence of biometric sensors and automated climate control enables premium-tier capsule concepts commanding rates approaching business hotel levels.
Industry Challenges
- Certification timeline compression:Japan's building code amendments require third-party fire resistance testing that extends pre-opening phases by 4-6 months, delaying cash flow generation.
- Legacy property integration:Converting aging love hotels or business hotels into capsule formats demands structural reinforcement for stacked shell configurations, complicating renovation economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsule Hotels Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Luxury, Budget, Mid-Range, Boutique Facility Type: Urban, Airport, Transit, Resorts Target Audience: Backpackers, Business Travelers, Tourists, Students Amenities: WiFi, Breakfast Included, Lockers, Shared Lounge |
| Companies Covered | The Pod Hotels, Zedwell, Book and Bed Tokyo, Capsule Inn Osaka, Bloc Hotel, First Cabin HD Co. Ltd., Nadeshiko Hotel, Pangea Pod Hotel, Nine Hours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsule Hotels Market Emerging Trajectories
Automation and modular construction are converging to redefine operational economics in compact hospitality, shifting competitive advantage toward technology-enabled asset-light models.
Contactless check-in systems leveraging facial recognition and mobile key distribution are decentralizing front-desk functions across Japanese capsule networks. Business travelers now expect 90-second arrival-to-sleep transitions, forcing operators to eliminate staffed reception entirely. This compression of touchpoints is decentralizing service labor from fixed properties into centralized remote monitoring hubs.
Singapore's Building and Construction Authority has introduced performance-based fire safety standards for micro-lodging, replacing prescriptive dimensional rules with engineered evacuation modeling. Developers can now optimize capsule density through computational fluid dynamics rather than uniform size mandates. Boutique operators in Marina Bay and Chinatown are responding by commissioning custom shell geometries that maximize yield per floor plate.
Bleisure travelers are unbundling accommodation from amenity access, purchasing sleep-only capsule nights while sourcing showers, meals, and workspace from third-party providers. This fragmentation is disrupting the traditional full-service hotel bundle in Tokyo's Shibuya and Osaka's Umeda districts. Younger demographic segments in these clusters increasingly treat lodging as pure utility, spending saved accommodation budget on experiential consumption elsewhere in the urban core.
Capsule Hotels Market Segmentation
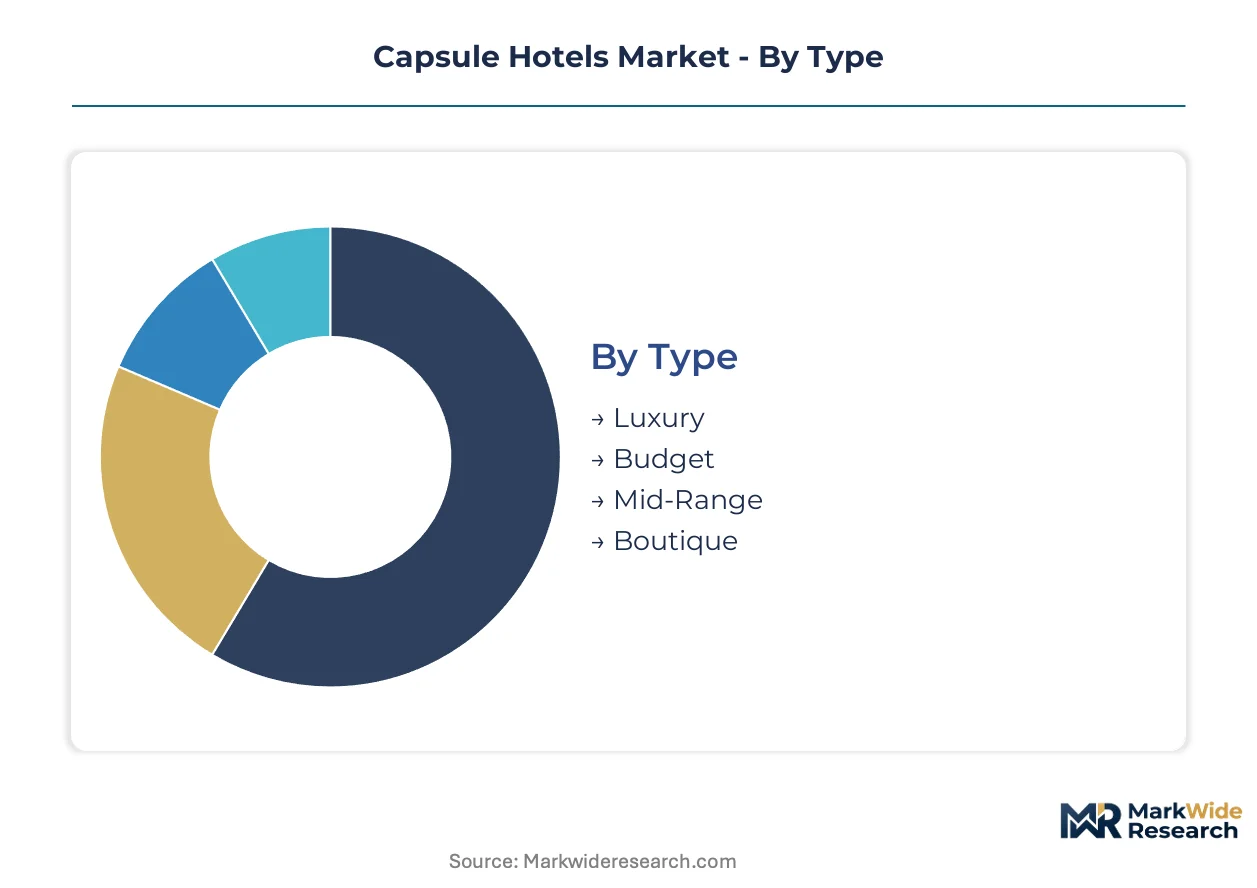
Segmentation in the capsule hotel market reveals how regulatory frameworks and space economics fragment revenue models across distinct operational formats. Each category carries unique compliance burdens that reshape capital deployment and margin structures for operators.
Type:
Japan's Ministry of Health, Labour and Welfare applies differential fire safety testing based on capsule density and material composition, with luxury and boutique formats facing extended certification timelines due to integrated climate systems.
- Budget:Reinforced plastic shells with minimal mechanical systems dominate volume deployment. Demand concentrates in Tokyo's Shibuya and Osaka's Umeda districts where transit proximity overrides amenity expectations. Japan's streamlined evacuation protocols for low-complexity configurations accelerate permitting.
- Mid-Range:Fiberglass-reinforced shells with modular ventilation units balance cost and comfort. Singapore's Urban Redevelopment Authority permits higher density for mid-range formats meeting performance-based fire standards. Business travelers in Changi Airport corridors drive repeat bookings.
- Luxury:Custom shell geometries with biometric climate control and premium finishes.
- Boutique:Curated design concepts with social programming and localized aesthetic integration.
Leading the category by volume: Budget. Growing fastest: Boutique.
Facility Type:
Facility location determines which municipal zoning board holds permitting authority, with airport-adjacent properties facing dual aviation and building code oversight that extends pre-construction phases.
- Urban:High-rise commercial zone installations with stacked shell configurations maximizing floor-plate yield. Tokyo's 23 wards and Osaka's central business districts anchor installed base. Singapore's Building and Construction Authority regulates density through computational fluid dynamics modeling rather than fixed dimensional mandates.
- Airport:Terminal-adjacent sleep pods capturing layover tourism demand between long-haul connections. Haneda and Narita clusters in Japan plus Changi in Singapore convert dead transit time into revenue. Aviation authority coordination adds regulatory layer beyond standard hospitality codes.
- Transit:Railway station-integrated formats targeting bleisure travelers with fragmented itineraries.
- Resorts:Seasonal destination properties with lower turnover and higher nightly rates.
Highest revenue per square meter: Airport. Steepest expansion trajectory: Transit.
Target Audience:
Audience segmentation aligns booking patterns with operational design, as business travelers demand automated check-in while backpackers prioritize social infrastructure.
- Business Travelers:Corporate accounts seeking 90-second arrival-to-sleep transitions and subscription-based loyalty access. First Cabin HD Co. Ltd. captures this segment through tiered cabin formats across Japanese transit hubs. Procurement managers negotiate bulk-purchase agreements for transit-hub sleeping pods.
- Backpackers:Price-sensitive solo travelers treating lodging as pure utility while sourcing amenities from third-party providers. Pangea Pod Hotel targets this demographic through shared lounge concepts in Canadian and Asian markets. Shibuya and Chinatown clusters see highest concentration.
- Tourists:Leisure visitors seeking novel accommodation experiences in dense urban cores.
- Students:Academic-term and examination-period demand with extended-stay pricing models.
Dominant share by booking volume: Business Travelers. Climbing the fastest: Students.
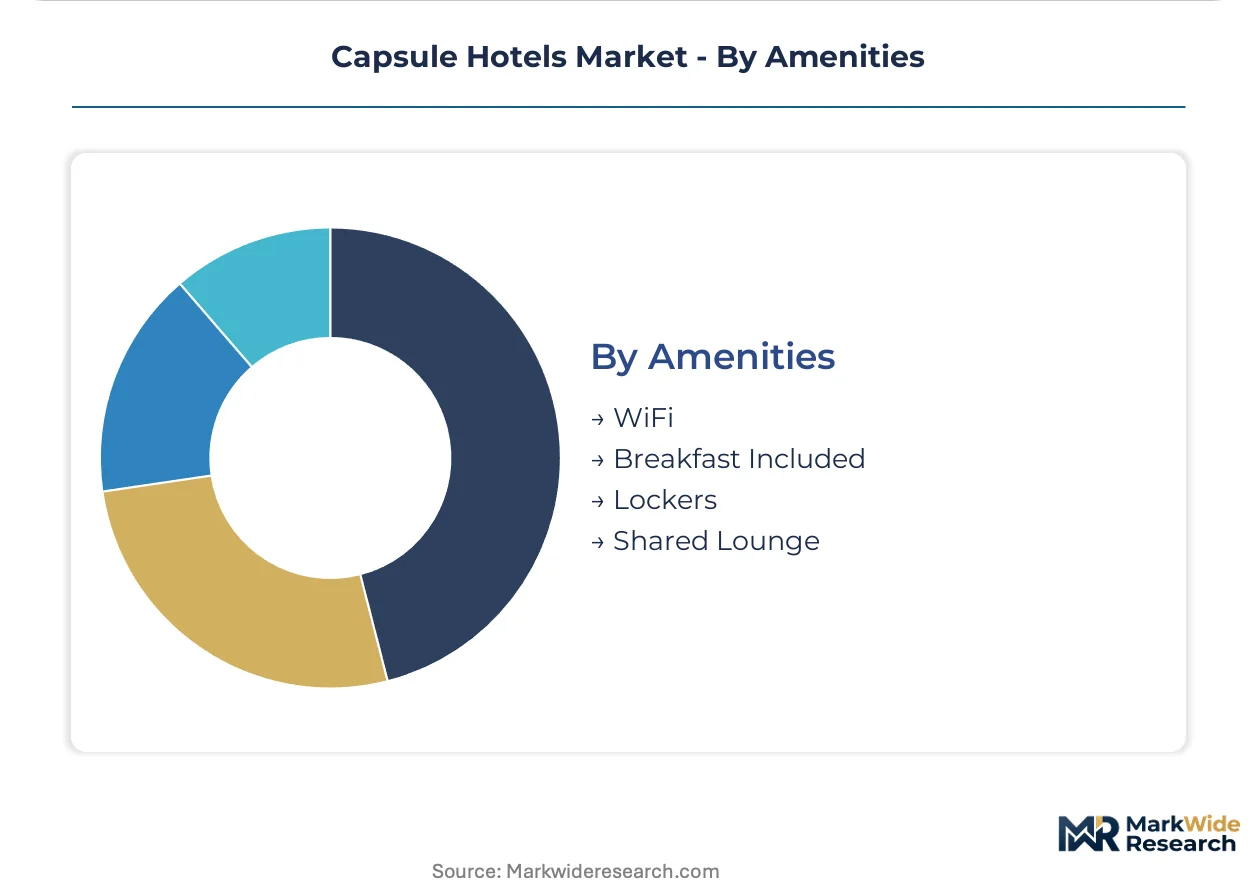
Amenities:
Amenity bundling fragments as bleisure travelers unbundle full-service hotel packages, purchasing sleep-only nights while sourcing showers, meals, and workspace externally.
- WiFi:Baseline connectivity infrastructure now mandatory across all price tiers. Nine Hours sustains minimalist automated models where wireless access replaces staffed reception entirely. Remote monitoring hubs manage network performance across decentralized properties.
- Shared Lounge:Social programming spaces differentiating boutique operators from pure utility formats. Younger demographics in Marina Bay and Umeda treat these as experiential anchors justifying rate premiums over bare-budget alternatives. Design-forward concepts command rates approaching business hotel levels.
- Breakfast Included:Food service integration raising fire safety and sanitation compliance burdens.
- Lockers:Secure storage infrastructure essential for transit-corridor properties with high guest turnover.
Widest penetration: WiFi. Gaining share fastest: Shared Lounge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates capsule manufacturing capacity through three domestic shell producers based in Osaka, while consumption spreads across dense Asian transit corridors where land scarcity compresses lodging formats. Production geography remains narrow. Demand geography fragments across urban cores seeking modular sleep solutions.
Japan
Tokyo's 23 wards and Osaka's central business districts anchor installed capacity, with First Cabin HD Co. Ltd. and Nine Hours operating tiered formats across transit hubs. Japan's Ministry of Health, Labour and Welfare enforces strict fire safety and sanitation standards that dictate capsule dimensions and ventilation requirements. Kansai manufacturers supply fiberglass-reinforced shells to domestic operators, though supplier concentration creates bottleneck risk for expansion.
Singapore
Changi Airport corridors and Marina Bay clusters capture layover tourism demand between long-haul connections, converting dead transit time into revenue. The Urban Redevelopment Authority and Building and Construction Authority jointly regulate micro-lodging density within commercial zones through performance-based fire safety standards. Chinatown boutique operators commission custom shell geometries that maximize yield per floor plate under computational fluid dynamics modeling.
South Korea
Seoul Capital Area transit corridors see rising adoption among bleisure travelers with fragmented itineraries seeking utility-focused lodging. The country's national construction regulator maintains prescriptive dimensional rules for compact hospitality formats that lag Singapore's performance-based approach. Gangnam and Hongdae districts host emerging capsule clusters targeting younger demographics unbundling accommodation from amenity access.
United States
New York Metro and Pacific Northwest urban cores experiment with pod-hotel concepts adapted from Asian precedents, though fire code fragmentation across municipal jurisdictions slows standardization. Local building authorities in dense coastal cities pilot amended egress protocols for modular sleeping configurations. Manhattan and San Francisco see limited pilot properties targeting tech-sector business travelers seeking 90-second arrival-to-sleep transitions.
Canada
Pangea Pod Hotel anchors social-programming concepts in Vancouver and Whistler, differentiating through shared lounge infrastructure aimed at younger travelers. Provincial building codes vary in treatment of micro-lodging density, with British Columbia permitting more experimental formats than Ontario. Canadian operators import shell components from Asian suppliers, extending lead times for property launches.
Capsule Hotels Market Vendor Landscape
Capital-heavy property owners compete with asset-light brand licensors across the capsule hotel landscape, creating a tiered structure where real estate investors, manufacturing specialists, and hospitality operators occupy distinct profit pools. The market fragments across three strategic archetypes: integrated owner-operators controlling shell production and property management, pure-play brand licensors collecting franchise fees without asset ownership, and technology-enabled platform operators aggregating inventory without physical infrastructure. Consolidation pressure concentrates among mid-tier owner-operators seeking scale to offset rising compliance costs, while brand licensors pursue geographic expansion through master franchise agreements.
Within the integrated owner-operator tier, First Cabin HD Co. Ltd. and Nine Hours exemplify the Japanese model of tiered cabin formats and automated check-in systems that minimize labor overhead. Pangea Pod Hotel occupies a position among experience-focused specialists differentiating through social programming rather than pure utility. These three anchors represent divergent strategic bets on whether capsule lodging converges toward commodity sleep infrastructure or retains experiential differentiation through design and community programming.
| Leading Market Players |
|---|
| The Pod Hotels |
| Zedwell |
| Book and Bed Tokyo |
| Capsule Inn Osaka |
| Bloc Hotel |
| First Cabin HD Co. Ltd. |
| Nadeshiko Hotel |
| Pangea Pod Hotel |
| Nine Hours |
| Others |
Supply Flow & Price Mechanics
Bleisure travelers unbundling accommodation from amenity access force operators to strip out service layers and source sleep-only infrastructure from concentrated shell manufacturers, compressing rate premiums toward commodity levels.
Pricing Analysis
Margin tightening in budget tiers reflects ventilation mandate compliance costs from Japan's Ministry of Health, Labour and Welfare. Three-tier pricing structure across luxury, mid-range, and budget levels separates properties by fire certification grade and automation integration. Cost-down pressure on economy formats accelerates as micro-apartment substitutes in Tokyo offer comparable nightly rates with private facilities. Backpackers exhibit highest price sensitivity, while corporate procurement managers negotiate least-sensitive subscription contracts.
Supply Chain Analysis
Fiberglass-reinforced shell production rests on three domestic manufacturers clustered in Osaka, Japan. Raw material inputs include resin compounds, ventilation modules, and biometric sensor packages sourced from South Korea and Taiwan. Single-source vulnerability concentrates in shell molding capacity, where property launch timelines hinge on Osaka backlog queues. Distribution runs through direct operator procurement with limited third-party logistics intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's fire safety code amendments professionalize construction standards, filtering informal operators and forcing consolidation among capital-constrained mid-tier owner-operators unable to absorb extended certification timelines.
For Market Incumbents: Anchor tiered cabin formats across transit hubs to capture recurring corporate subscription revenue. Invest in automated check-in systems that eliminate staffed reception overhead. Defend against micro-apartment substitution by emphasizing 90-second arrival-to-sleep transitions unavailable in furnished rentals. Prioritize certification investment to maintain licensed status under tightened evacuation protocols. For New Entrants and Emerging Players: Singapore's Urban Redevelopment Authority zoning recalibration opens a window for boutique capsule density in heritage districts currently restricted to traditional hotels. Target bleisure travelers unbundling accommodation from amenity access in Chinatown and Marina Bay clusters. Pursue white-space in IoT-integrated sleep optimization commanding premium rates. Launch through performance-based fire safety compliance rather than prescriptive dimensional adherence. For Investors and Strategic Acquirers: Re-rating potential sits with technology-enabled platform operators aggregating inventory without physical infrastructure given automation convergence reducing labor dependency. Long-term viability favors asset-light brand licensors expanding through master franchise agreements across Asian transit corridors. Monitor certification timeline compression as inflection indicator for distressed acquisition opportunities among legacy property converters facing structural reinforcement cost overruns.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Manufacturing Scale-Up | Osaka shell producers expanding capacity reduces property launch lead times for operators. |
| Subscription Loyalty Platform Launch | Corporate bulk-purchase agreements stabilize revenue volatility from leisure booking fluctuations. |
| Performance-Based Fire Safety Certification | Singapore's computational fluid dynamics modeling permits custom shell geometries maximizing yield. |
| Automated Check-In System Deployment | Nine Hours' remote monitoring hub model decentralizes service labor from fixed properties. |
| Transit Hub Property Clustering | Haneda and Changi airport-adjacent locations convert dead transit time into revenue streams. |
Methodological Framework
Independent corroboration across hospitality operations executives, municipal zoning officials, and fiberglass manufacturing specialists underwrites the qualitative findings. Primary fieldwork captured perspectives from capsule hotel operators in Tokyo's 23 wards and Osaka's central business districts, transit authority planners in Singapore, and shell production managers in Kansai. Secondary validation drew from Japan's Ministry of Health, Labour and Welfare regulatory filings, Singapore's Building and Construction Authority technical circulars, and urban densification studies from OECD metropolitan databases. Bottom-up property-level capacity assessments and top-down regional tourism flow projections were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by type tier, facility location, and target audience archetype. The analytical framework models capsule density per floor plate, nightly turnover velocity, and subscription contract penetration as industry-specific demand drivers. CAGRs were derived from fitted growth curves calibrated against historical permit issuance patterns and transit passenger volume correlations.
The model assumes a particular technology adoption path; alternative pathways for IoT-integrated sleep optimization would alter the outlook if biometric sensor costs fall faster than projected. Forecasts reflect assumptions about regulatory enforcement consistency and bleisure travel pattern persistence. A small set of triggers—including fire code amendment delays, micro-apartment supply surges, and aviation demand shocks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Romania Hospitality Market
Accommodation
Sweden Hospitality Market
Accommodation
Switzerland Hospitality Market
Accommodation
Germany Student Accommodation Market
Accommodation
Casino Hotel Market
Accommodation
Africa Hotel Market
Accommodation
Canada Hospitality Market
Accommodation
France Casino Tourism Market
Accommodation
Hotel Market
Accommodation
Austria Hospitality Market
Accommodation
United States Online Accommodation Market
Accommodation
UK Student Accommodation Market
Accommodation
United Kingdom Hospitality Market
Accommodation
France Online Accommodation Market
Accommodation
Russia Online Accommodation Market
Accommodation
Italy Online Accommodation Market