
 France Casino Tourism Market | 2026-2036
France Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
France Casino Tourism Market Foresight
Project finance and sale-leaseback structures for integrated resort assets is fragmenting competitive access across the French casino tourism landscape. Groupe Lucien Barrière leverages its vertically integrated hospitality portfolio to sustain premium positioning along the Atlantic and Mediterranean coasts. Groupe Partouche anchors mid-market segments through regional casino-hotels outside Paris, while FDJ United competes via digital-physical convergence strategies that extend its lottery-origin brand into experiential tourism.
France casino tourism encompasses destination gaming integrated with hospitality, entertainment, and cultural programming, typically operating under concession agreements with minimum slot machine counts and table game ratios mandated by the Ministry of Interior. Its primary commercial purpose is to capture extended-stay visitor expenditure through bundled lodging, dining, and gaming services. Resort casinos dominate absolute revenue contribution along the Riviera and in Deauville, while culinary experiences within casino complexes represent the fastest-growing tourist purpose segment as gastronomy-driven itineraries expand. High net worth individuals command disproportionate margin pools through private salons and bespoke concierge programming, though millennial travelers are reshaping booking channel dynamics toward mobile apps and direct online platforms.
France's casino sector operates under joint oversight from the Autorité de Régulation des Jeux En Ligne and Tracfin, with concession renewals requiring compliance with evolving responsible gambling protocols and anti-money laundering verification standards. The EU's Digital Services Act and France's own Loi Sapin anti-corruption framework further constrain cross-border marketing and third-party intermediary relationships. Stakeholders must monitor how proposed revisions to concession duration limits and digital integration mandates will alter capital deployment timelines for physical asset upgrades.
Market Dynamics
Integrated resort financing structures are fragmenting competitive access across the French casino tourism landscape, as project finance and sale-leaseback arrangements concentrate asset ownership among vertically integrated hospitality groups while excluding mid-tier operators from prime coastal positions.
Growth Catalysts
- Culinary-driven itineraries:Gastronomy programming within casino complexes is attracting extended-stay visitors seeking Michelin-recognized dining experiences alongside gaming services.
- Autorité de Régulation des Jeux En Ligne digital integration:Evolving regulatory frameworks are mandating technology upgrades that enable seamless physical-digital convergence for visitor engagement.
- Côte d'Azur corridor concentration:Premium gaming-entertainment clusters anchored by Nice and Cannes capture disproportionate international leisure traveler expenditure.
Market Restraints
- Concession renewal compliance costs:Tracfin anti-money laundering verification standards and responsible gambling protocol mandates impose structural capital burdens on legacy operators.
- Paris basin exclusion:Regulatory prohibitions on casino operations within the capital region constrain geographic expansion for domestic market penetration.
- Fixed asset intensity:Ministry of Interior-mandated minimum slot machine counts and table game ratios lock operators into inflexible physical capacity commitments regardless of demand fluctuation.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur secondary destinations:Underdeveloped coastal municipalities outside established Nice-Cannes clusters present white-space acquisition targets for integrated resort development.
- Loi Sapin anti-corruption framework adaptation:Compliance infrastructure investments create competitive moats against cross-border operators lacking established French regulatory relationships.
- Mobile app direct booking:Millennial traveler channel preferences are compressing traditional intermediary commission structures and enabling margin recapture through proprietary digital platforms.
Industry Challenges
- Tracfin verification specialist scarcity:Anti-money laundering compliance functions require rare dual competencies in financial forensics and hospitality operations.
- Concession duration uncertainty:Proposed revisions to renewal timelines are freezing multi-year capital deployment decisions for physical asset renovations.
- EU Digital Services Act cross-border marketing constraints:Platform liability provisions complicate targeted customer acquisition campaigns across member state boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Casino Tourism Market |
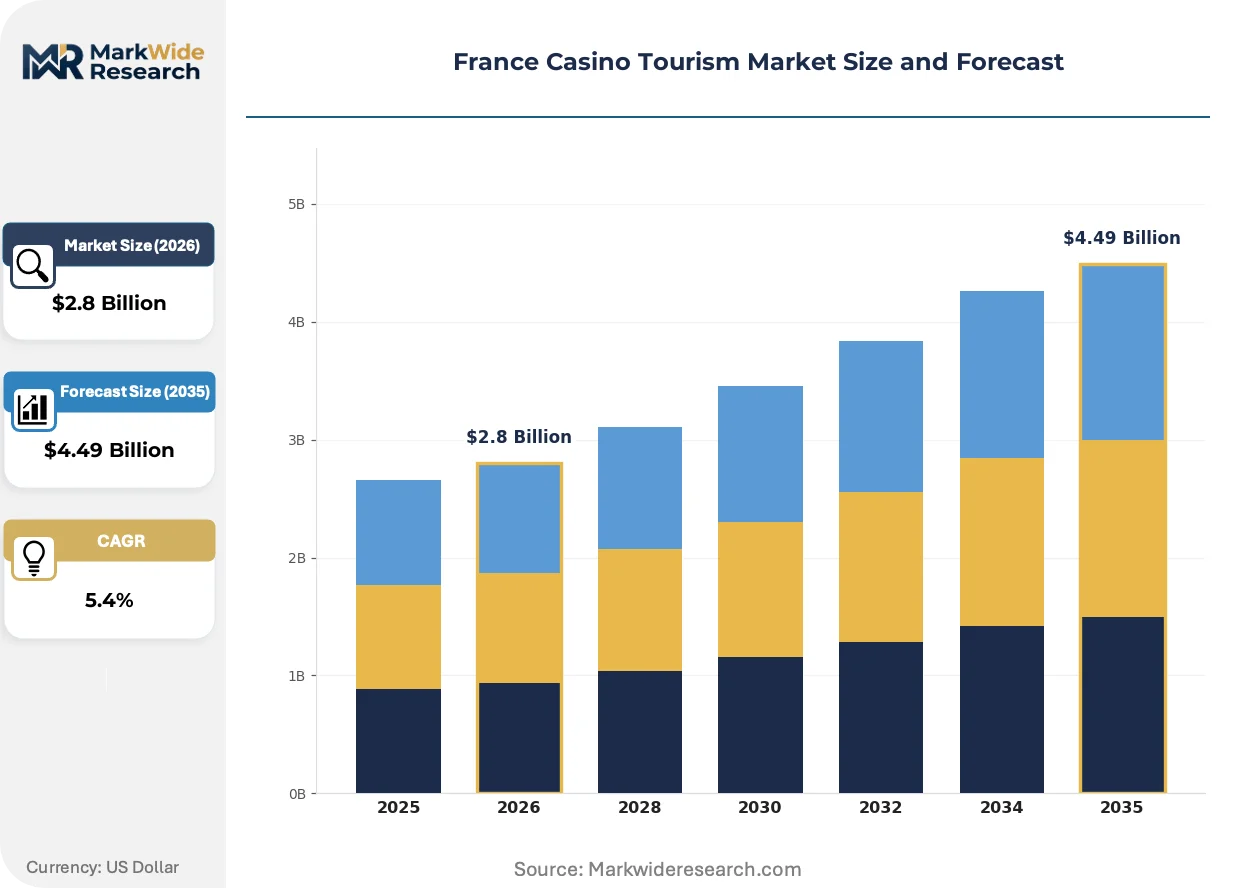
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Casino Type: Resort Casinos, Riverboat Casinos, Native Casinos, Private Card Rooms Tourist Purpose: Leisure Gaming, Business Events, Entertainment Shows, Culinary Experiences, Cultural Exploration Customer Demographic: Millennial Travelers, Senior Visitors, High Net Worth Individuals, Budget Tourists Booking Channel: Direct Online, Travel Agents, Package Tours, Mobile Apps, Walk-in Reservations |
| Companies Covered | Casinos Austria AG, Holland Casino, Française des Jeux (FDJ United), Bet365, Rank Group (Grosvenor Casinos), Groupe Lucien Barrière, Novomatic AG, Allwyn, Groupe Partouche, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Casino Tourism Market Shifts & Advancements
Digital-physical convergence technologies are compressing traditional casino tourism operating models, while regulatory digitization mandates and shifting generational booking behaviors are forcing asset-level reinvention across the French hospitality-gaming sector.
Cashless gaming systems integrating biometric authentication and real-time spending controls are replacing legacy chip-and-cage transactions across premium resort properties. High net worth individual segments are adopting these platforms fastest, driven by concierge service integration demands. The technology is rendering obsolete manual reconciliation processes and floor-based currency handling infrastructure that previously dominated casino operations.
ANJ responsible gambling protocol digitization is mandating algorithmic player monitoring and automated intervention triggers for concession renewal eligibility. Operator compliance departments are restructuring around data science capabilities to meet real-time reporting requirements. Private salon segments face the steepest adaptation costs as bespoke service traditions conflict with standardized digital surveillance mandates.
Direct-to-consumer mobile platforms are displacing traditional travel intermediary channels for integrated resort bookings. Millennial traveler segments are consolidating accommodation, dining, and entertainment reservations through single-app ecosystems. This channel compression is most visible in Cannes and Deauville, where operator-owned platforms now capture majority share of advance bookings previously controlled by tour operators and online travel agencies.
France Casino Tourism Market Segmentation
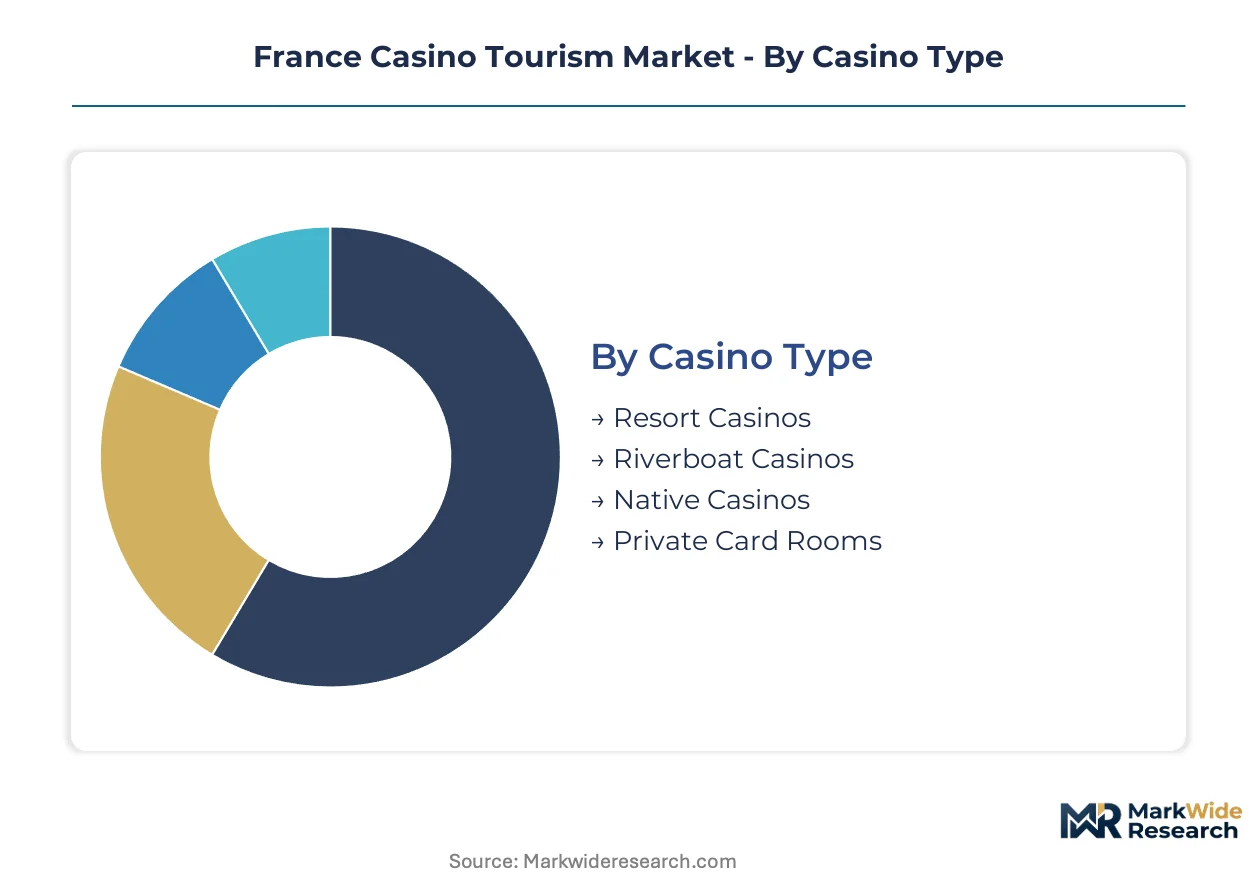
Segmentation in France casino tourism reveals how distinct visitor motivations and operational formats create divergent margin profiles. Operators configure service intensity, gaming floor composition, and hospitality programming differently across each category to capture specific expenditure patterns.
Casino Type:
After-sales service intensity varies dramatically by physical format, with integrated resorts requiring continuous hospitality staffing versus limited-service venues.
- Resort Casinos:Full-service properties bundle lodging, fine dining, and entertainment with gaming floors exceeding Ministry of Interior minimums for slots and tables. Demand concentrates along the Côte d'Azur corridor where Nice and Cannes properties capture extended-stay international leisure travelers through Michelin-recognized culinary programming.
- Riverboat Casinos:Maritime-constrained venues operating under specialized concession frameworks with reduced physical footprints and limited non-gaming amenities. These properties serve regional markets where geographic restrictions prevent land-based alternatives, though Autorité de Régulation des Jeux En Ligne oversight applies equally.
- Native Casinos:Properties operating under distinct regulatory frameworks with sovereign or semi-autonomous governance structures.
- Private Card Rooms:Intimate gaming spaces emphasizing table games over slot machines with personalized dealer services and lower capital intensity.
By volume, Resort Casinos lead. By growth pace, Private Card Rooms are expanding most quickly.
Tourist Purpose:
Cost tier stratification separates high-commission entertainment programming from low-margin pure gaming visitation.
- Leisure Gaming:Core casino visitors prioritizing slots and table games as primary trip motivation with shorter average stays and higher per-session gaming intensity. This segment dominates absolute visitor counts across all French casino properties.
- Business Events:Corporate gatherings utilizing conference facilities and private salons with gaming as secondary programming, generating disproportionate food and beverage revenue per occupied room.
- Entertainment Shows:Theater and concert-driven visitation combining ticketed performances with gaming floor access.
- Culinary Experiences:Gastronomy-focused itineraries where Michelin-recognized restaurants within casino complexes serve as primary attraction, attracting extended-stay visitors with higher ancillary spend.
- Cultural Exploration:Heritage and arts programming integrated with gaming properties, particularly strong in Deauville and Biarritz where architectural preservation enhances destination appeal.
By volume, Leisure Gaming leads. By growth pace, Culinary Experiences are gaining share fastest.
Customer Demographic:
Application-based segmentation aligns property programming with life-stage expenditure patterns and technology adoption profiles.
- Millennial Travelers:Digital-native visitors consolidating bookings through mobile apps and direct platforms, reshaping channel economics away from traditional intermediaries. This demographic demands seamless physical-digital convergence and cashless gaming integration.
- Senior Visitors:Established casino tourists with loyalty program tenure and preference for familiar properties with traditional service models and human-mediated transactions.
- High Net Worth Individuals:Ultra-premium segment commanding private salons and bespoke concierge programming with disproportionate margin contribution through personalized table limits and exclusive entertainment access.
- Budget Tourists:Price-sensitive visitors utilizing package tours and promotional offers with constrained ancillary spend and higher price elasticity.
By volume, Senior Visitors lead. By growth pace, Millennial Travelers show the steepest expansion trajectory.
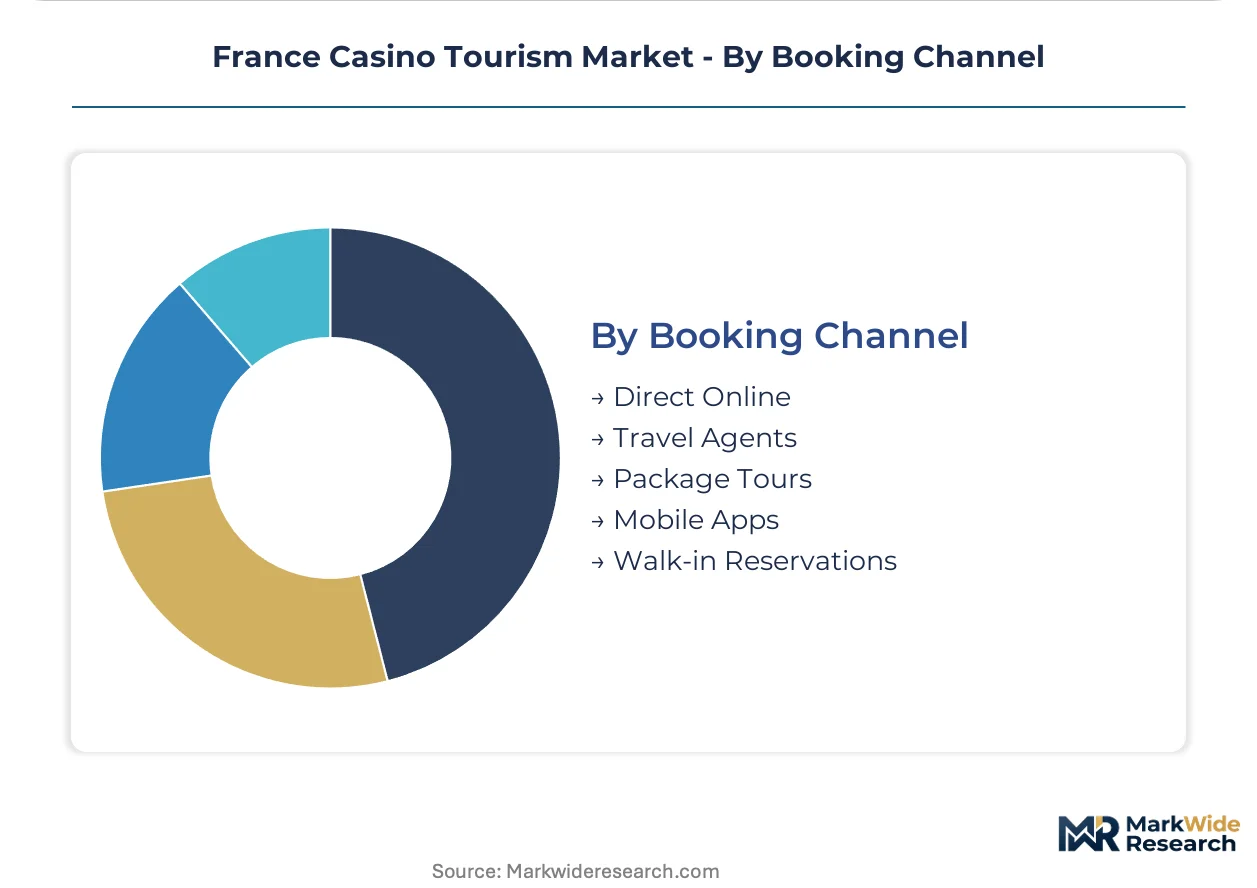
Booking Channel:
Customer type segmentation distinguishes between intermediary-dependent and direct-acquisition revenue streams with divergent commission structures.
- Direct Online:Proprietary website and email-driven reservations capturing full margin without third-party commissions, fastest-growing channel among independent travelers.
- Travel Agents:Traditional intermediary bookings with 10-15% commission burdens, declining share but remaining significant for senior demographics and international source markets.
- Package Tours:Bundled air-hotel-gaming products through tour operators with volume guarantees and reduced rate structures.
- Mobile Apps:Operator-owned platform ecosystems consolidating accommodation, dining, and entertainment reservations, dominant in Cannes and Deauville for advance bookings.
- Walk-in Reservations:Unplanned arrivals with highest cancellation risk but lowest acquisition cost, concentrated in regional properties outside peak season.
By volume, Travel Agents still lead. By growth pace, Mobile Apps are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's casino tourism sector generates substantial service exports through Riviera properties attracting high-spending international visitors, while import dependency remains minimal given domestic operator dominance and regulatory barriers to foreign establishment.
Provence-Alpes-Côte d'Azur
Nice and Cannes anchor the nation's premier gaming-entertainment corridor, drawing extended-stay leisure travelers through integrated resort offerings. The Autorité de Régulation des Jeux En Ligne mandates digital integration standards that operators here must satisfy for concession renewal. Coastal municipalities from Antibes to Saint-Tropez concentrate premium private salon capacity targeting ultra-high-net-worth visitors from Gulf states and Asia.
Normandy
Deauville maintains historic prestige through architectural preservation and equestrian-event tie-ins that differentiate its casino tourism product. Ministry of Interior concession frameworks require minimum physical gaming capacities that lock Deauville properties into fixed asset commitments. The resort town's culinary programming, including multiple Michelin-recognized venues within casino complexes, drives gastronomy-focused itineraries from Paris and London.
Aquitaine
Biarritz and surrounding Basque Country properties leverage surf culture and thermal spa traditions to diversify beyond pure gaming visitation. Tracfin anti-money laundering protocols impose verification burdens that disproportionately affect cross-border visitor flows from Spain. The Atlantic coastline here represents secondary market positioning compared to Mediterranean rivals, with lower average daily rates but stronger seasonal occupancy consistency.
Île-de-France Periphery
Regulatory prohibitions on casino operations within Paris proper push development to outer-ring departments like Seine-et-Marne and Yvelines. FDJ United's digital-physical convergence strategies target this captive suburban market with lottery-origin brand extension into experiential hospitality. Enghien-les-Bains remains the sole legal gaming venue within the capital region's immediate orbit, operating under exceptional concession terms.
France Casino Tourism Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The French casino tourism market structures around vertically integrated hospitality groups controlling prime coastal real estate, while mid-tier operators compete through regional positioning and digital channel innovation. Three archetypes dominate: legacy resort conglomerates with Atlantic and Mediterranean portfolios, lottery-origin platforms extending into physical hospitality, and specialized regional casino-hotel chains. Consolidation pressures manifest through concession renewal barriers and capital intensity requirements that favor scale, while partnership strategies emerge around technology integration and culinary programming.
Within the integrated resort tier, Groupe Lucien Barrière and Groupe Partouche exemplify contrasting geographic and market-positioning strategies, with the former representing premium coastal concentration and the latter anchoring mid-market regional penetration. FDJ United occupies a distinct platform position, leveraging its lottery heritage into digital-physical convergence approaches. These three French-origin entities collectively illustrate how domestic regulatory relationships and concession history create competitive moats against cross-border operators lacking established Autorité de Régulation des Jeux En Ligne compliance infrastructure.
| Leading Market Players |
|---|
| Casinos Austria AG |
| Holland Casino |
| Française des Jeux (FDJ United) |
| Bet365 |
| Rank Group (Grosvenor Casinos) |
| Groupe Lucien Barrière |
| Novomatic AG |
| Allwyn |
| Groupe Partouche |
| Others |
Supply & Pricing Matrix
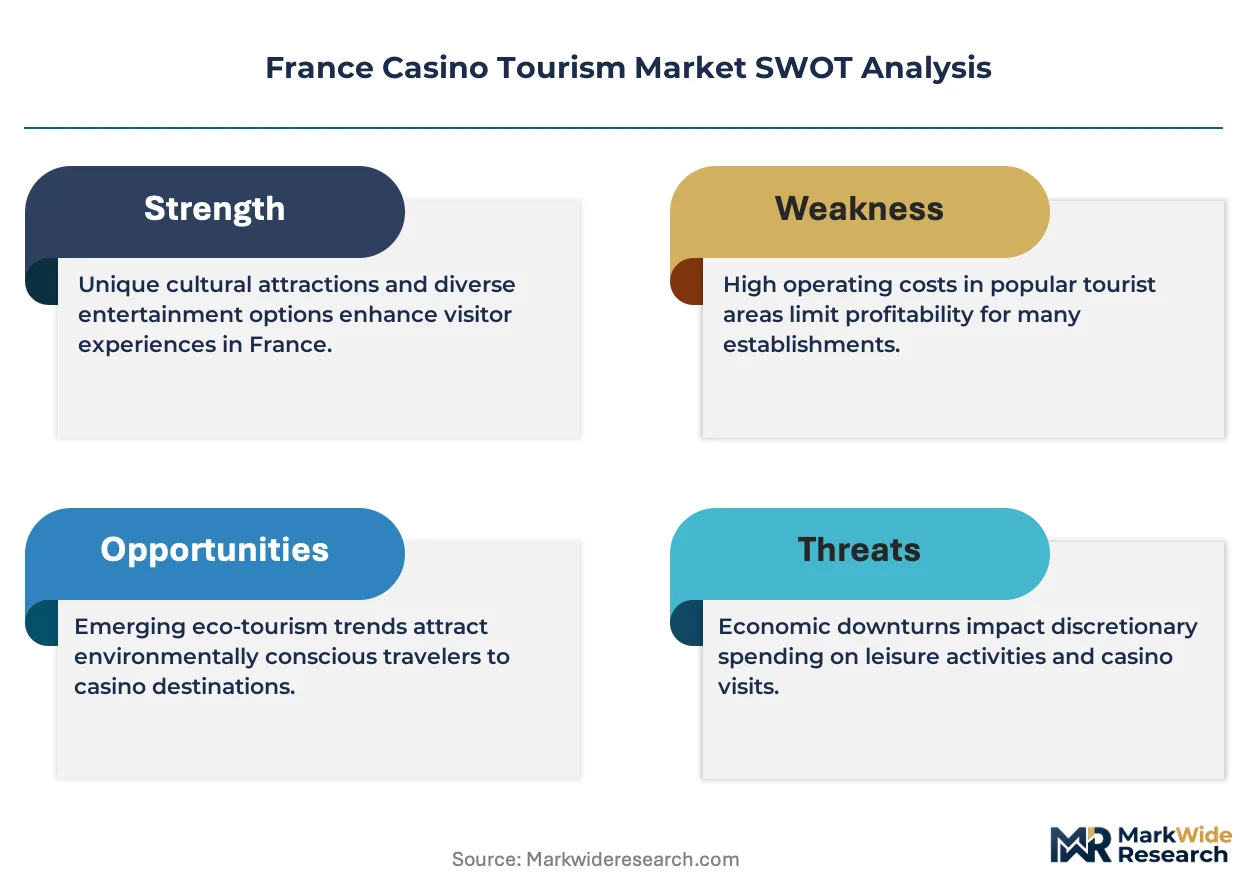
Nice and Cannes cluster capacity dynamics concentrate premium gaming-entertainment real estate, granting integrated resort operators substantial pricing power over culinary-experience bundling and private salon access that mid-tier regional competitors cannot replicate.
Pricing Analysis
High net worth individuals anchor three-tier pricing structure across premium, standard, and economy levels within French casino tourism. Price differentiation hinges on private salon exclusivity and Michelin-recognized dining certification tiers. Cost compression in mid-market regional properties is intensifying because FDJ United's digital-physical convergence strategies compress intermediary margins. Budget tourists exhibit highest price sensitivity through package tour dependency, while ultra-premium segments demonstrate lowest elasticity for bespoke concierge programming.
Supply Chain Analysis
Extended payment terms from gaming equipment manufacturers and supply-chain finance facilities sustain operator liquidity through concession renewal cycles. Hardware sourcing draws from Germany, Austria, and Japan for slot machine assemblies and biometric authentication systems. Raw material dependencies encompass precision-machined components, semiconductor chips, and specialized surveillance equipment. Single-source vulnerability concentrates in proprietary cashless gaming platform providers. Distribution runs through vertically integrated hospitality groups controlling prime Côte d'Azur and Atlantic coastal positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France casino tourism exhibits cyclical recovery characteristics as international leisure travel rebounds from regulatory compression phases, with concession renewal timelines and digital integration mandates serving as the primary cyclical driver.
For Market Incumbents: Insulate premium positioning through backward integration into proprietary mobile booking platforms and captive culinary programming partnerships. Groupe Lucien Barrière's vertically integrated hospitality portfolio demonstrates how coastal real estate control neutralizes emerging digital-native competitors. Accelerate ANJ-mandated responsible gambling protocol digitization to convert compliance burden into competitive moat against cross-border operators lacking established Tracfin relationships. For New Entrants and Emerging Players: Pursue white-space acquisition in Provence-Alpes-Côte d'Azur secondary municipalities outside saturated Nice-Cannes corridors, where underdeveloped coastal infrastructure permits integrated resort ground-floor positioning. Culinary-experience tourism represents the most penetrable segment given gastronomy-driven itinerary growth. Direct-to-consumer mobile platform development enables margin recapture from traditional travel intermediary channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with demonstrated Autorité de Régulation des Jeux En Ligne compliance infrastructure and proven concession renewal track records. Long-term viability across the analysis window hinges on regulatory relationship depth rather than pure asset scale. Monitor proposed concession duration limit revisions as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Digital-Physical Convergence Platform | FDJ United's lottery-origin brand extension demonstrates how seamless mobile-app integration captures millennial booking channel migration from traditional intermediaries. |
| Culinary Programming Partnership | Michelin-recognized restaurant integration within casino complexes drives extended-stay visitation and highest ancillary spend per occupied room in Deauville and Cannes properties. |
| Private Salon Capacity Expansion | Bespoke concierge programming for high net worth individuals commands disproportionate margin pools through personalized table limits and exclusive entertainment access. |
| Regulatory Compliance Infrastructure | ANJ-mandated algorithmic player monitoring and automated intervention triggers create competitive moats against operators lacking established French regulatory relationships. |
| Secondary Destination Development | Underdeveloped coastal municipalities from Antibes to Saint-Tropez present acquisition targets for integrated resort development outside established premium clusters. |
Research Methodology
Initial hypotheses were tested against primary input from casino operations executives, regulatory compliance officers, hospitality procurement directors, and concession renewal specialists and refined through secondary validation. Primary fieldwork encompassed structured interviews with Autorité de Régulation des Jeux En Ligne policy stakeholders and Tracfin verification specialists. Secondary sources included Ministry of Interior concession filings, ANJ regulatory guidance documents, EU Digital Services Act implementation texts, and hospitality sector trade data. Bottom-up property-level revenue modeling and top-down national tourism expenditure triangulation anchored market sizing.
Demand-supply-balance framing structured the analytical framework across the projection horizon. Segmentation dimensions encompassed casino type, tourist purpose, customer demographic, and booking channel. CAGRs were derived through trend extrapolation adjusted for regulatory intervention probability and concession renewal cycle impacts. Industry-specific forecast inputs incorporated international leisure travel recovery patterns and millennial channel preference migration toward direct digital platforms.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility affecting Gulf state and Asian visitor purchasing power would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and concession renewal timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Canada Hospitality Market
Accommodation
Casino Hotel Market
Accommodation
Capsule Hotels Market
Accommodation
Extended Stay Hotel Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Hotel Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
France Hospitality Market
Accommodation
Austria Hospitality Market
Accommodation
India Student Accommodation Market
Accommodation
United Kingdom Hospitality Market
Accommodation
US Student Accommodation Market
Accommodation
Hostel Market
Accommodation
Glamping Market
Accommodation
Italy Online Accommodation Market
Accommodation
Movie Theaters Market