
 Online Travel Agencies (Otas) Services Market | 2026-2036
Online Travel Agencies (Otas) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Online Travel Agencies (Otas) Services Market Insights
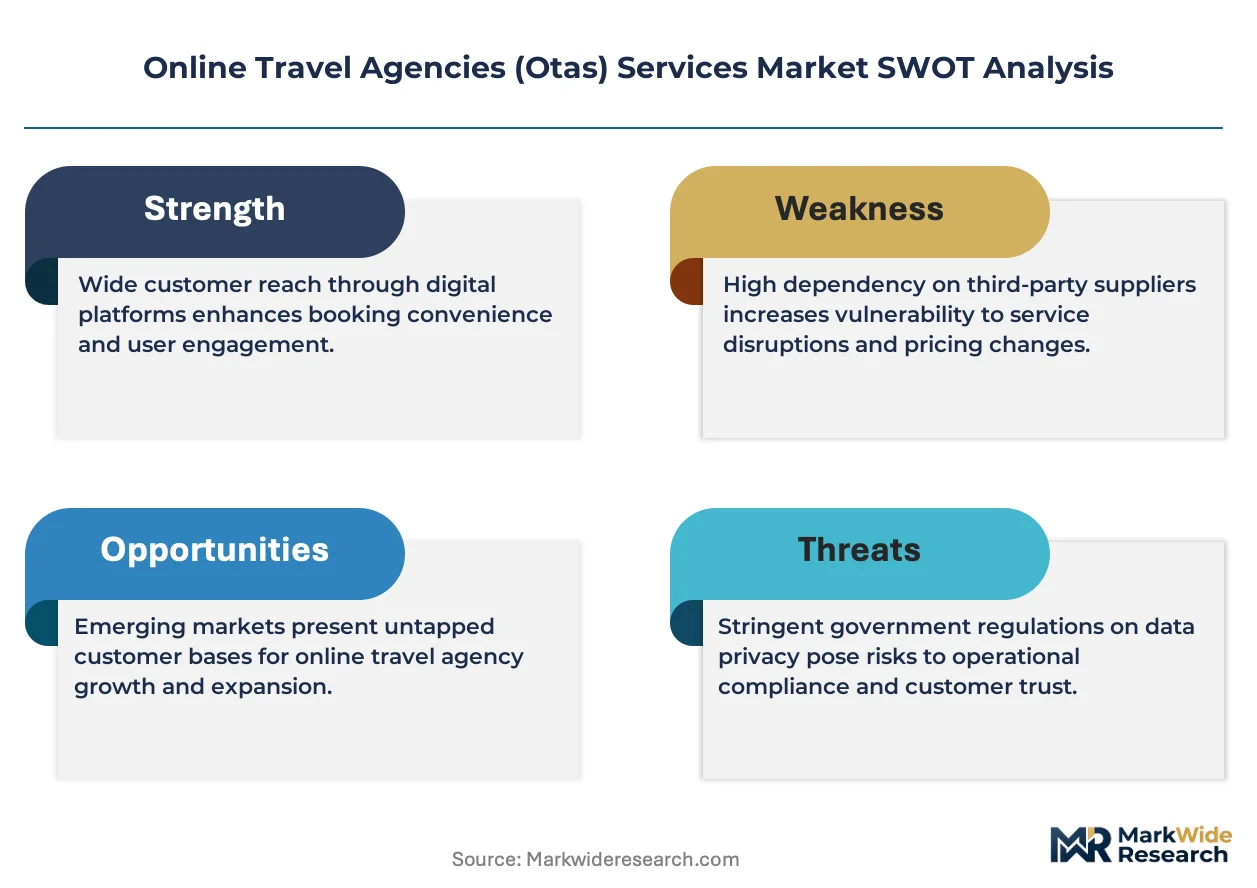
The EU Green Deal is repositioning supplier certification requirements across European travel distribution channels. Booking Holdings Inc. leverages its vast property network to anchor sustainable inventory sourcing. Expedia Group competes through technology leadership in AI-powered itinerary optimization. Trip.com Group dominates Greater China outbound flows while extending its European rail and attraction partnerships.
Online Travel Agencies (OTAs) Services constitute digital intermediation platforms that aggregate transportation, accommodation, and experience inventory through application programming interfaces and global distribution systems, processing real-time availability, dynamic pricing algorithms, and secure payment tokenization to match travelers with suppliers. Their primary commercial purpose is reducing search friction and transaction costs in fragmented hospitality and transport markets. Flight booking and hotel reservations capture the largest transaction volumes, while vacation packages concentrate margin pools through bundled commission stacking. The commission-based pricing model sustains platform economics across high-frequency segments, whereas subscription models are gaining traction among business travelers seeking guaranteed rate access and loyalty acceleration.
The EU Green Deal and GDPR shape OTA operational requirements across Europe, mandating carbon disclosure on booking interfaces and restricting cross-border passenger data flows. The FAA and DOT oversee US consumer protection standards for ticket refunds and fare transparency, directly affecting OTA liability exposure and booking workflow design. China's SAMR and MIIT regulate platform algorithm transparency and data localization for domestic OTAs operating cross-border inventory. Stakeholders must monitor regulatory divergence between carbon accounting standards and data sovereignty rules as these will determine which platforms can operate seamlessly across jurisdictions.
Market Dynamics
Generative AI is compressing itinerary planning cycles from hours to minutes, forcing OTAs to restructure their search-to-booking funnels around conversational interfaces rather than traditional filter-based navigation.
Growth Catalysts
- China's Outbound Travel Surge:Tongcheng Travel and Trip.com Group are expanding cross-border inventory partnerships, pulling inventory from European rail operators and Asian attraction aggregators into unified booking flows.
- EU Green Deal Certification Mandates:Carbon disclosure requirements on booking interfaces are creating competitive differentiation for platforms that pre-filter sustainable inventory, rewarding early compliance investments.
- Corporate Managed Booking Platforms:Business travelers are consolidating spend through centralized platforms that negotiate guaranteed rate access and accelerate loyalty tier progression.
Market Restraints
- GDPR Cross-Border Data Friction:Restrictions on passenger data flows between EU and non-EU jurisdictions complicate real-time inventory synchronization and dynamic pricing algorithms.
- Payment Tokenization Costs:PCI-DSS compliance and multi-currency settlement infrastructure impose fixed cost burdens that disproportionately squeeze mid-tier OTAs.
- Supplier Consolidation Risk:Property management system concentration among three dominant vendors limits API negotiation leverage and increases platform dependency.
Strategic Opportunities
- India's Underserved Rail-Flight Bundling:The country's fragmented intercity transport market lacks integrated booking platforms combining domestic aviation with IRCTC rail inventory.
- AI-Generated Personalized Itineraries:Convergence of large language models with real-time availability APIs enables hyper-customized multi-day packages without manual agent intervention.
- Subscription Loyalty Acceleration:Guaranteed rate access and instant elite status are displacing traditional points-based programs among frequent business travelers.
Industry Challenges
- Legacy GDS Integration Complexity:Real-time inventory synchronization between modern cloud-native platforms and decades-old mainframe distribution systems requires expensive middleware maintenance.
- Algorithm Transparency Compliance:China's SAMR mandates on recommendation engine explainability force platforms to document ranking logic that was previously proprietary black-box IP.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Travel Agencies (Otas) Services Market |
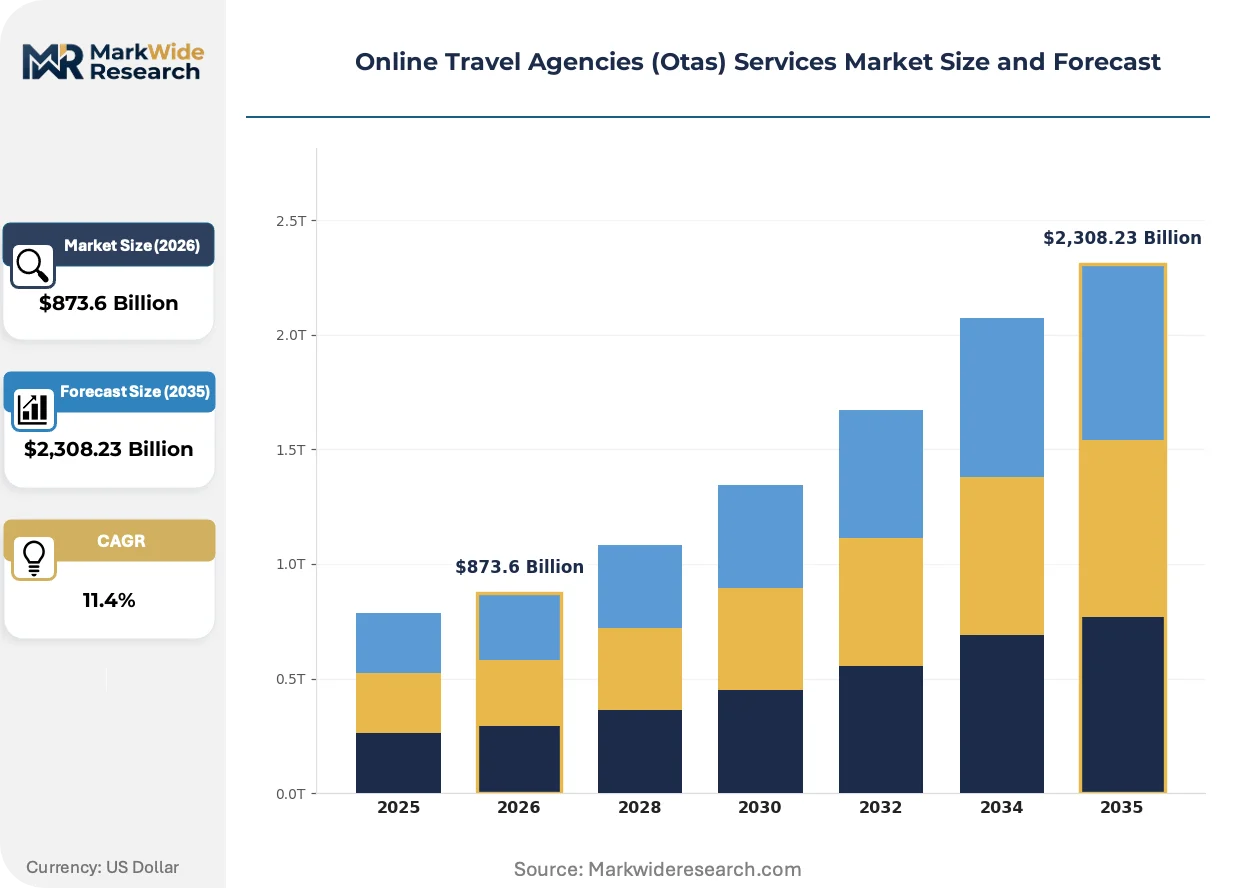
| Market Size in 2026 | $873.6 Billion |
| Market Size in 2035 | $2,308.23 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Flight Booking, Hotel Reservations, Vacation Packages, Car Rentals Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Solo Travelers Pricing Model: Commission-Based, Subscription Model, Pay-Per-Booking, Freemium End User: Individual Users, Corporates, Travel Agents, Tour Operators |
| Companies Covered | Booking Holdings Inc., Expedia Group, Trip.com Group, Airbnb Inc., MakeMyTrip Pvt. Ltd., Tongcheng Travel, TripAdvisor LLC, eDreams ODIGEO, Despegar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Travel Agencies (Otas) Services Market Trends and Innovations
Conversational search interfaces are displacing traditional filter-based booking flows, compressing the discovery-to-transaction timeline while raising the stakes for platform natural-language processing capabilities.
Generative AI itinerary builders are electrifying how travelers discover multi-stop experiences. These systems parse unstructured preferences—"beach towns with direct train connections"—into bookable sequences. Leisure travelers under 35 are adopting these tools at the fastest clip. The technology is electrifying margin capture by bundling previously unconnected inventory segments into single-transaction packages.
The EU Green Deal's carbon disclosure mandates are reshaping supplier certification workflows. Properties must now document energy ratings and waste management protocols to maintain OTA listing priority. European urban inventory faces the steepest compliance curve, with Amsterdam and Barcelona city governments already requiring verified sustainability credentials for short-term rental licensing.
Corporate procurement departments are consolidating travel spend through centralized booking platforms that negotiate direct supplier contracts. Traditional agent-mediated business travel is contracting fastest in the US and UK, where procurement functions have matured travel category management. These platforms extract rate guarantees and instant elite status in exchange for volume commitments, compressing commission pools for intermediaries without direct corporate relationships.
Online Travel Agencies (Otas) Services Market Segmentation
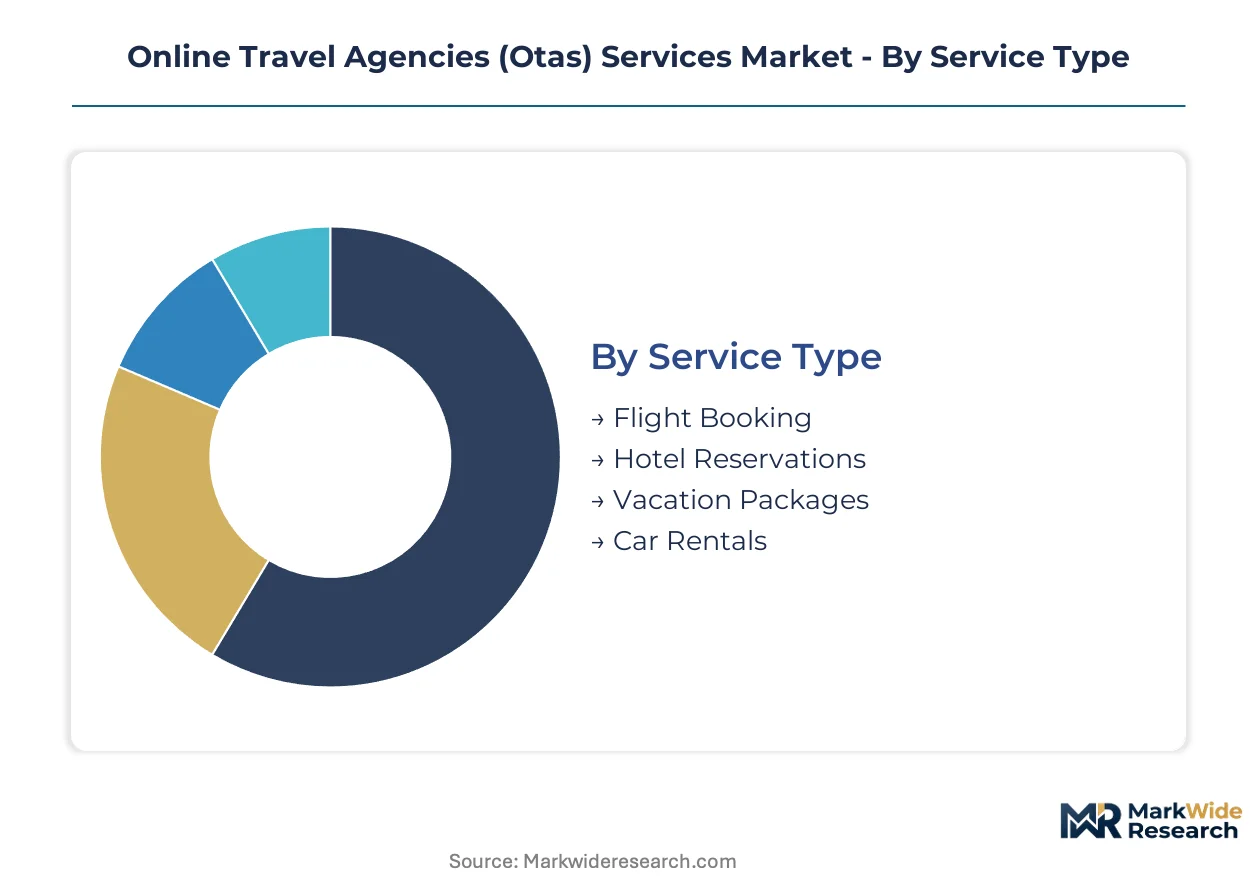
Segmentation in online travel agencies services reveals divergent margin structures and technology requirements across service lines. Flight and hotel transactions drive volume liquidity while vacation packages concentrate profitability through bundled inventory. Customer mix determines platform architecture investments, with corporate segments demanding API-first integration and leisure segments favoring mobile-native discovery.
Service Type:
Volume concentrates in high-frequency, low-margin transactions while premium bundles capture disproportionate profitability through commission stacking.
- Flight Booking:Real-time GDS integration processes availability queries across hundreds of carriers simultaneously. China's outbound routes and European short-haul segments generate the highest query-per-booking ratios, straining infrastructure costs during peak windows.
- Hotel Reservations:Property management system APIs synchronize room inventory with dynamic pricing engines that adjust rates multiple times hourly. Urban business corridors in Germany and boutique leisure clusters in Portugal command the steepest rate volatility, rewarding platforms with predictive demand modeling.
- Vacation Packages:Bundled multi-component itineraries combine transportation, accommodation, and experience inventory into single-transaction offerings.
- Car Rentals:Fleet availability APIs integrate with airline arrival data to surface contextual ground transportation options.
Today's leader: Hotel Reservations. Tomorrow's challenger: Vacation Packages.
Customer Type:
Procurement centralization separates enterprise-grade platforms from consumer-facing interfaces, with divergent loyalty mechanics and rate negotiation frameworks.
- Leisure Travelers:Mobile-first discovery interfaces prioritize visual content and social proof signals over functional efficiency. Southeast Asian millennials and European retirees represent the fastest-expanding cohorts, driving investments in localized payment methods and multilingual conversational AI.
- Business Travelers:Managed booking platforms enforce policy compliance while capturing negotiated rate access and accelerated loyalty tier progression. Procurement departments in UK financial services and German manufacturing consolidate spend through centralized contracts that extract guaranteed inventory access.
- Group Travelers:Block booking workflows coordinate multi-passenger itineraries with consolidated payment and amendment protocols.
- Solo Travelers:Single-occupancy inventory filters and community-driven safety ratings address distinct risk-assessment behaviors.
Enterprise procurement locks in Business Travelers. Solo Travelers are gaining share fastest through safety-centric platform differentiation.
Pricing Model:
Revenue predictability separates subscription platforms from transaction-dependent competitors, with hybrid models emerging at the intersection.
- Commission-Based:Percentage-of-transaction fees sustain platform economics across high-frequency segments with minimal upfront user commitment.
- Subscription Model:Annual or monthly fees unlock guaranteed rate access, waived amendment fees, and instant elite status recognition. Frequent business travelers in US technology sectors and UK professional services adopt these programs fastest, displacing traditional points-based loyalty structures.
- Pay-Per-Booking:Flat fees per completed transaction reduce friction for infrequent users without recurring commitment.
- Freemium:Tiered feature access converts free users through premium functionality gates including price prediction and flexible cancellation.
Commission-Based still dominates transaction counts. Subscription Model climbs the fastest as procurement departments seek spend predictability.
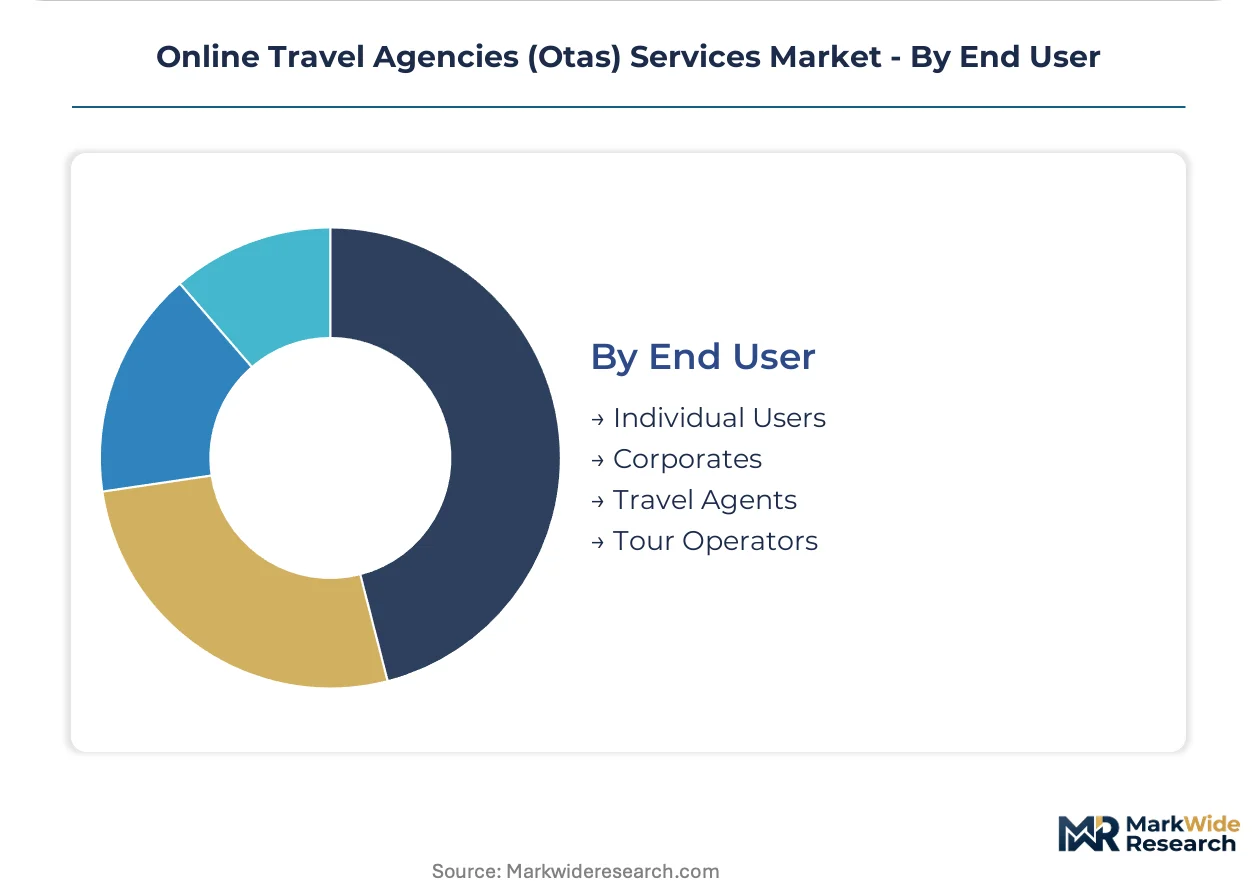
End User:
Intermediation depth determines platform architecture, with direct-to-consumer interfaces diverging sharply from B2B wholesale tooling.
- Individual Users:Consumer-facing applications optimize for discovery speed and payment friction reduction. Mobile penetration in India and Indonesia drives platform investments in lightweight Android-native builds and regional wallet integrations.
- Corporates:Enterprise travel management platforms integrate with expense systems and policy engines to enforce pre-trip authorization. Multinational headquarters in Netherlands and Singapore demand multi-entity reporting and consolidated invoicing across operating subsidiaries.
- Travel Agents:Agent desktops provide override capabilities and manual intervention tools for complex itinerary exceptions.
- Tour Operators:Wholesale contracting interfaces negotiate block inventory commitments with extended payment terms and exclusive distribution windows.
Corporates anchor revenue stability. Tour Operators are expanding fastest through exclusive inventory partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in cloud infrastructure and machine learning anchor geographic platform development. Regulatory divergence across carbon disclosure and data sovereignty rules fragments cross-border operational models. City-level tourism clusters concentrate inventory sourcing relationships and supplier certification workflows.
United States
Corporate procurement departments in New York and Chicago consolidate travel spend through managed booking platforms. FAA and DOT consumer protection standards govern ticket refund policies and fare transparency requirements. Austin and Seattle technology corridors host cloud-native platform engineering teams building conversational AI search interfaces.
Germany
Industrial manufacturing headquarters in Munich and Stuttgart drive enterprise travel demand with centralized policy enforcement. EU Green Deal carbon disclosure mandates require booking interface integration of verified sustainability credentials. Frankfurt's financial services cluster negotiates guaranteed rate access through direct supplier contracts.
China
SAMR algorithm transparency mandates and MIIT data localization rules shape cross-border inventory platform architecture. Outbound travel demand from Shanghai and Beijing concentrates in European rail and Asian attraction partnerships. Shenzhen's mobile payment infrastructure enables seamless wallet integration for domestic booking flows.
United Kingdom
GDPR cross-border data friction complicates real-time inventory synchronization with non-EU jurisdictions. London's financial services procurement functions mature travel category management through centralized booking platforms. Manchester and Edinburgh corporate hubs accelerate adoption of subscription loyalty programs with instant elite status.
India
Fragmented intercity transport markets create whitespace for integrated rail-flight bundling platforms. IRCTC rail inventory APIs remain underexploited by aviation-focused intermediaries. Bangalore and Hyderabad technology centers develop lightweight Android-native builds for mobile-first leisure discovery.
Online Travel Agencies (Otas) Services Market Competitive Landscape
Capital-heavy inventory aggregators compete with asset-light technology platforms for traveler acquisition economics. The vendor structure concentrates among vertically integrated global platforms with direct supplier contracting relationships. Three archetypes dominate: full-stack inventory owners, technology-led intermediaries, and regional specialists with localized payment integration. Competitive dynamics center on exclusive supplier partnerships and conversational AI capability acquisition.
Within the full-stack inventory tier, Booking Holdings Inc. and Expedia Group occupy positions defined by property network scale and technology infrastructure depth. Trip.com Group exemplifies the regional-to-global expansion archetype, leveraging Greater China outbound demand to build cross-border rail and attraction partnerships. These three platforms anchor the competitive structure through divergent geographic prioritization and supplier relationship models.
| Leading Market Players |
|---|
| Booking Holdings Inc. |
| Expedia Group |
| Trip.com Group |
| Airbnb Inc. |
| MakeMyTrip Pvt. Ltd. |
| Tongcheng Travel |
| TripAdvisor LLC |
| eDreams ODIGEO |
| Despegar |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure engineers concentrated in Seattle and Bangalore create labor-cost differentials that widen pricing-tier spreads between premium AI-enabled platforms and basic transaction-only services. Commission compression in European markets forces mid-tier OTAs to absorb PCI-DSS compliance costs while subscription models in North America extract guaranteed rate premiums from procurement departments.
Pricing Analysis
Commission-based transaction fees anchor platform economics across high-frequency flight and hotel segments, while subscription models unlock guaranteed rate access and instant elite status for corporate travelers. Price differentiation rests on AI-powered itinerary optimization capabilities and EU Green Deal sustainability certification tiers. Cost compression in the mid-market intensifies as payment tokenization infrastructure burdens disproportionately squeeze smaller platforms. Leisure travelers in Southeast Asia exhibit highest price sensitivity, whereas UK financial services procurement departments prioritize policy compliance over rate minimization.
Supply Chain Analysis
Cross-border data transmission costs and multi-currency settlement complexity elevate operational overhead for inventory synchronization between EU and non-EU jurisdictions. Supply concentration centers on three dominant property management system vendors in the United States, Germany, and China, with API negotiation leverage tilting toward platform consolidators. Raw material dependencies include cloud compute capacity, real-time GDS connectivity, and secure payment processing infrastructure. Single-source vulnerability in legacy GDS mainframe systems threatens real-time availability accuracy. Distribution runs through direct supplier contracting for enterprise accounts and aggregated marketplace interfaces for leisure segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as corporate procurement departments shift demand toward premium platforms with guaranteed inventory access and AI-powered policy enforcement.
For Market Incumbents: Acquire conversational AI engineering teams to compress itinerary planning cycles before emerging LLM-native entrants capture leisure traveler discovery flows. Deepen direct supplier contracting relationships with European rail operators and Asian attraction aggregators to defend margin position against cross-border inventory specialists. Reinforce API-first architecture investments to serve procurement departments demanding seamless expense system integration. For New Entrants and Emerging Players: Enter via India's fragmented intercity transport market, where IRCTC rail inventory remains underexploited by aviation-focused incumbents. Target solo traveler safety-centric platform differentiation in Southeast Asia, where community-driven risk assessment tools command premium positioning. Pursue mobile-native Android builds with regional wallet integration as the primary go-to-market angle in Indonesia and Philippines leisure segments. For Investors and Strategic Acquirers: Technology-focused private equity firms are the most active acquirer in this space, consolidating mid-tier OTAs with proprietary inventory relationships but subscale AI capabilities. Long-term viability favors platforms with direct European rail partnerships and SAMR-compliant algorithm transparency documentation. Watch EU Green Deal enforcement intensity as the inflection indicator for sustainable inventory certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Conversational AI Platform Integration | Generative LLM deployment compresses Trip.com Group's search-to-booking funnel from hours to minutes. |
| EU Green Deal Certification Program | Sustainability credential integration enables Booking Holdings Inc. to pre-filter Amsterdam and Barcelona inventory. |
| Corporate Direct Contracting Expansion | Guaranteed rate access agreements with Munich manufacturing headquarters displace traditional agent mediation. |
| Rail-Flight Bundling Capability Buildout | IRCTC API integration captures India's undersupplied intercity transport coordination whitespace. |
| Subscription Loyalty Program Launch | Instant elite status recognition accelerates adoption among US technology sector frequent travelers. |
Research Methodology
Direct dialogue with OTA platform executives, corporate travel procurement managers, property management system vendors, and airline distribution strategists grounded qualitative findings in operational reality. Secondary validation drew from FAA consumer protection filings, EU Green Deal implementation guidance, SAMR algorithm transparency directives, GDS connectivity disclosures, and corporate travel management RFP documentation. Bottom-up transaction volume modeling and top-down market sizing triangulated value estimates across service type and customer segments.
Bottom-up modeling aggregated individual transaction economics across flight booking, hotel reservation, and vacation package lines, while top-down analysis tracked aggregate commission pool migration toward subscription platforms. Segmentation dimensions included service type, customer category, pricing model, and end-user intermediation depth. CAGRs derived from trend extrapolation of China's outbound travel surge, EU carbon disclosure mandate compliance curves, and corporate procurement centralization patterns. Forecast inputs incorporated real-time GDS query volume trajectories and mobile payment penetration rates in target geographies.
Inputs from regulatory filings and platform engineering disclosures were available through the study window; gaps in private company transaction-level data introduce uncertainty bands around mid-tier OTA market share estimates. Forecasts reflect assumptions regarding SAMR enforcement consistency and EU Green Deal certification timeline adherence. A model refresh is warranted upon material change in GDPR cross-border data friction resolution or FAA refund policy reinterpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market