
 Canada Hospitality Market | 2026-2036
Canada Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Hospitality Market Insights
Subscription-based loyalty programs and membership-driven booking platforms is repositioning how Canadian hospitality firms monetize repeat visitation. Marriott International leverages its Bonvoy ecosystem to sustain direct channel dominance and reduce online travel agent dependency. Fairmont Hotels and Resorts anchors its competitive stance through heritage property portfolios in Banff and Lake Louise. Coast Hotels specializes in mid-market positioning across secondary Canadian cities where brand density remains lower.
Canada hospitality encompasses lodging, foodservice, beverage, and event hosting operations governed by provincial health codes, fire safety standards, and municipal zoning bylaws, with properties ranging from full-service resorts to limited-service roadside inns. The sector's primary commercial purpose is delivering temporary accommodation and prepared food experiences to transient guests while generating revenue through ancillary services. Restaurant and hotel service types capture the bulk of revenue pools, with bar operations yielding higher per-capita margins in urban entertainment districts. Leisure travelers represent the fastest-expanding end-user category, while direct bookings are displacing online travel agent share as property-level digital investment rises.
Health Canada sets national food safety and cannabis hospitality guidelines, while provincial regulators including Ontario's Alcohol and Gaming Commission and British Columbia's Liquor and Cannabis Regulation Branch enforce sector-specific licensing standards that constrain market entry timelines. The Canadian Hotel Association coordinates industry compliance advocacy across these fragmented regulatory landscapes. Stakeholders must monitor evolving provincial short-term rental restrictions and carbon disclosure mandates that threaten to reshape capital allocation decisions for new property development.
Market Dynamics
Provincial short-term rental restrictions and carbon disclosure mandates are forcing capital reallocation decisions across Canadian hospitality development pipelines, compressing project timelines and elevating compliance costs before ground breaks.
Growth Catalysts
- Leisure Travel Concentration:Mountain tourism corridors in British Columbia and experiential property demand in Ontario's urban gateways are pulling investment toward resort and lifestyle assets.
- Bonvoy Ecosystem Expansion:Subscription-based loyalty architectures are reducing online travel agent dependency and capturing direct booking share through membership-driven platforms.
- Liquor Licensing Reforms:Provincial regulators including Ontario's Alcohol and Gaming Commission are streamlining beverage service approvals, accelerating hospitality venue openings.
Market Restraints
- Labor Cost Compression:Minimum wage escalations across Canadian provinces are narrowing operating margins in full-service restaurant and hotel segments.
- Supply Concentration Risk:Construction material and specialized hospitality equipment sourcing clusters in Asian manufacturing hubs expose development timelines to shipping volatility.
- Regulatory Fragmentation:Health Canada's national food safety protocols layer atop municipal zoning bylaws and provincial fire codes, multiplying compliance touchpoints.
Strategic Opportunities
- Secondary City Penetration:Mid-market positioning in Canadian cities below top-five metropolitan areas offers brand density advantages and lower competitive pressure.
- Cannabis Hospitality Integration:Health Canada's consumption venue guidelines and provincial licensing frameworks are opening regulated consumption lounge formats.
- Carbon Disclosure Alignment:Municipal green building mandates are creating first-mover positioning for properties achieving energy certification ahead of compliance deadlines.
Industry Challenges
- Digital Talent Scarcity:Property-level technology investment requires hospitality operators to compete with tech sector wages for data analytics and platform management skills.
- Legacy System Integration:Independent and heritage properties face capital intensity barriers when retrofitting property management systems to connect with modern distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Hospitality Market |
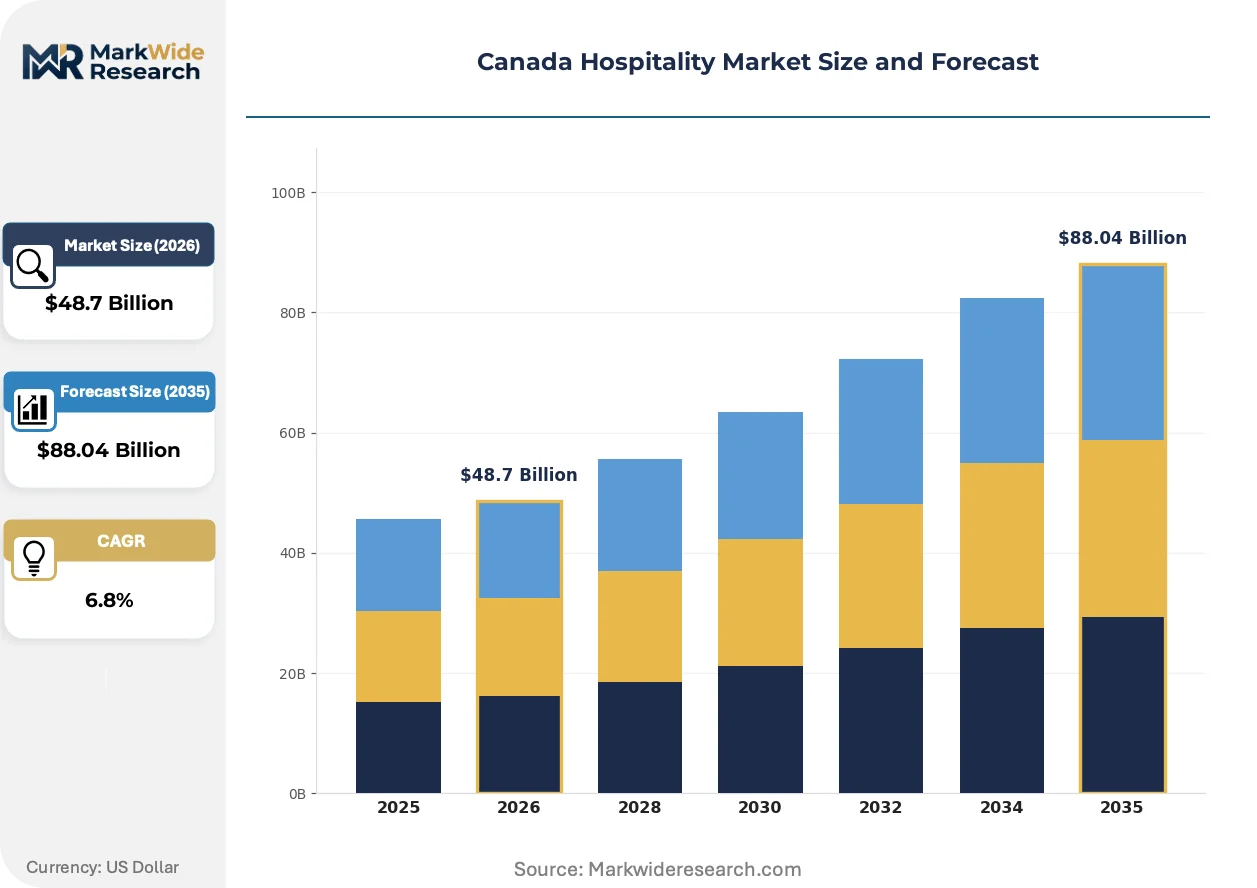
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Restaurant, Hotel, Bar, Catering End User: Leisure Travelers, Business Travelers, Event Planners, Tour Operators Distribution Channel: Online Travel Agents, Direct Bookings, Travel Agencies, Third-Party Websites Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Marriott International, Hilton Worldwide, Accor, InterContinental Hotels Group, Wyndham Hotels & Resorts, Four Seasons Hotels and Resorts, Fairmont Hotels & Resorts, Best Western Hotels & Resorts, Coast Hotels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Hospitality Market Trends and Innovations
Direct booking platforms and experiential programming are compressing traditional distribution intermediaries while elevating guest data ownership as a competitive asset.
Mobile-first property management systems are decentralizing front-desk operations across Canadian hotel portfolios. Independent operators and mid-market chains are adopting cloud-based platforms at accelerated replacement cycles. This technology is decentralizing service delivery nodes, enabling staff to operate across multiple guest touchpoints without fixed counter infrastructure.
Ontario's Alcohol and Gaming Commission has introduced streamlined liquor licensing pathways for hospitality venues with enhanced food service components. The reform compresses approval timelines from months to weeks for qualifying applicants. Urban entertainment district operators are responding by expanding bar-forward concepts with elevated culinary programming.
Experience-driven booking behavior is displacing price-first comparison shopping among leisure travelers. Destination properties in British Columbia's mountain corridors are capturing demand through activity packaging and localized programming rather than rate parity. This shift is most visible in resort segments where guest spend per stay now exceeds room revenue through ancillary experience sales.
Canada Hospitality Market Segmentation
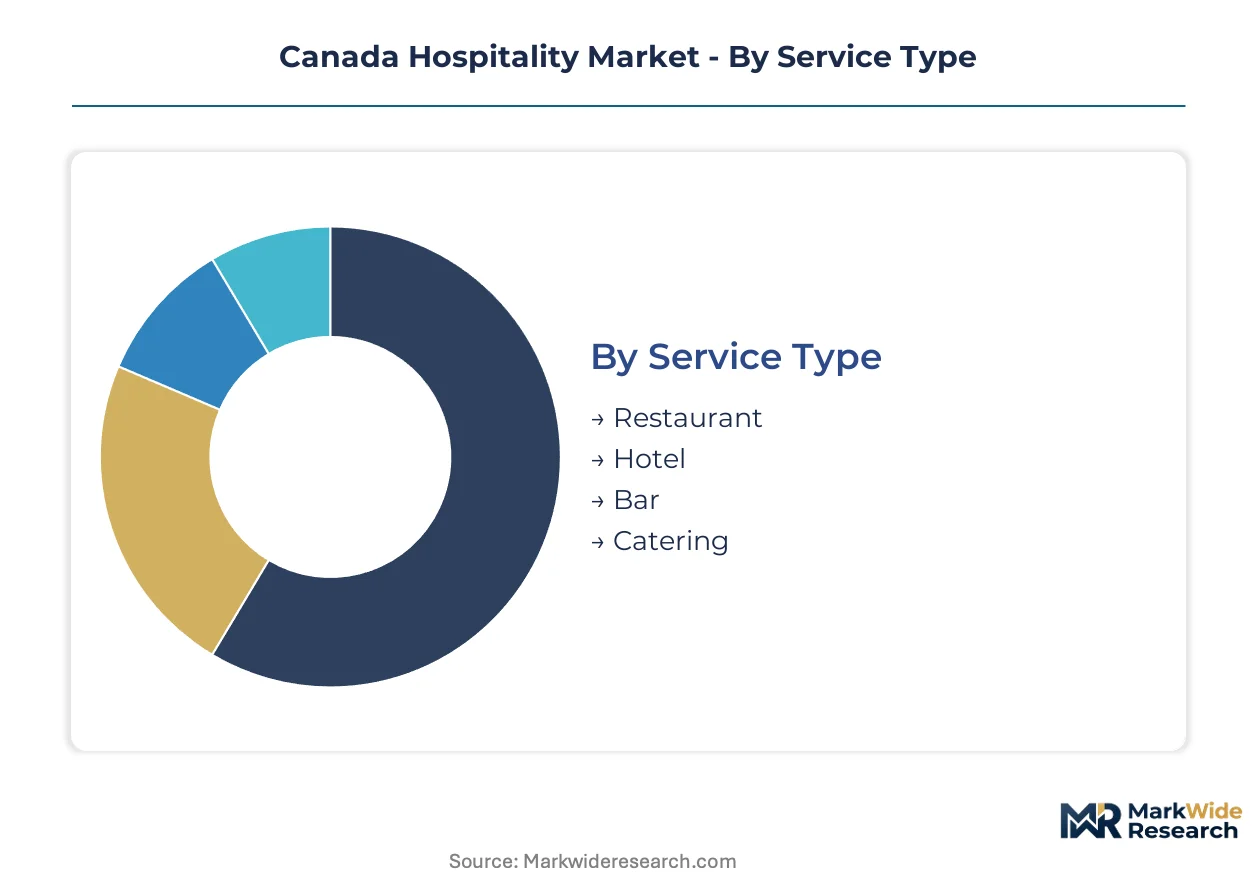
Segmentation in Canadian hospitality reveals divergent margin structures and capital intensity requirements across service formats. Distinct buyer behaviors between leisure and business travelers reshape distribution investments. Provincial regulatory frameworks further stratify operational compliance costs across price tiers.
Service Type:
Capital deployment intensity and labor cost exposure vary sharply across service formats, driving portfolio composition decisions for multi-brand operators.
- Restaurant:Full-service and quick-service formats generate recurring local revenue streams independent of accommodation demand. Ontario's urban entertainment districts concentrate independent restaurant development where liquor licensing reforms from the Alcohol and Gaming Commission accelerate venue openings.
- Hotel:Full-service resorts and limited-service properties anchor the sector's revenue base with the highest fixed-cost structures. Mountain tourism corridors in British Columbia pull investment toward resort assets where experiential programming now exceeds room revenue contribution.
- Bar:Beverage-forward concepts yield elevated per-capita margins in dense urban markets. Health Canada food safety protocols layer compliance requirements onto operational design.
- Catering:Event-driven revenue concentrates around corporate contracts and wedding destinations. Seasonal demand fluctuation requires flexible labor models.
Volume sits with Hotel; growth tilts toward Restaurant.
End User:
Booking behavior and ancillary spend patterns diverge materially across traveler motivations, reshaping property-level service design.
- Leisure Travelers:Experience-first booking decisions now displace rate comparison in destination markets. British Columbia's mountain corridors capture this demand through activity packaging and localized programming rather than price parity.
- Business Travelers:Corporate negotiated rates and loyalty program enrollment sustain weekday occupancy in urban gateway properties. Direct booking platforms capture disproportionate share from this segment.
- Event Planners:Group block commitments and catering minimums stabilize revenue forecasting for full-service properties. Municipal convention infrastructure investments in Toronto and Vancouver expand addressable demand.
- Tour Operators:Volume contracting and seasonal block purchasing concentrate demand in peak periods. Commission structures pressure net revenue realization.
Business Travelers anchor current volume; Leisure Travelers are climbing the fastest.
Distribution Channel:
Channel mix directly determines customer acquisition costs and guest data ownership, with technology investment now separating competitive positions.
- Online Travel Agents:Aggregator platforms maintain visibility dominance for independent properties lacking brand recognition. Commission structures extract 15-25 percent of booking value.
- Direct Bookings:Property-level digital investment and loyalty program enrollment reduce intermediary dependency. Marriott's Bonvoy ecosystem exemplifies this channel capture strategy.
- Travel Agencies:Corporate and luxury leisure segments retain agency intermediation for complex multi-destination itineraries. Service fees supplement commission revenue models.
- Third-Party Websites:Metasearch and review platforms influence consideration-stage decisions without completing transactions. Reputation management commands dedicated operational resources.
Online Travel Agents still hold volume; Direct Bookings are gaining share fastest.
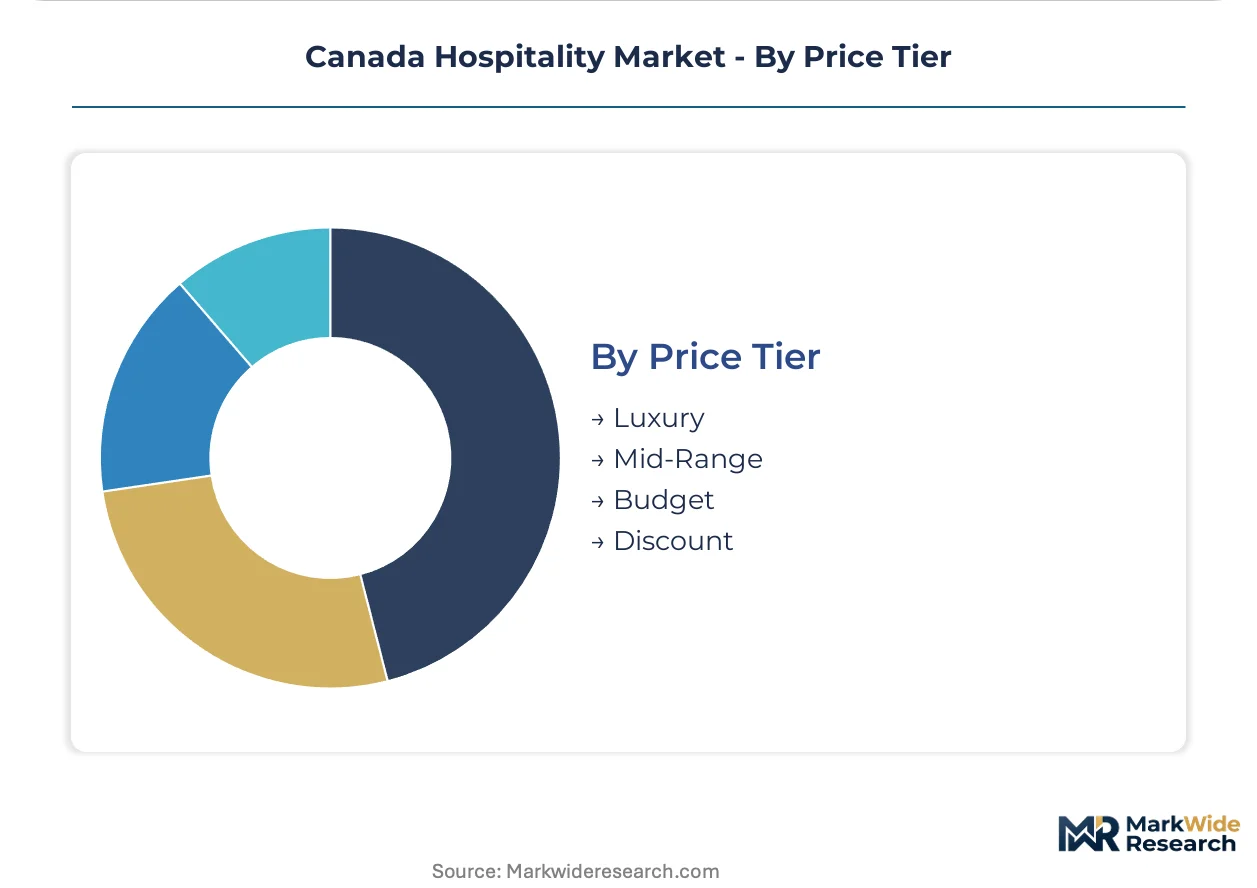
Price Tier:
Brand positioning determines development capital requirements and operating margin structures, with mid-market segments offering density advantages in secondary cities.
- Luxury:Heritage assets and full-service resorts command rate premiums through experiential differentiation and location scarcity. Fairmont's Banff and Lake Louise properties anchor this positioning.
- Mid-Range:Select-service and extended-stay formats balance amenity provision with labor efficiency. Coast Hotels targets secondary Canadian cities where competitive density remains lower.
- Budget:Limited-service roadside and airport properties prioritize cost discipline over experiential programming. Franchise models dominate ownership structures.
- Discount:Economy lodging and hostel formats compete on absolute price with minimal service inclusion. Short-term rental competition from unregulated supply compresses pricing power.
Mid-Range captures current development volume; Luxury shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vancouver anchors Canadian hospitality investment through its Pacific gateway positioning and mountain tourism corridor connectivity. Provincial regulatory frameworks and municipal zoning bylaws reshape capital deployment across five distinct regional markets.
Ontario
Toronto's urban gateway concentration and Ottawa's government-driven corporate demand sustain weekday occupancy in full-service properties. Ontario's Alcohol and Gaming Commission streamlines liquor licensing pathways for hospitality venues with enhanced food service components. The Greater Toronto Area concentrates mid-market development where Coast Hotels targets secondary municipalities with lower brand density.
British Columbia
Mountain tourism corridors in Whistler and Banff-adjacent regions pull investment toward experiential resort assets. Health Canada food safety protocols layer compliance requirements onto operational design for properties across the province. Vancouver's entertainment district operators expand bar-forward concepts following provincial beverage service reforms.
Alberta
Calgary's corporate energy sector demand and Edmonton's festival-driven leisure visitation create dual revenue anchors. Municipal zoning bylaws in both cities constrain short-term rental supply, protecting traditional hospitality pricing power. The Rocky Mountain corridor extending into Alberta captures destination resort investment focused on activity packaging.
Quebec
Montreal's cultural tourism positioning and Quebec City's heritage asset concentration sustain experiential property demand. Provincial liquor licensing frameworks operate alongside Health Canada national guidelines, multiplying compliance touchpoints for operators. The Laurentians mountain region concentrates seasonal resort development targeting leisure travelers.
Atlantic Canada
Halifax's port city positioning and St. John's offshore energy corporate demand anchor hospitality investment in smaller urban centers. Municipal carbon disclosure mandates in Nova Scotia and Newfoundland reshape capital allocation decisions for new property development. Secondary city markets here offer mid-market positioning advantages with reduced competitive pressure.
Canada Hospitality Market Competitive Landscape
Capital-heavy asset owners compete with asset-light brand licensors across tiered market positions. Full-service resort operators and select-service mid-market chains divide the revenue pool, with loyalty program scale determining direct booking capture. Three archetypes dominate: global brand ecosystems with subscription loyalty architectures, heritage property portfolios anchored in destination markets, and regional mid-market specialists targeting secondary cities. Competitive moves concentrate on M&A-driven portfolio diversification and technology licensing partnerships that compress online travel agent dependency.
Within the global brand ecosystem tier, Marriott International and Hilton Worldwide exemplify loyalty-driven direct channel strategies. Fairmont Hotels & Resorts occupies a heritage-anchored position concentrated in mountain destination markets. Coast Hotels represents the regional specialist archetype with mid-market positioning across secondary Canadian municipalities. These three patterns illustrate how scale, location scarcity, and geographic focus separate competitive positions in constrained development environments.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide |
| Accor |
| InterContinental Hotels Group |
| Wyndham Hotels & Resorts |
| Four Seasons Hotels and Resorts |
| Fairmont Hotels & Resorts |
| Best Western Hotels & Resorts |
| Coast Hotels |
| Others |
Pricing and Supply Chain Analysis
Leisure traveler concentration in British Columbia's mountain corridors and Ontario's urban gateways anchors value-based pricing for experiential resort assets. Rate premiums now attach to activity packaging and localized programming rather than room nights alone.
Pricing Analysis
Value-based pricing tied to guest experience throughput now dominates resort and lifestyle property segments. Three-tier pricing structure across premium, standard, and economy levels separates Fairmont's heritage assets from Coast Hotels' mid-market positioning and limited-service roadside properties. Price differentiation rests on experiential programming depth and loyalty program enrollment status. Cost compression in full-service restaurant segments is intensifying because minimum wage escalations across Canadian provinces are narrowing operating margins.
Supply Chain Analysis
Certification requirements under Health Canada food safety protocols and provincial liquor licensing frameworks gate supplier qualification for hospitality operators. Construction materials and specialized hospitality equipment draw from China, South Korea, and Germany, creating dependency on Asian manufacturing hubs for development timelines. Key inputs include foodservice equipment, furniture fixtures, and technology systems. Single-source vulnerability runs through concentrated shipping lanes connecting Pacific ports to interior development sites. Distribution runs through regional procurement consortia coordinated by the Canadian Hotel Association.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian hospitality is consolidating around loyalty scale and direct channel control, with regulatory compliance costs forcing independent operators toward brand affiliation or exit.
For Market Incumbents: Cement direct booking dominance through subscription loyalty architectures that reduce online travel agent dependency. Expand experiential programming in British Columbia mountain corridors where guest spend per stay now exceeds room revenue. Invest in mobile-first property management systems to decentralize front-desk operations and compress labor costs. Vertical integration into in-house activity packaging protects margin from third-party tour operator commissions. For New Entrants and Emerging Players: The price-point gap between Fairmont's luxury heritage assets and budget limited-service properties creates white-space opportunity for mid-market lifestyle concepts. Target secondary Canadian cities below top-five metropolitan areas where Coast Hotels has established presence but brand density remains lower. Pursue streamlined liquor licensing pathways through Ontario's Alcohol and Gaming Commission for food-forward beverage concepts. Launch with cannabis hospitality integration under Health Canada consumption venue guidelines as a differentiated format. For Investors and Strategic Acquirers: The window for entry favors asset-light brand licensors with loyalty platform scale over capital-heavy property owners. Mid-market portfolios in secondary municipalities offer consolidation targets as regulatory compliance costs pressure independent operators. Watch provincial short-term rental restrictions as the inflection signal that determines pricing power recovery timelines for traditional hospitality assets.| Strategic Initiative | Industry Significance |
|---|---|
| Loyalty Platform Integration | Marriott's Bonvoy ecosystem reduces online travel agent commission exposure through direct channel capture. |
| Experiential Programming Expansion | Activity packaging in Whistler and Banff-adjacent regions now generates ancillary revenue exceeding room rates. |
| Mobile-First Property Management | Cloud-based platforms enable staff to operate across multiple guest touchpoints without fixed counter infrastructure. |
| Secondary City Penetration | Coast Hotels targets municipalities with lower competitive density where mid-market positioning yields density advantages. |
| Cannabis Hospitality Licensing | Health Canada guidelines and provincial frameworks open regulated consumption lounge formats for first-mover positioning. |
Research Methodology
Health Canada regulatory filings, provincial liquor licensing databases, and Canadian Hotel Association industry reports formed the secondary backbone of this analysis. Primary interviews with hotel operations directors, provincial regulatory affairs leads, foodservice procurement managers, and loyalty program strategists validated demand assumptions. Bottom-up property-level data triangulated against top-down provincial hospitality revenue estimates.
Bottom-up modeling of property-level revenue pools across service types, end-user segments, distribution channels, and price tiers anchored the forecast framework. Segmentation dimensions included service format, traveler motivation, booking channel, and brand positioning tier across the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention timing and capital deployment cycle compression. Labor cost escalation indices and carbon disclosure mandate implementation schedules served as key forecast inputs.
Underlying measurement precision varies by segment; hotel and restaurant revenue pools carry tighter precision than emerging cannabis hospitality formats. Forecasts reflect assumptions about provincial short-term rental restriction enforcement and liquor licensing reform adoption. A model refresh is warranted upon material change in Health Canada food safety protocol amendments or municipal carbon disclosure mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
US Student Accommodation Market
Accommodation
United States Online Accommodation Market
Accommodation
Germany Student Accommodation Market
Accommodation
Croatia Hospitality Market
Accommodation
Capsule Hotels Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Youth Summer Camp Market
Accommodation
Africa Hotel Market
Accommodation
Asia-Pacific Student Accommodation Market
Accommodation
Sweden Hospitality Market
Accommodation
Europe Student Accommodation Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Underwater Hotels Market
Accommodation
In-Flight Catering Services Market
Accommodation
China Tourism and Hotel Market
Accommodation
Sri Lanka Hospitality Industry Market