
 Flash-Based Array Market | 2026-2036
Flash-Based Array Market Size, Share, and Industry Trends Forecast 2026-2036
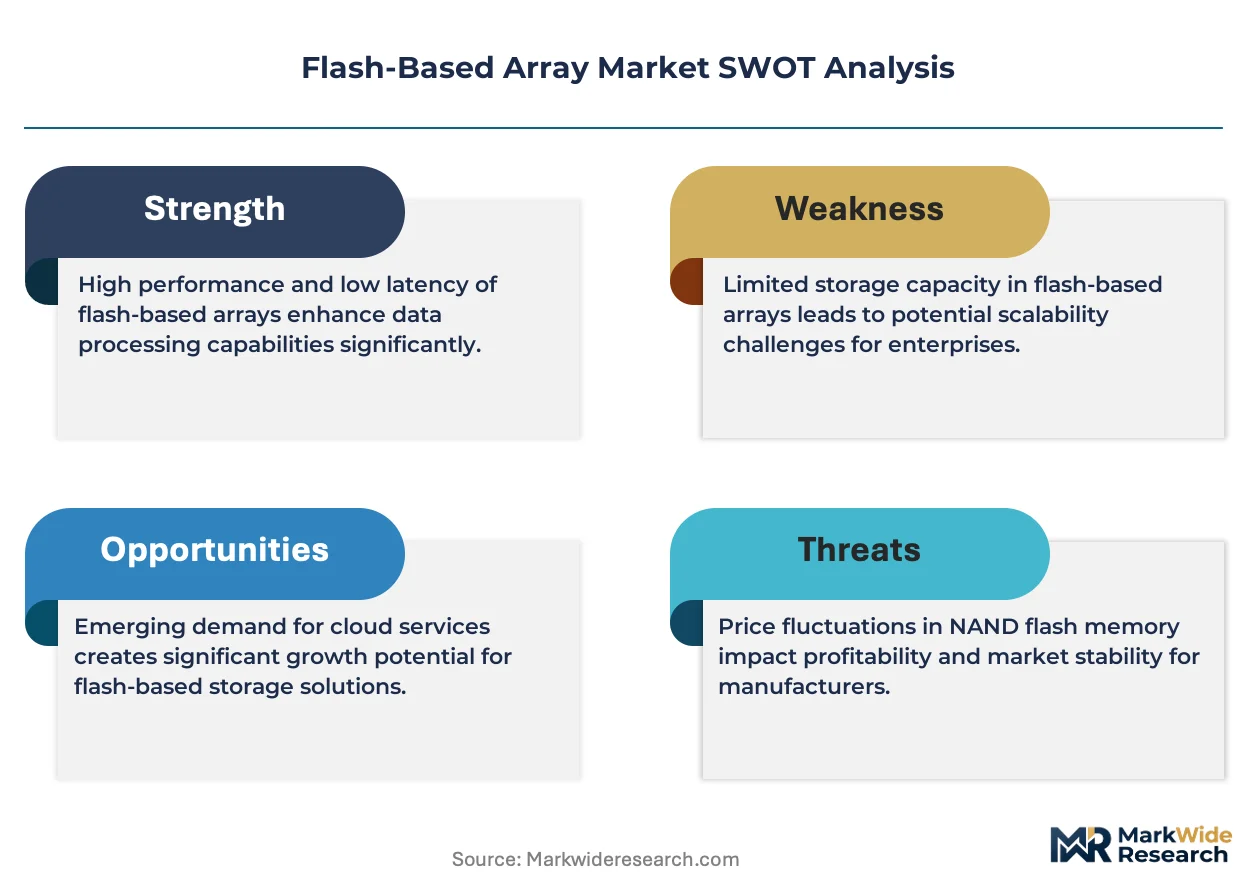
Flash-Based Array Market Analysis
NVMe-class performance tiers is reorganizing procurement priorities across enterprise data centers. Dell Technologies leverages its integrated server-storage portfolio to control large-scale deployment channels. Pure Storage differentiates through cloud-operating-model software that decouples hardware refresh cycles. Huawei Technologies anchors expansion in Asia-Pacific through vertically integrated NAND supply.
A flash-based array is a solid-state storage system built from NAND flash memory that delivers sub-millisecond latency and hundreds of thousands of IOPS for primary workloads such as databases, virtualization, and analytics. These systems replace mechanical disk arrays where throughput density and power efficiency determine total cost of ownership. All-flash array configurations now capture the majority of new primary storage spend as NVMe fabrics mature. Hybrid array demand persists in secondary tiers where cost-per-gigabyte constraints favor mixed media. Cloud provider end users represent the fastest-expanding customer segment as hyperscalers build captive flash capacity for hosted database services.
The U.S. Federal Trade Commission scrutinizes storage vendor consolidation under antitrust frameworks while the Securities and Exchange Commission mandates data retention integrity for financial records. Europe's GDPR and Cyber Resilience Act impose encryption and breach-notification standards that elevate certified flash array specifications. China's MIIT enforces domestic procurement preferences through GB standards that favor local NAND integration. Stakeholders must weigh sovereign data localization mandates against supply chain concentration in Korean and Japanese NAND fabrication when planning capacity expansion.
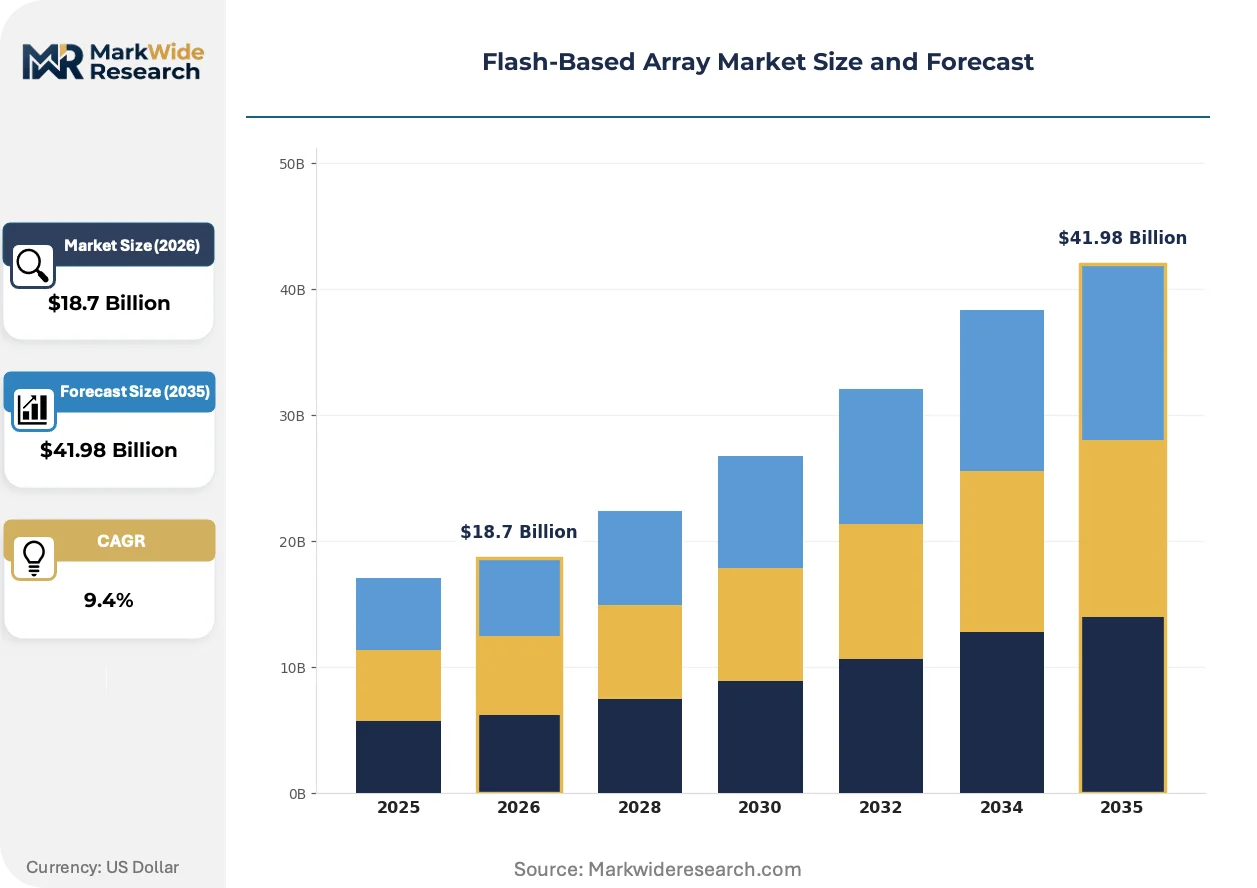
Market Dynamics
NVMe fabric maturation is compressing refresh cycles and forcing incumbent vendors to decouple hardware from software licensing, fundamentally restructuring how enterprise storage capacity is procured and monetized across primary data center tiers.
Growth Catalysts
- Financial services real-time mandates:SEC record-integrity rules for transaction logging are compelling banks to replace disk-based archives with certified all-flash configurations that guarantee sub-millisecond write consistency.
- GDPR encryption requirements:Europe's Cyber Resilience Act is elevating certified flash array specifications for breach-notification compliance, creating procurement pull across German and French data centers.
- Hyperscaler captive buildouts:Cloud providers in the United States and Japan are constructing sovereign flash capacity for hosted database services, absorbing high-performance NVMe-class output directly from module vendors.
Market Restraints
- NAND supply concentration:Korean and Japanese fabrication clusters control captive wafer output, exposing array manufacturers to geopolitical disruption and allocation priority shifts.
- Legacy SAS infrastructure lock-in:Enterprise data centers face forklift-upgrade costs when migrating from twelve-gigabit SAS to NVMe fabrics, delaying refresh decisions.
- Power density constraints:All-flash racks draw sustained thermal loads that exceed legacy cooling designs, requiring facility-level capital investment before deployment.
Strategic Opportunities
- India sovereign cloud buildout:RBI data-localization directives for financial records are creating first-mover advantage for vendors establishing domestic flash assembly and certification.
- Computational storage convergence:Integration of processing logic into flash controllers is enabling edge analytics without host CPU intervention, opening industrial IoT deployments.
- Japan METI efficiency standards:Domestic procurement preferences for power-optimized arrays are channeling subsidy flow toward NVMe-based systems with verified watt-per-TB metrics.
Industry Challenges
- Firmware security certification:Common Criteria and FIPS validation timelines for self-encrypting drives extend eighteen to twenty-four months, delaying product launches.
- Legacy mainframe integration:Financial institutions require specialized FICON protocol gateways to bridge z/OS environments with modern NVMe fabrics, adding integration cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flash-Based Array Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Flash Array, Hybrid Array, Storage Gateway, Flash Cache End User: Enterprise, SMBs, Government, Cloud Providers Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: SAS, SATA, PCIe, NVMe |
| Companies Covered | Dell Technologies, NetApp, Pure Storage, Hewlett Packard Enterprise, IBM Corporation, Huawei Technologies, Hitachi Vantara, Fujitsu, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flash-Based Array Market Emerging Trajectories
Storage-class memory hierarchies are collapsing the boundary between DRAM and flash, enabling new system architectures that treat persistent media as addressable memory rather than block storage.
Quad-level cell NAND is miniaturizing die geometries to one hundred thirty-two layers and beyond, doubling bit density per wafer while maintaining endurance through adaptive voltage algorithms. Hyperscale operators are absorbing this output for warm-tier object storage, compressing cost-per-gigabyte toward mechanical disk parity. The structural consequence is a bifurcation between performance-tier NVMe and capacity-tier QLC procurement streams.
China's MIIT is enforcing GB standards that mandate domestic NAND integration for government and state-owned enterprise procurement, creating parallel certification tracks for local and international vendors. This regulatory friction is fragmenting supply chain planning, as multinationals must maintain separate firmware and hardware SKUs for compliant and non-compliant channels. Array manufacturers are responding by establishing joint ventures with Yangtze Memory Technologies to preserve market access.
Consumption-based financing models are displacing capital purchase arrangements for mid-market enterprises, with vendors retaining ownership and charging per-terabyte-month fees. Systems integrators are inserting themselves as managed service intermediaries, capturing recurring revenue and customer stickiness. This shift is most visible in German Mittelstand manufacturing, where CFOs prefer operational expenditure treatment for storage assets.
Flash-Based Array Market Segmentation
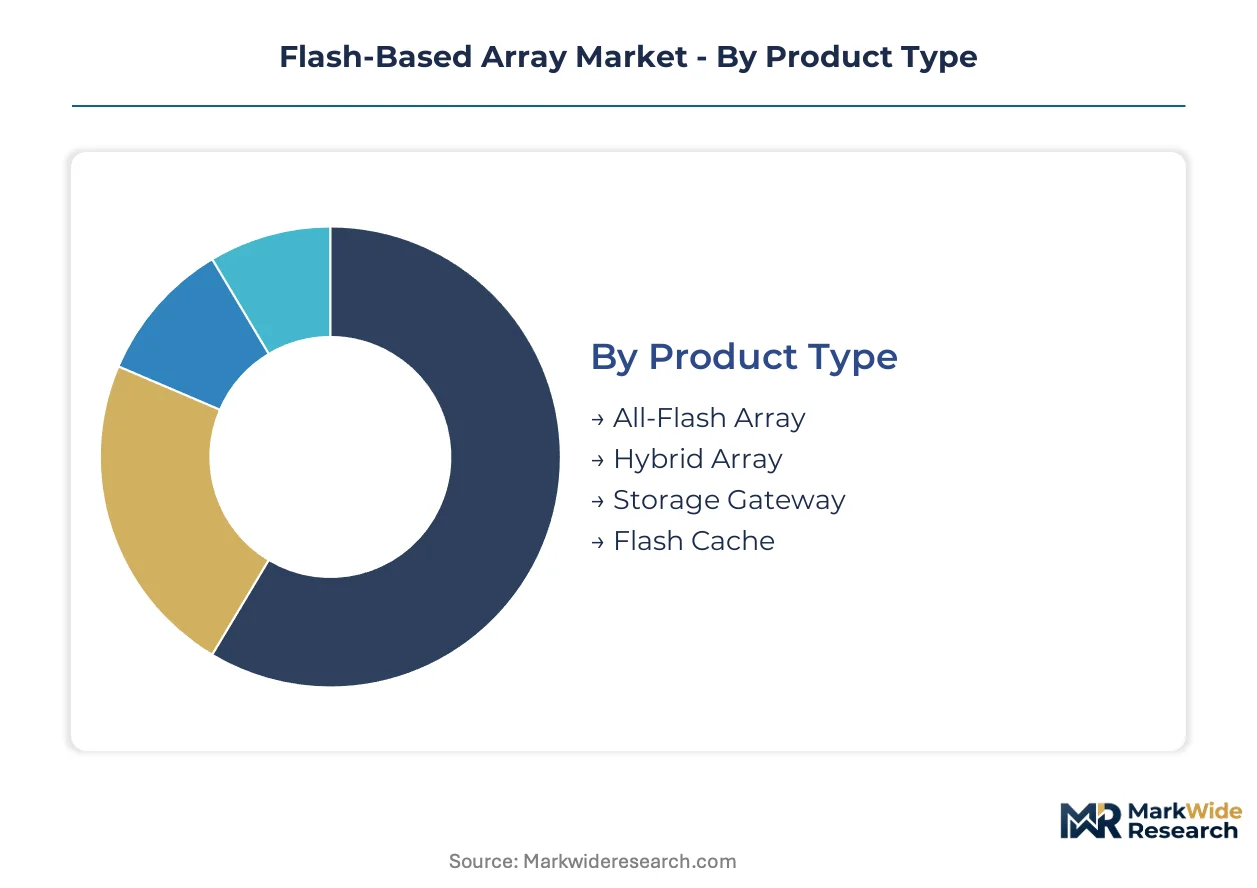
Flash-based array procurement channels diverge sharply by performance tier and buyer sophistication. Enterprise data centers route NVMe-class purchases through direct vendor relationships, while mid-market segments increasingly favor managed service intermediaries.
Product Type:
Channel mix varies dramatically across physical form factors, with all-flash configurations dominating direct enterprise sales while hybrid arrays flow through systems integrators serving cost-constrained buyers.
- All-Flash Array:Pure solid-state configurations built entirely from NAND flash deliver sub-millisecond latency for primary database and virtualization workloads. Demand concentrates in United States financial services data centers where SEC record-integrity mandates require certified write-consistency guarantees.
- Hybrid Array:Mixed media systems combining flash tiers with mechanical disks optimize cost-per-gigabyte for secondary storage applications. German Mittelstand manufacturers represent the strongest adoption corridor, driven by operational expenditure preferences under consumption-based financing models.
- Storage Gateway:Bridge appliances enabling cloud-tier extension of on-premises flash estates.
- Flash Cache:Acceleration modules augmenting existing disk arrays with hot-tier buffering.
By volume, hybrid arrays lead. By growth pace, all-flash configurations are gaining share fastest.
End User:
Cost tier segmentation separates sovereign cloud builders with captive procurement power from price-sensitive mid-market buyers dependent on financing structures.
- Enterprise:Large-scale data center operators with dedicated storage engineering teams and direct vendor negotiations. United States hyperscalers absorb the highest-performance NVMe output for hosted database services, creating allocation competition for array manufacturers.
- Cloud Providers:Hyperscale operators constructing captive flash capacity across sovereign jurisdictions. Japan-based cloud builders are expanding fastest under METI efficiency standards that channel subsidy toward power-optimized NVMe systems.
- SMBs:Resource-constrained buyers reliant on managed service providers for storage infrastructure.
- Government:Public sector procurement subject to domestic content mandates and security certification requirements.
Enterprise buyers dominate absolute spend. Cloud providers are expanding most quickly.
Deployment:
Application criticality determines whether buyers retain infrastructure control or delegate to third-party operators.
- On-Premises:Captive data center installations maintaining direct physical control over storage hardware. Financial institutions in Germany and France favor this model under GDPR encryption requirements that elevate certified array specifications.
- Managed Services:Third-party operated storage with per-terabyte-month pricing and vendor-retained ownership. Indian financial institutions are adopting this fastest under RBI data-localization directives that require domestic flash assembly certification.
- Cloud-Based:Fully abstracted storage consumed as utility service from hyperscale providers.
- Hybrid:Split-tier architectures spanning owned facilities and cloud extension.
On-premises retains the largest installed base. Managed services show the steepest expansion trajectory.
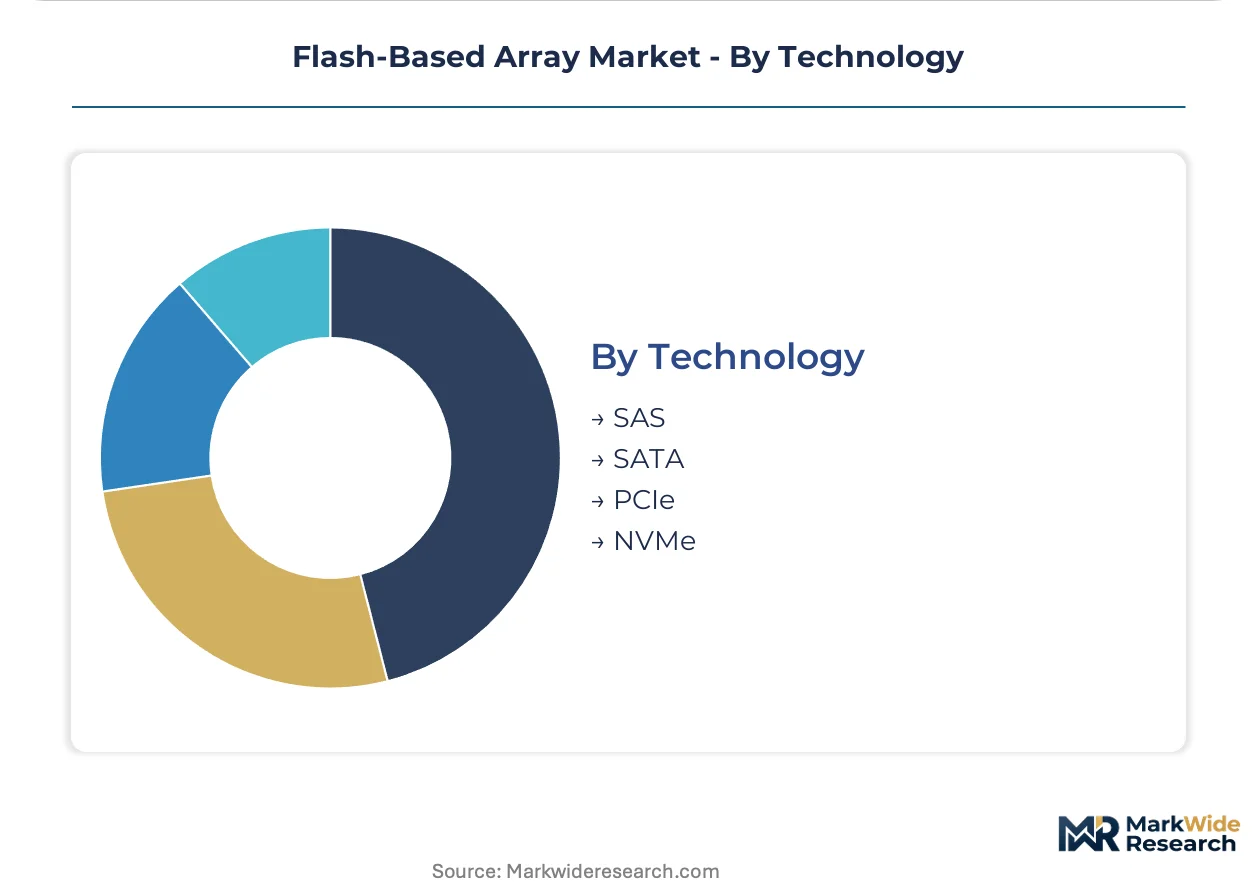
Technology:
Supply concentration in Korean and Japanese NAND fabrication creates procurement priority tiers that favor buyers with volume commitments.
- NVMe:Native PCIe-attached protocol eliminating SAS controller overhead and enabling fabric-scale disaggregation. United States cloud providers and German automotive manufacturers are the primary demand anchors, with the latter requiring real-time analytics throughput for connected vehicle platforms.
- SAS:Legacy twelve-gigabit serial attachment protocol retained in mainframe environments requiring FICON gateway compatibility. Financial institutions with z/OS estates face extended refresh timelines due to forklift-upgrade costs.
- SATA:Cost-optimized interface for cold-tier flash applications.
- PCIe:Direct-attached flash for highest-performance compute-local storage.
SAS maintains residual volume in legacy estates. NVMe is climbing the fastest across new procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flash-based array trade flows reveal a pronounced import dependency in European and Indian data centers offset by surplus production capacity concentrated in South Korean and Japanese NAND fabrication clusters. The United States maintains near-balanced trade in finished arrays while running substantial deficits in raw memory components.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth absorb the highest-performance NVMe output for hosted database services, creating allocation competition for array manufacturers. SEC record-integrity mandates for financial transaction logging are compelling banks to replace disk-based archives with certified all-flash configurations. The concentration of fintech engineering talent in San Francisco and New York accelerates deployment of sub-millisecond latency tiers.
Germany
Automotive manufacturers in Baden-Württemberg require real-time analytics throughput for connected vehicle platforms, anchoring demand for NVMe-class systems. GDPR encryption requirements under Europe's Cyber Resilience Act elevate certified flash array specifications for breach-notification compliance. Frankfurt's financial data center cluster is expanding sovereign flash capacity under BaFin supervisory guidance for transaction record retention.
Japan
Domestic cloud builders in Tokyo and Osaka are expanding fastest under METI efficiency standards that channel subsidy toward power-optimized NVMe systems. The country's NAND fabrication concentration in Yokkaichi and Kitakami supplies captive wafer output to regional array assemblers. Kansai-based manufacturers face procurement priority shifts when Korean competitors secure allocation ahead of cyclical demand spikes.
India
RBI data-localization directives for financial records are creating first-mover advantage for vendors establishing domestic flash assembly and certification in Mumbai and Bengaluru. Managed services adoption is accelerating fastest among mid-market enterprises seeking operational expenditure treatment for storage assets. The Maharashtra industrial corridor is attracting joint venture proposals from multinational array manufacturers seeking compliant local production.
China
MIIT enforcement of GB standards mandating domestic NAND integration is fragmenting supply chain planning for government and state-owned enterprise procurement. Yangtze Memory Technologies in Wuhan anchors parallel certification tracks that require separate firmware and hardware SKUs for compliant channels. Beijing-Tianjin-Hebei data center clusters are absorbing QLC output for warm-tier object storage at hyperscale deployment scale.
Flash-Based Array Market Vendor Landscape
Concentration sits with integrated server-storage portfolios and vertically controlled NAND supply chains. Dell Technologies leverages its captive distribution to control large-scale deployment channels, while Huawei anchors expansion through in-house production of memory components. Pure Storage differentiates through cloud-operating-model software that decouples hardware refresh cycles. The dominant competitive moves are strategic partnerships with hyperscale cloud providers and geographic expansion into sovereign cloud jurisdictions with data localization mandates.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify server-storage bundling strategies that capture enterprise procurement decisions. Pure Storage occupies a position representing software-defined disaggregation, while Huawei Technologies sits within the vertically controlled supply archetype. IBM Corporation and Hitachi Vantara represent legacy mainframe integration specialists facing extended refresh timelines due to FICON gateway requirements. NetApp exemplifies hybrid cloud extension positioning.
| Leading Market Players |
|---|
| Dell Technologies |
| NetApp |
| Pure Storage |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Huawei Technologies |
| Hitachi Vantara |
| Fujitsu |
| Micron Technology |
| Others |
Supply Flow & Price Mechanics
NVMe protocol substitution for legacy SAS architectures simultaneously redraws procurement geography toward Korean and Japanese fabrication clusters and compresses margin structures across incumbent array manufacturers. This displacement dynamic concentrates pricing power with NAND wafer suppliers while forcing systems vendors toward software-defined monetization models.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by FIPS certification grade and volume commitment scale. Cloud providers with petabyte-scale offtake command steepest discounts, while mid-market enterprises face pricing pressure from consumption-based financing preferences. Financial institutions show least price sensitivity due to SEC record-integrity mandates that override cost considerations.
Supply Chain Analysis
Inventory cycles for high-performance NAND modules currently stretch eighteen to twenty-four months from wafer allocation to array assembly, tethering procurement timelines to Korean and Japanese fabrication schedules. Raw material dependencies center on silicon wafers, rare earth dopants, and specialized controller ASICs. Single-source vulnerability concentrates in Yokkaichi and Kitakami production clusters. Distribution runs through direct vendor relationships for enterprise tiers and systems integrator intermediaries for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs lock financial institutions into certified array ecosystems, creating regulatory entrenchment that sustains incumbent positions.
For Market Incumbents: Shield installed base relationships through FICON gateway compatibility investments that extend mainframe integration timelines and delay competitive displacement. Deepen captive NAND supply arrangements with Korean fabrication partners to secure allocation priority during cyclical demand spikes. Software licensing decoupling from hardware refresh cycles represents the critical defensive lever against cloud-native challengers. For New Entrants and Emerging Players: Common Criteria certification fast-tracks for self-encrypting drives open procurement pathways into German and French financial data centers where GDPR compliance creates barrier entry. Indian sovereign cloud buildout under RBI localization directives presents the most penetrable geography. Managed service intermediary partnerships offer the strongest go-to-market angle for resource-constrained mid-market penetration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed software-defined storage specialists possessing cloud-operating-model platforms but lacking captive NAND supply. Long-term viability over the coming decade hinges on backward integration into memory component supply or hyperscale cloud provider partnership anchoring. Watch for MIIT enforcement intensity in China as the signal indicating whether parallel certification track fragmentation accelerates or stabilizes.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with Domestic NAND Producer | Preserves market access under China's GB standards enforcement for government procurement channels. |
| Consumption-Based Financing Model Launch | Captures German Mittelstand manufacturing demand through operational expenditure treatment preferences. |
| NVMe Fabric Certification Investment | Accelerates SEC-compliant all-flash adoption among United States financial services data centers. |
| Managed Services Channel Partnership | Routes Indian mid-market demand through domestic flash assembly certification under RBI directives. |
| Power-Optimized Array Efficiency Program | Channels Japan METI subsidy flow toward verified watt-per-TB metrics in Tokyo-Osaka cloud buildouts. |
Methodological Framework
The analysis maps all-flash configurations, hybrid arrays, NVMe fabrics, and SAS legacy estates, each validated through data center infrastructure directors, storage procurement officers, NAND supply chain managers, and systems integrator principals. Primary interview intelligence combined with customs trade data, SEC 10-K storage segment disclosures, hyperscaler capex filings, and MIIT GB standard documentation. Bottom-up array shipment aggregation and top-down NAND wafer demand modeling provided triangulation consistency.
Consistency checks against hyperscaler infrastructure spending benchmarks and vendor-reported segment revenues validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include performance tier, deployment model, end-user scale, protocol architecture, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates, with inputs from NAND bit supply forecasts and enterprise storage refresh cycle surveys.
Decision-makers should treat outputs as directional under assumptions of sustained NVMe adoption velocity and stable Korean-Japanese wafer supply; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
SAS Hard Disk Drives Market
Data Storage
Transparent Caching Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
Channel Storage Systems Market
Data Storage
Global Portable Data Storage Market
Data Storage
Ethernet Storage Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
Multiprotocol Storage Market
Data Storage
Zoned Flash Market
Data Storage
Solid State Array Market
Data Storage
South Korea Data Center Storage Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Global 3D Nand Flash Memory Market
Data Storage
NAND Flash Memory Market
Data Storage
Archival Grade Blu-Ray Discs Market