
 Syphilis Testing Market | 2026-2036
Syphilis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Syphilis Testing Market Outlook
Laboratory technologist shortages in rural health systems are unwinding traditional centralized testing workflows and pushing demand toward point-of-care platforms. Roche Diagnostics leverages its automated immunoassay installed base to sustain high-throughput laboratory dominance. Abbott Laboratories anchors the rapid diagnostics segment with lateral-flow platforms designed for decentralized settings. bioMérieux competes through molecular assay specialization that addresses early-stage infection detection where serological methods lag.
Syphilis testing encompasses diagnostic methods that detect Treponema pallidum antibodies or nucleic acids in serum, plasma, or whole blood specimens, with sensitivity thresholds ranging from 85% for rapid treponemal tests to over 99% for laboratory-based enzyme immunoassays. These methods serve dual clinical purposes: screening asymptomatic populations in prenatal and blood-donor programs while confirming active infection for treatment decisions. Serological tests occupy the mature volume core of the market, generating reliable recurring demand from blood bank screening mandates. Nucleic acid tests represent the fastest-expanding technology segment as PCR-based platforms displace culture methods in reference laboratories. Rapid tests concentrate margin pools in procurement contracts with ministries of health pursuing universal antenatal screening coverage.
FDA premarket notification requirements under 21 CFR 866 shape diagnostic performance claims and predicate device selection for US market entrants, while WHO prequalification governs access to procurement by Global Fund and UNICEF supply programs. The EU In Vitro Diagnostic Regulation imposes notified-body conformity assessment on all syphilis assays sold in member states, elevating documentation burdens for lateral-flow manufacturers. Laboratories and procurement agencies must monitor evolving WHO guideline revisions on dual HIV-syphilis test algorithms to align procurement specifications with forthcoming protocol changes.
Market Dynamics
Point-of-care diagnostic platforms are fragmenting syphilis testing workflows away from centralized laboratories, driven by WHO prequalification pathways for dual HIV-syphilis rapid tests and rural health system capacity constraints.
Growth Catalysts
- Antenatal screening mandates:India's National AIDS Control Organization has embedded syphilis testing into nationwide maternal health protocols, institutionalizing recurring procurement volumes for rapid diagnostic kits.
- WHO prequalification acceleration:Streamlined assessment pathways for dual HIV-syphilis assays are compressing product registration timelines and unlocking Global Fund procurement access for manufacturers.
- Laboratory technologist scarcity:Rural health worker shortages across sub-Saharan African and South Asian health systems are forcing decentralization toward lateral-flow platforms operable by non-specialist staff.
Market Restraints
- Serological test commoditization:Mature enzyme immunoassay segments face margin compression as blood bank screening mandates standardize around lowest-qualified bidders.
- Reagent supply concentration:PCR master mix and nucleic acid extraction kit production clusters in Chinese and German chemical manufacturing hubs, exposing molecular assay supply chains to single-source risk.
- EU MDR documentation burden:The In Vitro Diagnostic Regulation's notified-body conformity assessment requirements impose elevated technical file costs on lateral-flow manufacturers seeking European market access.
Strategic Opportunities
- Sub-Saharan African expansion:Underpenetrated rural clinic networks in Nigeria, Kenya, and Tanzania present procurement contract opportunities aligned with PEPFAR and Global Fund programmatic funding.
- Self-testing regulatory pathways:FDA and WHO guidance development for over-the-counter syphilis assays is opening channel expansion beyond clinical settings into pharmacy and direct-to-consumer distribution.
- Molecular-immunoassay convergence:Integrated platforms combining treponemal antibody detection with PCR confirmation are capturing reference laboratory workflow consolidation demand.
Industry Challenges
- Clinical laboratory specialist recruitment:Reference laboratories in India and Brazil struggle to hire trained immunoassay technologists capable of operating automated high-throughput platforms.
- Dual-test algorithm alignment:Procurement agencies must continuously reconfigure assay specifications to match evolving WHO guideline revisions on HIV-syphilis testing sequences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syphilis Testing Market |
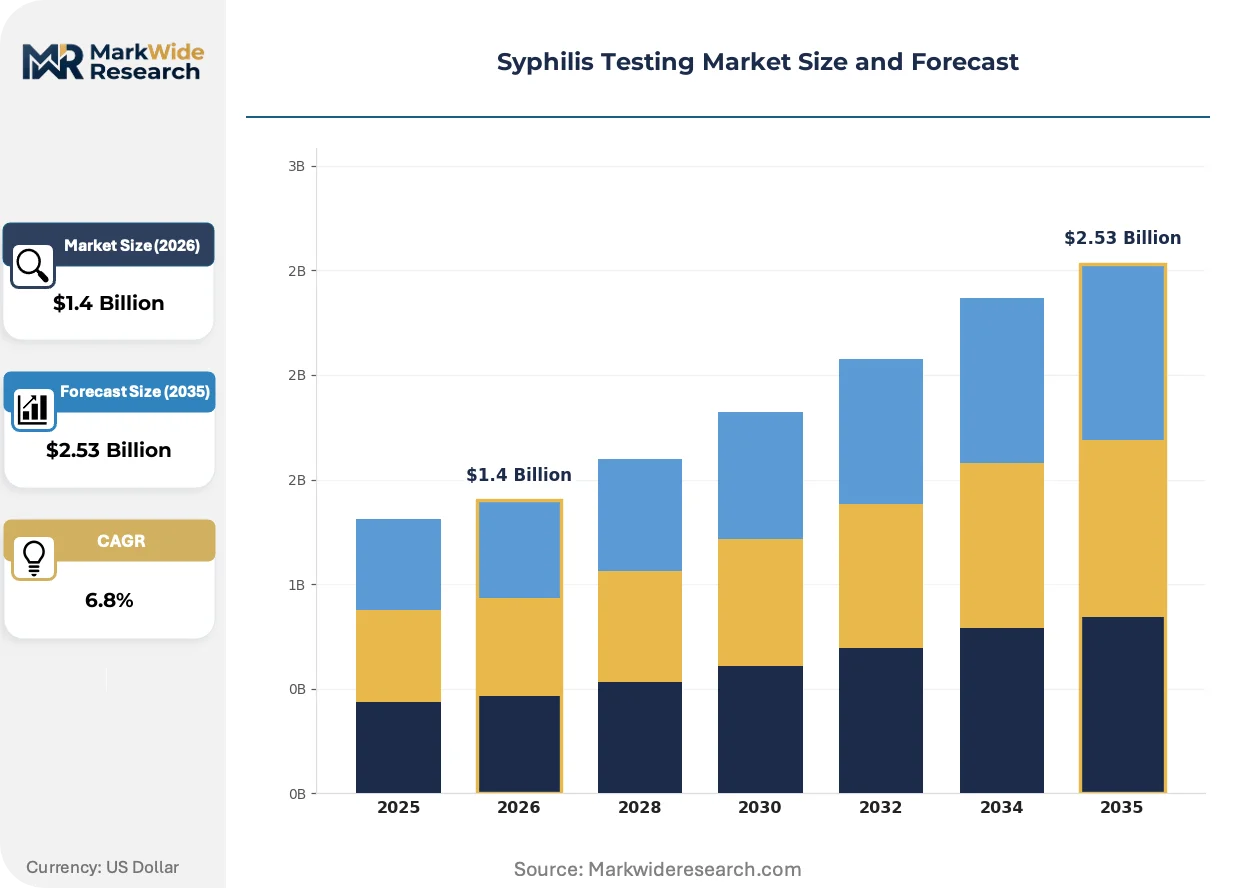
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, Enzyme Immunoassays, Nucleic Acid Tests, Serological Tests End User: Hospitals, Diagnostic Laboratories, Clinics, Blood Banks Technology: ELISA, PCR, Traditional Culture, Lateral Flow Distribution Channel: Direct Sales, Online Pharmacies, Wholesalers, Retail Pharmacies |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Becton Dickinson And Company, bioMérieux, Hologic, Inc., Siemens Healthineers, Bio-Rad Laboratories, Cepheid Inc., Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syphilis Testing Market Strategic Shifts
Technological substitution and regulatory pathway redesign are compressing traditional serology-dominated testing architectures while procurement centralization reshapes vendor-commercial relationships.
Multiplexed molecular platforms is decomposing the historical separation between screening and confirmation phases in syphilis diagnostics. Reference laboratories in the United States and Western Europe are adopting these integrated systems to consolidate workflow steps and reduce specimen handling costs. This convergence is compressing market segmentation between high-volume screening and specialized confirmatory testing segments.
EU MDR implementation timelines are forcing lateral-flow manufacturers to restructure quality management systems and technical documentation for European market continuity. The regulation's emphasis on clinical performance evidence and post-market surveillance is elevating compliance costs disproportionately for smaller assay producers. Manufacturers are responding by prioritizing notified-body relationships and withdrawing marginal SKUs from European distribution.
Ministry of health consolidated procurement is displacing fragmented distributor networks in low-resource settings. National AIDS control programs in India, South Africa, and Nigeria are centralizing rapid test purchasing through tender mechanisms that favor multi-year volume commitments. This channel consolidation is visible most acutely in antenatal care supply chains where vertical program funding streamlines procurement decision-making.
Syphilis Testing Market Segmentation
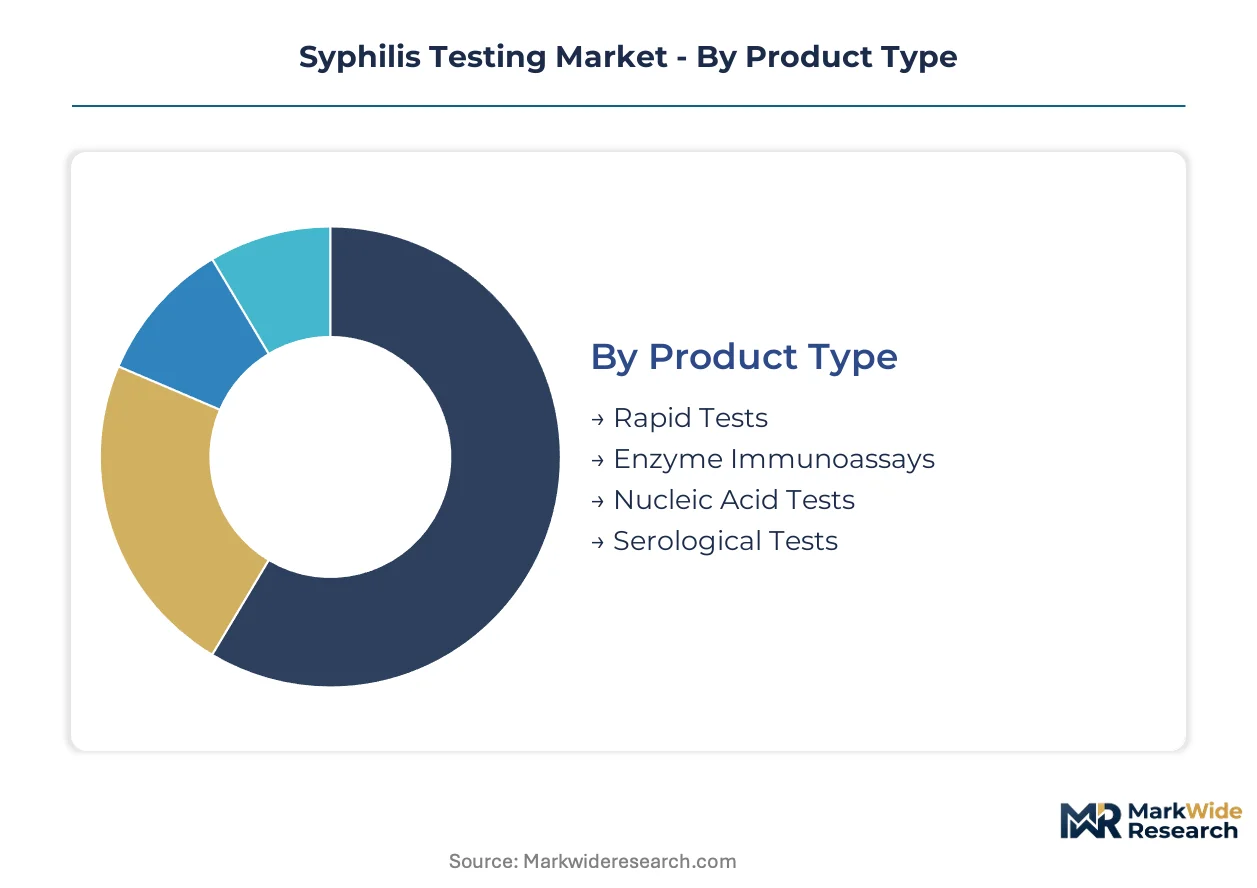
Syphilis testing segmentation reflects divergent regulatory pathways and procurement economics across clinical settings. Each category maps to distinct compliance frameworks, from FDA Emergency Use Authorization for rapid diagnostics to WHO prequalification for blood bank screening mandates.
Product Type:
FDA 510(k) clearances and WHO prequalification status create tiered market access barriers that stratify commercial opportunity across assay formats.
- Rapid Tests:Lateral-flow immunochromatographic devices deliver treponemal and non-treponemal antibody detection in 15-20 minutes without laboratory infrastructure. India's National AIDS Control Organization procurement contracts concentrate demand for dual HIV-syphilis formats in antenatal care settings, where point-of-care deployment bypasses rural technologist shortages.
- Enzyme Immunoassays:Automated microplate or chemiluminescent platforms process 100-400 specimens hourly with 99%+ sensitivity for treponemal IgG/IgM. Blood bank screening mandates in the United States and European Union sustain recurring high-throughput demand, though margin compression intensifies as procurement standardizes around lowest-qualified bidders.
- Nucleic Acid Tests:PCR-based platforms detect Treponema pallidum DNA in primary lesions and early infection stages where serology yields false negatives.
- Serological Tests:Traditional rapid plasma reagin and fluorescent treponemal antibody absorption assays remain reference standards for confirmatory testing algorithms.
Enzyme immunoassays handle the majority of throughput; nucleic acid tests are climbing the fastest on share as PCR platforms displace culture methods in reference laboratories.
End User:
Procurement centralization through ministry of health tenders is reshaping vendor relationships across institutional categories.
- Hospitals:Inpatient and emergency departments deploy rapid tests for symptomatic patients while routing high-volume screening to centralized laboratories. PEPFAR-funded facilities in Nigeria and Kenya anchor procurement growth for dual HIV-syphilis platforms.
- Diagnostic Laboratories:Automated immunoassay systems dominate reference laboratory workflows in urban India and Brazil, though technologist recruitment constraints limit expansion into tier-2 cities.
- Clinics:Decentralized primary care settings in sub-Saharan Africa drive lateral-flow volume through Global Fund and bilateral health program disbursements.
- Blood Banks:Regulatory mandates in the United States, European Union, and India institutionalize recurring serological screening demand with stringent sensitivity thresholds.
Diagnostic laboratories capture the highest absolute volume; clinics are expanding most quickly as procurement decentralization accelerates.
Technology:
Platform selection traces the tension between laboratory consolidation and point-of-care decentralization across health system architectures.
- ELISA:Enzyme-linked immunosorbent assay platforms anchor blood bank and high-throughput hospital laboratory screening with established predicate devices for FDA 510(k) submissions.
- PCR:Real-time and digital PCR systems enable early-stage infection detection and molecular confirmation of serological results in reference laboratories.
- Traditional Culture:Dark-field microscopy and rabbit infectivity testing persist in specialized reference centers despite labor intensity and biosafety requirements.
- Lateral Flow:Immunochromatographic strip formats enable non-laboratory personnel to perform testing in rural clinics and antenatal care outreach programs.
ELISA sustains the dominant throughput position; lateral flow is gaining share fastest as WHO prequalification unlocks ministry of health procurement at scale.
Distribution Channel:
Channel structure varies sharply between mature markets with fragmented retail access and low-resource settings with centralized programmatic procurement.
- Direct Sales:Manufacturer field forces negotiate multi-year tenders with national AIDS control programs and blood transfusion services, capturing volume commitments in India and South Africa.
- Online Pharmacies:Direct-to-consumer channels remain nascent pending FDA and WHO guidance on over-the-counter syphilis self-testing regulatory pathways.
- Wholesalers:Regional distributors serve private laboratory networks and hospital group purchasing organizations in Brazil and Mexico.
- Retail Pharmacies:Community pharmacy access for rapid HIV-syphilis tests is expanding in European markets with self-testing regulatory clarity.
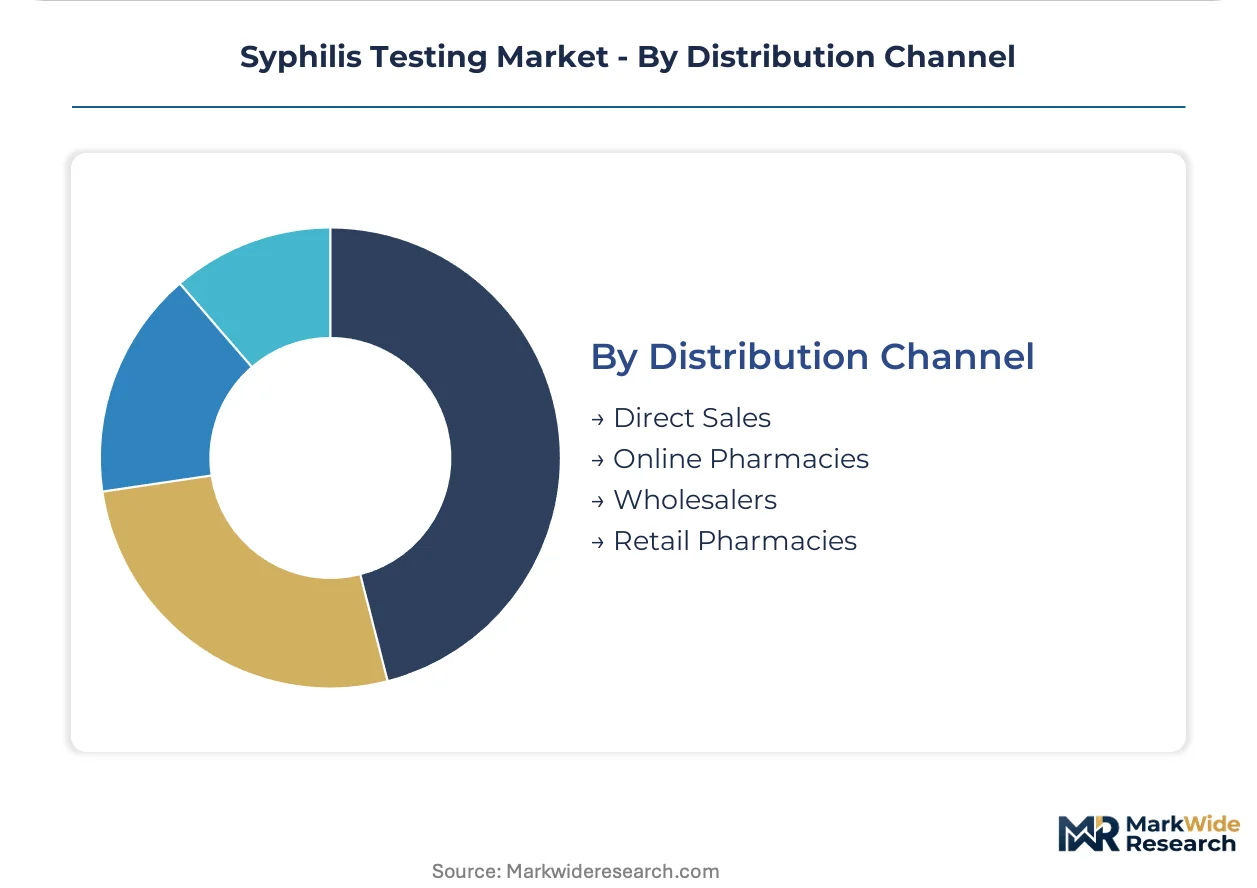
Direct sales channels command the largest procurement volumes; online pharmacies show the steepest expansion trajectory as self-testing frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between high-resource settings that automate laboratory workflows and low-resource health systems that decentralize testing to point-of-care platforms operated by non-specialists.
United States
Blood bank screening mandates from the FDA sustain high-throughput enzyme immunoassay demand across the American Red Cross and hospital transfusion services. The FDA's 510(k) pathway shapes predicate device selection for new assay entrants. Boston and San Diego anchor molecular diagnostics clusters where PCR-based platforms serve reference laboratory confirmation workflows.
India
The National AIDS Control Organization has institutionalized syphilis screening within nationwide antenatal care protocols, creating recurring procurement volumes for rapid diagnostic kits. CDSCO regulatory oversight governs import and registration of lateral-flow devices. Mumbai and Hyderabad concentrate diagnostic manufacturing capacity serving ministry of health tender contracts.
Germany
The EU In Vitro Diagnostic Regulation imposes notified-body conformity assessment requirements that elevate compliance costs for lateral-flow manufacturers seeking European market access. EMA guidance on diagnostic performance standards influences predicate device claims. The Rhine-Ruhr and Munich regions host automated immunoassay development for blood bank screening applications.
Brazil
ANVISA registration requirements structure market access for imported rapid tests serving PEPFAR-funded clinic networks. Public health laboratories in São Paulo and Rio de Janeiro deploy automated platforms for high-volume screening, while northern states push decentralized testing to address technologist shortages. Ministry of health consolidated procurement is displacing fragmented distributor networks.
South Africa
The National Department of Health centralizes rapid test purchasing through tender mechanisms aligned with Global Fund programmatic funding. WHO prequalification status determines eligibility for public sector procurement. Johannesburg and Cape Town concentrate private laboratory networks that bridge public screening programs with confirmatory testing capacity.
Syphilis Testing Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding automated high-throughput platforms and the lower tier competing on point-of-care accessibility. Market structure reflects consolidation around diagnostic conglomerates with multi-modality portfolios alongside fragmentation among rapid test specialists. Two strategic archetypes dominate: automated immunoassay incumbents defending laboratory installed bases, and lateral-flow innovators capturing ministry of health procurement contracts. Competitive moves center on regulatory pathway acceleration through WHO prequalification pursuit and geographic expansion into underpenetrated sub-Saharan African clinic networks.
Within the integrated diagnostics tier, Roche Diagnostics and Abbott Laboratories occupy positions exemplifying divergent platform strategies, with the former anchoring laboratory automation and the latter representing decentralized rapid test deployment. bioMérieux sits within the molecular specialization archetype, its positioning reflecting PCR-based assay development for early-stage infection detection where serological methods face sensitivity limitations. These three entities collectively illustrate how vendor strategy fragments across the centralization-decentralization axis of health system architecture.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Becton Dickinson And Company |
| bioMérieux |
| Hologic, Inc. |
| Siemens Healthineers |
| Bio-Rad Laboratories |
| Cepheid Inc. |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Multi-year tender contracts with national AIDS control programs lock in supply access for rapid diagnostic manufacturers while anchoring price visibility across procurement cycles. India's National AIDS Control Organization and South Africa's National Department of Health structure volume commitments that compress unit economics for lateral-flow producers competing on WHO prequalification status.
Pricing Analysis
Long-term offtake agreements dominate procurement relationships with ministry of health buyers, particularly for dual HIV-syphilis rapid tests in antenatal care programs. Price differentiation rests on WHO prequalification tier and manufacturing scale, with CDSCO-registered Indian producers commanding premiums over unqualified competitors. Pricing pressure stems from serological test commoditization in blood bank segments, where automated immunoassay procurement standardizes around lowest-qualified bidders. Clinic networks in sub-Saharan Africa exhibit highest price sensitivity, while reference laboratories in the United States and Germany prioritize sensitivity thresholds over unit cost.
Supply Chain Analysis
Strategic stockpiling preferences dominate ministry of health procurement, with buffer inventories maintained to address rural distribution gaps and cold-chain limitations. Manufacturing concentrates in India, China, and Germany, with Mumbai and Hyderabad anchoring lateral-flow production for Global Fund disbursements. PCR master mix and nucleic acid extraction kits draw from Chinese and German chemical manufacturing hubs, creating single-source vulnerability for molecular assay producers. Distribution runs through consolidated tender mechanisms that displace fragmented distributor networks in Nigeria, Kenya, and Tanzania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Syphilis testing sits in early-cycle expansion as WHO prequalification acceleration for dual HIV-syphilis assays unlocks ministry of health procurement at scale across underpenetrated rural clinic networks.
For Market Incumbents: Shield automated immunoassay installed bases in blood bank segments by deepening backward integration into reagent manufacturing and accelerating FDA 510(k) predicate device filings for next-generation platforms. Roche Diagnostics and Abbott Laboratories should prioritize capacity reservation agreements with Chinese PCR master mix suppliers to mitigate single-source exposure. Certification investment in EU MDR notified-body relationships preserves European market continuity as technical documentation burdens escalate. For New Entrants and Emerging Players: Differentiate on molecular-immunoassay convergence platforms that consolidate screening and confirmation workflows for reference laboratories in Brazil and India. White-space targets include self-testing regulatory pathways pending FDA over-the-counter guidance and PEPFAR-funded clinic networks in northern Nigerian states. Go-to-market execution should anchor on WHO prequalification pursuit to unlock Global Fund procurement eligibility. For Investors and Strategic Acquirers: Capital is best deployed toward lateral-flow specialists with established CDSCO registration and active WHO prequalification dossiers, positioned to capture ministry of health tender consolidation. Long-term viability across the analysis window hinges on dual-test algorithm alignment capabilities as WHO guideline revisions reconfigure procurement specifications. The signal to watch is FDA Emergency Use Authorization pathway expansion for over-the-counter syphilis assays, which would rechannel distribution into pharmacy and direct-to-consumer segments.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks Global Fund and UNICEF procurement access for lateral-flow manufacturers in low-resource settings. |
| EU MDR Notified-Body Relationship | Preserves European market continuity as conformity assessment requirements elevate compliance costs. |
| Dual HIV-Syphilis Test Development | Aligns with India's National AIDS Control Organization antenatal care protocols and PEPFAR programmatic funding. |
| PCR Master Mix Backward Integration | Mitigates single-source supply chain risk concentrated in Chinese and German chemical manufacturing hubs. |
| Self-Testing Regulatory Pathway | Expands channel access beyond clinical settings into pharmacy and direct-to-consumer distribution pending FDA guidance. |
Study Parameters
Desk research of WHO prequalification databases, FDA 510(k) filings, and Global Fund procurement records preceded structured interviews with diagnostic laboratory directors, ministry of health procurement officers, biomedical engineers, and regulatory affairs specialists at IVD manufacturers. Secondary validation drew from CDSCO import registration data, EU MDR notified-body assessment reports, and PEPFAR supply chain disclosures. Bottom-up demand modeling triangulated against top-down health system expenditure analysis.
Variance decomposition across technology segments, end-user categories, and geographic procurement clusters anchored the analytical framework over the projection horizon. Modeled dimensions included assay format, automation level, regulatory pathway, and ministry of health tender participation. CAGRs derived from logistic penetration curves applied to antenatal care screening coverage targets and blood bank mandate expansion trajectories. Forecast inputs incorporated laboratory technologist shortage projections and WHO guideline revision timelines.
Decision-makers should treat outputs as directional under assumptions of sustained PEPFAR funding continuity and stable WHO prequalification throughput; material deviation would warrant model refresh. Specific risk factors include EU MDR implementation delays disrupting lateral-flow supply, reagent export restrictions from Chinese manufacturing hubs, and algorithm changes in dual HIV-syphilis testing sequences. Revision becomes warranted when WHO guideline revisions cross implementation thresholds in major procurement markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Rapid Sterility Testing Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Point of Care Lipid Test Market
Testing Services
Point of Care Testing Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Global Sleep Testing Services Market
Testing Services
At-Home Testing Market
Testing Services
Global Sterility Testing Market