
 Phenytoin Testing Market | 2026-2036
Phenytoin Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Phenytoin Testing Market Analytics
Liquid chromatography-tandem mass spectrometry is rebalancing cost structures against older immunoassay platforms in phenytoin testing workflows. Thermo Fisher Scientific leverages its chromatography portfolio to anchor high-throughput laboratory contracts across North American health systems. Abbott competes through integrated immunoassay architectures embedded within its core laboratory analyzers. Danaher sustains precision positioning through its analytical instrument subsidiaries serving reference laboratories.
Phenytoin testing encompasses quantitative analytical methods that measure serum or plasma concentrations of the hydantoin anticonvulsant drug, typically requiring detection thresholds below therapeutic ranges of micrograms per milliliter to guide dosing in epilepsy management. Chromatography-based assay systems command premium placement in academic medical centers where simultaneous multi-drug panels reduce per-sample costs, while immunoassay reagents dominate hospital laboratories prioritizing rapid turnaround for emergency therapeutic monitoring. Research institutes represent the fastest-growing end-user segment as pharmacogenomic investigations link CYP2C9 polymorphisms to phenytoin metabolism variability.
The FDA's Clinical Laboratory Improvement Amendments and the European Union's In Vitro Diagnostic Regulation impose escalating analytical validation requirements on phenytoin assay manufacturers seeking market access. ISO 15189 accreditation standards further constrain laboratory operations in Japan's hospital networks, where METI guidelines shape procurement specifications for imported diagnostic platforms. Stakeholders must weigh capital deployment toward mass spectrometry infrastructure against the installed base of immunoassay analyzers when forecasting test menu expansion.
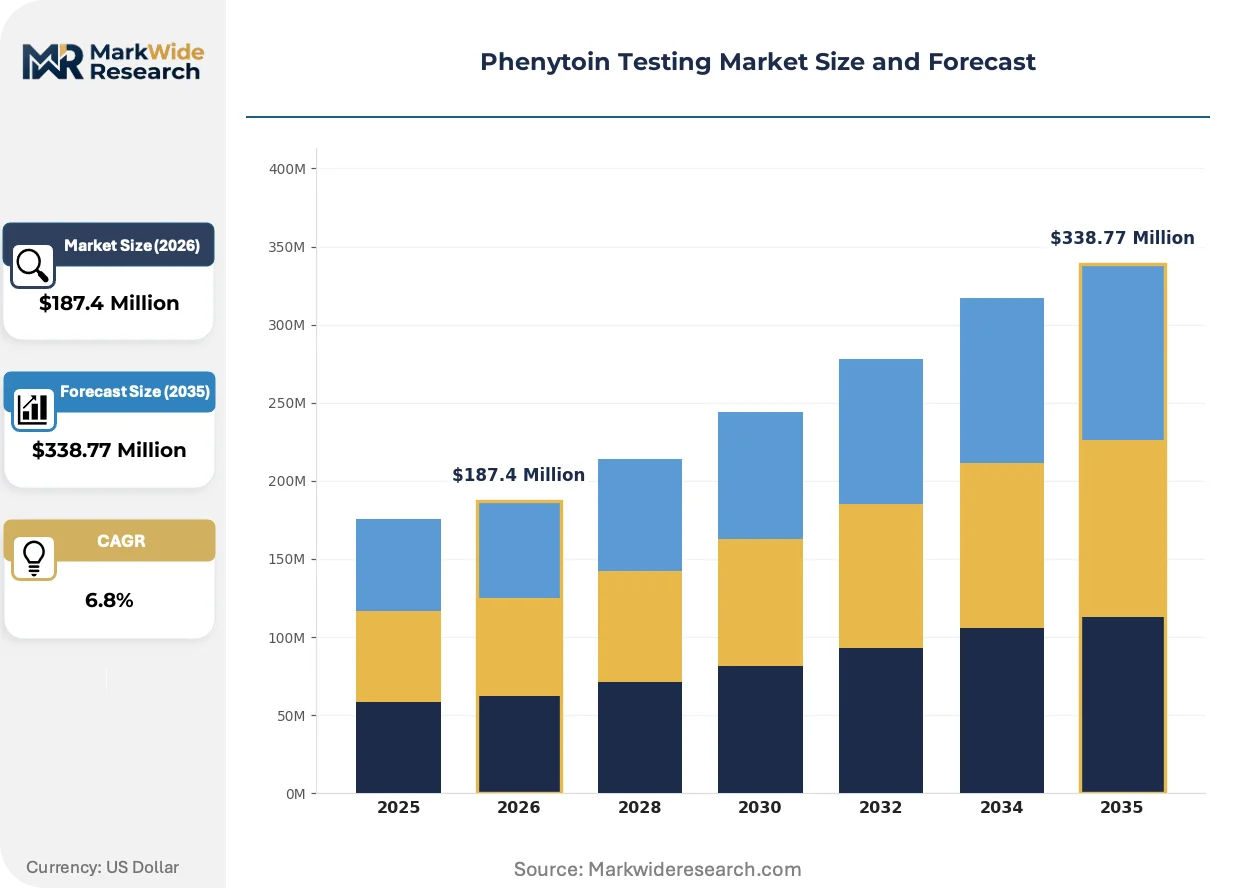
Market Dynamics
Liquid chromatography-tandem mass spectrometry is compressing turnaround times and assay costs, forcing laboratories to rebalance capital deployment between chromatography infrastructure and legacy immunoassay analyzers.
Growth Catalysts
- FDA Clinical Laboratory Improvement Amendments:Tightening analytical performance requirements for quantitative phenytoin assays are accelerating replacement cycles in hospital laboratories seeking compliant platforms.
- Pharmacogenomic research institutes:Investigations linking CYP2C9 polymorphisms to phenytoin metabolism variability are expanding test volumes beyond traditional therapeutic drug monitoring.
- Germany's university hospital networks:Centralized reference laboratories processing high-volume epilepsy patient cohorts are consolidating procurement power for advanced analytical systems.
Market Restraints
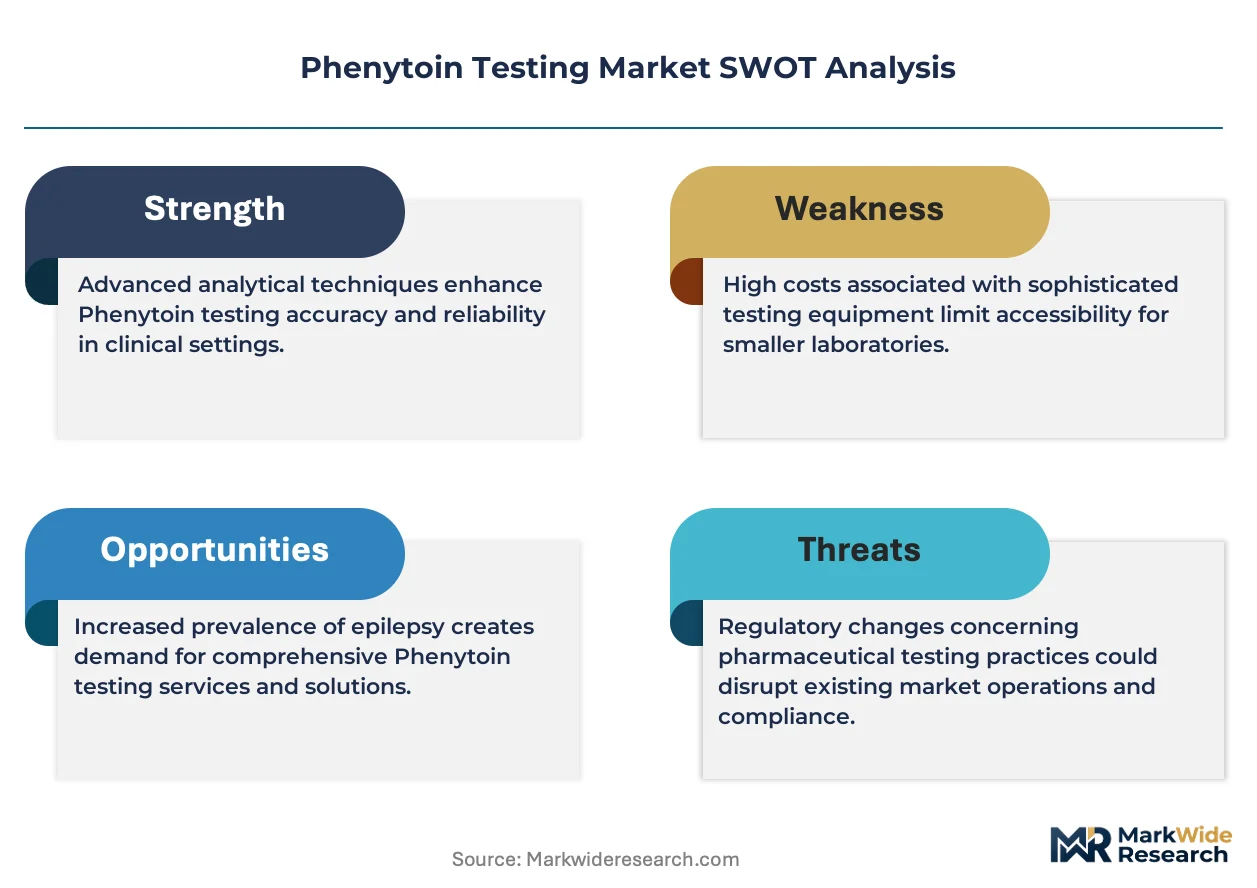
- Capital intensity of mass spectrometry:LC-MS/MS platforms require substantial upfront investment and specialized infrastructure, limiting adoption in smaller hospital laboratories.
- Reagent supply concentration:Immunoassay reagent production concentrates among a limited supplier base, creating vulnerability to input cost volatility and allocation constraints.
- Cross-reactivity limitations:Immunoassay platforms face inherent specificity constraints when metabolite interference compromises phenytoin quantification accuracy.
Strategic Opportunities
- Research institute expansion:Pharmacogenomic and personalized medicine programs in academic medical centers represent underpenetrated demand for high-precision phenytoin testing.
- Integrated multi-drug panels:Chromatography systems enabling simultaneous antiepileptic drug quantification are capturing premium placement through per-sample cost reduction.
- ISO 15189 accreditation pathways:Quality management standards are creating competitive differentiation for laboratories demonstrating analytical rigor in epilepsy management protocols.
Industry Challenges
- Mass spectrometry specialist shortage:LC-MS/MS operation and maintenance require scarce technical expertise, constraining laboratory expansion timelines.
- Legacy analyzer integration:Hospital laboratories face workflow friction when connecting new chromatography platforms to existing laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenytoin Testing Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Diagnostic Kits, Assay Systems, Instruments End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics Technology: Immunoassays, Chromatography, Mass Spectrometry, Enzyme-Linked Immunosorbent Assay Application: Therapeutic Monitoring, Toxicology Testing, Pharmacokinetic Studies, Research Applications |
| Companies Covered | Thermo Fisher Scientific, Abbott, Danaher, F. Hoffmann-La Roche, Neogen, Sekisui Medical, Randox Laboratories, Quest Diagnostics, ARUP Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenytoin Testing Market Evolving Landscape
Automation, regulatory harmonization, and procurement consolidation are converging to reshape how phenytoin testing platforms are specified, deployed, and operated across clinical and research environments.
Automated sample preparation systems for liquid chromatography-tandem mass spectrometry are automating pre-analytical workflows that previously required manual technician intervention. Reference laboratories in Germany and the United States are deploying these platforms to achieve 24-hour turnaround for urgent therapeutic monitoring requests. This automation is compressing labor costs per test while reducing pre-analytical error rates that compromise assay reliability.
Europe's In Vitro Diagnostic Regulation is imposing escalating analytical validation documentation requirements on phenytoin assay manufacturers seeking CE marking. Manufacturers must now demonstrate extended performance characteristics across multiple instrument configurations and reagent lots. Academic medical centers and commercial reference laboratories are prioritizing suppliers with established technical files, reshaping competitive positioning for platform selection.
Consolidated procurement through centralized laboratory networks is displacing decentralized purchasing decisions in multi-hospital health systems. Germany's university hospital networks and integrated delivery networks in the United States are negotiating enterprise-wide contracts for phenytoin testing platforms, extracting volume-based pricing concessions. This concentration is most visible in metropolitan regions where health system mergers have created single procurement entities controlling dozens of hospital laboratories.
Phenytoin Testing Market Segmentation
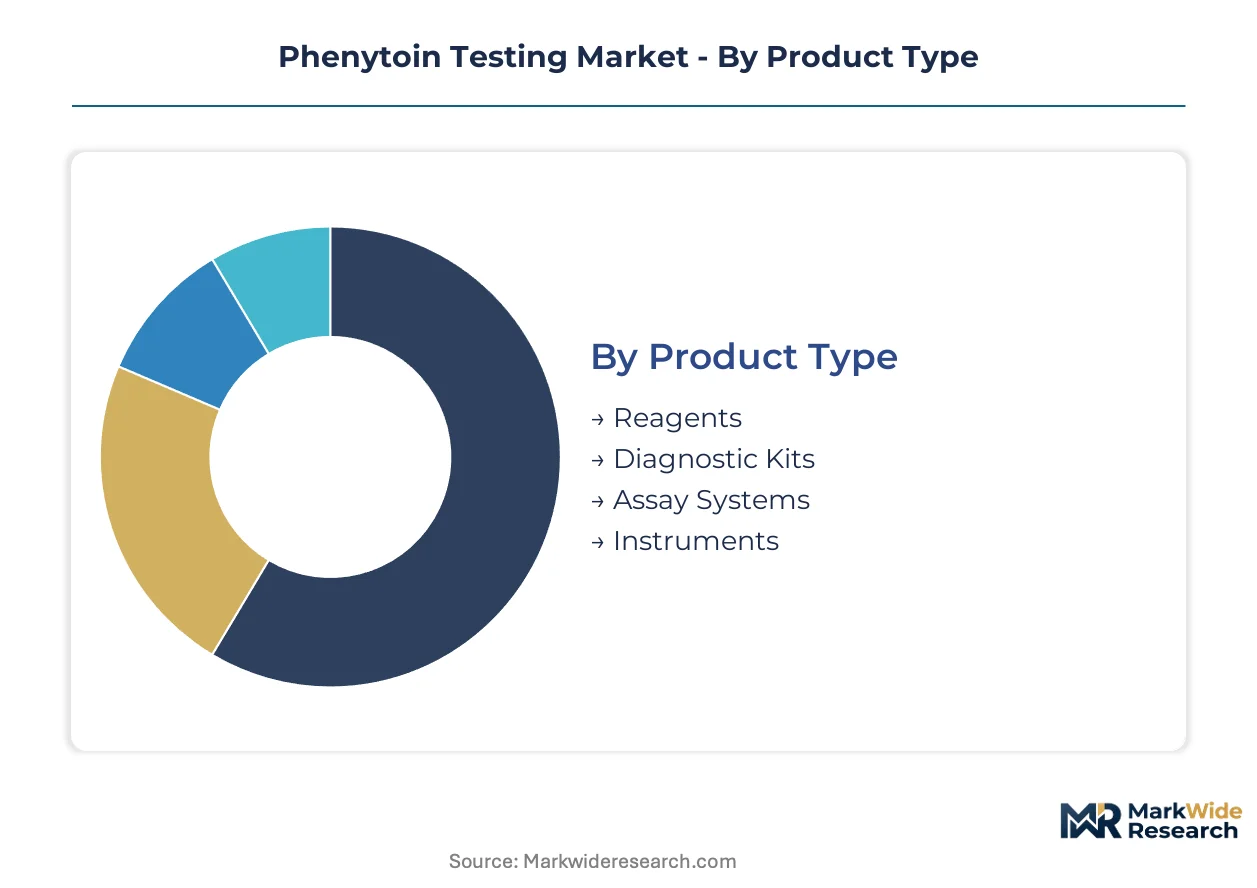
Phenytoin testing segments diverge sharply in regulatory burden and capital requirements. Certification pathways from FDA, EMA, and METI create tiered barriers that reshape competitive positioning across product categories and end-user channels.
Product Type:
FDA Clinical Laboratory Improvement Amendments and EU IVDR impose escalating validation demands that segment manufacturers by compliance infrastructure depth.
- Reagents:Calibrator and control materials for phenytoin quantification require lot-to-lot stability documentation under ISO 15189. Hospital laboratories in Germany's university hospital networks concentrate procurement for high-throughput reagent contracts. Reagent supply concentration creates vulnerability to input cost volatility.
- Diagnostic Kits:Pre-packaged assay consumables bundle reagents with protocol documentation for standardized workflows. Diagnostic laboratories in the United States prioritize kits with FDA 510(k) clearance for rapid deployment. Kits face margin pressure from integrated system vendors.
- Assay Systems:Chromatography-based assay systems command premium placement in academic medical centers where simultaneous multi-drug panels reduce per-sample costs.
- Instruments:LC-MS/MS platforms require substantial upfront investment and specialized infrastructure, limiting adoption in smaller hospital laboratories.
Reagents sit at the top of the volume ranking, with assay systems climbing the fastest.
End User:
Customer type determines pricing tolerance and technical specification rigor, from emergency turnaround requirements to research-grade precision demands.
- Hospitals:Emergency departments and neurology units demand rapid turnaround for therapeutic drug monitoring, prioritizing immunoassay platforms integrated into core laboratory analyzers. Hospital laboratories in the United States are expanding therapeutic drug monitoring programs for antiepileptic medications. Tightening FDA analytical performance requirements accelerate replacement cycles.
- Diagnostic Laboratories:Commercial reference laboratories process high-volume phenytoin testing with 24-hour turnaround targets, deploying automated sample preparation systems to compress labor costs. Germany's centralized reference laboratories consolidate procurement power for advanced analytical systems. ISO 15189 accreditation standards constrain operations in Japan's hospital networks.
- Research Institutes:Pharmacogenomic investigations linking CYP2C9 polymorphisms to phenytoin metabolism variability are expanding test volumes beyond traditional therapeutic drug monitoring.
- Clinics:Outpatient neurology practices require point-of-care compatible platforms with simplified workflows and minimal technical expertise requirements.
Diagnostic laboratories capture the highest absolute volume, with research institutes expanding most quickly.
Technology:
Capital intensity and specialist availability segment laboratories by platform selection, with mass spectrometry requiring infrastructure investments that immunoassays avoid.
- Immunoassays:Automated chemiluminescent and fluorescence polarization assays dominate hospital laboratories prioritizing rapid turnaround for emergency therapeutic monitoring. Cross-reactivity limitations compromise specificity when metabolite interference affects quantification accuracy.
- Chromatography:High-performance liquid chromatography with ultraviolet detection offers intermediate precision at moderate capital cost for mid-volume laboratories.
- Mass Spectrometry:Liquid chromatography-tandem mass spectrometry is compressing turnaround times and assay costs, forcing laboratories to rebalance capital deployment. LC-MS/MS operation and maintenance require scarce technical expertise, constraining laboratory expansion timelines.
- Enzyme-Linked Immunosorbent Assay:ELISA formats serve research applications and resource-constrained settings with manual workflow requirements and lower throughput ceilings.
Immunoassays retain the largest installed base, with mass spectrometry gaining share fastest.
Application:
Clinical urgency and reimbursement pathways differentiate segments, from routine therapeutic monitoring to specialized toxicology and research investigations.
- Therapeutic Monitoring:Quantitative serum concentration measurement guides dosing adjustments in epilepsy management, requiring detection thresholds below therapeutic ranges of micrograms per milliliter. Therapeutic drug monitoring programs in the United States are expanding across hospital networks.
- Toxicology Testing:Emergency department overdose evaluations and forensic investigations demand rapid qualitative and quantitative phenytoin detection.
- Pharmacokinetic Studies:Drug interaction and bioavailability investigations in clinical trial settings require intensive sampling protocols and high analytical precision.
- Research Applications:Pharmacogenomic and personalized medicine programs in academic medical centers represent underpenetrated demand for high-precision phenytoin testing.
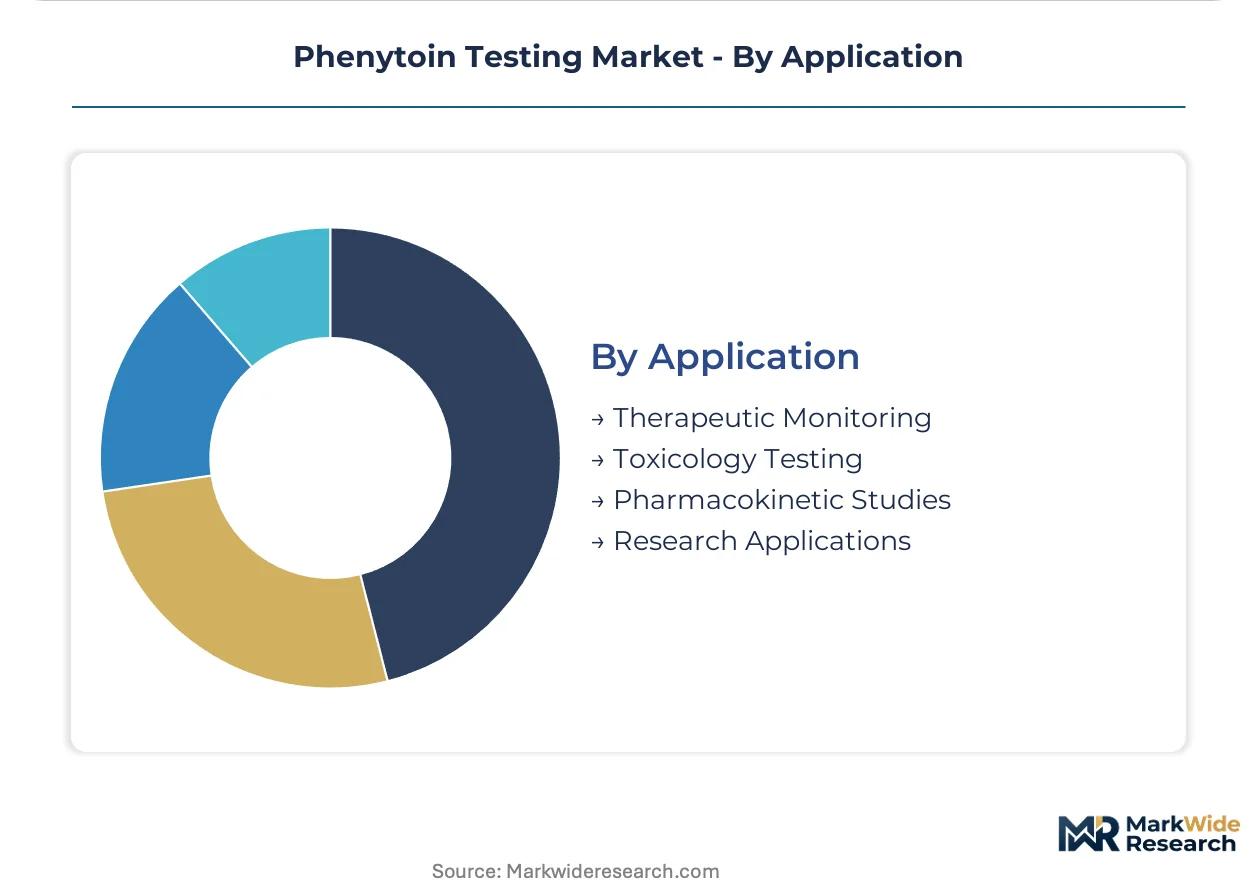
Therapeutic monitoring commands the highest test volume, with research applications showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's university hospital networks anchor phenytoin testing demand through centralized reference laboratories processing high-volume epilepsy patient cohorts. FDA tightening of analytical performance requirements and Japan's METI procurement guidelines are reshaping platform specifications across hospital networks. Regional expansion concentrates in academic medical centers and commercial reference laboratories with mass spectrometry infrastructure.
United States
Hospital laboratories across the United States are expanding therapeutic drug monitoring programs for antiepileptic medications at scale. FDA Clinical Laboratory Improvement Amendments continue tightening analytical performance requirements for quantitative phenytoin assays. Integrated delivery networks in metropolitan regions negotiate enterprise-wide contracts controlling dozens of hospital laboratories.
Germany
University hospital networks concentrate procurement power for advanced analytical systems serving high-volume epilepsy cohorts. EU In Vitro Diagnostic Regulation imposes escalating analytical validation documentation requirements for CE marking. Centralized reference laboratories in metropolitan academic clusters process phenytoin testing with 24-hour turnaround targets.
Japan
Hospital networks prioritize ISO 15189 accreditation standards constraining laboratory operations and platform selection. METI guidelines shape procurement specifications for imported diagnostic platforms including chromatography systems. Academic medical centers in the Kanto region deploy automated sample preparation for urgent therapeutic monitoring.
China
Pharmacogenomic investigations linking CYP2C9 polymorphisms to phenytoin metabolism variability are expanding test volumes in research institutes. NMPA regulatory pathways for in vitro diagnostics are tightening validation requirements for quantitative assays. Yangtze River Delta academic medical centers invest in mass spectrometry infrastructure for multi-drug therapeutic panels.
United Kingdom
Commercial reference laboratories process high-volume phenytoin testing with compressed turnaround requirements for neurology units. MHRA alignment with EU IVDR standards is extending performance characterization demands across reagent lots. London-Southeast laboratory networks consolidate procurement for chromatography platforms serving NHS hospital trusts.
Phenytoin Testing Market Competitive Landscape
Global majors compete with regional champions across technology platform deployment and reference laboratory contracting. The vendor base segments between integrated diagnostics conglomerates and specialized analytical instrument manufacturers. Three archetypes dominate: chromatography portfolio anchors, immunoassay-integrated platform providers, and precision analytical instrument specialists. Competitive moves concentrate on mass spectrometry infrastructure partnerships and multi-year service contracts for high-throughput laboratory networks.
Among diversified diagnostics conglomerates, Thermo Fisher Scientific and Abbott exemplify contrasting platform strategies. Thermo Fisher Scientific occupies a position representing chromatography portfolio anchors leveraging analytical instrument breadth. Abbott sits within the immunoassay-integrated tier, embedding testing architectures within core laboratory analyzer ecosystems. Danaher represents precision positioning through analytical instrument subsidiaries serving reference laboratory segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott |
| Danaher |
| F. Hoffmann-La Roche |
| Neogen |
| Sekisui Medical |
| Randox Laboratories |
| Quest Diagnostics |
| ARUP Laboratories |
| Others |
Value Network & Pricing Analysis
ISO 15189 accreditation standards gate qualified supply access for phenytoin testing platforms in Japan's hospital networks, with laboratories bearing certification costs that feed into premium-tier pricing for compliant reagent contracts. Buyers in Germany's university hospital networks extract volume concessions from suppliers, while smaller diagnostic laboratories face price compression from reagent supply concentration among limited manufacturers.
Pricing Analysis
Input-cost pass-through from specialized chromatography consumables and mass spectrometry reagents shapes phenytoin testing economics, with suppliers indexing calibrator and control material pricing to raw material volatility. Three-tier pricing structure across premium, standard, and economy levels separates LC-MS/MS platforms from immunoassay-integrated systems and manual ELISA formats. Pricing pressure stems from consolidated procurement through centralized laboratory networks in metropolitan health systems. Hospital emergency departments demonstrate highest price sensitivity due to budget constraints, while academic medical centers prioritize analytical precision over unit cost.
Supply Chain Analysis
Direct-to-reference-laboratory channels handle high-volume phenytoin testing demand in Germany and the United States, bypassing distribution intermediaries for enterprise-wide contracts. Manufacturing concentration for immunoassay reagents centers on the United States, Germany, and Japan, with chromatography consumables drawing from specialized chemical suppliers in Switzerland and the Netherlands. Critical dependencies include high-purity solvents, isotopically labeled internal standards, and antibody reagents. Single-source vulnerability for mass spectrometry ionization sources creates procurement risk for laboratories expanding LC-MS/MS capacity. Distribution runs through regional diagnostic distributors serving hospital networks and independent reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phenytoin testing represents a late-cycle quality story as pharmacogenomic research institutes shift demand toward high-precision mass spectrometry platforms with documented CYP2C9 metabolite discrimination capability.
For Market Incumbents: Deploy multi-year service contracts as the anchor lever to lock reference laboratory relationships against emerging chromatography specialists. Incumbents should deepen backward integration into isotopically labeled internal standard production to secure reagent supply continuity. FDA tightening of analytical performance requirements threatens immunoassay-embedded platforms, accelerating replacement cycles that favor mass spectrometry infrastructure providers with established technical files. For New Entrants and Emerging Players: Automated sample preparation technology offers entry wedge against legacy manual workflow incumbents. White-space targets include China's Yangtze River Delta academic medical centers investing in multi-drug therapeutic panels and mid-volume diagnostic laboratories in the United Kingdom seeking ISO 15189-compliant platforms. Research institute procurement channels present the most penetrable segment due to fragmented purchasing authority. Go-to-market positioning should emphasize 24-hour turnaround capability with compressed labor costs per test. For Investors and Strategic Acquirers: Roll-up economics work for precision analytical instrument specialists because reference laboratory consolidation in Germany and the United States creates demand for standardized platform fleets. Long-term viability hinges on mass spectrometry service infrastructure rather than hardware margins alone. Acquisition targets should demonstrate installed base density in metropolitan health system clusters. The signal to watch is hospital laboratory outsourcing trends that shift test volume toward commercial reference laboratories with enterprise contracting leverage.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Infrastructure Partnership | Thermo Fisher Scientific anchors high-throughput contracts across North American health systems with chromatography breadth. |
| Automated Sample Preparation Deployment | Germany's reference laboratories achieve 24-hour turnaround targets while compressing pre-analytical error rates. |
| ISO 15189 Accreditation Investment | Japan's hospital networks constrain platform selection to suppliers with documented quality management systems. |
| Multi-Drug Panel Integration | Academic medical centers capture per-sample cost reduction through simultaneous antiepileptic drug quantification. |
| Enterprise Procurement Consolidation | Integrated delivery networks in metropolitan United States regions extract volume-based pricing from reagent suppliers. |
Research Methodology
Bottom-up hospital laboratory modeling reconciled against top-down reagent manufacturer tracking forms the analytical core of this study. Primary interviews with clinical laboratory directors, reference laboratory operations managers, biomedical engineers, and GPO contracts managers informed capacity expansion timelines and procurement specification shifts. Secondary validation drew from FDA 510(k) filings, EU IVDR technical documentation, hospital procurement databases, and CMS Medicare laboratory fee schedule data. Triangulation between demand-side test volume assumptions and supply-side reagent production capacity ensured forecast consistency.
Input-output matrices mapped phenytoin testing demand across technology platform, end-user channel, and application segments throughout the projection horizon. Modeled dimensions included assay methodology, laboratory scale tier, and regional regulatory cluster. CAGRs derived from segment-level test volume growth rates applied against per-test pricing trajectories. Forecast inputs incorporated pharmacogenomic research funding flows, hospital laboratory outsourcing rates, and mass spectrometry specialist availability constraints.
The model holds under stable regulatory enforcement intensity; deviation in FDA CLIA analytical performance thresholds or EU IVDR documentation requirements would shift platform replacement timelines. Forecasts reflect assumptions regarding consolidated procurement concentration and reagent supply stability. Specific risk factors include mass spectrometry technical specialist shortages constraining laboratory expansion and cross-reactivity limitations accelerating immunoassay displacement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Sterility Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
Ferritin Testing Market
Testing Services
Drug Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Lab Screening Test Kit Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
Home Care Testing Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Global Bioburden Testing Market