
 Asia-Pacific Hereditary Cancer Testing Market | 2026-2036
Asia-Pacific Hereditary Cancer Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hereditary Cancer Testing Market Outlook
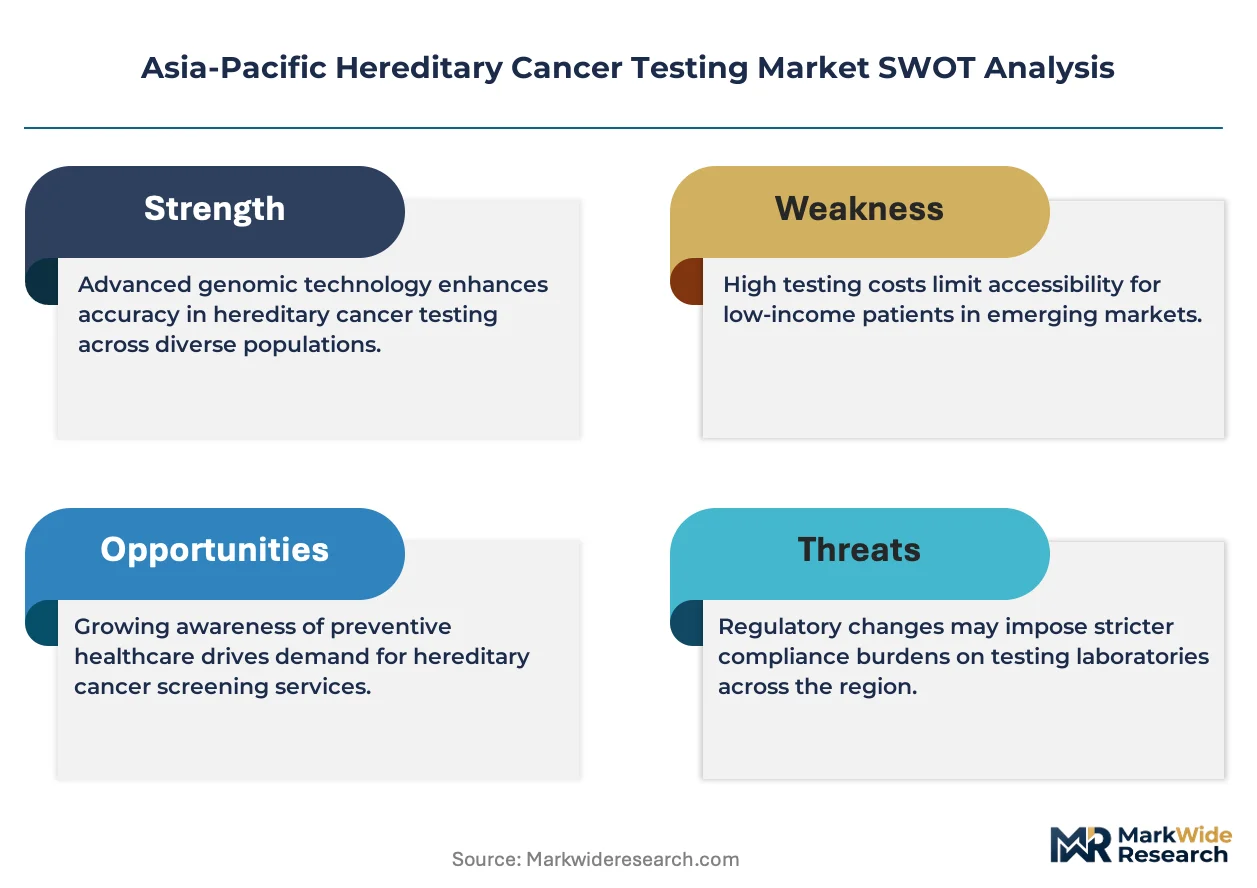
Hospital procurement channels across Southeast Asia and South Asia are reshaping how hereditary cancer testing kits reach end users, with centralized tender systems replacing fragmented purchasing. BGI Genomics Co., Ltd. leverages its manufacturing scale to dominate government laboratory contracts in China. MedGenome Labs Ltd. anchors its position through specialized oncology-focused gene panels tailored to South Asian mutation profiles. Strand Life Sciences Pvt. Ltd. competes on R&D intensity, sustaining development of population-specific Lynch Syndrome assays.
Hereditary cancer testing encompasses molecular diagnostic procedures that detect germline mutations in BRCA1/2, mismatch repair genes, and other oncogenic loci through blood or saliva samples, typically employing next-generation sequencing with read depths exceeding 100x to ensure variant calling accuracy. The primary purpose centers on stratifying individual cancer risk to enable preventive surveillance, prophylactic surgery decisions, and cascade screening of at-risk relatives. Gene panels and next-generation sequencing together command the dominant share of test volume, as multi-gene approaches displace single-site BRCA testing by offering superior diagnostic yield per specimen. Diagnostic labs and hospitals constitute the primary end-user destinations, with hospital-based genetic counseling programs driving higher test adherence rates than standalone clinic referrals.
China's NMPA genetic test registration requirements and India's CDSCO in vitro diagnostic rules together shape product approval timelines and clinical validation standards for market entrants. Japan's PMDA and South Korea's MFDS impose additional quality benchmarks that filter out lower-complexity assay providers. Australia's TGA recognition framework creates pathway efficiencies for tests already approved by reference regulators. Stakeholders must monitor evolving reimbursement decisions by national health insurers across the region, as coverage expansion for BRCA and Lynch Syndrome screening remains the decisive variable for volume scalability.
Market Dynamics
Centralized hospital procurement systems across Southeast Asia and South Asia are consolidating purchasing power, compressing margins for standalone hereditary cancer testing kit vendors while favoring manufacturers with scale to absorb tender-driven price compression.
Growth Catalysts
- Multi-gene panel expansion:Next-generation sequencing platforms now detect BRCA1/2, Lynch Syndrome genes, and rare oncogenic variants in single workflows, elevating diagnostic yield per specimen above single-site testing.
- China's NMPA streamlining:Accelerated genetic test registration pathways have shortened approval timelines for multi-gene panels, enabling faster commercialization of expanded carrier screening.
- Tier-one city demand concentration:Beijing, Shanghai, and Guangzhou generate disproportionate test volumes due to concentrated tertiary hospital infrastructure and genetic counseling capacity.
Market Restraints
- Reimbursement fragmentation:India's CDSCO diagnostic rules lack harmonized national coverage for hereditary cancer screening, forcing patients to absorb out-of-pocket costs that dampen volume scalability.
- Sample logistics constraints:Cold chain infrastructure gaps in Indonesia and Philippines degrade specimen integrity for saliva-based collection kits, elevating invalid result rates.
- Genetic counselor scarcity:The region's clinical genetics workforce remains concentrated in metropolitan diagnostic corridors, creating interpretation bottlenecks that extend report turnaround times.
Strategic Opportunities
- Vietnam and Philippines penetration:These markets exhibit sub-5% hereditary cancer screening penetration among eligible high-risk populations, presenting first-mover advantages for localized gene panels.
- Telemedicine-integrated counseling:Remote genetic counseling platforms are collapsing geographic barriers to pre-test consent and post-test interpretation, extending reach beyond hospital-based programs.
- Japan's PMDA quality benchmarks:Stringent analytical validation requirements filter out lower-complexity competitors, creating protected market space for laboratories with documented 100x+ read depth protocols.
Industry Challenges
- Variant classification expertise:The region lacks sufficient molecular pathologists trained in ACMG guidelines for germline variant interpretation, forcing laboratories to outsource tertiary review to Australian or North American reference centers.
- Laboratory information system integration:Legacy hospital IT architectures in India's public sector resist API-based connectivity with cloud-based variant interpretation pipelines, fragmenting data workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hereditary Cancer Testing Market |
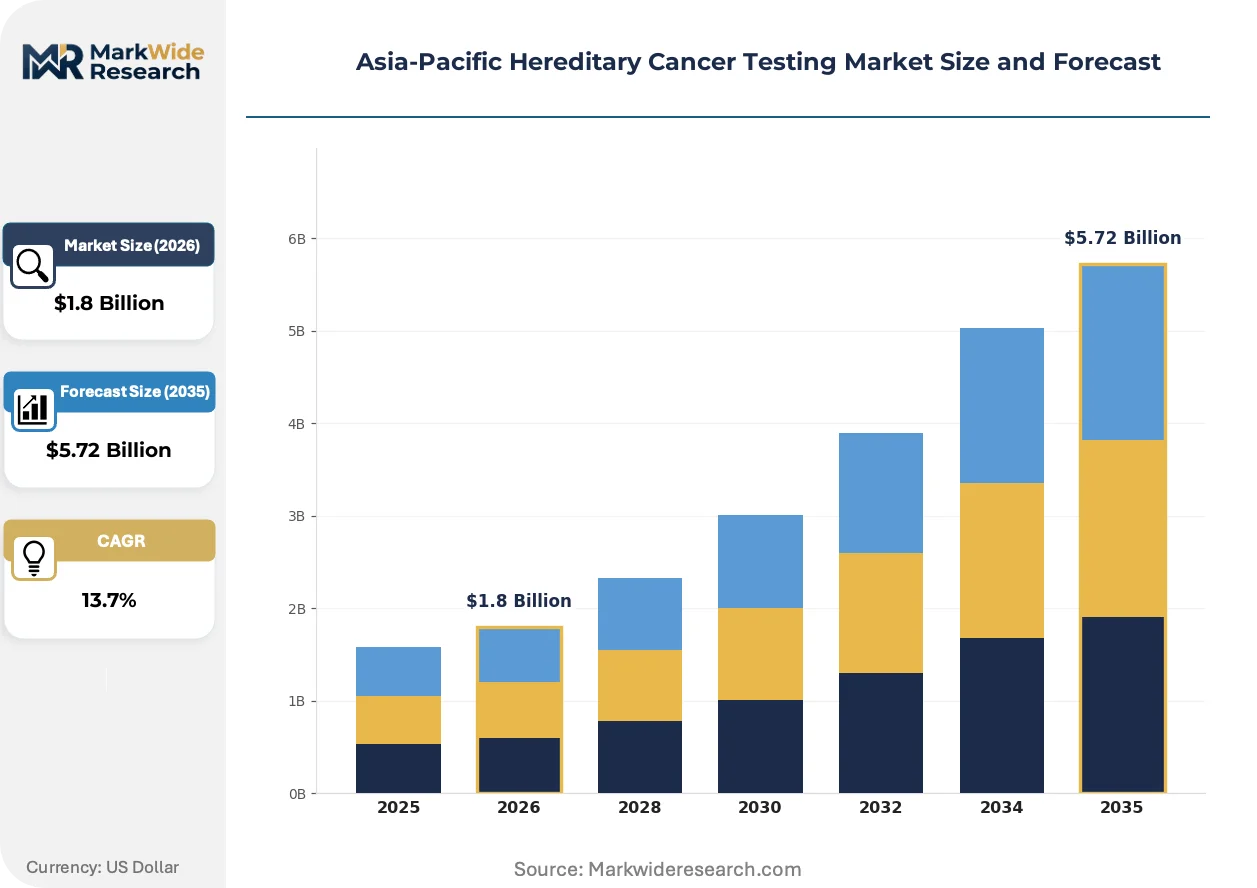
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: BRCA, Lynch Syndrome, Next-Generation Sequencing, Gene Panels Technology: Sanger Sequencing, PCR, Microarray, Whole Exome Sequencing End User: Hospitals, Clinics, Diagnostic Labs, Research Institutions Distribution Channel: Direct Sales, Online Sales, Distributors, Partnerships |
| Companies Covered | BGI Genomics Co., Ltd., MedGenome Labs Ltd., Strand Life Sciences Pvt. Ltd., Prenetics Limited, Gene Solutions, PathGen Diagnostics Pvt. Ltd., 4baseCare, Mapmygenome, Myriad Genetics, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hereditary Cancer Testing Market Strategic Shifts
Cloud-based bioinformatics pipelines are compressing variant interpretation timelines from weeks to days, fundamentally altering competitive positioning around report turnaround speed rather than wet-lab throughput alone.
Artificial intelligence-assisted variant prioritization software is digitizing the manual curation workflow for VUS (variants of uncertain significance) classification. Diagnostic laboratories in Singapore and South Korea are deploying these tools at scale, reducing genetic counselor review burden by automating literature mining and segregation analysis. This compression of interpretation labor is enabling higher test volumes without proportional staffing expansion.
South Korea's MFDS has implemented phased-in quality management system requirements for laboratory-developed tests, mandating documented traceability from specimen accession through variant reporting. The regulation forces mid-sized laboratories to invest in LIMS upgrades or exit the hereditary cancer testing category entirely. Seoul-based reference laboratories are consolidating market share by absorbing compliance costs that smaller competitors cannot shoulder.
Direct-to-consumer genetic testing platforms are disintermediating traditional physician-referral channels in Australia's metropolitan markets, though TGA oversight limits clinical-grade claims. Consumers in Sydney and Melbourne are purchasing BRCA screening online, then seeking confirmatory testing through hospital genetics departments when positive results emerge. This two-step pattern is straining genetic counseling capacity and creating liability ambiguity around unsupervised result disclosure.
Asia-Pacific Hereditary Cancer Testing Market Segmentation
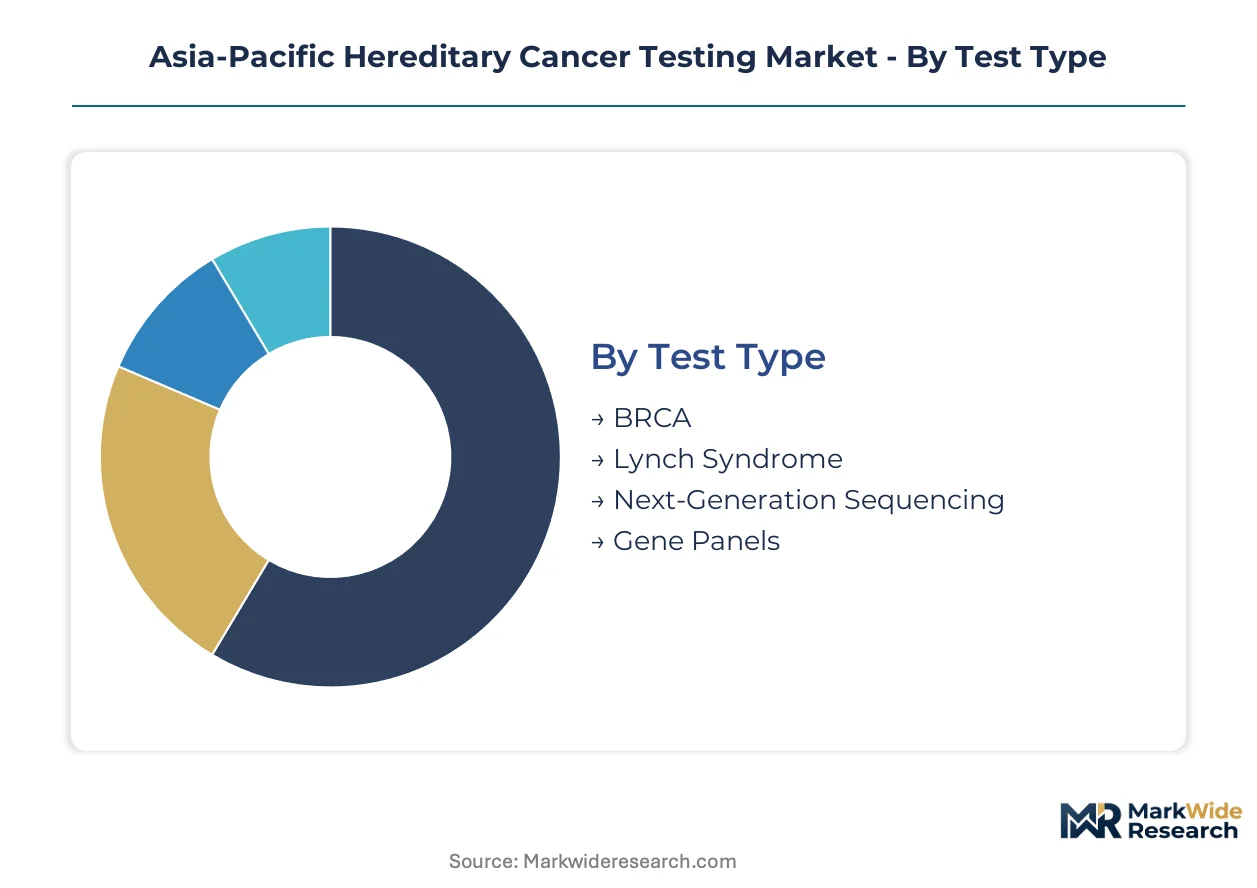
Hereditary cancer testing in the Asia-Pacific region fragments across multiple technical and commercial dimensions that determine reimbursement pathways, procurement channels, and laboratory infrastructure investments. Understanding these segment boundaries clarifies why test volumes concentrate in specific end-user settings and which technology platforms capture disproportionate margin.
Test Type:
Mature single-gene assays coexist with emerging multi-gene approaches across the maturity spectrum, creating tiered diagnostic workflows that laboratories deploy based on clinical indication complexity and payer coverage.
- BRCA:Germline mutation screening for BRCA1 and BRCA2 variants remains the most clinically validated entry point for hereditary breast and ovarian cancer risk assessment. Demand concentrates in China's tier-one city hospital genetics departments and India's metropolitan oncology centers, driven by established reimbursement for high-risk patient stratification.
- Lynch Syndrome:Mismatch repair gene testing for colorectal and endometrial cancer predisposition requires immunohistochemistry pre-screening followed by confirmatory sequencing. South Korea's National Cancer Screening Program and Japan's hospital-based tumor board protocols generate concentrated demand, constrained by genetic counselor availability for post-test family cascade screening.
- Next-Generation Sequencing:High-throughput platforms enable simultaneous interrogation of multiple oncogenic loci with read depths exceeding 100x.
- Gene Panels:Curated multi-gene assays combine BRCA, Lynch Syndrome, and moderate-risk genes in single workflows.
BRCA testing retains volume leadership; gene panels hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy methods from premium sequencing platforms, with procurement budgets determining which laboratories can sustain next-generation infrastructure.
- Sanger Sequencing:First-generation capillary electrophoresis remains the gold standard for single-site variant confirmation and familial mutation tracking. India's CDSCO-registered reference laboratories and China's provincial hospital networks deploy Sanger for targeted follow-up of NGS-detected variants, constrained by lower throughput and higher per-sample labor costs.
- PCR:Polymerase chain reaction-based methods enable rapid, cost-effective detection of known founder mutations in specific populations. Diagnostic corridors in South Asia leverage PCR for BRCA1/2 hotspot screening, though limited variant detection scope restricts clinical utility in genetically heterogeneous populations.
- Microarray:Chip-based comparative genomic hybridization identifies large genomic rearrangements invisible to short-read sequencing.
- Whole Exome Sequencing:Comprehensive protein-coding region analysis captures rare and novel variants beyond targeted panels.
PCR retains volume leadership; whole exome sequencing holds the steepest expansion curve.
End User:
Customer type determines test adherence rates and pre-test counseling completeness, with hospital-integrated programs outperforming standalone referrals on clinical utility metrics.
- Hospitals:Tertiary medical center genetics departments combine oncologist referral pathways with embedded genetic counseling programs. China's tier-one city hospitals and Japan's National Cancer Center network generate the highest test volumes, supported by multidisciplinary tumor boards that integrate testing into standard care protocols.
- Clinics:Outpatient specialty practices in gynecologic oncology and gastroenterology serve as initial access points for at-risk patients. Australia's metropolitan private clinics and South Korea's cancer screening centers drive demand, though fragmented pre-test consent processes elevate variant interpretation complexity.
- Diagnostic Labs:Independent reference laboratories process specimens from multiple referring sites with centralized bioinformatics pipelines.
- Research Institutions:Academic medical centers conduct population genomic studies and novel variant discovery.
Hospitals retain volume leadership; diagnostic labs hold the steepest expansion curve.
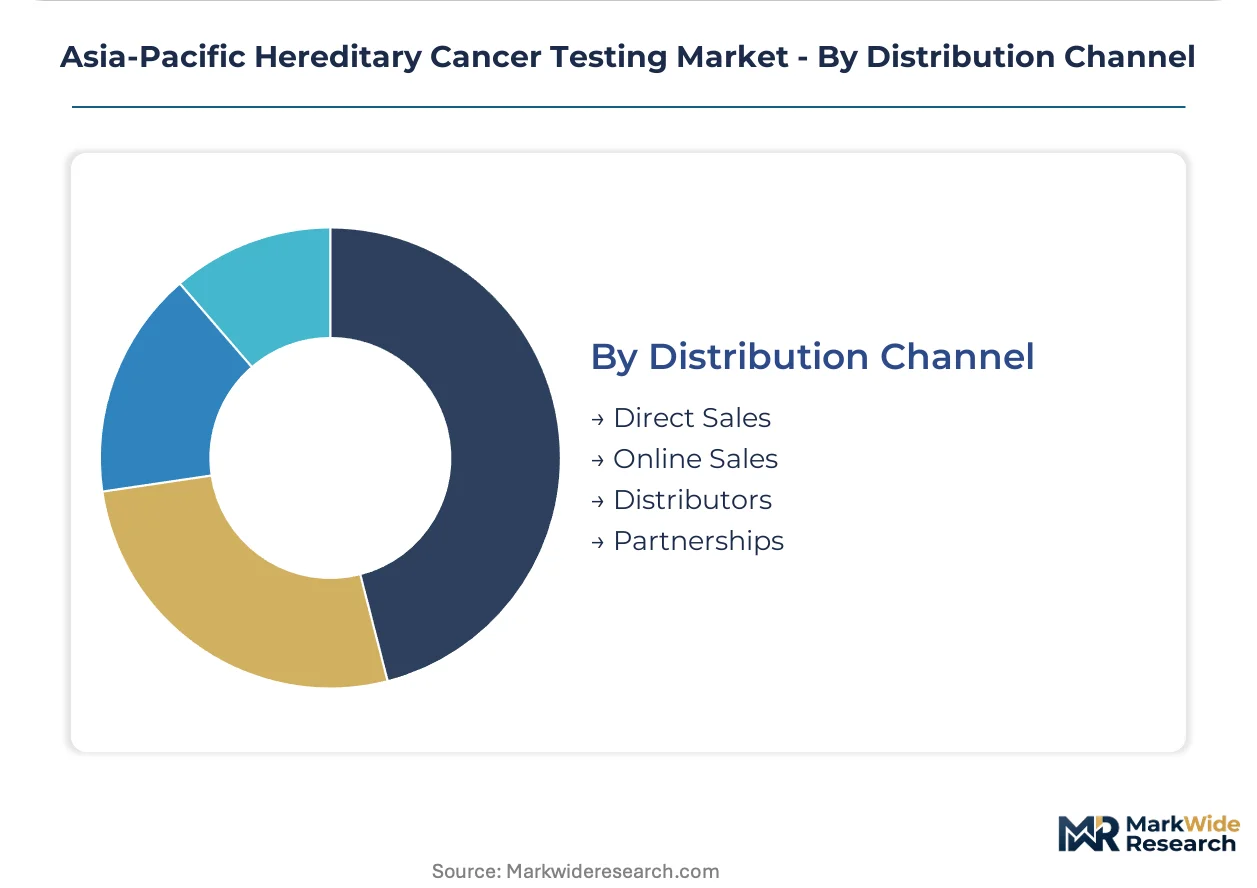
Distribution Channel:
Supply concentration varies by market maturity, with direct sales dominating institutional procurement and online channels emerging in consumer-facing segments.
- Direct Sales:Manufacturer field teams engage hospital laboratory directors and procurement committees for high-volume instrument and reagent contracts. BGI Genomics deploys direct sales forces across China's provincial health systems, securing multi-year supply agreements that lock out distributor intermediaries.
- Online Sales:E-commerce platforms and direct-to-consumer websites enable patient-initiated test kit ordering. Australia's TGA-regulated online channels and Singapore's telemedicine-integrated platforms are gaining transaction volume, though confirmatory testing requirements limit standalone clinical utility.
- Distributors:Regional medical supply networks extend reach into secondary cities and private laboratory segments.
- Partnerships:Strategic alliances between test developers and hospital systems create exclusive service arrangements.
Direct sales retain volume leadership; online sales hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA anchors the Asia-Pacific hereditary cancer testing landscape through streamlined genetic test registration pathways that compress approval timelines for multi-gene panels. The regulator's accelerated pathways enable faster commercialization of expanded carrier screening across the region's largest addressable market.
China
Beijing, Shanghai, and Guangzhou generate disproportionate test volumes through concentrated tertiary hospital infrastructure and genetic counseling capacity. NMPA's 2023 guidance on high-throughput sequencing-based genetic tests reduced clinical validation requirements for Class III diagnostic reagents. BGI Genomics leverages manufacturing scale to dominate government laboratory contracts across provincial health systems.
India
Metropolitan diagnostic corridors in Mumbai, Delhi, and Bangalore drive demand for BRCA and Lynch Syndrome screening among high-risk oncology patients. CDSCO's in vitro diagnostic rules shape product approval timelines, though national reimbursement remains fragmented across state-level health insurance schemes. MedGenome Labs anchors market position through specialized gene panels tailored to South Asian mutation profiles.
Japan
PMDA quality benchmarks filter out lower-complexity assay providers, creating protected market space for laboratories with documented validation protocols. The National Cancer Center network integrates hereditary testing into standard tumor board protocols. Tokyo and Osaka clusters concentrate both test volume and the limited clinical genetics workforce capable of variant interpretation.
South Korea
MFDS phased-in quality management system requirements for laboratory-developed tests mandate documented traceability from specimen accession through variant reporting. Seoul-based reference laboratories consolidate market share by absorbing compliance costs that smaller competitors cannot shoulder. The National Cancer Screening Program generates concentrated demand for mismatch repair gene testing.
Australia
TGA recognition framework creates pathway efficiencies for tests already approved by reference regulators, accelerating market entry for international assay providers. Direct-to-consumer platforms in Sydney and Melbourne are disintermediating traditional physician-referral channels, though confirmatory testing requirements limit standalone clinical utility. Telemedicine-integrated counseling extends reach beyond hospital-based programs.
Asia-Pacific Hereditary Cancer Testing Market Competitive Environment
Genomics platform operators and specialized reference laboratories split the market along capability and scale vectors. The vendor base concentrates around manufacturers with captive sequencing infrastructure and laboratories with population-specific assay portfolios. Two archetypes dominate: vertically integrated platform companies with government contract access, and specialized oncology-focused laboratories with mutation-profile expertise. Competitive dynamics center on M&A absorption of regional reference labs and strategic partnerships with tertiary hospital systems for exclusive service arrangements.
Within the integrated platform tier, BGI Genomics Co., Ltd. represents the scale-driven archetype through its position in China's provincial health procurement systems. MedGenome Labs Ltd. and Strand Life Sciences Pvt. Ltd. exemplify the specialized laboratory model, occupying positions defined by population-specific assay development rather than instrument manufacturing. These three entities anchor the competitive structure across the region's two largest addressable markets, with their respective strategic postures reflecting divergent bets on centralized manufacturing versus distributed clinical expertise.
| Leading Market Players |
|---|
| BGI Genomics Co., Ltd. |
| MedGenome Labs Ltd. |
| Strand Life Sciences Pvt. Ltd. |
| Prenetics Limited |
| Gene Solutions |
| PathGen Diagnostics Pvt. Ltd. |
| 4baseCare |
| Mapmygenome |
| Myriad Genetics, Inc. |
| Others |
Value Chain & Pricing Dynamics
Beijing's concentrated sequencing reagent manufacturing base generates asymmetric pricing power for domestic kit vendors serving China's provincial hospital networks, while import-dependent laboratories across Southeast Asia absorb currency-driven cost volatility that compresses operating margins.
Pricing Analysis
China-to-Australia price spreads exceed threefold for equivalent BRCA panels, with NMPA-registered domestic assays commanding premium positioning against CDSCO-imported alternatives in India. Pricing stratifies across hospital-direct, distributor-mediated, and online-direct tiers, with volume scale and genetic counselor bundling as primary differentiation drivers. Cost compression in mid-tier gene panels is intensifying because BGI Genomics leverages captive manufacturing to undercut regional competitors. Price-sensitive standalone diagnostic laboratories in Indonesia and Philippines defer multi-gene adoption, while tertiary hospital systems in Japan and South Korea absorb premium pricing for PMDA-validated and MFDS-registered assays.
Supply Chain Analysis
Extended payment terms from Seoul-based reference laboratories to Seoul-area consumables distributors illustrate how supplier financing stabilizes working capital for laboratories absorbing MFDS compliance costs. Sequencing instrument supply concentrates in China, South Korea, and the United States; reagent production draws from domestic fermentation capacity in China and contract manufacturing in Singapore. Illumina flow cells and Agilent capture probes constitute critical single-source dependencies vulnerable to export control restrictions. Distribution runs through direct sales teams for government laboratory contracts, with regional medical supply networks penetrating secondary cities in Vietnam and Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a reimbursement-driven cyclical recovery, with national health insurer coverage expansion for BRCA and Lynch Syndrome screening serving as the decisive volume inflection mechanism across the region.
For Market Incumbents: Insulate market position by deepening backward integration into population-specific assay development and securing exclusive partnerships with China's tier-one city hospital systems. Threat from telemedicine-integrated counseling platforms demands counter-investment in remote genetic counselor networks to preserve pre-test consent control. Certification investment in Australia's TGA recognition framework creates pathway efficiencies that lock out late entrants. For New Entrants and Emerging Players: Vietnam and Philippines diagnostic corridors represent the most penetrable entry point, with sub-5% screening penetration among eligible high-risk populations and minimal incumbent loyalty. Localized gene panels tailored to Southeast Asian mutation frequencies offer differentiation against standardized imports. Go-to-market through telemedicine-integrated platforms collapses geographic barriers without requiring embedded hospital genetics department presence. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance cost absorption favors scaled reference laboratories over fragmented mid-tier competitors. Acquisition targets with documented 100x+ read depth protocols and ACMG-trained variant interpretation capacity command defensive positioning. Signal to watch is MFDS and PMDA enforcement intensity, as accelerated quality management mandates would force exit of undercapitalized laboratories and concentrate share among Seoul-based and Tokyo-based consolidators.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Gene Panel Regulatory Registration | NMPA streamlining accelerates commercialization timelines for expanded carrier screening across China's provincial health systems. |
| Telemedicine-Integrated Counseling Platform | Remote pre-test consent and post-test interpretation extends reach beyond hospital-based genetic counseling programs in Australia. |
| Population-Specific Assay Development | South Asian mutation profile tailoring anchors MedGenome's competitive position against standardized international gene panels. |
| Hospital System Exclusive Partnership | BGI Genomics secures multi-year supply agreements that lock out distributor intermediaries in China's government laboratory contracts. |
| LIMS Upgrade and Compliance Investment | MFDS-mandated traceability documentation forces mid-sized laboratories to invest or exit the hereditary cancer testing category. |
Study Parameters
The analysis maps gene panel testing, single-gene assays, and next-generation sequencing workflows, each validated through laboratory directors, hospital procurement managers, genetic counselors, and regulatory affairs specialists across the Asia-Pacific region. Primary interviews with these stakeholders combined with secondary validation from NMPA registration databases, CDSCO in vitro diagnostic filings, PMDA approval records, and MFDS quality management system audits. Bottom-up test volume modeling and top-down market sizing triangulate across hospital procurement databases and national cancer screening program disclosures.
Assumptions held fixed include current NMPA, CDSCO, PMDA, and MFDS regulatory frameworks, while reimbursement expansion trajectories and telemedicine penetration rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass test type, technology platform, end-user setting, and distribution channel, with regional regulatory clusters as an additional cross-cutting dimension. CAGRs were derived from test volume build-ups applied to average revenue per test estimates, incorporating sequencing reagent cost curves and genetic counselor labor cost inflation as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility, healthcare budget allocation priorities, or cross-border specimen logistics restrictions would shift the trajectory. Forecasts reflect documented assumptions around regulatory stability and reimbursement expansion timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Monkeypox Testing Market
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Blood Sugar Tester Market
Testing Services
Global Urinalysis Test Market
Testing Services
Friability Tester Market
Testing Services
Service Laboratory Market
Testing Services
Pneumococcal Testing Market
Testing Services
South Korea GMP Testing Service Market
Testing Services
Nicotine Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Global Drug Abuse Testing Market