
 Europe Network and Location Analytics Market | 2026-2036
Europe Network and Location Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Network and Location Analytics Market Analytics
The gap between premium real-time network analytics and commodity batch geocoding is broadening. HERE Global B.V. leverages its HD mapping heritage to dominate automotive-grade location services. TomTom International B.V. sustains competitive pressure through specialized fleet telematics platforms. SAP anchors enterprise demand by integrating geospatial modules into its core ERP workflows.
Europe Network and Location Analytics encompasses the processing of spatial, network topology, and movement data to derive operational intelligence, typically involving sub-meter GPS correction, graph-based routing algorithms, and real-time stream processing at the edge. The field serves industrial purposes from predictive infrastructure maintenance to dynamic supply chain reconfiguration. Cloud-based deployment is capturing the fastest expansion as telecommunications operators and retail chains abandon rigid on-premise installations. Within applications, traffic management and asset tracking are deepening their margin pools while urban planning remains comparatively mature. AI Analytics and IoT Integration are emerging as the technology layers where differentiation concentrates most intensely.
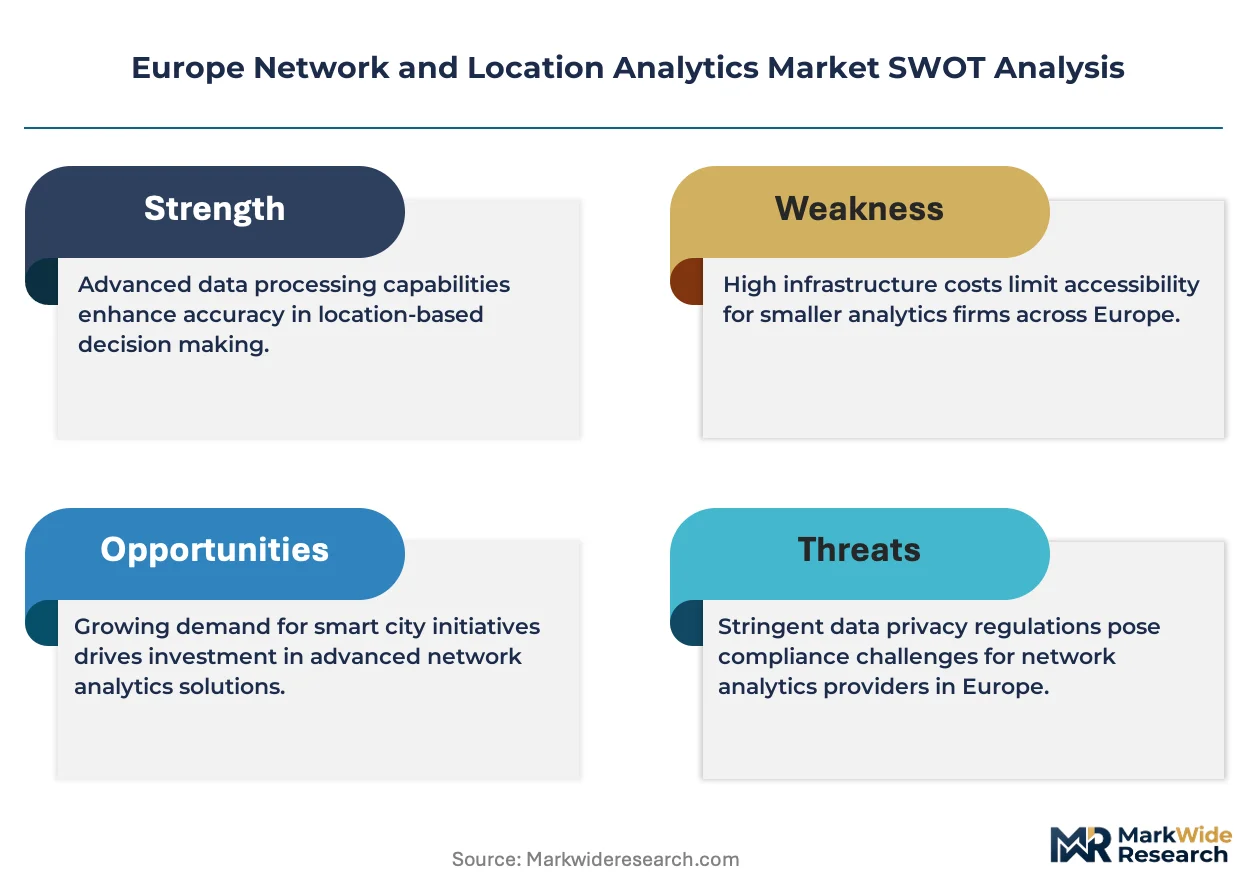
The EU AI Act, GDPR, and CE marking requirements collectively shape product architecture decisions across the European vendor landscape. EMA and national data protection authorities in France and Germany enforce strictures on cross-border geospatial data flows, compelling providers to localize processing infrastructure. Stakeholders must weigh the trade-off between centralized AI model training and federated edge architectures as regulatory scrutiny intensifies.
Market Dynamics
The EU AI Act's risk classification framework is forcing vendors to re-architect geospatial processing pipelines, splitting model training from inference to keep sensitive location data within national borders.
Growth Catalysts
- GDPR Article 17 data erasure mandates:Privacy-preserving federated learning architectures are winning municipal procurement contracts in France and Germany where citizen data protection carries legal weight.
- Automotive OEMs:HD map refresh requirements for Level 3+ autonomy are pulling real-time network analytics into production vehicle programs faster than originally projected.
- Netherlands logistics corridor:Rotterdam-Antwerp port operators are deploying edge-based fleet optimization at scale, creating reference architectures copied across North Sea shipping lanes.
Market Restraints
- GPU compute cost volatility:Cloud inference pricing for transformer-based geospatial models fluctuates with semiconductor supply, compressing margins for mid-tier analytics providers.
- Cross-border data fragmentation:French CNIL and German BfDI interpret GDPR geolocation rules divergently, forcing redundant infrastructure deployment that duplicates operational overhead.
- Legacy GIS substitution:Established ArcGIS deployments in public sector agencies resist displacement despite superior real-time capabilities from cloud-native alternatives.
Strategic Opportunities
- Polish smart city underpenetration:Warsaw and Krakow lag Western European municipal analytics adoption, opening first-mover advantage for vendors with localized edge infrastructure.
- EU Green Deal building performance mandates:Location-linked energy consumption monitoring is becoming compulsory for commercial real estate, pulling spatial analytics into facility management software stacks.
- 5G network digital twin convergence:Telecommunications operators in Spain and Italy are merging radio propagation modeling with geospatial platforms, creating integrated procurement categories.
Industry Challenges
- Geospatial-AI skill scarcity:The intersection of graph neural networks and coordinate reference systems expertise concentrates in a handful of academic programs across ETH Zurich and TU Munich.
- CE marking timeline compression:Hardware edge devices with embedded analytics must navigate Notified Body queues that extend 14-18 months, delaying product launches.
- Multi-CRS integration complexity:Municipal buyers operate across legacy national grid systems, ETRS89, and WGS84, requiring custom transformation pipelines that inflate implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Network and Location Analytics Market |
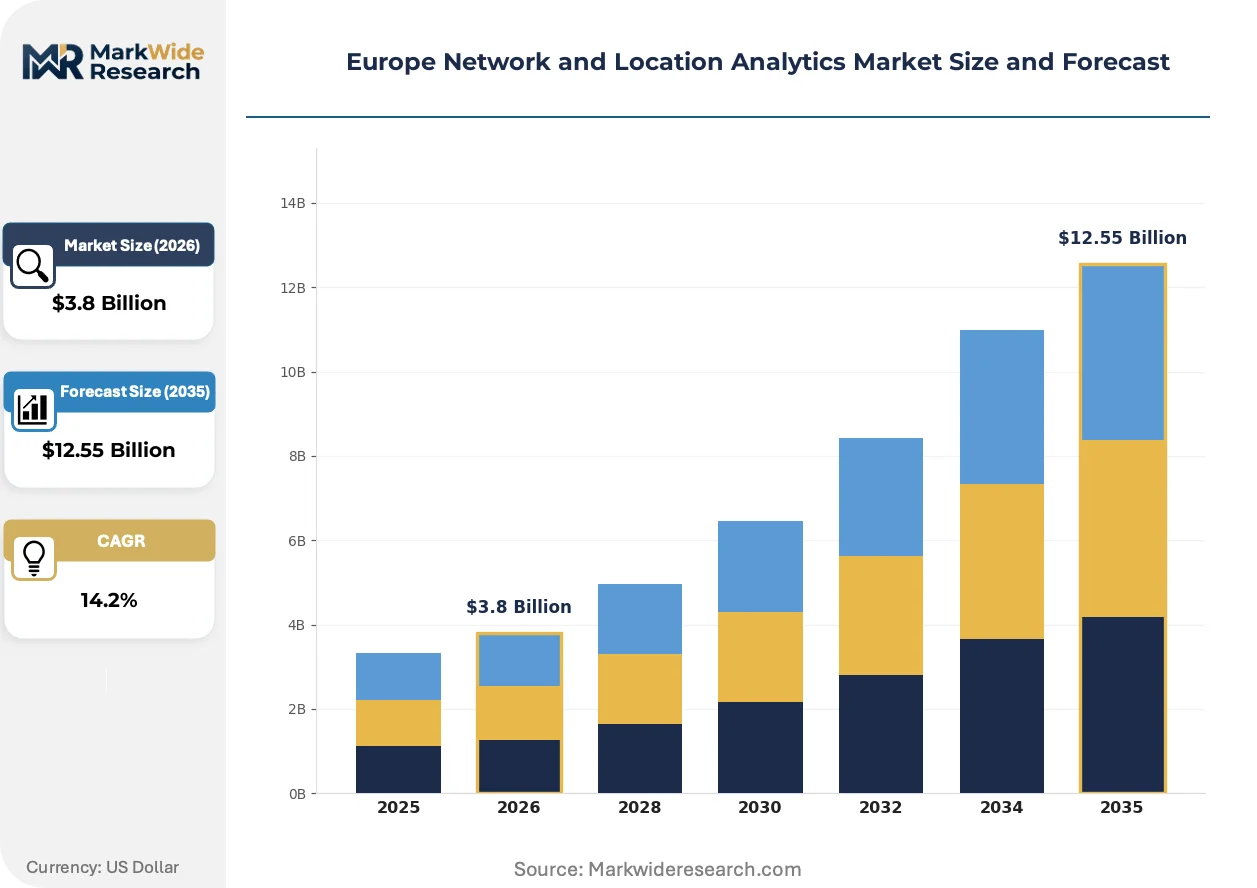
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Urban Planning, Traffic Management, Geospatial Analysis, Asset Tracking End User: Government Agencies, Retail Chains, Logistics Providers, Telecommunications Technology: AI Analytics, GIS Software, Big Data Solutions, IoT Integration |
| Companies Covered | HERE Global B.V., TomTom International B.V., SAP, Hexagon, Esri Global, Inc., Microsoft Corporation, Google LLC, IBM, Cisco Systems Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Network and Location Analytics Market Evolving Landscape
Edge-native processing architectures are displacing centralized cloud workflows as latency requirements tighten and data sovereignty rules harden across European jurisdictions.
Digital twin infrastructure is converging with real-time location streams to enable predictive maintenance of transport and utility networks. Railway operators in Switzerland and Austria are deploying these fused systems to anticipate switch failures before service disruption. The convergence is compressing vendor categories that previously separated simulation software from operational telemetry platforms.
The EU AI Act's high-risk system classification now captures automated traffic management and critical infrastructure monitoring. Vendors must maintain technical documentation, human oversight protocols, and conformity assessments that add 12-18 months to product development cycles. French smart city procurements are requiring explicit AI Act compliance certifications, filtering out smaller competitors lacking regulatory affairs capacity.
Subscription-based platform access is replacing perpetual software licenses in enterprise geospatial procurement. Dutch retail chains and German automotive suppliers now demand usage-based pricing tied to API call volumes rather than seat counts. This shift is most visible in the DACH region where procurement functions have consolidated vendor management under centralized IT category teams.
Europe Network and Location Analytics Market Segmentation
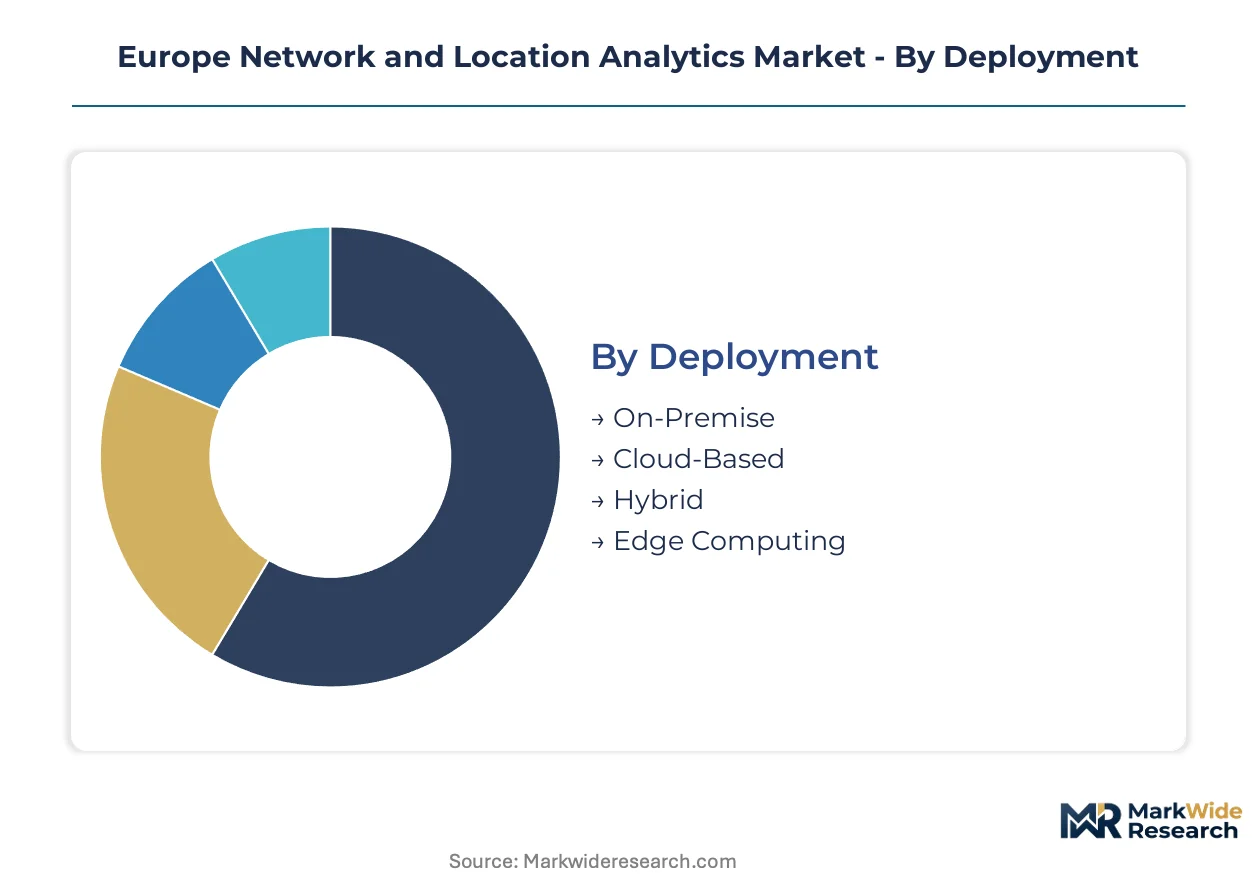
Europe's network and location analytics market fragments across four critical dimensions that determine integration architecture, procurement patterns, and margin structures. Deployment mode dictates data sovereignty compliance costs. Application focus shapes latency requirements and real-time processing investments.
Deployment:
Standalone installations dominate regulated environments while embedded architectures penetrate operational technology stacks.
- On-Premise:Dedicated hardware installations within client facilities process sensitive geospatial data under direct institutional control. German federal agencies and French CNIL-supervised municipalities mandate these configurations for citizen location databases, despite higher capital expenditure and 18-24 month refresh cycles.
- Cloud-Based:Multi-tenant SaaS platforms with API-accessible geocoding, routing, and network analytics engines. Dutch retail chains and Spanish telecommunications operators are consolidating procurement here, driven by usage-based pricing and rapid feature deployment that outpaces on-premise upgrade timelines.
- Hybrid:Split architectures keeping sensitive inference at the edge while pushing model training to centralized cloud resources. This configuration satisfies GDPR Article 44 cross-border transfer restrictions for automotive OEMs running pan-European fleet analytics.
- Edge Computing:Sub-10ms latency processing on gateway devices deployed at Rotterdam port terminals and Swiss railway switching yards. Containerized analytics modules run inference locally before transmitting aggregated telemetry upstream.
Cloud-Based leads volumes today; Edge Computing is gaining share fastest.
Application:
Functional use cases separate mature planning tools from emerging real-time operational systems with diverging margin profiles.
- Urban Planning:Long-horizon zoning and infrastructure capacity modeling using historical demographic and land-use datasets. Paris, Lyon, and Marseille municipal authorities dominate procurement, though budget cycles extend 36-48 months and resist subscription pricing transitions.
- Traffic Management:Real-time signal optimization and congestion prediction integrating 5G vehicle telemetry with HD map streams. Austrian and Swiss railway operators are deploying predictive switch maintenance systems that fuse digital twin simulation with live location feeds.
- Geospatial Analysis:Coordinate transformation, spatial querying, and visualization workflows supporting environmental monitoring and insurance risk assessment. ETRS89-WGS84 CRS conversion complexity inflates implementation costs for cross-border projects.
- Asset Tracking:Sub-meter GPS correction and indoor positioning for high-value equipment and fleet vehicles. Logistics corridors across the Netherlands and Belgium are standardizing on edge-native architectures for container yard optimization.
Urban Planning commands the largest installed base; Traffic Management shows the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, compliance burden, and integration depth with existing enterprise systems.
- Government Agencies:National mapping institutes, transport ministries, and municipal smart city departments with strict public tender requirements. French and German authorities now mandate EU AI Act conformity assessments for automated traffic systems, extending vendor qualification to 14-18 months.
- Retail Chains:Location intelligence for site selection, supply chain optimization, and customer movement analytics within store environments. DACH-region category managers have consolidated vendor relationships under centralized IT procurement functions demanding API-volume pricing.
- Logistics Providers:Fleet telematics, route optimization, and warehouse siting analytics. Rotterdam-Antwerp port operators are deploying reference architectures copied across North Sea shipping lanes.
- Telecommunications:Radio propagation modeling, network digital twins, and subscriber geolocation for service quality management. Spanish and Italian operators are merging RF engineering platforms with geospatial analytics into integrated procurement categories.
Government Agencies anchor current revenue; Logistics Providers are climbing the fastest.
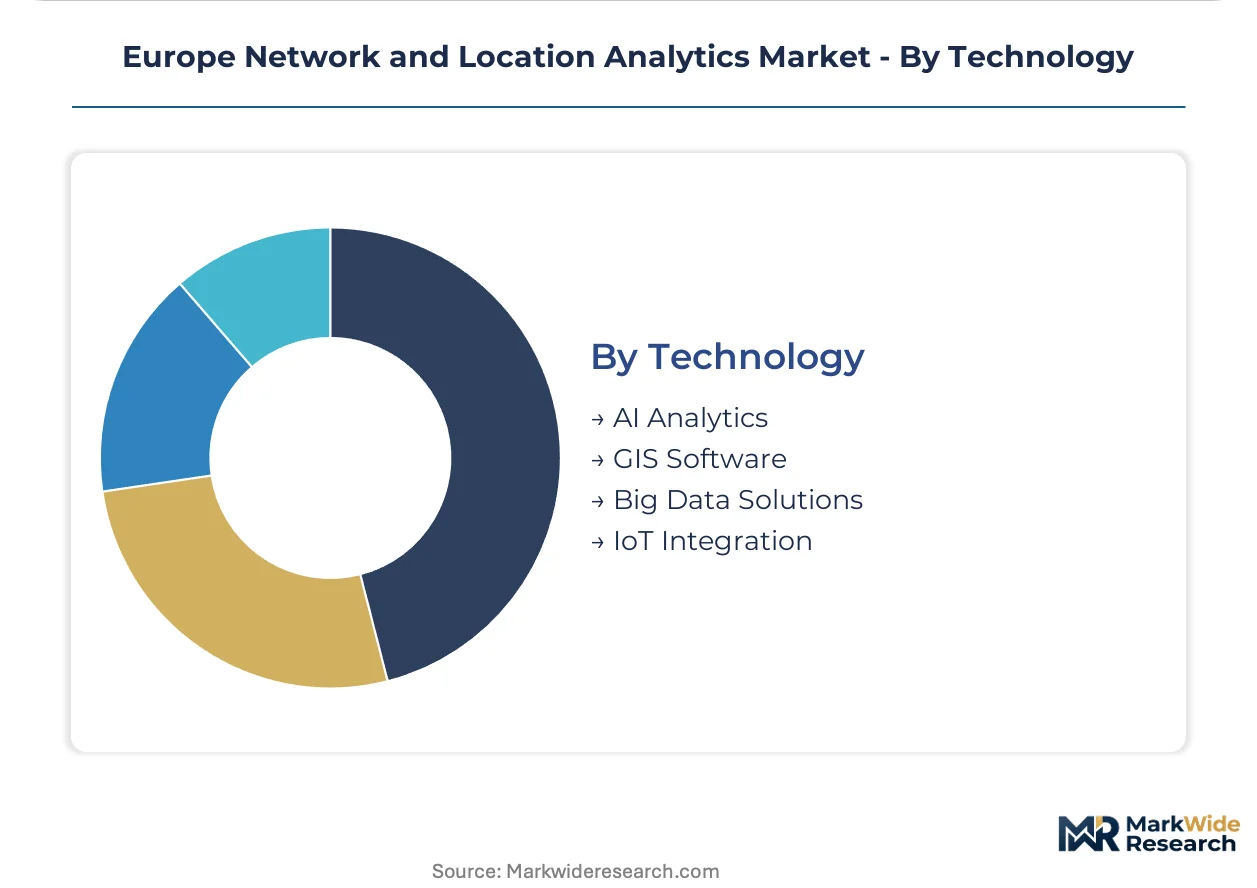
Technology:
Technology layer determines competitive differentiation, skill requirements, and vulnerability to rapid architectural shifts.
- AI Analytics:Graph neural networks and transformer-based models for predictive routing, anomaly detection, and automated feature extraction from satellite imagery. ETH Zurich and TU Munich supply scarce talent combining coordinate reference systems expertise with deep learning implementation.
- GIS Software:Traditional spatial databases, mapping engines, and cartographic visualization tools. Legacy ArcGIS deployments in European public sector agencies resist displacement despite cloud-native alternatives offering superior real-time capabilities.
- Big Data Solutions:Distributed stream processing frameworks handling petabyte-scale telemetry ingestion from connected vehicle and IoT sensor fleets. CE marking timelines for hardware edge devices compress product launch windows.
- IoT Integration:Sensor fusion protocols, device management platforms, and low-power wide-area network connectivity for distributed asset monitoring. EU Green Deal building performance mandates are pulling spatial analytics into commercial real estate facility management stacks.
GIS Software retains the largest footprint; AI Analytics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graph neural network and coordinate reference systems expertise concentrates at ETH Zurich and TU Munich, anchoring geospatial-AI talent pools that European vendors recruit aggressively.
Germany
Federal transport ministries and automotive OEMs drive demand for HD map refresh capabilities and fleet telematics. BfDI interpretations of GDPR geolocation rules mandate localized processing infrastructure for citizen location databases. Munich and Stuttgart industrial clusters host production vehicle programs pulling real-time network analytics into Level 3+ autonomy systems.
France
Paris, Lyon, and Marseille municipal authorities accelerate procurement of traffic and utility management platforms. CNIL now requires explicit EU AI Act compliance certifications for automated traffic systems in smart city tenders. Île-de-France regional operators deploy privacy-preserving federated learning architectures to satisfy Article 17 data erasure mandates.
Netherlands
Rotterdam-Antwerp port operators and logistics providers deploy edge-based fleet optimization at scale. GDPR Article 44 cross-border transfer restrictions shape hybrid architectures for pan-European fleet analytics. Randstad logistics corridors create reference architectures copied across North Sea shipping lanes.
United Kingdom
London metropolitan transport authorities and insurance risk assessors deepen geospatial analysis deployments. Post-Brexit data adequacy arrangements with the EU influence processing location decisions for cross-border telemetry streams. Southeast England technology clusters attract vendors establishing European headquarters outside single market jurisdiction.
Switzerland
Railway operators in Zurich and Bern deploy predictive switch maintenance systems fusing digital twin simulation with live location feeds. Swissmedic and federal data protection frameworks impose strictures on health-related geospatial data processing. Alpine logistics corridors demand sub-10ms latency edge processing for container yard optimization.
Europe Network and Location Analytics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European network and location analytics landscape. HERE Global B.V. and TomTom International B.V. maintain substantial mapping infrastructure investments while cloud-native entrants scale without proprietary sensor networks. Three archetypes dominate: HD mapping heritage players, enterprise ERP-integrated platform vendors, and API-first cloud analytics specialists. Consolidation pressure intensifies through strategic partnerships between telecommunications operators and geospatial platform providers, alongside vertical integration into edge hardware manufacturing.
Within the HD mapping tier, HERE Global B.V. and TomTom International B.V. occupy positions shaped by automotive-grade location service heritage. SAP anchors enterprise demand through ERP-integrated geospatial modules. Among cloud-native specialists, Microsoft Corporation and Google LLC exemplify API-volume pricing models displacing perpetual licenses in DACH-region retail procurement. Cisco Systems Inc. sits within the network infrastructure convergence archetype, merging radio propagation modeling with operational analytics for telecommunications operators in Spain and Italy.
| Leading Market Players |
|---|
| HERE Global B.V. |
| TomTom International B.V. |
| SAP |
| Hexagon |
| Esri Global, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM |
| Cisco Systems Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal building performance mandates gate access to premium-tier pricing for location analytics vendors serving commercial real estate, while simultaneously restricting qualified supply to providers with localized edge infrastructure and CE-marked hardware certifications. French and German procurement officers now bundle energy monitoring compliance into geospatial platform RFPs, compressing margins for uncertified competitors.
Pricing Analysis
The bundled-vs-unbundled service split separates compliance-heavy municipal contracts from lightweight API access for retail chains. Subscription SaaS-tiered pricing dominates, with differentiation resting on GDPR certification tier and after-sales implementation support. Cost compression in mid-tier cloud analytics is intensifying because GPU inference pricing fluctuates with semiconductor supply cycles. Logistics providers in the Netherlands exhibit highest price sensitivity due to thin freight margins, while automotive OEMs accept premium pricing for HD map refresh guarantees.
Supply Chain Analysis
Workforce availability for graph neural network implementation concentrates in Germany, Switzerland, and the Netherlands, where ETH Zurich and TU Munich anchor scarce talent pools. Hardware edge devices draw from Taiwanese semiconductor foundries and German industrial sensor manufacturers, with software modules resting on open-source geospatial libraries. Single-source vulnerability runs through specialized GPS correction chipset suppliers. Distribution feeds from direct enterprise sales teams for government agencies and hyperscaler marketplaces for cloud-native entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between France's stringent CNIL compliance costs and Poland's underpenetrated municipal procurement, where identical platform capabilities command divergent margin structures.
For Market Incumbents: Lock in automotive OEM relationships through captive HD map refresh infrastructure in Stuttgart and Munich production corridors. Deepen backward integration into edge hardware manufacturing to offset CE marking timeline compression that delays product launches by 14-18 months. SAP and HERE Global B.V. anchor positions through ERP-integrated modules that resist displacement.
For New Entrants and Emerging Players: Enter via Polish smart city verticals where Warsaw and Krakow lag Western European analytics adoption. Target traffic management applications in secondary French municipalities where AI Act compliance certifications filter out smaller competitors lacking regulatory affairs capacity. Lead with federated learning architectures that satisfy GDPR Article 17 mandates without centralized data storage.
For Investors and Strategic Acquirers: Roll-up economics work for API-first cloud analytics specialists because DACH-region procurement consolidation under centralized IT category teams favors platform breadth over point solutions. Five-to-ten year viability hinges on edge-native architecture ownership. Watch for inflection when telecommunications operators in Spain and Italy complete 5G digital twin convergence with geospatial platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Architecture Development | Federated learning modules satisfy French CNIL data erasure mandates for municipal contracts. |
| CE Marking Acceleration Program | Reduced Notified Body queues compress hardware launch timelines for edge analytics devices. |
| Telecommunications Partnership | Spanish operators merging RF propagation with geospatial platforms create integrated procurement categories. |
| Academic Talent Pipeline | ETH Zurich and TU Munich programs supply scarce graph neural network expertise. |
| Polish Market Entry | Warsaw smart city underpenetration offers first-mover advantage for localized edge infrastructure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with smart city procurement officers, automotive platform engineers, logistics fleet managers, and telecommunications network planners with secondary validation against EU AI Act implementation guidance, GDPR Article 44 cross-border transfer rulings, EMA geospatial data processing advisories, and hyperscaler capex disclosures for European cloud regions. Bottom-up segment sizing and top-down macro constraint checks triangulated volume estimates.
Segment-weighting approaches distributed value across deployment mode, application focus, end-user type, and technology layer, with particular attention to edge computing's accelerating share and AI analytics expansion trajectory. CAGRs derived from logistic diffusion modeling of autonomous vehicle program timelines and 5G network digital twin adoption curves. Forecast inputs incorporated GDPR enforcement intensity indices and EU Green Deal building mandate rollout schedules.
The model holds under stable regulatory enforcement and continued automotive OEM production commitments; deviation in GDPR interpretation divergence between French CNIL and German BfDI or GPU supply chain disruption would shift deployment mode preferences toward on-premise configurations. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Mobile Apps and Web Analytics Market
Analytics
Practice Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Global Analytics Software Market
Analytics
Japan Geospatial Analytics Market
Analytics
Learning Analytics Solution Market
Analytics
Process Analytics Market
Analytics
Europe Location Data Analytics Market
Analytics
Content Analytics Market
Analytics
Germany Geospatial Analytics Market
Analytics
Europe Predictive Analytics Market
Analytics
Cyprus ICT Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Edge Analytics Market
Analytics
Content Intelligence Market
Analytics
Global Customer Analytics Market