
 Japan Geospatial Analytics Market | 2026-2036
Japan Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Geospatial Analytics Market Insights
Enterprise-grade spatial intelligence is rotating toward higher-precision satellite imagery and real-time sensor fusion. PASCO Corporation leverages its decades of aerial surveying heritage to dominate Japan's remote sensing services. Zenrin Co., Ltd. anchors the market through its exhaustive domestic map database and location intelligence APIs. NTT DATA Corporation extends its cloud infrastructure dominance into geospatial platform delivery for government clients.
Geospatial analytics encompasses the computational processing of location-referenced data through coordinate-based algorithms, spatial statistics, and remote sensing interpretation to generate actionable intelligence for asset positioning, risk visualization, and resource optimization. Cloud Computing deployment now leads technology adoption as Japanese enterprises migrate from on-premise GIS installations to elastic, API-driven spatial services. Machine Learning integration represents the fastest-expanding capability layer, automating feature extraction from satellite and drone imagery for infrastructure inspection. Environmental Management applications command deepening public investment as climate adaptation mandates intensify.
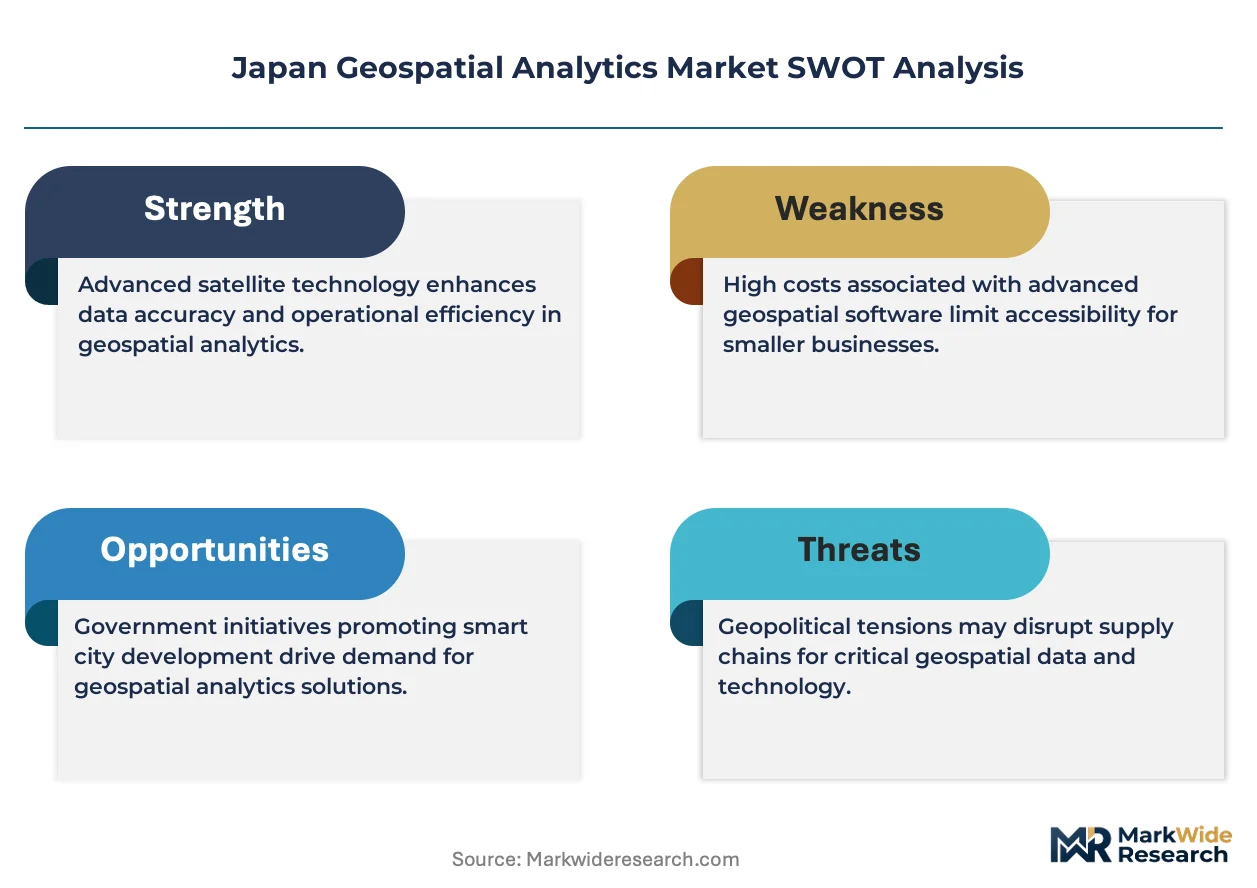
METI's digital infrastructure directives, the Cabinet Office's disaster management protocols, and JIS standards for geographic information interoperability collectively shape vendor certification requirements and procurement eligibility. These frameworks mandate open data formats and cross-agency platform compatibility, compressing margins for proprietary solution providers while rewarding modular, standards-compliant architectures. Stakeholders must weigh the trade-off between specialized sensor hardware investments and software-centric platform scalability as public-sector tender criteria evolve.
Market Dynamics
METI's Society 5.0 mandates are compressing procurement cycles for cloud-native spatial platforms, forcing legacy GIS vendors to modularize architectures or forfeit government eligibility. This regulatory pressure cascades through prefectural disaster management offices and metropolitan smart city pilots alike.
Growth Catalysts
- Climate Adaptation Mandates:Japan's Cabinet Office disaster resilience protocols require real-time flood and seismic risk visualization across all 47 prefectures, driving sensor network procurement.
- Tokyo Metropolitan Smart City Pilots:Infrastructure monitoring convergence in the capital corridor creates concentrated demand for integrated aerial and ground-based analytics.
- Cloud Migration:Elastic API-driven spatial services are replacing on-premise GIS installations as enterprises prioritize interoperability over proprietary lock-in.
Market Restraints
- Specialized Hardware Costs:High-resolution satellite imagery and LiDAR sensor procurement strains municipal budgets, particularly in rural prefectures outside Tokyo-Osaka corridors.
- Vendor Concentration:Remote sensing capabilities cluster among established aerial surveyors with decades of flight operation heritage, limiting new entrant access.
- JIS Standards Friction:Geographic information interoperability mandates compress margins for proprietary solution providers unaccustomed to open data format requirements.
Strategic Opportunities
- Kansai Region Underpenetration:Osaka-Kobe industrial corridor lags Tokyo in real-time infrastructure analytics deployment, creating whitespace for platform expansion.
- Machine Learning Feature Extraction:Automated drone and satellite imagery interpretation for bridge and tunnel inspection remains nascent, with significant efficiency gains available.
- Cross-Agency Platform Convergence:METI's open data directives reward modular architectures capable of serving METI, Cabinet Office, and prefectural clients through single deployments.
Industry Challenges
- Geospatial Data Science Talent Scarcity:Shortage of practitioners combining remote sensing expertise with cloud engineering skills constrains platform development velocity.
- Legacy System Integration Complexity:Municipal clients operate decades-old GIS installations requiring costly middleware development for cloud platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Geospatial Analytics Market |
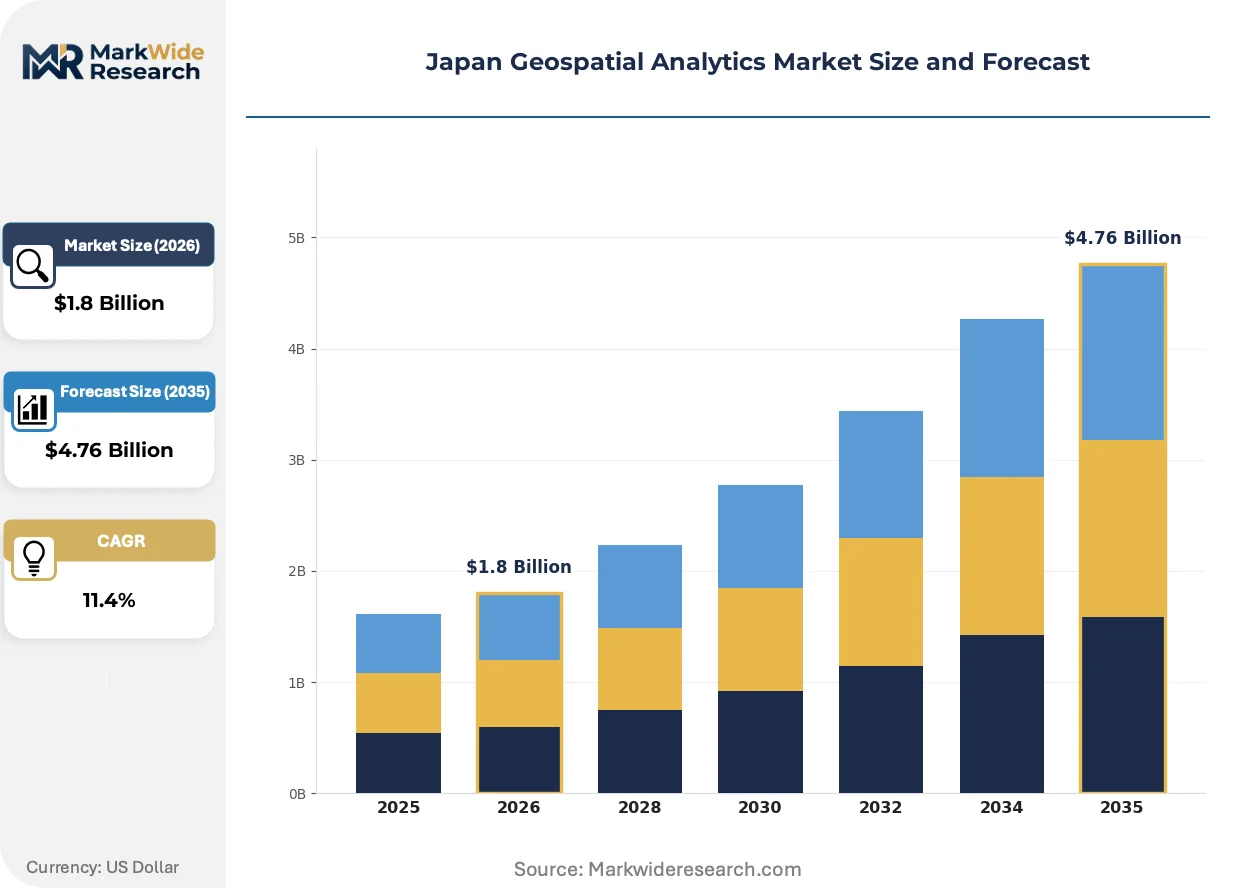
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GIS Software, Remote Sensing, Data Management, Spatial Analysis Technology: Cloud Computing, Big Data, Machine Learning, IoT End User: Government Agencies, Transportation, Agriculture, Environmental Management Application: Urban Planning, Disaster Management, Asset Tracking, Market Analysis |
| Companies Covered | ESRI Japan Corp., PASCO Corporation, NTT DATA Corporation, Hexagon AB, Trimble Inc., Zenrin Co., Ltd., Hitachi, Ltd., NEC Corporation, Maxar Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Geospatial Analytics Market Trends and Innovations
Real-time sensor fusion and automated feature extraction are redefining competitive differentiation, compressing the gap between raw imagery capture and actionable intelligence delivery. Vendors race to embed machine learning pipelines directly into cloud-native spatial platforms.
Real-time sensor fusion architectures are supplanting batch-processed imagery workflows in infrastructure monitoring applications. Railway operators and highway authorities in the Tokyo metropolitan corridor now demand sub-hour latency between drone capture and defect identification. This compression of analytics cycles is collapsing traditional service boundaries between aerial surveyors and software platform providers.
METI's digital infrastructure directives now mandate open data formats and cross-agency platform compatibility for all central government procurement. This regulatory architecture favors modular, standards-compliant vendors while penalizing proprietary solution providers dependent on format lock-in. Prefectural disaster management offices are accelerating compliance timelines to maintain central funding eligibility.
Subscription-based platform access is displacing perpetual license purchases across municipal and enterprise buyers. Kansai region industrial clients now prioritize operational expenditure models that bundle sensor hardware, cloud processing, and analytics outputs into unified service tiers. This procurement evolution favors vertically integrated providers capable of controlling capture-to-insight pipelines rather than software-only specialists.
Japan Geospatial Analytics Market Segmentation
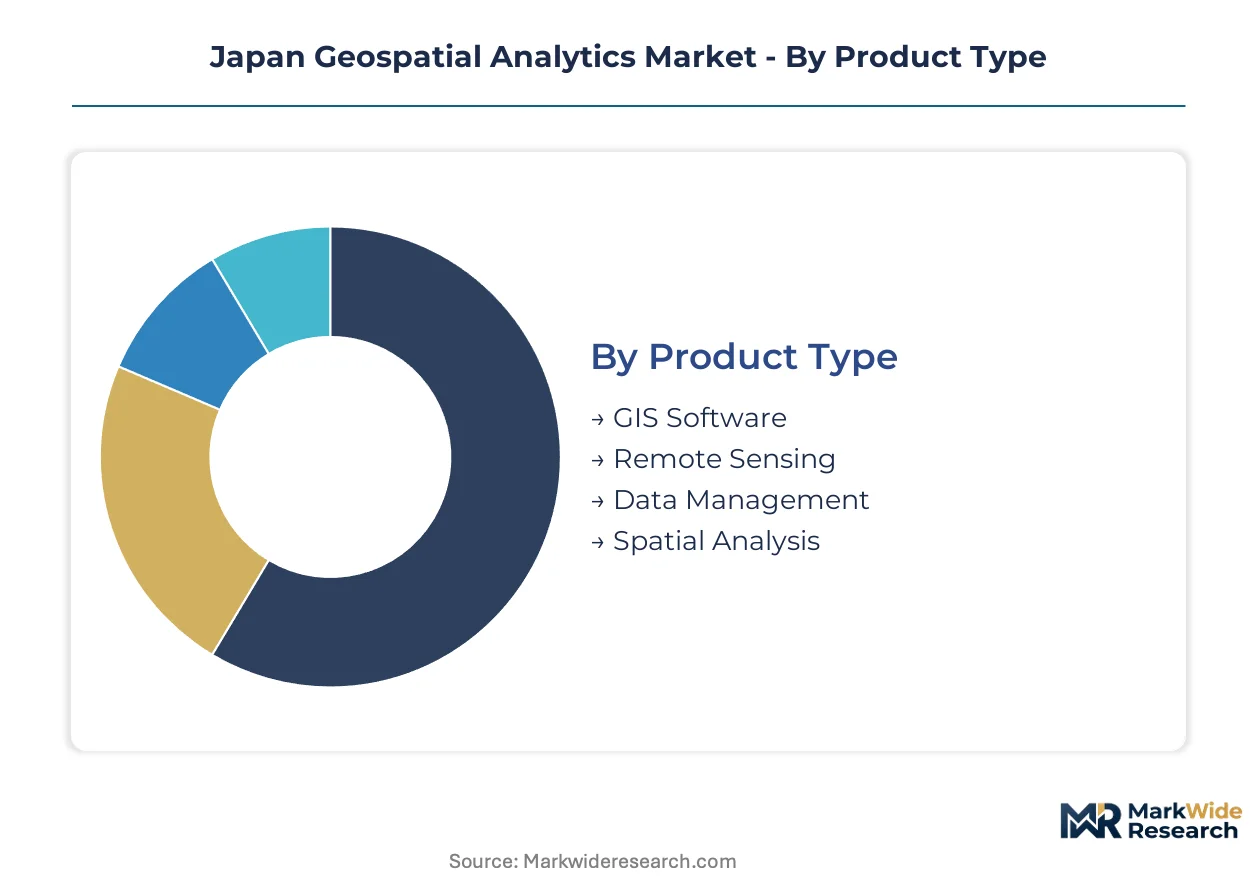
Segmentation in Japan's geospatial analytics market reveals how METI's procurement directives and prefectural disaster mandates reshape vendor priorities across software, infrastructure, and service layers. Technology choices and end-user requirements diverge sharply between Tokyo's metropolitan corridor and rural prefectures.
Product Type:
Remote Sensing faces acute substitution pressure from drone-captured photogrammetry and satellite constellations offering comparable resolution at lower operational cost, compressing margins for legacy aerial surveyors.
- Remote Sensing:Aerial and satellite imagery acquisition systems process electromagnetic signatures across spectral bands to generate terrain models and land-use classifications. Demand concentrates in Tokyo's infrastructure monitoring contracts where PASCO Corporation's flight heritage secures recurring municipal engagements despite sensor commoditization.
- GIS Software:Spatial data visualization and cartographic production platforms enable coordinate-based asset mapping and network topology analysis. Prefectural governments in Osaka-Kobe industrial corridors prioritize cloud-native deployments over perpetual licenses as METI funding eligibility requires open API architectures.
- Data Management:Geodatabase administration and metadata standardization systems ensure JIS-compliant interoperability across agency boundaries.
- Spatial Analysis:Geostatistical modeling and proximity algorithms support site selection and risk surface generation for climate adaptation planning.
GIS Software retains volume leadership; Remote Sensing holds the steepest expansion curve as satellite revisit frequencies improve.
Technology:
Cost tier stratification separates capital-intensive edge deployments from subscription-based cloud consumption, with municipal buyers gravitating toward operational expenditure models that bundle processing and storage.
- Cloud Computing:Elastic infrastructure delivers API-driven spatial services with metered compute and storage scaling. NTT DATA Corporation dominates government platform delivery as prefectural clients abandon on-premise server farms for METI-certified cloud environments.
- Machine Learning:Convolutional neural networks automate feature extraction from imagery, collapsing defect detection timelines from days to hours. Railway operators in the Tokyo metropolitan corridor now mandate sub-hour latency between drone capture and crack identification in bridge inspection workflows.
- Big Data:Distributed processing frameworks handle petabyte-scale sensor archives for historical trend analysis and predictive modeling.
- IoT:Ground-based sensor networks stream real-time telemetry on structural strain, seismic activity, and hydrological conditions to centralized platforms.
Cloud Computing commands the largest procurement budgets; Machine Learning is climbing the fastest as infrastructure authorities automate visual inspection protocols.
End User:
Customer type determines pricing tolerance and compliance rigor, with central government tenders imposing stricter open-data mandates than private sector buyers.
- Government Agencies:METI, Cabinet Office, and prefectural disaster management offices procure integrated spatial platforms for risk visualization and emergency response coordination. The Cabinet Office's climate adaptation mandates require real-time flood modeling across all 47 prefectures, driving sensor network standardization.
- Transportation:Railway and highway authorities deploy aerial analytics for corridor monitoring and maintenance scheduling. JR East and Central Nippon Expressway in the Tokyo corridor lead adoption of automated defect detection from drone imagery.
- Agriculture:Precision farming operations utilize multispectral crop health monitoring and yield prediction models.
- Environmental Management:Climate adaptation agencies track coastal erosion, forest cover change, and watershed dynamics for policy formulation.
Government Agencies retain volume leadership; Transportation holds the steepest expansion curve as infrastructure monitoring converges with smart city pilots.
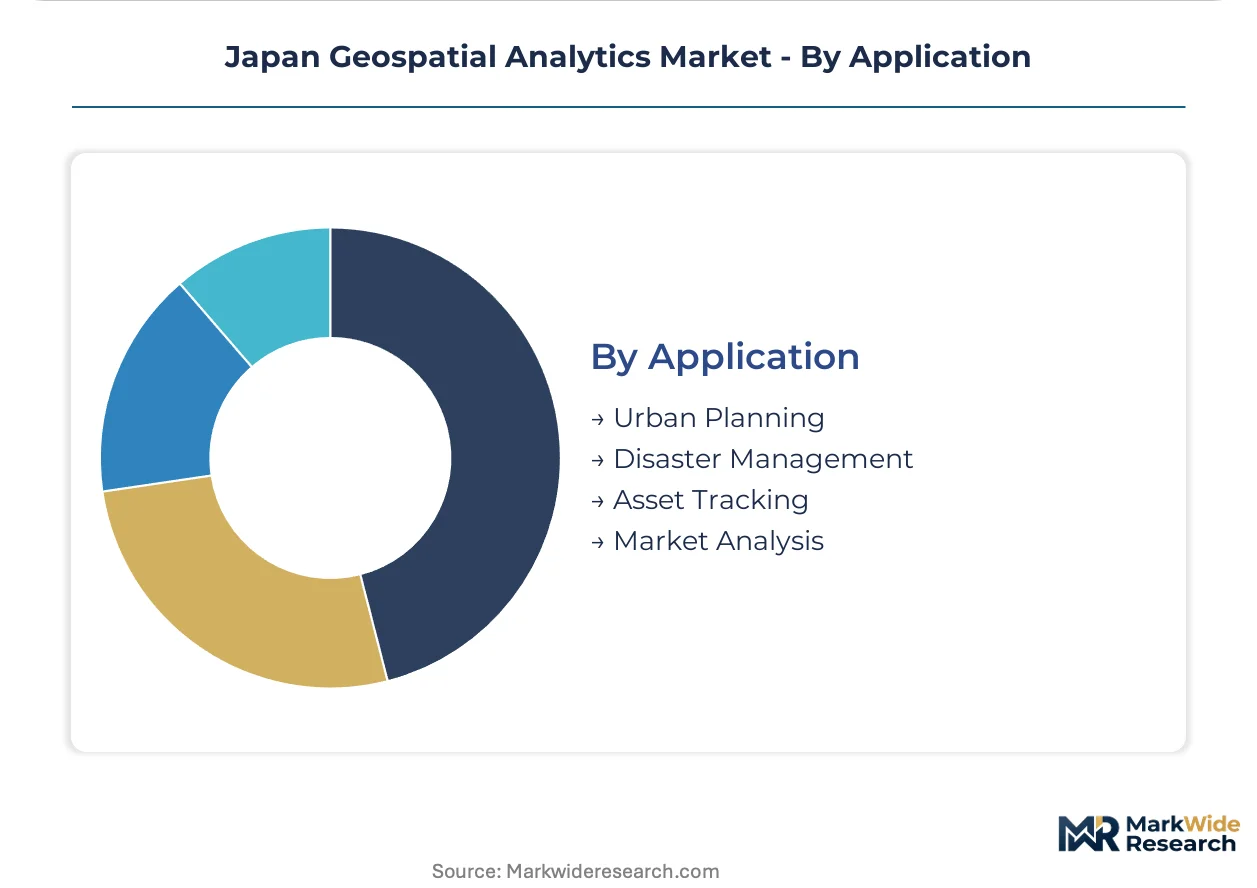
Application:
Geographic concentration in the Kanto region creates demand density for urban-focused applications, while disaster management requirements span the archipelago uniformly.
- Urban Planning:Zoning analysis, population density modeling, and infrastructure capacity planning support metropolitan development authorities. Tokyo's smart city pilots integrate aerial survey data with underground utility mapping for 3D city modeling.
- Disaster Management:Seismic risk surface generation, flood inundation mapping, and evacuation route optimization serve Cabinet Office protocols. Real-time sensor fusion for earthquake early warning and tsunami propagation modeling commands priority funding across all prefectures.
- Asset Tracking:Fleet management and logistics optimization utilize real-time location intelligence for supply chain visibility.
- Market Analysis:Retail site selection and demographic profiling leverage spatial statistics for revenue forecasting.
Disaster Management retains volume leadership; Urban Planning holds the steepest expansion curve as Tokyo's metropolitan corridor densifies sensor deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports geospatial analytics services and platform expertise across East Asian infrastructure corridors, with domestic demand concentrated in metropolitan smart city deployments and prefectural disaster resilience networks.
Kanto/Tokyo
Tokyo's metropolitan corridor drives concentrated demand for real-time infrastructure monitoring and 3D city modeling. METI's Society 5.0 directives mandate cloud-native spatial platforms for central government procurement. Railway operators and highway authorities in Greater Tokyo deploy automated defect detection from drone imagery with sub-hour latency requirements.
Kansai/Osaka
Osaka-Kobe industrial corridor exhibits underpenetration in real-time analytics relative to Tokyo, creating expansion whitespace for platform vendors. Prefectural governments prioritize operational expenditure models bundling sensor hardware and cloud processing. Manufacturing logistics clusters in Osaka Bay area adopt fleet management and supply chain visibility solutions.
Chubu/Nagoya
Nagoya's automotive and aerospace manufacturing base generates demand for precision asset tracking and facility optimization. Central Japan's prefectural disaster management offices accelerate compliance with Cabinet Office climate adaptation protocols. Toyota-led industrial consortiums pilot integrated aerial and ground-based analytics for supply chain resilience.
Kyushu
Fukuoka's emerging tech hub attracts geospatial data science talent scarce in Tokyo-Osaka corridors. Regional disaster resilience mandates require seismic risk visualization and tsunami propagation modeling across coastal prefectures. Semiconductor fabrication clusters in Kumamoto and Kagoshima deploy environmental monitoring for facility siting decisions.
Tohoku
Post-2011 reconstruction investments sustain demand for flood inundation mapping and evacuation route optimization. Rural prefectures outside metropolitan corridors face budget constraints for high-resolution sensor procurement. Sendai's reconstruction authority serves as a testbed for cross-agency platform convergence under METI open data directives.
Japan Geospatial Analytics Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and remote sensing heritage dimensions, producing a tiered structure where scale-driven platform providers face focused aerial surveyors. The vendor base separates into three archetypes: vertically integrated flight operators with decades of survey heritage, cloud-native software platforms backed by telecommunications infrastructure, and modular specialists delivering JIS-compliant interoperability layers. Dominant competitive moves include modular architecture refactoring to meet METI certification requirements and subscription-based service tiering to capture municipal operational expenditure budgets.
Within the heritage flight operator tier, PASCO Corporation and Zenrin Co., Ltd. exemplify distinct positioning strategies—PASCO anchoring aerial survey services while Zenrin dominates domestic map database and location intelligence APIs. NTT DATA Corporation occupies a position representing telecommunications-backed cloud platform delivery, extending infrastructure dominance into government spatial services. These three entities collectively illustrate how vendor concentration in remote sensing capabilities limits new entrant access while rewarding modular, standards-compliant architectures under evolving procurement criteria.
| Leading Market Players |
|---|
| ESRI Japan Corp. |
| PASCO Corporation |
| NTT DATA Corporation |
| Hexagon AB |
| Trimble Inc. |
| Zenrin Co., Ltd. |
| Hitachi, Ltd. |
| NEC Corporation |
| Maxar Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term subscription contracts with bundled sensor hardware lock in municipal buyers to predictable operational expenditure while securing vendor access to prefectural disaster resilience budgets. METI's Society 5.0 procurement mandates favor these arrangements over perpetual licenses, compressing upfront capital requirements into metered service tiers that align with Japan's public-sector fiscal constraints.
Pricing Analysis
The pricing gap between cloud-native API platforms and legacy on-premise GIS installations widens as municipal buyers migrate toward subscription models. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade machine learning pipelines from basic data visualization tools. Cost compression in the standard tier intensifies because satellite imagery commoditization erodes aerial surveyor margins. Prefectural governments outside Tokyo-Osaka corridors exhibit highest price sensitivity; central government agencies tolerate premium tiers for sub-hour latency guarantees.
Supply Chain Analysis
Strait of Malacca satellite ground station access underwrites Japan's real-time imagery pipeline, creating vulnerability to regional geopolitical friction. Hardware sourcing draws from Taiwan for semiconductor components, the United States for hyperspectral sensors, and domestic precision optics manufacturers. Single-source vulnerability concentrates in high-resolution LiDAR arrays where German and Australian suppliers dominate. Distribution runs through NTT DATA's cloud infrastructure and PASCO's flight operations network to municipal procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source geospatial platforms and international satellite constellations threaten incumbent positioning by eroding proprietary data format lock-in. Incumbents must defend substitution through architectural modularity and JIS certification depth.
For Market Incumbents: Consolidate aerial survey heritage with cloud platform delivery to maintain government eligibility under METI's open data directives. Deepen backward integration into drone sensor manufacturing to capture Kansai region whitespace before specialized hardware commoditization accelerates. Threat from international platform entrants demands faster subscription tiering than legacy perpetual license operations permit. For New Entrants and Emerging Players: Differentiate on machine learning feature extraction velocity for infrastructure inspection workflows where railway operators demand sub-hour defect identification. Target Osaka-Kobe industrial corridor logistics clusters with fleet management solutions bundled into operational expenditure contracts. Go-to-market through prefectural smart city pilots outside Tokyo's saturated metropolitan corridor. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated flight operators with JIS-certified cloud architectures. Long-term viability rests on controlling capture-to-insight pipelines rather than software-only specialization. Watch for METI procurement timeline acceleration as inflection signal indicating vendor eligibility compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | NTT DATA's cloud infrastructure absorbs modular geospatial APIs to serve METI's cross-agency mandates. |
| Acquisition of Specialist Firm | Machine learning boutiques automate defect detection for JR East's bridge inspection workflows. |
| Geographic Expansion | Osaka-Kobe corridor logistics clusters adopt real-time fleet analytics lagging Tokyo deployment. |
| Strategic Partnership | Prefectural governments bundle sensor hardware and cloud processing into unified service tiers. |
| Product Launch | Subscription-based platform access displaces perpetual licenses across municipal procurement offices. |
Research Methodology
A standing panel of prefectural disaster management officers, METI digital infrastructure leads, railway maintenance directors, and cloud platform engineers provided ongoing calibration across the research window. Primary interviews combined with secondary validation from JIS standards documentation, Cabinet Office climate adaptation protocols, METI Society 5.0 procurement guidelines, and municipal tender databases. Bottom-up segment modeling triangulated against top-down macroeconomic indicators for the Japanese digital infrastructure sector.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures, satellite operator revenue filings, and aerial surveyor contract announcements. The analytical framework modeled deployment model, organization size, vertical application, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from segment-level unit economics and technology substitution curves, with machine learning pipeline adoption rates and cloud migration velocity serving as primary forecast inputs.
Forecasts assume regulatory continuity in METI digital infrastructure directives and Cabinet Office disaster resilience protocols; material policy shifts would require re-modeling. Satellite imagery commoditization timelines and municipal budget compression scenarios present specific revision risks. Practitioners should keep alternative scenarios live as JIS interoperability mandates and international platform competition evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Italy ICT Market
Analytics
Patent Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Global People and HR Analytics Software Market
Analytics
Big Data Analytics in Retail Market
Analytics
Sales Intelligence Market
Analytics
CSP Network Analytics Market
Analytics
Global Data Analysis Software Market
Analytics
Middle East Geospatial Analytics Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Embedded Analytics Software Market
Analytics
Content Analytics and Discovery Software Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
United States Geospatial Analytics Market
Analytics
Customer Journey Analytics Market