
 Mobile Apps and Web Analytics Market | 2026-2036
Mobile Apps and Web Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Apps and Web Analytics Market Outlook
Real-time event streaming architecture is tilting the technology stack toward edge-first data collection and serverless processing pipelines. Google LLC leverages its cloud-native infrastructure to dominate real-time analytics ingestion at scale. Microsoft Corporation anchors enterprise demand through deep Azure integration and cross-suite data connectivity. Adobe, Inc. differentiates via creative-cloud-adjacent behavioral analytics that tie content performance to conversion outcomes.
Mobile apps and web analytics encompass software systems that capture, process, and visualize user interaction data across digital touchpoints, typically processing billions of events per day through distributed stream-processing frameworks like Apache Kafka and Flink, with primary commercial purpose being the optimization of user acquisition cost, retention rates, and lifetime value for digital businesses. Cloud-based deployment models lead in new adoption due to elastic scaling and reduced infrastructure overhead, while predictive analytics segments command attention from enterprises seeking churn reduction and revenue forecasting capabilities. SaaS delivery within the deployment model category is accelerating fastest among mid-market buyers who prioritize rapid implementation over customization depth.
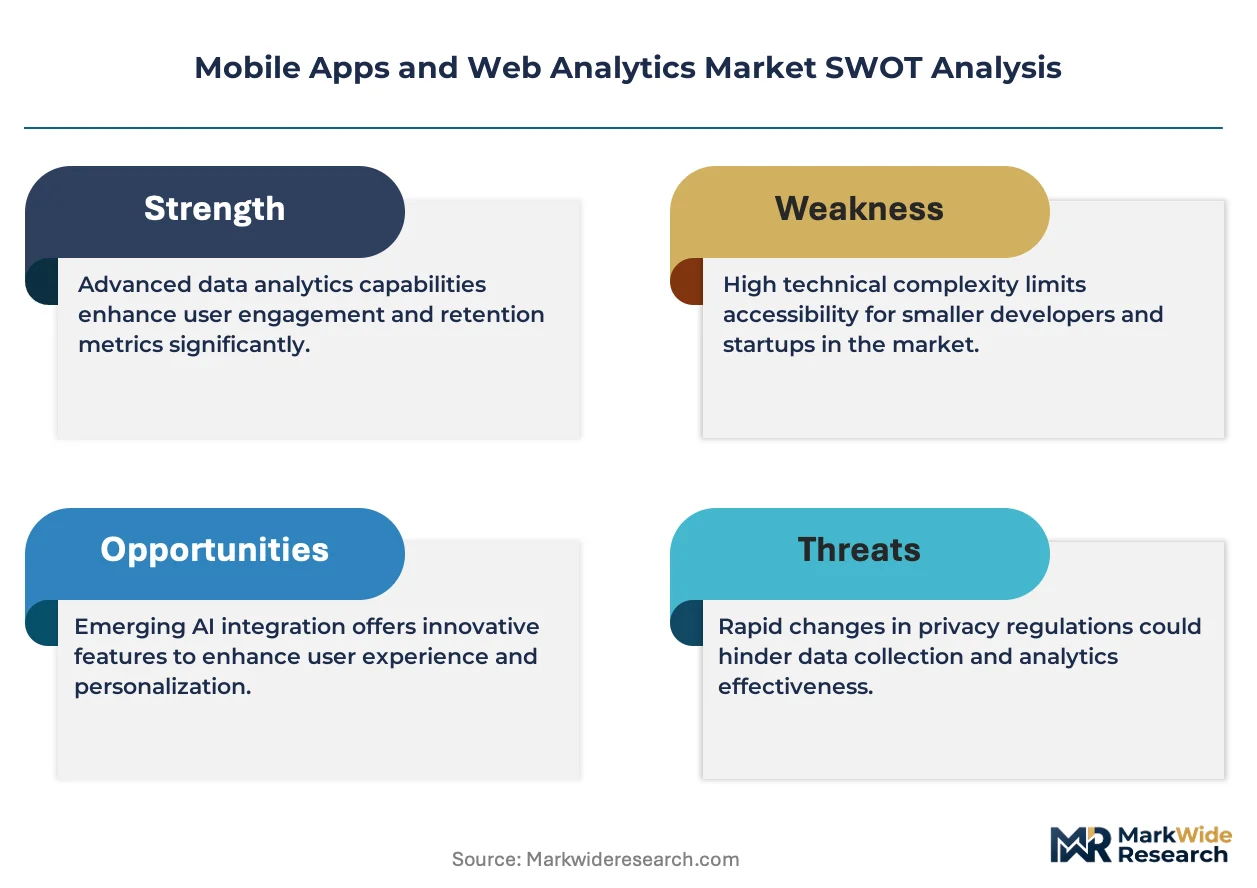
The EU AI Act and GDPR impose strict constraints on automated profiling and cross-border data transfers, forcing vendors to architect region-specific data residency and consent-management layers into their platforms. In the United States, the FTC's evolving stance on dark patterns and deceptive data practices shapes how behavioral analytics tools may lawfully nudge user decisions. Stakeholders must weigh regulatory fragmentation against the operational cost of maintaining compliant, geographically segmented analytics stacks.
Market Dynamics
Real-time event streaming infrastructure is compressing data pipelines from edge ingestion to actionable insight, forcing vendors to rearchitect around serverless processing and sub-second latency guarantees as the baseline competitive threshold.
Growth Catalysts
- EU AI Act compliance mandates:Automated profiling restrictions are accelerating investment in consent-management platforms and explainable AI layers within analytics stacks, creating upgrade cycles across European enterprise deployments.
- E-commerce conversion optimization:Online retailers processing billions of daily events demand granular funnel analysis and attribution modeling, pulling advanced behavioral analytics into standard operational tooling.
- Edge computing proliferation:Distributed stream-processing frameworks like Apache Kafka and Flink enable millisecond-latency personalization, collapsing the cost barrier for real-time decisioning previously reserved for hyperscalers.
Market Restraints
- Cross-border data transfer friction:GDPR's Schrems II enforcement and divergent national implementations fragment cloud architectures, forcing redundant regional infrastructure that inflates operational overhead.
- Specialized talent scarcity:Shortage of engineers fluent in distributed systems, privacy engineering, and statistical modeling constrains implementation velocity for mid-market buyers.
- Consent fatigue degradation:Users rejecting tracking prompts at rising rates erodes data completeness, degrading model accuracy and compressing addressable audience pools for behavioral targeting.
Strategic Opportunities
- India's digital acceleration:Rapid smartphone penetration and UPI-driven e-commerce growth create greenfield demand for mobile-first analytics among domestic startups and multinational expansions.
- Predictive churn reduction:Machine learning models forecasting user lifetime value and subscription cancellations open premium pricing tiers for vertical SaaS vendors serving subscription economy players.
- First-party data consolidation:Cookie deprecation and identifier restrictions position customer data platforms with native analytics as essential infrastructure, rewarding early movers with platform stickiness.
Industry Challenges
- Legacy system integration complexity:Enterprises with decades of fragmented data warehouses struggle to unify schemas and governance models, extending implementation timelines and inflating professional services dependency.
- Model explainability requirements:Regulatory and internal audit demands for interpretable algorithmic decisions strain engineering teams, forcing tradeoffs between predictive power and transparency.
- Real-time infrastructure capex intensity:Sub-second latency guarantees require specialized hardware, dedicated fiber, and multi-region redundancy that challenge unit economics outside high-value use cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Apps and Web Analytics Market |
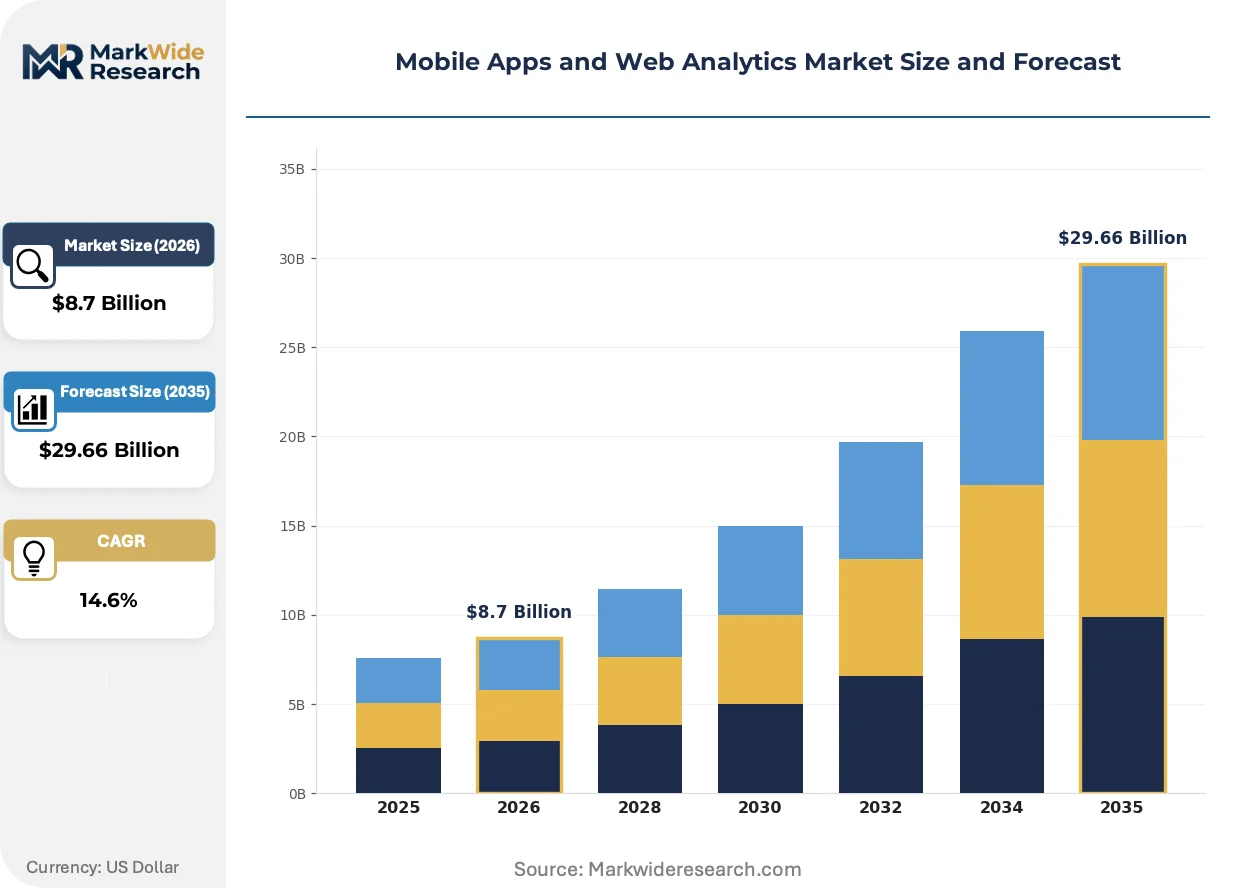
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Gaming, E-commerce, Social Media, News Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS User Segment: Business Users, Individual Consumers, Developers, Enterprises Analytics Type: Real-Time Analytics, Predictive Analytics, A/B Testing, User Behavior |
| Companies Covered | Google LLC, Microsoft Corporation, Adobe, Inc., IBM Corporation, Oracle Corporation, SAP SE, Amazon Web Services, Inc., Teradata Corporation, Amplitude, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Apps and Web Analytics Market Strategic Shifts
Privacy-preserving computation and federated learning architectures are redrawing competitive boundaries, enabling analytics vendors to deliver insights without centralizing sensitive raw data. Three developments merit particular attention.
Edge-first data collection architectures are collapsing the traditional boundary between device-side processing and cloud analytics. Mobile SDKs now execute feature extraction, anomaly detection, and model inference locally, transmitting only aggregated embeddings rather than raw event streams. E-commerce applications in Germany and the United States adopt these patterns most aggressively, driven by GDPR consent constraints and bandwidth cost optimization in emerging markets.
The EU AI Act's risk-based classification system imposes mandatory human oversight and documentation requirements on high-risk automated decisioning systems. Analytics platforms serving credit, employment, or insurance verticals must embed audit trails, bias testing, and override mechanisms directly into their product workflows. Vendors are responding by pre-certifying modules against anticipated enforcement standards, converting compliance burden into competitive differentiation.
Buyer procurement patterns are fragmenting across specialized point solutions and consolidated enterprise suites. Mid-market digital natives prioritize best-of-breed tools with rapid API-based integration, while regulated incumbents in financial services and healthcare demand unified governance layers that only integrated platforms provide. This bifurcation is most visible in the United States, where FTC scrutiny of dark patterns simultaneously increases demand for behavioral analytics and constrains how vendors may lawfully nudge user decisions.
Mobile Apps and Web Analytics Market Segmentation
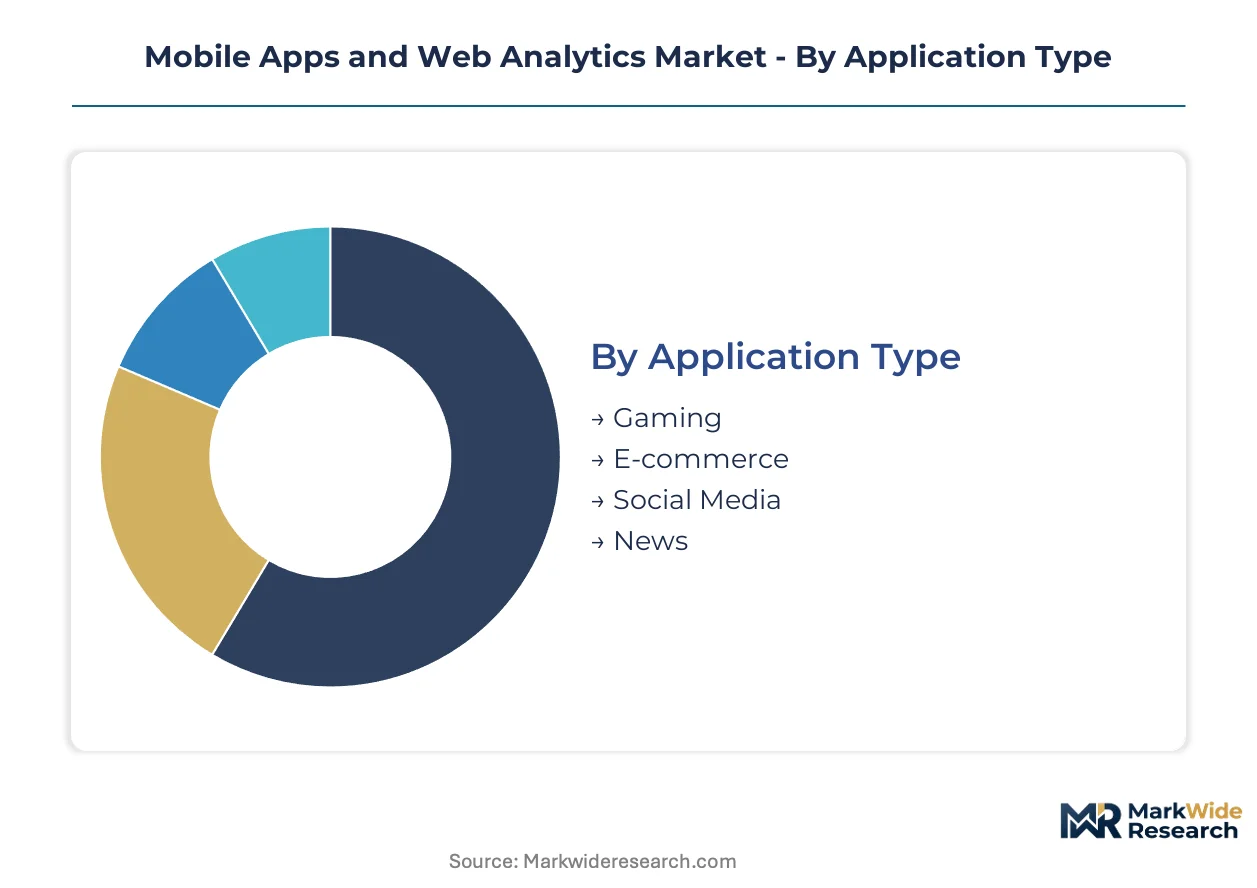
Granular segmentation reveals divergent technology requirements across use cases. Gaming platforms demand sub-millisecond event ingestion, while regulated enterprises prioritize audit-ready governance layers. Deployment preferences split sharply between cloud-native startups and hybrid-locked financial institutions.
Application Type:
After-sales service intensity varies dramatically across application categories, with gaming and e-commerce platforms requiring 24/7 incident response for revenue-critical analytics pipelines.
- Gaming:Real-time telemetry systems process 10,000+ events per second per title, tracking player progression and monetization triggers. Demand concentrates in the United States and South Korea, where live-service game economics depend on instantaneous churn prediction and dynamic difficulty adjustment.
- E-commerce:Funnel visualization and attribution modeling dominate feature requirements, with cart abandonment recovery driving ROI calculations. German retailers under GDPR constraints invest heavily in first-party data collection infrastructure, while Indian marketplaces prioritize low-bandwidth SDK optimization for tier-2 and tier-3 city penetration.
- Social Media:Engagement metric dashboards and viral coefficient tracking serve content recommendation algorithms.
- News:Paywall conversion analytics and subscriber lifetime value modeling support subscription journalism business models.
E-commerce holds the largest share; momentum sits with gaming as live-service monetization deepens.
Deployment Model:
Cost tier stratification separates hyperscaler-friendly cloud deployments from compliance-driven on-premise installations, with hybrid architectures capturing mid-market buyers seeking staged migration paths.
- Cloud-Based:Elastic auto-scaling and pay-per-event pricing eliminate capital expenditure for seasonal traffic spikes. Indian SaaS startups and Southeast Asian e-commerce platforms adopt this model fastest, leveraging AWS and Google Cloud regions in Mumbai and Singapore for data residency compliance.
- SaaS:Pre-configured dashboards and API-first integrations reduce time-to-insight to under 48 hours for standard implementations. Mid-market digital agencies in the United States and United Kingdom favor this deployment for client reporting automation, though GDPR data processing agreements now extend procurement cycles by 6-8 weeks.
- On-Premise:Air-gapped installations serve defense contractors and classified government systems with strict network isolation mandates.
- Hybrid:Edge preprocessing with cloud aggregation balances latency and cost for IoT-heavy retail environments.
Cloud-Based commands current revenue concentration; SaaS is expanding most quickly among budget-constrained buyers.
User Segment:
Customer type determines contract structure complexity, with enterprises demanding custom SLAs and dedicated support tiers unavailable to individual developers.
- Enterprises:Multi-tenant governance, role-based access control, and SOC 2 Type II certification requirements dominate procurement checklists. Financial services firms in Germany and healthcare systems in the United States drive demand for HIPAA and GDPR-compliant audit trails with 7-year retention guarantees.
- Developers:Free-tier SDKs with generous event quotas and extensive documentation lower adoption barriers. Open-source community adoption in India and Brazil accelerates through GitHub-integrated onboarding flows and local language technical support.
- Business Users:Self-service visualization tools with drag-and-drop segment builders serve marketing teams without SQL proficiency.
- Individual Consumers:Personal portfolio analytics and fitness tracking apps represent niche, low-ARPU demand.
Enterprises generate the highest absolute revenue; developers represent the steepest expansion trajectory through bottom-up viral adoption.
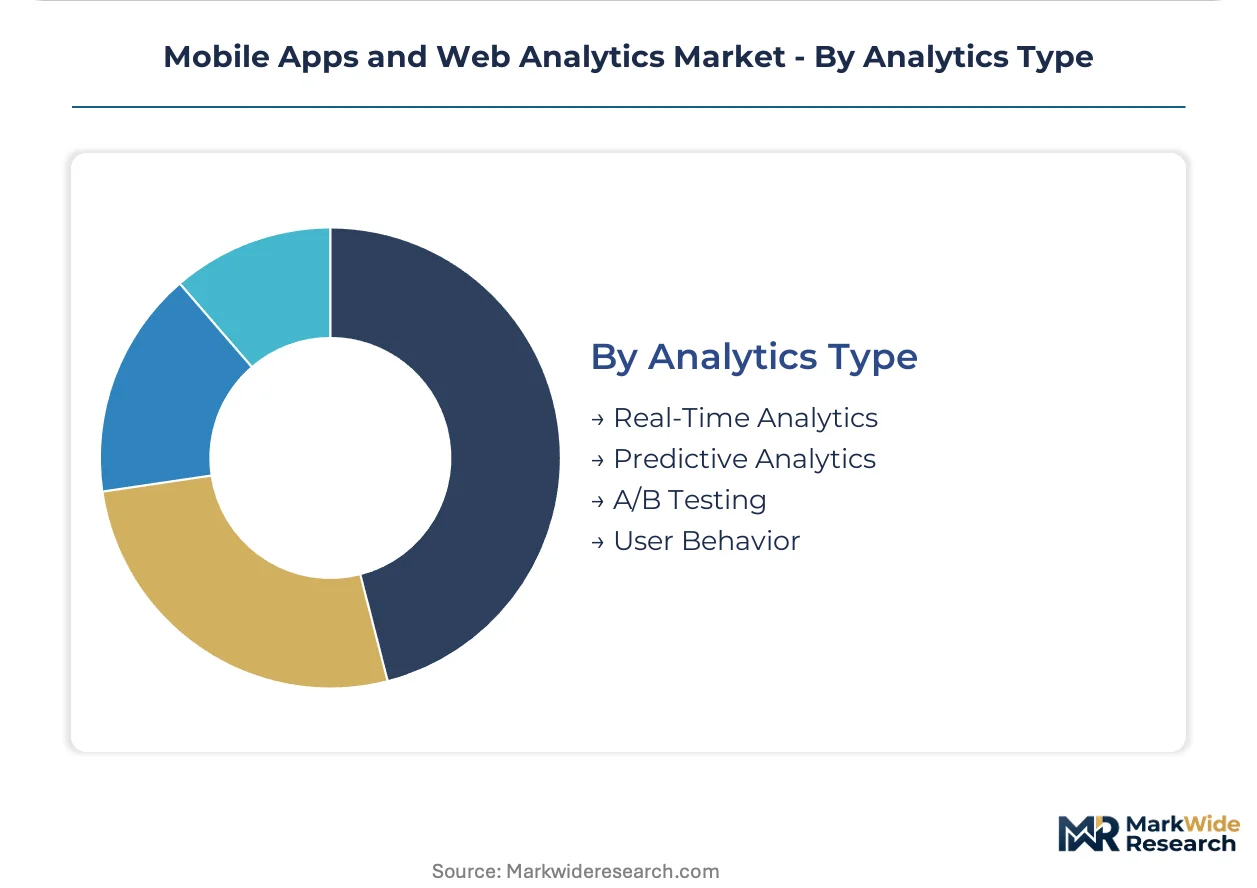
Analytics Type:
Technology maturity separates established descriptive analytics from emerging predictive and real-time capabilities requiring specialized infrastructure investment.
- Real-Time Analytics:Sub-second latency pipelines enable immediate personalization and fraud detection, demanding Apache Kafka or Flink expertise. United States fintech applications and German automotive connected-car platforms lead adoption, with edge computing investments collapsing data transfer costs for geographically distributed fleets.
- Predictive Analytics:Machine learning models forecast churn, lifetime value, and inventory demand, commanding 40-60% pricing premiums over descriptive tools. Subscription economy verticals in the United States and subscription-box retailers in the United Kingdom prioritize this capability for automated intervention workflows.
- A/B Testing:Statistical significance engines and multi-armed bandit algorithms optimize conversion rates through controlled experimentation.
- User Behavior:Session replay and heatmap visualization support UX research and funnel optimization for product teams.
User Behavior retains the largest installed base; Real-Time Analytics is gaining share fastest as infrastructure costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement of mobile and web analytics concentrates in digital-native economies with advanced cloud infrastructure and stringent data governance frameworks. Buyer archetypes split between North American hyperscaler-dependent enterprises, European compliance-first organizations, and Asia-Pacific mobile-first startups.
United States
FTC scrutiny of dark patterns and deceptive data practices shapes vendor product roadmaps for behavioral analytics tools. HIPAA compliance requirements dominate healthcare sector procurement, extending sales cycles for enterprise deployments. Silicon Valley clusters and Seattle metro areas anchor cloud-native analytics development, with fintech applications in New York demanding sub-second latency pipelines.
Germany
Automotive connected-car platforms and industrial IoT deployments drive demand for edge-first analytics architectures. GDPR and the EU AI Act impose mandatory human oversight requirements on high-risk automated decisioning systems. Munich and Stuttgart industrial corridors concentrate predictive maintenance analytics adoption, with Berlin startups prioritizing privacy-preserving computation methods.
India
UPI-driven e-commerce growth and rapid smartphone penetration create greenfield demand for mobile-first analytics among domestic startups. RBI guidelines on data localization influence vendor infrastructure decisions for financial services applications. Bangalore and Hyderabad technology clusters host multinational R&D centers, while Mumbai-based retailers optimize low-bandwidth SDKs for tier-2 city penetration.
United Kingdom
Subscription-box retailers and subscription economy verticals prioritize predictive churn reduction capabilities. Post-Brexit data protection divergence from EU standards complicates cross-border analytics architectures for multinational enterprises. London fintech density drives real-time fraud detection analytics adoption, with Manchester media clusters emphasizing content performance attribution.
South Korea
Live-service gaming economics and esports analytics demand instantaneous player behavior processing at massive scale. Personal Information Protection Act amendments tighten consent requirements for behavioral profiling. Seoul Capital Area game studios deploy dynamic difficulty adjustment systems, while Busan-Ulsan manufacturing hubs integrate supply chain analytics with mobile workforce dashboards.
Mobile Apps and Web Analytics Market Competitive Environment
Channel-controlling players compete with product-specialist players across deployment models, with hyperscaler cloud platforms and independent analytics vendors occupying distinct competitive tiers. Market structure tilts toward consolidation at the infrastructure layer while fragmenting across specialized application modules. Two strategic archetypes dominate: cloud-native platforms leveraging elastic scaling advantages, and vertical SaaS vendors embedding analytics into industry-specific workflows. Competitive moves center on API ecosystem expansion and pre-certified compliance module development for regulated verticals.
Within the cloud-platform tier, Google LLC and Microsoft Corporation anchor enterprise demand through deep infrastructure integration, while Adobe, Inc. occupies a position tying creative-cloud-adjacent behavioral analytics to conversion outcomes. These three exemplify how vendor differentiation increasingly depends on native connectivity to adjacent software ecosystems rather than standalone analytics capabilities.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Adobe, Inc. |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Amazon Web Services, Inc. |
| Teradata Corporation |
| Amplitude, Inc. |
| Others |
Value Chain & Pricing Dynamics
Seattle's hyperscaler infrastructure cluster concentrates real-time stream-processing capacity, giving vendors anchored there pricing leverage over mid-market buyers lacking comparable in-house Apache Kafka or Flink expertise. This geographic concentration of specialized engineering talent and serverless compute resources shapes how SaaS tiers are calibrated against on-premise alternatives.
Pricing Analysis
Cost-plus contracts with cloud infrastructure indexation dominate enterprise procurement, with pricing stratifying across premium, standard, and economy tiers based on event volume commitments and GDPR compliance certification levels. Price differentiation rests on latency guarantees and explainable AI module inclusion. Cost compression in the economy tier intensifies because Indian SaaS startups commoditize basic event ingestion. Mid-market digital agencies exhibit highest price sensitivity; regulated German automotive firms show lowest.
Supply Chain Analysis
Supply-chain finance facilities from AWS and Google Cloud extend payment terms for analytics vendors provisioning multi-region infrastructure, reducing working capital pressure. Component sourcing draws from United States cloud regions, Indian data engineering talent pools, and German privacy-preserving computation specialists. Single-source vulnerability concentrates in hyperscaler compute dependencies. Distribution runs through API-first integration marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile and web analytics functions as a service-attach opportunity where managed consent platforms and real-time personalization layers expand faster than core event ingestion infrastructure. Recurring revenue from compliance modules and edge-computing management outpaces license growth.
For Market Incumbents: Build switching-cost moats through deep Azure or Google Cloud native integration that embeds analytics into enterprise data lakes. Incumbents should pre-certify modules against EU AI Act enforcement standards before competitors, converting compliance burden into retention leverage. Capacity addition in Mumbai and Singapore cloud regions captures India-UPI-driven demand while hedging Schrems II transfer restrictions.
For New Entrants and Emerging Players: Build out vertical-specific churn prediction tools for subscription-box retailers and live-service gaming studios where incumbent platforms lack feature depth. India's tier-2 city e-commerce penetration represents the most penetrable geography, with low-bandwidth SDK optimization as the critical go-to-market angle. API-first documentation in Hindi and regional languages accelerates developer adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-consolidation play because mid-market buyers fatigue from best-of-breed integration complexity. Acquisition targets should exhibit native CDP connectivity and pre-built GDPR consent workflows. The signal to watch is FTC enforcement action on dark patterns, which simultaneously expands compliance-addressable market and constrains growth tactics.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Azure or Google Cloud connectivity embeds analytics into enterprise data governance stacks. |
| Acquisition of Specialist Firm | CDP vendors with first-party data consolidation capabilities command premium multiples. |
| Product Launch | Edge-first SDKs with local model inference address GDPR consent constraints in Germany. |
| Strategic Partnership | Hyperscaler co-selling agreements unlock enterprise procurement through existing cloud commitments. |
| Geographic Expansion | Mumbai and Hyderabad infrastructure captures UPI-driven Indian e-commerce analytics demand. |
Study Parameters
Desk research of SEC hyperscaler capex disclosures, App Annie mobile SDK adoption data, and EU regulatory filings preceded structured interviews with CTOs, platform engineers, data privacy officers, and channel integration specialists. Primary fieldwork with SaaS procurement teams and IT directors at e-commerce and gaming platforms combined with secondary validation from trade databases. Bottom-up event-volume modeling and top-down cloud infrastructure spend analysis provided triangulation.
Assumptions held cloud region expansion timelines and regulatory enforcement intensity within observed patterns while varying AI Act implementation strictness and cookie deprecation pace across scenarios. Segmentation dimensions modeled deployment model, organization size, vertical application, integration complexity, and regional data residency requirements. CAGRs derived from elasticity-adjusted pricing curves and event-volume growth trajectories. Apache Kafka adoption rates and serverless processing cost curves served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertical SaaS specialists embedding analytics into industry workflows would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Audio and Video Analytics Software Market
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Contact Center Analytics Market
Analytics
Europe Retail Analytics Market
Analytics
Europe HR Analytics Market
Analytics
Global Development Analytics Tools Market
Analytics
Regression Analysis Tool Market
Analytics
Global Analytics Software Market
Analytics
Behavior Analytics Market
Analytics
Business Intelligence (BI) Market
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Germany Geospatial Analytics Market
Analytics
Datacenter Analytics Market
Analytics
Augmented Analytics Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market