
 Content Analytics Market | 2026-2036
Content Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Content Analytics Market Analysis
ISO/IEC 27001 certification for information security management is collapsing the vendor qualification cycle, forcing prospective entrants to demonstrate compliant data governance before procurement review. Microsoft sustains cloud infrastructure dominance through Azure-native analytics integration. IBM Corporation differentiates via Watson's natural language processing heritage and hybrid deployment architecture. Adobe Systems Inc. leverages its Creative Cloud ecosystem to embed analytics directly within content production workflows.
Content analytics encompasses the algorithmic extraction of structured intelligence from unstructured text, image, audio, and video assets using computational linguistics, statistical pattern recognition, and neural network architectures. The technology processes multilingual sentiment, entity relationships, and semantic relevance at throughput rates exceeding human analytical capacity by orders of magnitude, primarily serving commercial functions of audience targeting, risk detection, and operational knowledge management. Cloud-based deployment leads segment adoption as enterprises migrate legacy on-premises installations to elastic infrastructure, while machine learning capabilities within the technology dimension capture the fastest expansion trajectory due to transformer-model advances in generative understanding. Natural language processing remains the mature revenue base, though margin pools are shifting toward predictive analytics as customers demand forward-looking content performance forecasting rather than retrospective reporting.
FDA oversight of software-as-medical-device classification intersects with content analytics applications in healthcare communications, while the EU AI Act imposes risk-tiered conformity obligations on automated content moderation systems deployed in European markets. The Securities and Exchange Commission's escalating scrutiny of social media sentiment manipulation further tightens compliance parameters for financial services deployments. Stakeholders must monitor the divergence between emerging sovereign AI frameworks and established data protection regimes to anticipate certification burdens that will determine market access eligibility.
Market Dynamics
Transformer-based neural architectures are compressing model deployment costs while expanding multilingual capability, forcing incumbents to reprice legacy natural language processing offerings or cede procurement cycles to cloud-native challengers.
Growth Catalysts
- EU AI Act Conformity Mandates:Risk-tiered obligations for automated content moderation systems are compelling European enterprises to upgrade analytics infrastructure ahead of enforcement deadlines, accelerating replacement cycles for legacy sentiment analysis tools.
- Healthcare Communications Surveillance:FDA software-as-medical-device classification intersects with patient-facing content analytics, creating compliance-driven procurement among pharmaceutical marketing departments for auditable classification systems.
- Elastic Cloud Migration:Enterprise data gravity is shifting toward Azure-native and AWS-native architectures, with procurement teams prioritizing analytics vendors offering serverless auto-scaling for seasonal content volume spikes.
Market Restraints
- ISO/IEC 27001 Certification Burden:Vendor qualification cycles now require demonstrable information security management compliance before procurement review, extending sales timelines and elevating pre-revenue engineering costs for prospective entrants.
- GPU Compute Cost Volatility:Training and inference workloads for transformer models remain tethered to NVIDIA datacenter supply allocations, with spot pricing fluctuations compressing margins for SaaS-native analytics providers.
- Data Residency Fragmentation:Divergent sovereign AI frameworks across jurisdictions are forcing redundant infrastructure deployment, with EU, Chinese, and Middle Eastern data localization requirements preventing unified global service architectures.
Strategic Opportunities
- Underpenetrated Middle East Deployment:MOHAP and SFDA regulatory modernization in UAE and Saudi Arabia is creating first-mover advantage for compliant content analytics in healthcare and financial services verticals.
- Generative Content Provenance:Convergence of blockchain attestation with neural watermarking is opening new revenue pools for authentication-as-a-service offerings targeting media conglomerates battling synthetic media disinformation.
- India PLI Scheme Alignment:Domestic data center capacity expansion under production-linked incentive frameworks is enabling localized analytics deployment for BFSI and e-commerce sectors previously dependent on Singapore or Mumbai hyperscaler regions.
Industry Challenges
- Transformer Architecture Talent Scarcity:Deep expertise in attention mechanism optimization and low-precision quantization remains concentrated among a narrow cohort of researchers, inflating compensation costs for model development teams.
- Legacy CMS Integration Friction:On-premises content management systems at established media enterprises require custom API middleware for real-time analytics ingestion, extending implementation timelines and elevating professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Analytics Market |
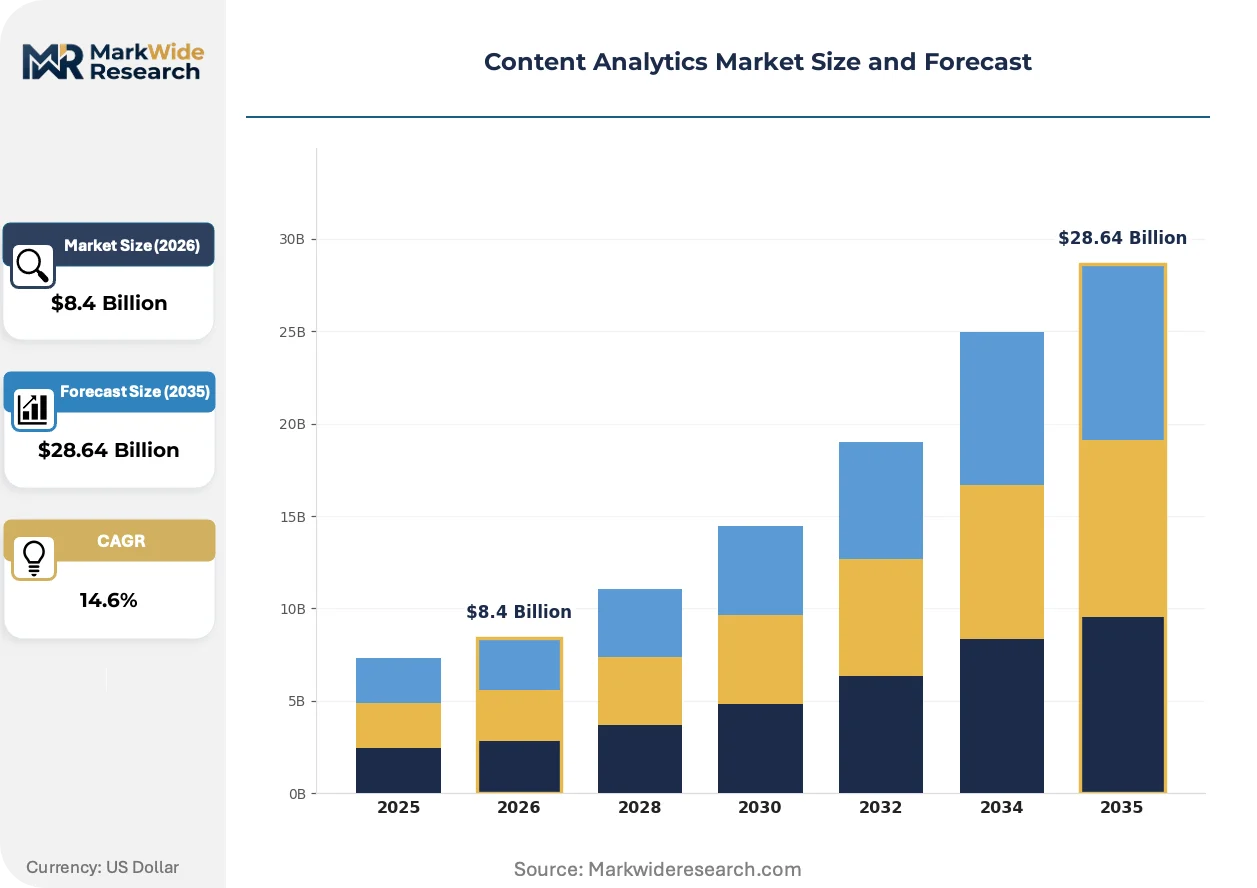
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Marketing Automation, Social Media Monitoring, Content Management, Search Engine Optimization Technology: Natural Language Processing, Machine Learning, Sentiment Analysis, Predictive Analytics Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Enterprises, Small Businesses, Agencies, Content Creators |
| Companies Covered | Adobe Systems Inc., IBM Corporation, Microsoft, Oracle Corporation, SAP SE, OpenText Corporation, Clarabridge, Inc., SAS Institute, Inc., NICE Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Analytics Market Emerging Trajectories
Edge-optimized model architectures are redistributing computational load away from centralized cloud infrastructure, enabling real-time content classification on commodity hardware without persistent connectivity.
Multimodal transformer stacks are miniaturizing through distillation and quantization techniques, allowing on-device inference for video sentiment analysis and automated thumbnail generation. Mobile-first publishers and field journalism networks are adopting these compressed models for immediate content optimization without upload latency. This capability is miniaturizing the hardware barrier to entry for analytics deployment, compressing the traditional cloud-dependency advantage held by hyperscale incumbents.
The EU AI Act's risk-tiered conformity framework is imposing documentation and human-in-the-loop requirements on high-risk content moderation applications. Automated systems deployed for news curation and political discourse classification must now maintain auditable decision trails and bias assessment protocols. Financial services deployments in Frankfurt and Amsterdam are responding by segregating European data processing from global analytics pipelines, fragmenting previously unified product architectures.
Enterprise buying committees are consolidating vendor relationships around integrated creative-to-analytics workflows rather than standalone point solutions. Media production teams in Los Angeles and New York are embedding classification and performance forecasting directly within Adobe Creative Cloud and equivalent production environments, displacing separate dashboard-centric procurement. This pattern is most visible among streaming platform content operations seeking to compress time-to-publish metrics for competitive release windows.
Content Analytics Market Segmentation
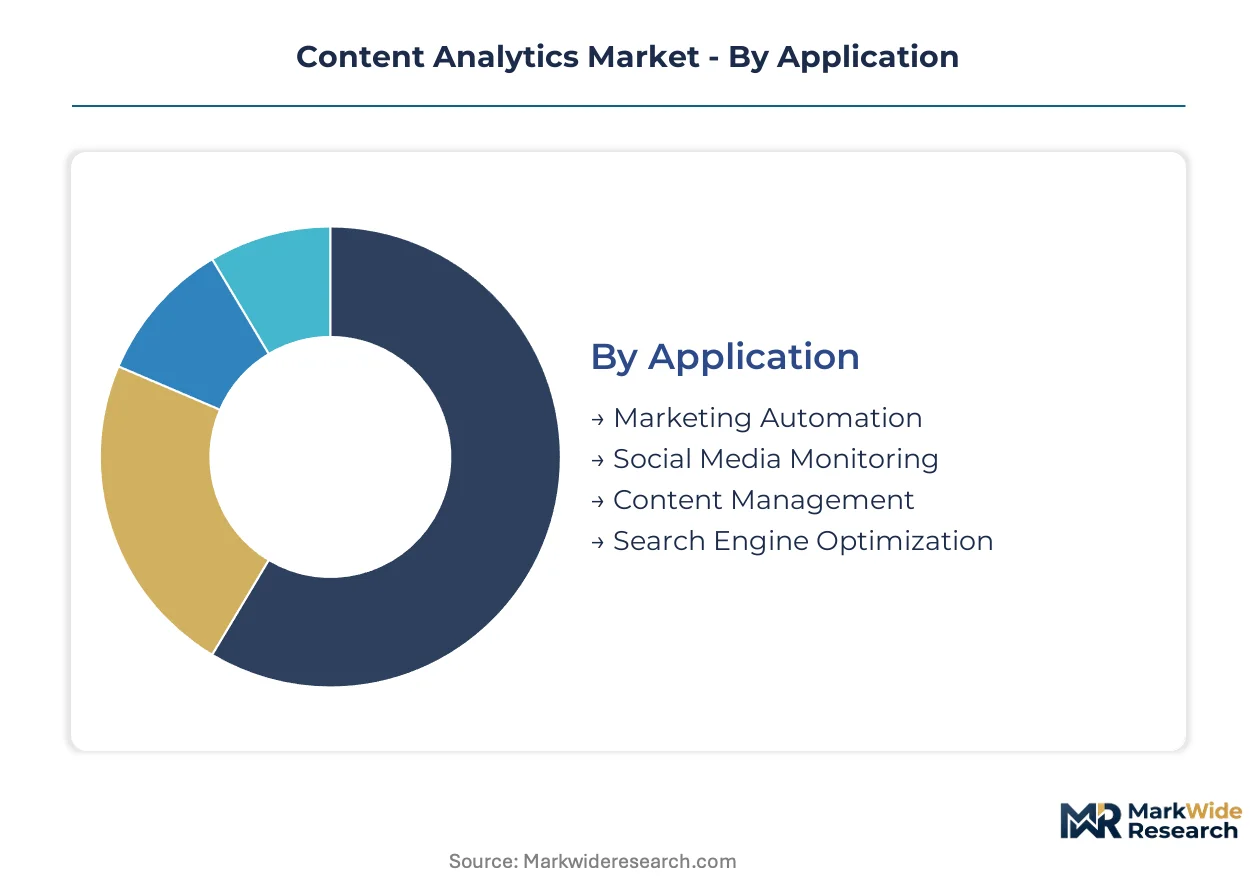
Content analytics vendors structure pricing and service tiers around deployment complexity and buyer sophistication. Channel strategy varies sharply between self-serve SaaS portals and enterprise field sales organizations.
Application:
Marketing automation platforms absorb the highest volume of content analytics licensing, while social media monitoring commands premium per-seat pricing due to real-time throughput requirements.
- Marketing Automation:Campaign orchestration tools ingest audience sentiment signals to trigger personalized content delivery. Demand concentrates among B2B technology vendors in California and Massachusetts seeking account-based engagement optimization.
- Social Media Monitoring:Real-time brand reputation tracking processes millions of posts hourly for crisis detection. Financial services compliance teams in New York and London drive procurement for SEC and FCA audit trail requirements.
- Content Management:Editorial workflow systems embed classification for asset discoverability.
- Search Engine Optimization:Rank tracking and semantic keyword tools serve digital marketing agencies.
By volume, marketing automation leads. By growth pace, social media monitoring is gaining share fastest.
Technology:
Cost tiering separates mature natural language processing stacks from emerging predictive capabilities requiring specialized engineering talent.
- Natural Language Processing:Named entity recognition and syntactic parsing form the foundational layer of content intelligence. Media conglomerates in Los Angeles and New York maintain the largest installed bases for automated tagging and summarization.
- Machine Learning:Transformer-based models enable generative content understanding beyond pattern matching. Healthcare communications teams at pharmaceutical headquarters in New Jersey and Basel pursue FDA-compliant classification systems.
- Sentiment Analysis:Polarity scoring and emotion detection serve customer experience dashboards.
- Predictive Analytics:Forward-looking performance forecasting commands implementation premiums.
Natural language processing dominates current revenue. Predictive analytics shows the steepest expansion trajectory.
Deployment:
Customer type determines infrastructure choice — regulated industries demand data residency while digital-native firms prioritize elasticity.
- Cloud-Based:Serverless architectures auto-scale with seasonal content surges. E-commerce platforms and streaming services in Seattle and Shenzhen favor consumption-based pricing over capital expenditure.
- Hybrid:Sensitive processing remains on-premises while model training leverages cloud GPU pools. European banks in Frankfurt and Paris adopt this architecture for EU AI Act compliance without sacrificing computational access.
- On-Premises:Air-gapped installations serve classified government communications.
- SaaS:Multi-tenant platforms reduce time-to-value for mid-market buyers.
Cloud-based deployment leads by volume. Hybrid architectures are climbing the fastest among compliance-sensitive verticals.
End User:
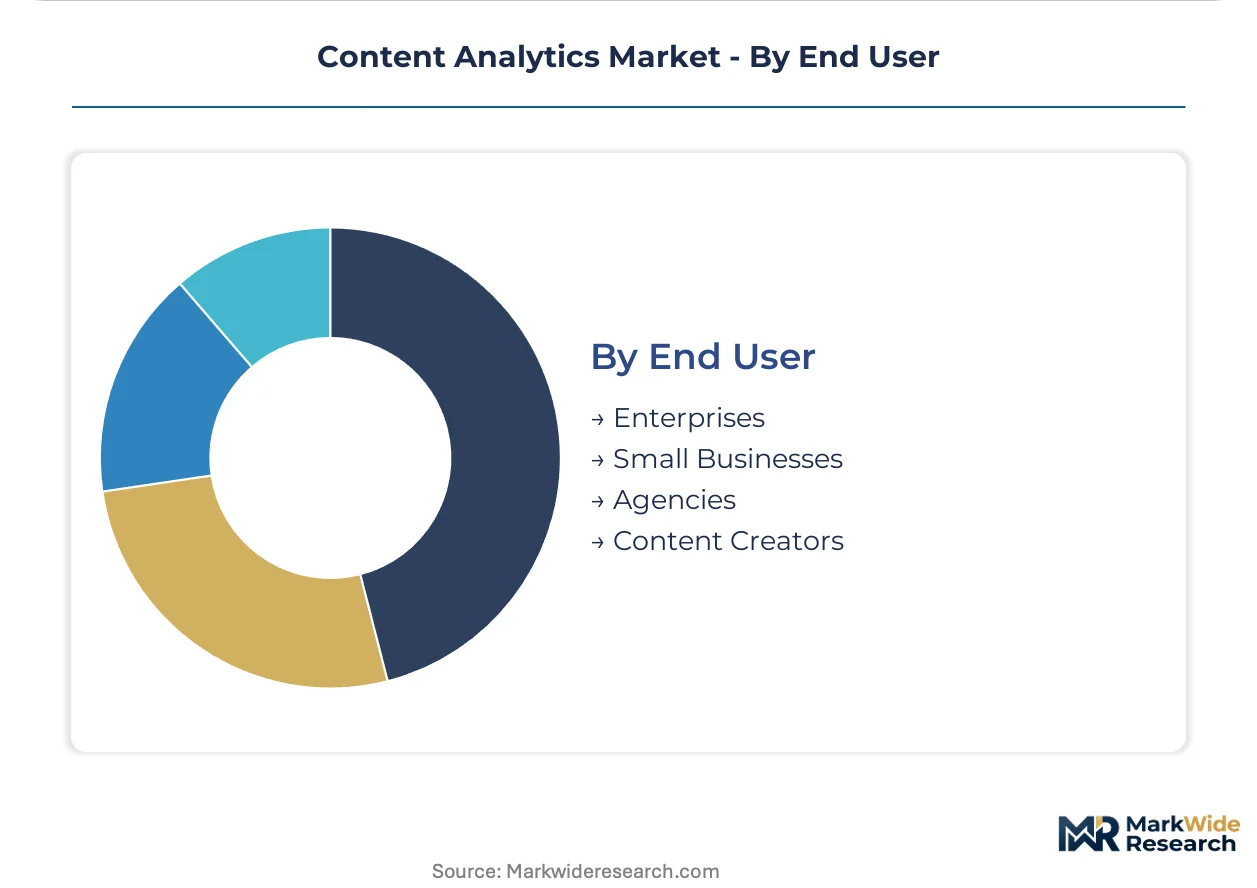
Margin pools concentrate with enterprise buyers seeking customized model training, while agencies drive volume through standardized seat licenses.
- Enterprises:Global marketing organizations require bespoke integrations with existing martech stacks. Fortune 500 headquarters in Chicago and Dallas negotiate multi-year contracts with dedicated customer success resources.
- Agencies:Multi-client service providers need cross-account analytics with role-based access controls. Holding company networks in London and Tokyo consolidate vendor relationships for portfolio-wide efficiency.
- Small Businesses:Self-serve onboarding and template dashboards reduce implementation friction.
- Content Creators:Individual practitioners prioritize mobile-optimized performance insights.
Enterprises lead by contract value. Agencies represent the fastest-expanding user category by seat count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's risk-tiered conformity framework is accelerating infrastructure upgrades across European enterprises, while sovereign data localization mandates in Asia-Pacific and the Middle East are fragmenting previously unified service architectures.
United States
Enterprise marketing teams at media conglomerates headquartered in New York and Los Angeles drive procurement for sentiment analysis tools integrated into brand reputation management workflows. SEC scrutiny of social media sentiment manipulation tightens compliance parameters for financial services deployments in Manhattan and Chicago. FDA oversight of software-as-medical-device classification intersects with content analytics applications in healthcare communications, creating compliance-driven procurement among pharmaceutical marketing departments in New Jersey.
Germany
European banks in Frankfurt and Paris adopt hybrid deployment architectures for EU AI Act compliance without sacrificing computational access to cloud GPU pools. The EU AI Act imposes documentation and human-in-the-loop requirements on high-risk content moderation applications deployed for news curation and political discourse classification. Financial services deployments in Frankfurt are responding by segregating European data processing from global analytics pipelines.
United Kingdom
Agency holding company networks in London consolidate vendor relationships for portfolio-wide efficiency across multi-client analytics deployments. FCA audit trail requirements drive procurement for real-time brand reputation tracking systems among financial services compliance teams. The city's concentration of B2B technology vendors seeks account-based engagement optimization through campaign orchestration tools ingesting audience sentiment signals.
India
Domestic data center capacity expansion under production-linked incentive frameworks enables localized analytics deployment for BFSI and e-commerce sectors previously dependent on Singapore or Mumbai hyperscaler regions. BIS certification requirements and RBI data localization mandates shape vendor qualification criteria for financial services procurement. Bengaluru and Hyderabad clusters concentrate engineering talent for transformer model optimization and low-precision quantization development.
United Arab Emirates
MOHAP and SFDA regulatory modernization in UAE and Saudi Arabia creates first-mover advantage for compliant content analytics in healthcare and financial services verticals. Dubai's media production ecosystem embeds classification and performance forecasting directly within creative workflows for streaming platform content operations. Data residency requirements across Middle Eastern jurisdictions prevent unified global service architectures, forcing redundant infrastructure deployment.
Content Analytics Market Vendor Landscape
Listed leaders compete with private specialists across cloud infrastructure and natural language processing heritage dimensions, creating a tiered competitive structure where scale advantages in compute provisioning confront vertical expertise in regulatory compliance. Public cloud hyperscalers leverage existing enterprise relationships to bundle analytics capabilities within broader infrastructure contracts. Strategic archetypes include infrastructure-integrated platforms, heritage AI research laboratories, and creative ecosystem embedders. Dominant competitive moves center on hybrid deployment architecture expansion and workflow integration partnerships with production software vendors.
Within the heritage AI tier, IBM Corporation and SAS Institute occupy positions exemplifying natural language processing lineage and statistical computing heritage. Microsoft anchors the infrastructure-integrated archetype through Azure-native analytics integration, while Adobe Systems represents creative ecosystem embedding through Creative Cloud workflow integration. These three companies collectively illustrate the competitive vectors of hybrid deployment, cloud-native scaling, and production-environment embedding that define current procurement evaluation criteria.
| Leading Market Players |
|---|
| Adobe Systems Inc. |
| IBM Corporation |
| Microsoft |
| Oracle Corporation |
| SAP SE |
| OpenText Corporation |
| Clarabridge, Inc. |
| SAS Institute, Inc. |
| NICE Systems Ltd. |
| Others |
Supply Flow & Price Mechanics
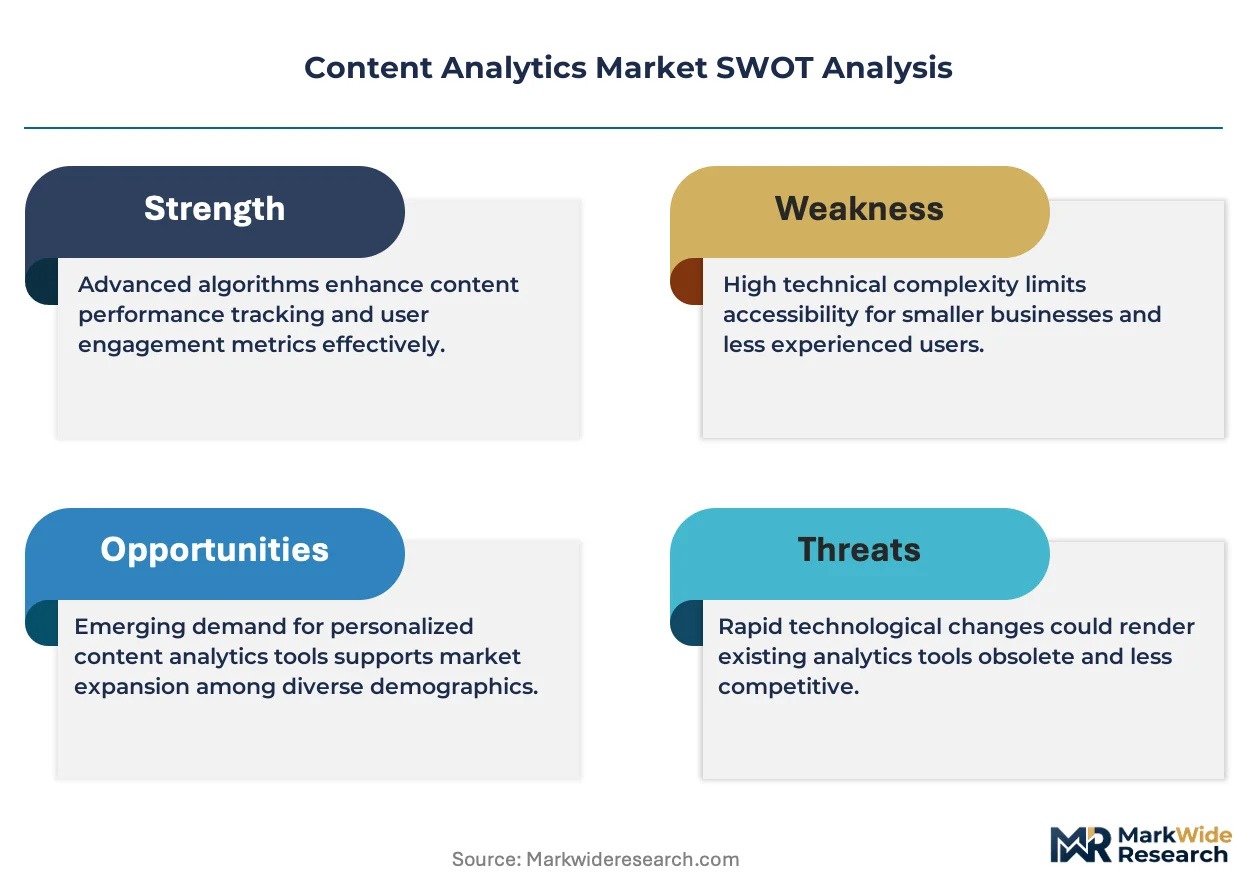
ISO/IEC 27001 certification gates both vendor qualification and price differentiation in content analytics procurement, forcing prospective suppliers to absorb compliance engineering costs before revenue recognition while enabling certified incumbents to command implementation premiums from risk-averse enterprise buyers.
Pricing Analysis
Certification level creates the primary spread between pricing tiers, with ISO/IEC 27001 and EU AI Act conformity-grade deployments commanding substantial premiums over standard SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates audit-ready enterprise installations from mid-market dashboard access and self-serve API tiers. Cost compression in the standard tier intensifies because transformer model commoditization erodes differentiation among cloud-native challengers. Small businesses and individual content creators exhibit highest price sensitivity, while pharmaceutical marketing departments in New Jersey and financial services compliance teams in Manhattan demonstrate lowest elasticity due to regulatory audit trail requirements.
Supply Chain Analysis
Inventory cycles for GPU compute instances and specialized AI accelerators now dictate vendor delivery timelines, with NVIDIA datacenter supply allocations creating 12-16 week fulfillment windows for training infrastructure. Hardware supply concentrates in Taiwan, South Korea, and the United States, while cloud infrastructure provisioning draws from hyperscaler regions in Virginia, Frankfurt, and Singapore. Transformer architecture talent scarcity in Bengaluru and Hyderabad clusters creates single-source vulnerability for model optimization expertise. Distribution runs through direct enterprise field sales for Fortune 500 accounts and self-serve SaaS portals for mid-market buyers, with agency holding companies in London and Tokyo consolidating multi-seat procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buying committee consolidation around integrated creative-to-analytics workflows has shifted bargaining power toward procurement teams at media conglomerates and pharmaceutical headquarters, compressing standalone vendor margins.
For Market Incumbents: Fortify hybrid deployment architecture leadership by expanding on-premises certification coverage for EU AI Act compliance in Frankfurt and Paris banking corridors. Deepen backward integration into edge-optimized model distillation capabilities to counter cloud-native challengers exploiting transformer commoditization. Prioritize Adobe Creative Cloud and equivalent production environment partnerships to embed classification directly within content workflows, displacing separate dashboard-centric procurement at Los Angeles and New York streaming operations. For New Entrants and Emerging Players: BIS certification fast-track for Indian domestic data center deployment under PLI schemes opens white-space access to BFSI and e-commerce sectors previously dependent on Singapore hyperscaler regions. Target Middle East healthcare communications modernization in UAE and Saudi Arabia, where MOHAP and SFDA regulatory alignment creates first-mover advantage before incumbent field sales organizations establish presence. Pursue generative content provenance authentication-as-a-service offerings, combining blockchain attestation with neural watermarking for media conglomerates battling synthetic media disinformation. For Investors and Strategic Acquirers: EU AI Act enforcement milestone reshapes the acquisition landscape toward compliance-ready infrastructure with documented human-in-the-loop architectures and auditable decision trails. Long-term viability over the projection horizon favors transformer model optimization specialists with demonstrated low-precision quantization expertise concentrated in narrow research cohorts. Monitor divergence between sovereign AI frameworks and established data protection regimes as the critical signal for certification burden escalation that will determine market access eligibility and target valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Architecture Expansion | European banks in Frankfurt adopt segregated data processing for EU AI Act compliance without sacrificing cloud GPU access. |
| Creative Ecosystem Integration Partnership | Los Angeles streaming operations embed classification within Adobe Creative Cloud to compress time-to-publish metrics. |
| Edge-Optimized Model Miniaturization | Mobile-first publishers deploy compressed multimodal transformers for real-time video sentiment analysis without upload latency. |
| Generative Content Provenance Service Launch | Media conglomerates battling synthetic media disinformation purchase blockchain-neural watermarking authentication bundles. |
| Regulatory Certification Fast-Track Investment | Indian BFSI procurement shifts to PLI-enabled domestic data centers with BIS and RBI compliant analytics deployment. |
Methodological Framework
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory frameworks preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across enterprise marketing organizations and agency holding companies. Primary fieldwork with pharmaceutical regulatory affairs leads and financial services compliance directors validated secondary data on FDA software-as-medical-device classification and SEC sentiment manipulation scrutiny. Bottom-up sizing of deployment volumes and top-down validation against cloud infrastructure spending patterns ensured cross-method consistency.
Variance decomposition across deployment model, organization size, vertical integration complexity, and regional regulatory adoption pattern drove segment-level projections. CAGRs were derived from elasticity-adjusted penetration curves and technology substitution rates throughout the forecast period. Transformer model cost compression trajectories and GPU supply allocation constraints informed infrastructure investment assumptions, while EU AI Act compliance deadlines shaped European replacement cycle timing.
Underlying assumptions cover sovereign AI framework stability and hyperscaler pricing continuity, with deviation risk concentrated in NVIDIA supply allocation volatility and divergence between national data localization mandates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Data Preparation Market
Analytics
Big Data Analytics Market
Analytics
North America Crowd Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Europe Data Monetization Market
Analytics
Legal Analytics Market
Analytics
AI Performance Marketing Market
Analytics
Global Visual Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
India Big Data Technology and Service Market
Analytics
Capacity Management Analytics Market
Analytics
Multichannel Analytics Market
Analytics
India Geospatial Analytics Market
Analytics
Marketing Analytics Market
Analytics
UK Geospatial Analytics Market
Analytics
Global Business Intelligence and Analytics Market