
 Predictive and Prescriptive Analytics Market | 2026-2036
Predictive and Prescriptive Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Predictive and Prescriptive Analytics Market Analytics
North American cloud infrastructure providers is rebalancing capacity allocation toward AI-native compute clusters. Palantir Technologies leverages government and defense sector relationships to sustain high-margin contract flows. IBM anchors enterprise credibility through decades of statistical computing heritage. C3 AI differentiates via energy-sector specialization and pre-built industry application templates.
Predictive and prescriptive analytics encompasses algorithmic methods that forecast future states from historical data patterns and recommend optimal decisions through simulation and optimization engines, typically operating on structured and unstructured datasets exceeding terabyte scale with sub-second inference latency requirements. The primary commercial purpose centers on reducing operational uncertainty and automating complex choice architectures across capital-intensive industries. Software solutions command the dominant revenue share while cloud-based delivery models capture the fastest expansion trajectory as enterprises abandon on-premise maintenance burdens. Healthcare and finance end-user segments generate the steepest growth curves due to regulatory pressure for explainable risk modeling and precision intervention protocols.
FDA guidelines on AI-enabled medical devices, the EU AI Act risk classification framework for high-stakes algorithmic systems, and HIPAA data governance requirements collectively reshape product development roadmaps and liability exposure for vendors serving regulated industries. These compliance architectures force platform providers to invest in interpretability layers, audit trails, and human-in-the-loop validation mechanisms as baseline market access conditions. Stakeholders must monitor how emerging sector-specific algorithmic accountability standards in finance and healthcare redefine competitive moats before committing to long-term architecture decisions.
Market Dynamics
The EU AI Act's risk classification framework for high-stakes algorithmic systems is forcing platform providers to embed interpretability layers and human-in-the-loop validation as baseline market access conditions, fundamentally restructuring product development economics across healthcare and finance deployments.
Growth Catalysts
- FDA AI/ML-Based Medical Device Guidelines:Healthcare providers accelerate deployment of predictive patient outcome models to meet precision intervention mandates and reduce readmission penalties.
- Cloud-Native Compute Infrastructure:Enterprise abandonment of on-premise maintenance burdens drives fastest expansion trajectory for cloud-based delivery models.
- Energy Sector Digitalization:Capital-intensive utilities deploy pre-built industry application templates to optimize grid operations and renewable asset forecasting.
Market Restraints
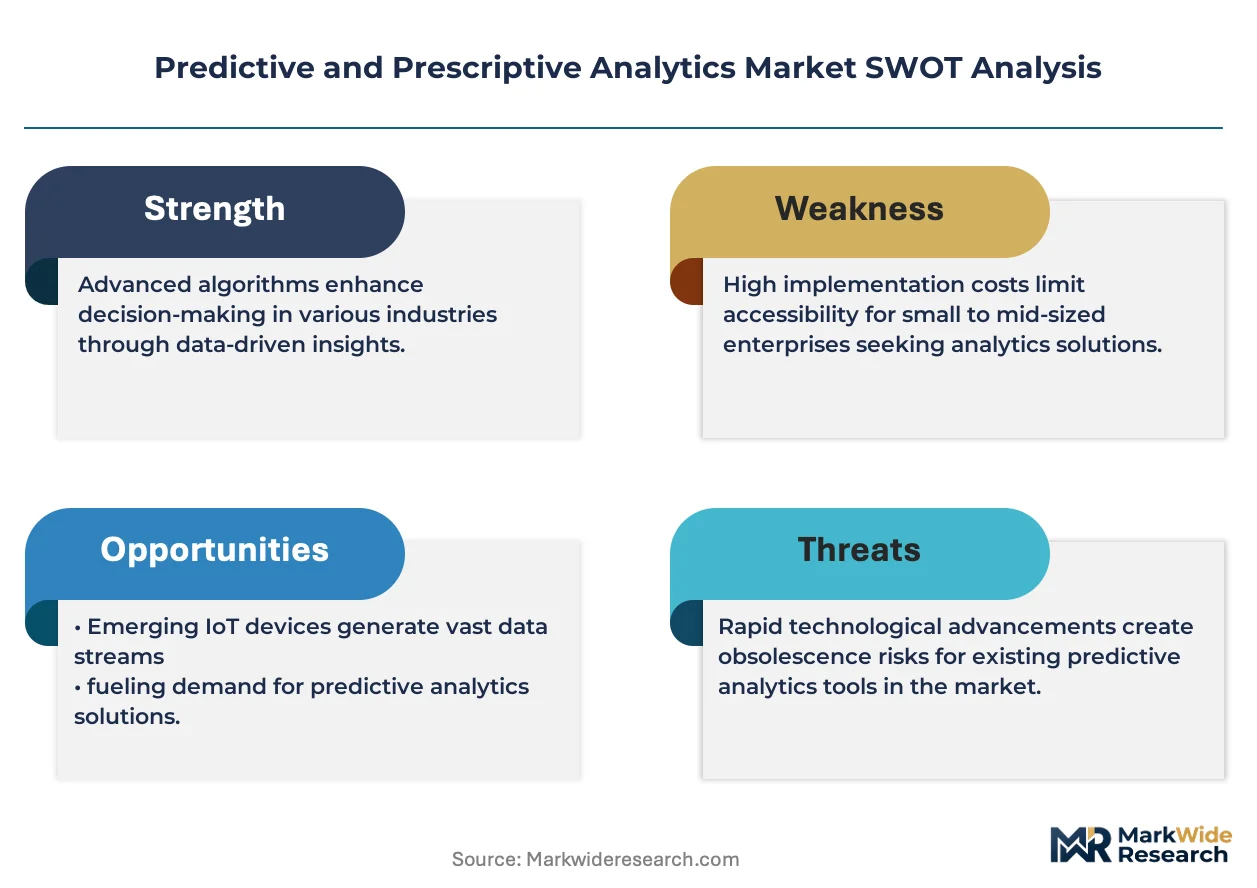
- Specialized Talent Scarcity:Shortage of data engineers capable of building sub-second inference pipelines on terabyte-scale datasets inflates implementation costs.
- Cross-Border Data Fragmentation:HIPAA data governance requirements and GDPR territoriality rules create architectural complexity for multi-national deployments.
- Legacy System Entrenchment:Decades-old statistical computing installations in established enterprises slow replacement cycles for modern optimization engines.
Strategic Opportunities
- Explainable AI Mandates:Regulatory pressure for interpretable risk modeling in finance creates demand for audit-trail-enabled platforms.
- Edge Computing Convergence:Integration of federated learning with 5G infrastructure enables real-time prescriptive analytics in manufacturing and logistics.
- Defense Sector Expansion:Government intelligence contracts sustain high-margin revenue flows for vendors with security clearance capabilities.
Industry Challenges
- Model Drift Management:Production environments require continuous retraining pipelines as underlying data distributions shift, demanding specialized MLOps functions.
- Algorithmic Accountability Standards:Emerging sector-specific liability frameworks in finance and healthcare redefine competitive moats before architecture decisions lock in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Predictive and Prescriptive Analytics Market |
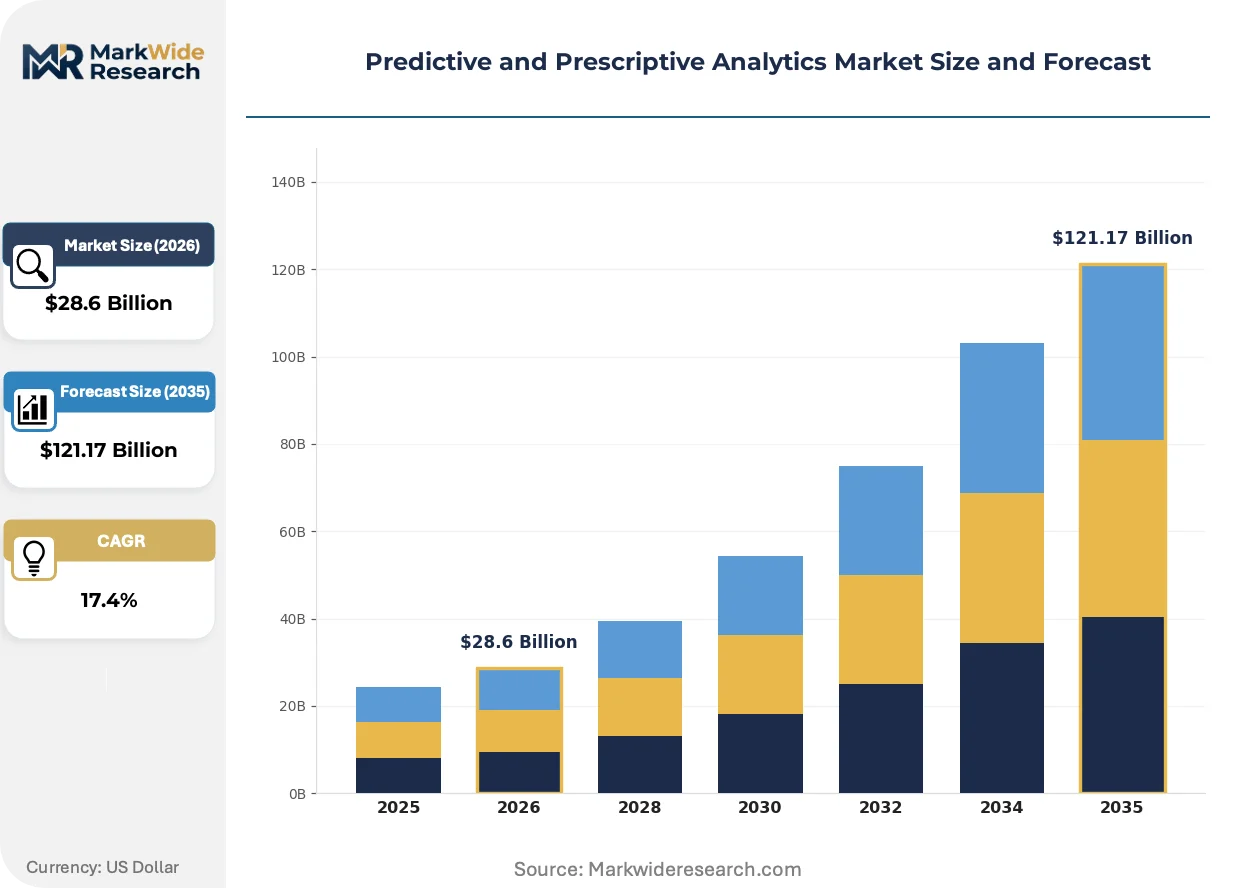
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Software, Services, Cloud-Based, On-Premise Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing End User: Healthcare, Finance, Retail, Manufacturing Use Case: Customer Analytics, Risk Management, Supply Chain Optimization, Marketing Automation |
| Companies Covered | Palantir Technologies, C3 AI, DataRobot, Deloitte, Accenture, IBM, Dataiku, Wildnet Edge, SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Predictive and Prescriptive Analytics Market Evolving Landscape
Foundation model architectures are compressing development timelines for industry-specific predictive applications, while regulatory pressure for algorithmic transparency accelerates investment in explainability tooling.
Graph neural networks for relational reasoning in fraud detection and supply chain optimization are converging with transformer-based sequence modeling to enable multi-modal forecasting across structured and unstructured data sources. Financial institutions in the United States adopt these hybrid architectures fastest, compressing model deployment cycles from quarters to weeks. This convergence is collapsing the historical separation between descriptive business intelligence and prescriptive decision automation.
The EU AI Act's mandatory conformity assessments for high-risk algorithmic systems impose documentation burdens that favor established vendors with compliance infrastructure. European healthcare providers now require CE-marked interpretability modules as procurement prerequisites. German and French regulators are pioneering sector-specific audit protocols that will likely propagate to other member states through harmonized standards.
Enterprise buyers increasingly unbundle implementation services from software licensing, shifting toward outcome-guarantee contracting with penalty clauses for model accuracy degradation. This procurement evolution concentrates purchasing power among Fortune 500 technology procurement offices. United States-based healthcare networks lead this transition, demanding performance-based pricing tied to measurable operational efficiency gains.
Predictive and Prescriptive Analytics Market Segmentation
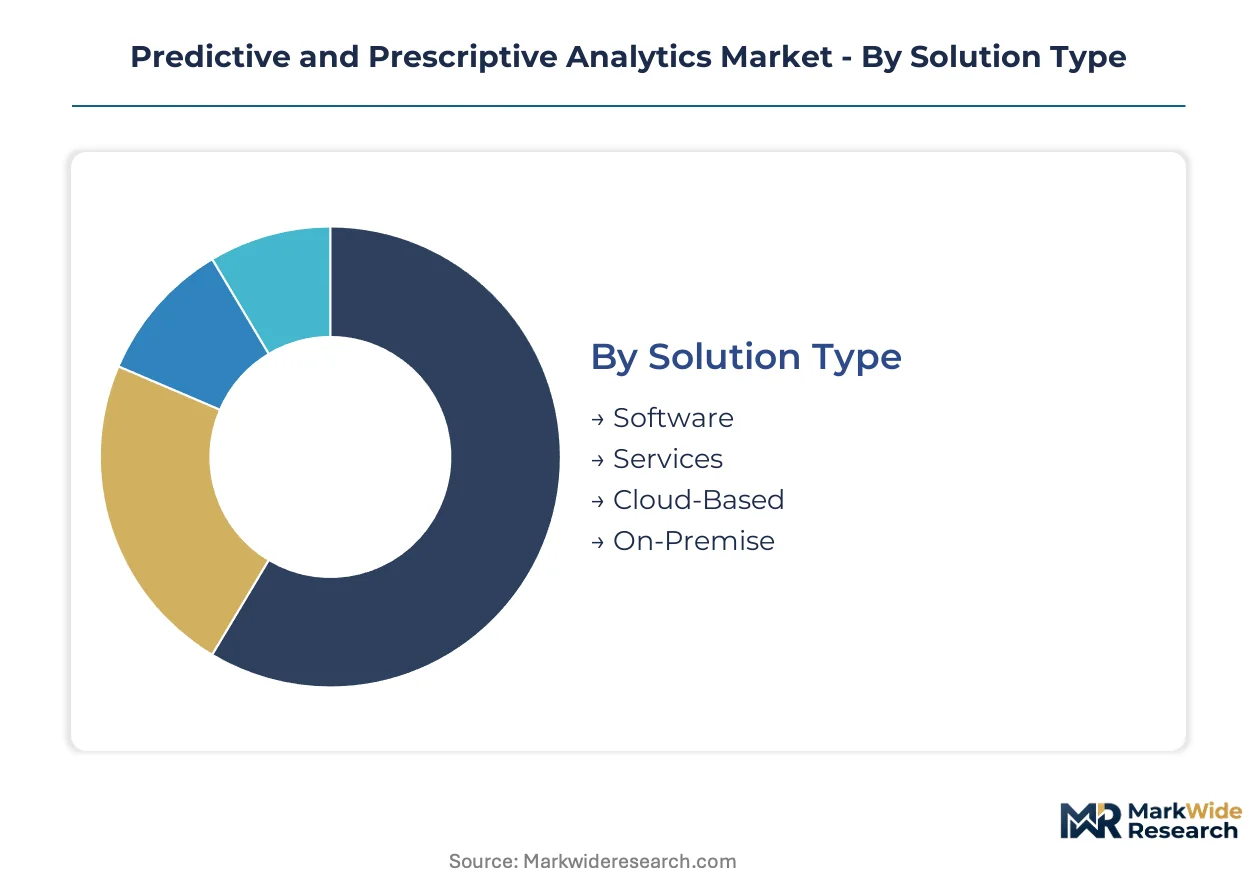
Segmentation in predictive and prescriptive analytics reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and operational complexity. Buyers select solution architectures based on inference latency requirements, data sovereignty constraints, and existing cloud commitments rather than feature comparisons alone.
Solution Type:
Enterprise procurement teams weight total cost of ownership against customization depth when selecting solution formats.
- Software:Licensed platforms deliver sub-second inference engines and pre-built optimization algorithms for terabyte-scale datasets. Healthcare networks in the United States favor perpetual licenses for patient outcome models to satisfy HIPAA audit requirements and avoid recurring cloud egress fees.
- Services:Implementation and managed analytics offerings bridge talent gaps for organizations lacking MLOps capabilities. Finance sector buyers in Frankfurt and Singapore contract specialized firms to build interpretability layers mandated by EU AI Act conformity assessments.
- Cloud-Based:Subscription models eliminate capital expenditure for compute infrastructure. Retail chains deploy auto-scaling inference clusters during seasonal demand spikes without provisioning idle capacity.
- On-Premise:Air-gapped installations serve defense and intelligence agencies with security clearance requirements. German automotive manufacturers maintain local optimization engines to protect proprietary supply chain data.
Volume sits with Software; growth tilts toward Cloud-Based.
Deployment Model:
Latency tolerance and data residency rules determine infrastructure topology selection.
- Public Cloud:Shared compute pools offer lowest unit economics for batch forecasting workloads. United States-based marketing automation platforms process petabyte-scale consumer behavior datasets through hyperscaler regions.
- Private Cloud:Dedicated tenant environments satisfy financial services regulators in Switzerland and Singapore. Swiss private banks deploy isolated Kubernetes clusters for wealth management algorithms subject to FINMA scrutiny.
- Hybrid Cloud:Split architectures separate sensitive training data from scalable inference endpoints. French healthcare providers route patient records through on-premise de-identification pipelines before cloud-based model execution.
- Edge Computing:Federated learning nodes enable real-time prescriptive analytics without central data aggregation. Japanese automotive suppliers embed optimization engines directly into factory floor controllers.
Public Cloud captures current deployment majority; Hybrid Cloud climbs the fastest as sovereignty requirements harden.
End User:
Industry-specific liability frameworks and intervention mandates reshape platform requirements.
- Healthcare:FDA AI/ML medical device guidelines and EU MDR conformity assessments demand explainable prediction pathways. Cleveland Clinic and Charité Berlin require CE-marked interpretability modules for surgical risk models.
- Finance:Basel IV operational risk standards and SEC algorithmic trading disclosures drive audit-trail investments. JPMorgan Chase and Deutsche Bank deploy counterfactual explanation engines for credit decision appeals.
- Retail:Demand forecasting and dynamic pricing optimization consume seasonal demand volatility. Walmart and Carrefour integrate weather data streams with inventory repositioning algorithms.
- Manufacturing:Predictive maintenance and quality control applications reduce unplanned downtime. Siemens and Toyota Motor deploy vibration sensor networks feeding edge-based failure prediction models.
Healthcare commands premium pricing; Finance gains share fastest on regulatory automation demand.
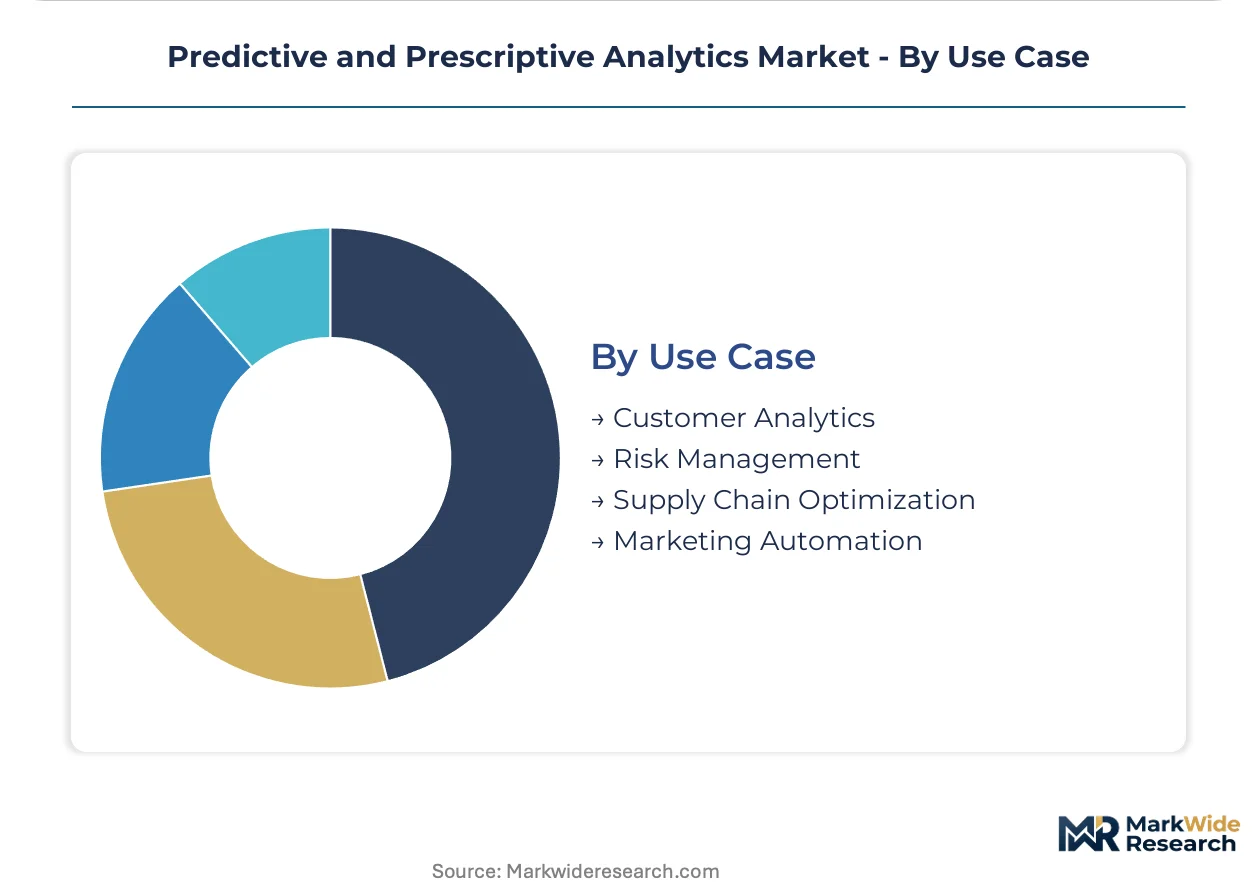
Use Case:
Functional applications vary in data complexity, decision velocity, and human oversight requirements.
- Customer Analytics:Churn prediction and lifetime value scoring leverage transactional and behavioral data fusion. United States telecom operators combine call detail records with social sentiment feeds.
- Risk Management:Credit default and insurance underwriting models face strict adverse action documentation rules. Lloyd's of London syndicates implement SHAP-value explanations for policy rejection appeals.
- Supply Chain Optimization:Multi-echelon inventory positioning and disruption response require graph neural network architectures. Maersk and DHL simulate port congestion scenarios through digital twin environments.
- Marketing Automation:Real-time bid optimization and content personalization demand millisecond inference latency. Procter & Gamble and L'Oréal deploy creative performance prediction across programmatic advertising exchanges.
Customer Analytics retains largest installed base; Supply Chain Optimization expands most quickly on geopolitical disruption response needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler concentration anchors North American cloud infrastructure investment. European data sovereignty requirements reshape procurement patterns. Asian financial centers accelerate regulatory technology deployment.
United States
FDA AI/ML medical device guidelines drive healthcare provider adoption of predictive patient outcome models. HIPAA data governance requirements enforce strict audit trails for algorithmic decision systems. Cleveland Clinic and Mayo Clinic deploy CE-marked interpretability modules for surgical risk scoring.
Germany
Industrial automotive clusters demand edge-based optimization engines for supply chain resilience. EU AI Act conformity assessments mandate documentation burdens favoring established compliance infrastructure. Siemens and BMW embed federated learning nodes into Bavarian factory floor controllers.
United Kingdom
Financial services regulators enforce algorithmic trading disclosure standards through FCA scrutiny. Basel IV operational risk frameworks accelerate audit-trail investments. Lloyd's of London syndicates implement SHAP-value explanations for credit decision appeals.
Japan
Manufacturing predictive maintenance applications reduce unplanned downtime in automotive supply chains. METI industrial digitalization programs subsidize edge computing convergence. Toyota Motor deploys vibration sensor networks feeding failure prediction models across Aichi prefecture facilities.
India
IT services exports create MLOps talent pipelines for multinational implementation contracts. RBI guidelines on algorithmic credit scoring drive explainable AI investments. Bangalore and Hyderabad clusters host delivery centers for healthcare analytics platforms serving US hospital networks.
Predictive and Prescriptive Analytics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue vertical specialization and outcome-based contracting. The vendor base stratifies across three maturity levels: legacy statistical computing heritage, cloud-native AI platforms, and consulting-anchored implementation services. Strategic archetypes include government-contract specialists, energy-sector verticalists, and enterprise credibility anchors. Competitive moves concentrate on compliance infrastructure acquisition and interpretability layer development.
Within the government-contract tier, Palantir Technologies occupies a position exemplifying security-clearance-dependent revenue models. C3 AI and DataRobot represent the vertical-specialist archetype, anchoring energy-sector and automated machine learning positioning respectively. IBM exemplifies the heritage-anchor category, leveraging decades of statistical computing credibility for enterprise procurement decisions.
| Leading Market Players |
|---|
| Palantir Technologies |
| C3 AI |
| DataRobot |
| Deloitte |
| Accenture |
| IBM |
| Dataiku |
| Wildnet Edge |
| SAS |
| Others |
Value Network & Pricing Analysis
EU AI Act conformity assessments for high-risk algorithmic systems gate qualified supply for vendors serving regulated healthcare and finance sectors, with CE-marked interpretability modules commanding premium-tier pricing access over unbundled software licenses lacking audit-trail infrastructure.
Pricing Analysis
Warranty and managed service bundling separates premium-tier platform providers from commodity software vendors in this market. Three-tier pricing structure across enterprise-grade, mid-market, and developer-access levels reflects differentiation by compliance certification depth and MLOps support inclusion. Pricing pressure stems from hyperscaler cloud compute commoditization eroding margins on raw inference capacity. Healthcare networks exhibit lowest price sensitivity due to HIPAA liability exposure, while retail demand forecasting buyers negotiate aggressively on per-query pricing.
Supply Chain Analysis
India's domestic-content mandates for government IT procurement are reshaping sourcing patterns for implementation services and MLOps talent pipelines. Core supply concentrates in the United States, India, and Germany, with hyperscaler infrastructure anchoring cloud-based delivery and Bangalore-Hyderabad clusters feeding multinational implementation contracts. GPU accelerator hardware and specialized data engineering talent constitute critical input dependencies. Single-source vulnerability runs through NVIDIA's dominance in AI training silicon. Distribution runs through direct enterprise sales teams for licensed platforms and hyperscaler marketplaces for cloud-native solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where scarcity of data engineers capable of sub-second inference pipeline construction props pricing power for implementation services and MLOps tooling.
For Market Incumbents: Deepen vertical integration into specialized compliance infrastructure by acquiring CE-marking consultancies and FDA regulatory submission specialists. Fortify against emerging cloud-native challengers by embedding human-in-the-loop validation workflows as non-negotiable procurement prerequisites. Expand capacity in German and French regulatory technology clusters where EU AI Act audit protocol expertise concentrates.
For New Entrants and Emerging Players: Cloud-native API marketplaces offer the most penetrable route for specialized optimization engine providers lacking enterprise sales infrastructure. Target mid-market manufacturing segments in Japan and Germany where edge computing convergence demand outpaces incumbent platform customization cycles. Pursue outcome-guarantee contracting with performance-based pricing tied to measurable operational efficiency gains.
For Investors and Strategic Acquirers: FDA 510(k) clearance timelines for AI-enabled medical devices are the leading indicator that regulatory capacity will become the binding constraint on platform scalability. Five-to-ten year viability hinges on acquiring vendors with pre-built compliance documentation libraries and established conformity assessment relationships. Monitor EU MDR notified body backlogs as the signal for where regulatory arbitrage opportunities will emerge.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Compliance Infrastructure | CE-marking expertise and FDA submission capabilities accelerate market access for high-risk algorithmic systems. |
| Platform Integration with Hyperscaler Marketplaces | AWS Marketplace and Azure Marketplace listings reduce customer acquisition costs for cloud-native inference engines. |
| Strategic Partnership with Healthcare GPOs | Vizient and Premier contracts unlock procurement pathways for predictive patient outcome models. |
| Geographic Expansion into German Industrial Clusters | Bavarian automotive supply chains demand edge-based federated learning for proprietary data protection. |
| Product Launch of Outcome-Guarantee Contracts | Performance-based pricing with penalty clauses aligns vendor incentives with measurable efficiency gains. |
Research Methodology
Independent corroboration across platform engineering leads at hyperscaler cloud providers, healthcare CIOs managing FDA-regulated AI deployments, and procurement officers at Fortune 500 industrial conglomerates underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings of publicly traded analytics vendors, EU AI Act implementation guidance documents, and hospital GPO contract databases. Bottom-up sizing of individual use case deployments triangulates against top-down infrastructure spend estimates from hyperscaler capex disclosures.
Rate-of-change decomposition across the projection horizon segments expansion by deployment model, end-user industry vertical, solution type, and regulatory jurisdiction cluster. CAGRs derive from fitted growth curves calibrated to historical adoption patterns in comparable enterprise software categories. Model inputs include FDA medical device approval velocity, EU notified body capacity constraints, and cloud infrastructure pricing trajectories from hyperscaler earnings disclosures.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around healthcare segment estimates. Forecasts reflect documented assumptions regarding EU AI Act enforcement intensity and hyperscaler capacity expansion commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Graph Analytics Market
Analytics
Analytics of Things (Aot) Market
Analytics
App Analytics Tools Market
Analytics
Latin America Big Data Analytics Market
Analytics
Data Analysis Tools Market
Analytics
Cloud-Based Predictive Analytics Platform Market
Analytics
Video Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Augmented Analytics Market
Analytics
Augmented Analytics in BFSI Market
Analytics
Embedded Business Intelligence Market
Analytics
Learning Analytics Solution Market
Analytics
Network Analytics Services Market
Analytics
North America Crowd Analytics Market
Analytics
Patent Analytics Market
Analytics
Pandemic Analytics Market