
 Global Analytics Software Market | 2026-2036
Global Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Analytics Software Market Foresight
Open-source query engines are expanding their footprint in enterprise data stacks, displacing proprietary data warehouse appliances across mid-market and large accounts. Microsoft Corporation leverages its Azure cloud infrastructure to bundle analytics with compute workloads, sustaining pricing power through ecosystem lock-in. IBM Corporation anchors its competitive stance in regulated industries with governance-heavy AI platforms. Google differentiates through BigQuery's serverless architecture, dominating query performance benchmarks for petabyte-scale datasets.
Analytics software encompasses programs that ingest structured and semi-structured data, apply statistical algorithms and machine learning models, and render outputs through dashboards, APIs, or embedded decision systems. These platforms typically process data through distributed computing frameworks such as Apache Spark or proprietary columnar engines, enabling sub-second response times on billion-row datasets for commercial intelligence and operational automation. Cloud-based deployment leads solution type adoption as enterprises retire on-premises server farms, while predictive analytics captures the fastest expansion among solution categories due to its integration with generative AI pipelines. Business intelligence remains the most mature segment with compressed margins, whereas data mining tools command premium pricing in specialized verticals like pharmaceutical supply chains.
The EU AI Act imposes risk-tiered compliance obligations on analytics vendors deploying automated decision systems in European jurisdictions, while GDPR's data minimization principles constrain cross-border model training datasets. The US Federal Trade Commission scrutinizes analytics platforms for discriminatory algorithmic outputs under existing consumer protection statutes, and India's Digital Personal Data Protection Act establishes localization requirements affecting cloud-based predictive models. Stakeholders must monitor divergent sovereignty rules as they architect multi-region data fabrics and select deployment modes that satisfy overlapping compliance regimes without fragmenting analytical consistency.
Market Dynamics
The EU AI Act's risk-tiered compliance obligations are forcing analytics vendors to reengineer automated decision systems, while cloud migration mandates from GDPR data minimization principles accelerate infrastructure redesign across European deployments.
Growth Catalysts
- EU AI Act enforcement:Risk-classification requirements for automated decision systems are compelling enterprises to upgrade governance capabilities, creating replacement demand for compliant analytics platforms.
- Apache Spark adoption:Open-source distributed computing frameworks are displacing proprietary data warehouse appliances in mid-market accounts, lowering total cost of ownership for billion-row dataset processing.
- Financial services modernization:Predictive analytics integration with generative AI pipelines is accelerating platform procurement among investment banks and insurance carriers.
Market Restraints
- Cross-border data friction:GDPR's data minimization principles constrain model training datasets that span European and non-European jurisdictions, fragmenting analytical consistency.
- Cloud concentration risk:Three hyperscale providers dominate serverless query infrastructure, creating vendor lock-in and pricing power asymmetries for enterprise buyers.
- Skills scarcity:Shortage of engineers proficient in both statistical modeling and distributed systems architecture limits deployment velocity for complex implementations.
Strategic Opportunities
- India localization:The Digital Personal Data Protection Act establishes data residency requirements that favor domestic cloud infrastructure providers and local analytics vendors.
- Pharmaceutical supply chains:Data mining tools command premium pricing in specialized verticals requiring traceability across multi-tier supplier networks.
- Edge-to-cloud convergence:Integration of Apache Kafka stream processing with serverless query engines enables real-time operational automation for manufacturing and logistics.
Industry Challenges
- Multi-region compliance architecture:Engineering teams must satisfy overlapping sovereignty regimes without fragmenting model performance across EU, US, and Indian deployments.
- Legacy system integration:Enterprises retiring on-premises server farms face data migration complexity when connecting historical warehouse schemas to modern columnar engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Analytics Software Market |
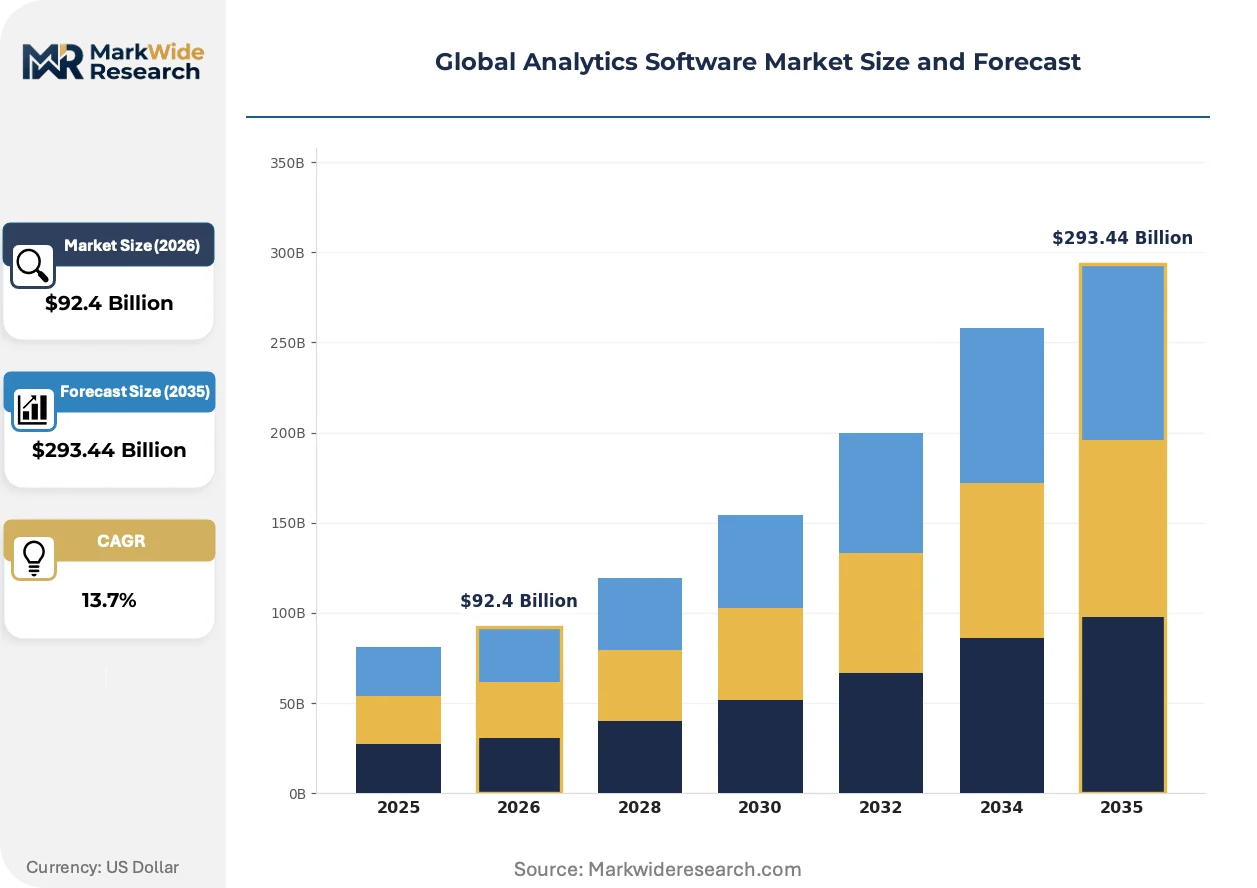
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $293.44 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Private Cloud Solution Type: Business Intelligence, Predictive Analytics, Data Visualization, Reporting Tools, Data Mining End User Industry: Telecommunications, Manufacturing, Energy & Utilities, Government, Transportation Pricing Model: Subscription, Perpetual License, Freemium, Pay-As-You-Go, Enterprise Agreement |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., Tableau Software, Amazon Web Services, Google, Alteryx Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Analytics Software Market Shifts & Advancements
Serverless query architectures and open-source engine maturation are compressing traditional business intelligence margins while elevating performance benchmarks for petabyte-scale workloads.
Apache Iceberg table formats are expanding into enterprise data lakes as the dominant open standard for time-travel queries and schema evolution. Mid-market technology companies and digital-native retailers are adopting Iceberg at the fastest pace, migrating from Hive-based systems within 18-month procurement cycles. This format standardization is expanding into vendor-agnostic interoperability, eroding proprietary warehouse lock-in and enabling multi-engine query portability across cloud providers.
The EU AI Act's automated decision system classifications impose documentation and human-in-the-loop requirements on high-risk deployments. Analytics vendors serving credit scoring, hiring, and healthcare triage applications must now maintain algorithmic impact assessments and audit trails. Financial services firms in Germany and France are responding by segregating European model training environments and appointing dedicated AI governance officers.
Consumption-based pricing models are displacing perpetual license structures in enterprise procurement. Buyers in the United States and India increasingly negotiate query-volume commitments rather than seat-based subscriptions, unbundling storage from compute costs. This shift is most visible among SaaS companies and e-commerce platforms with spiky analytical workloads, who prefer cost alignment with actual usage patterns over fixed infrastructure commitments.
Global Analytics Software Market Segmentation
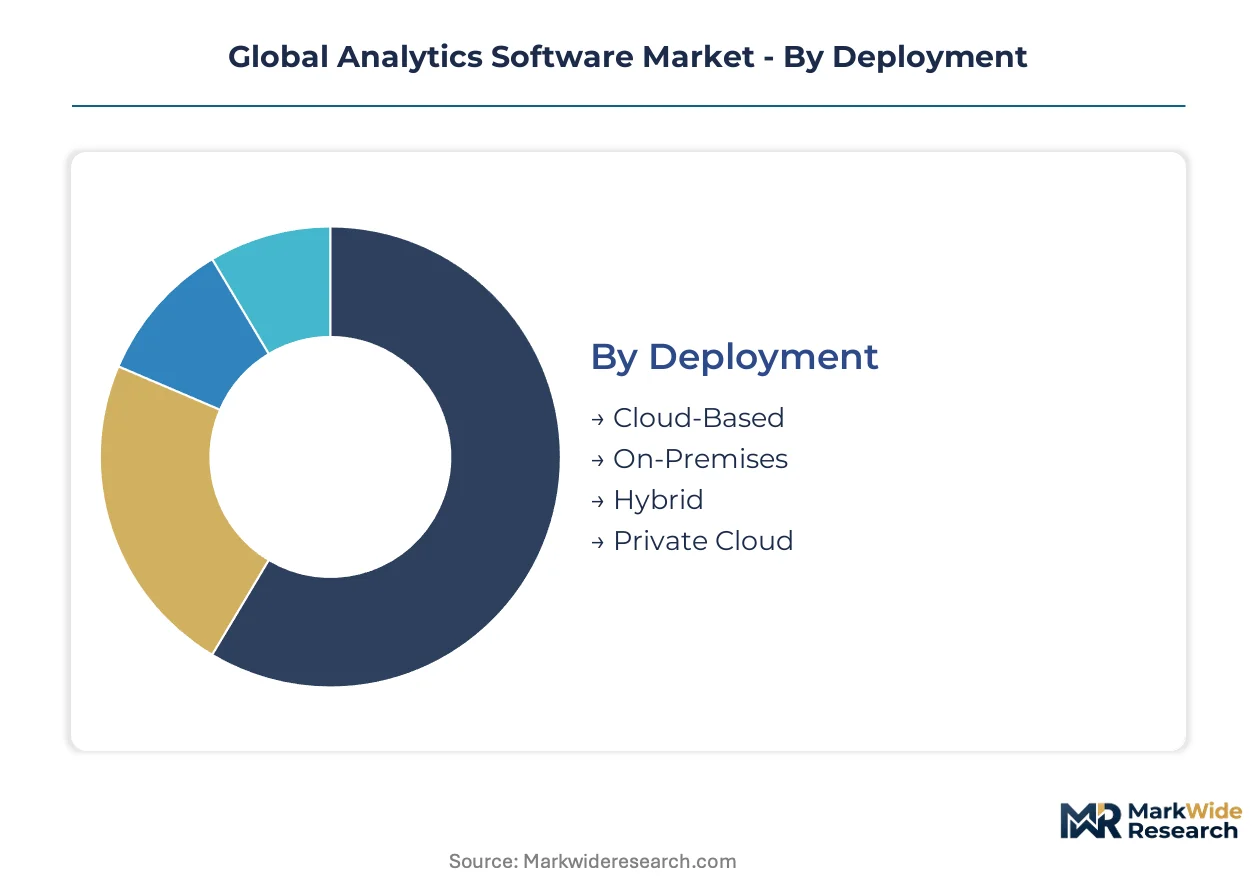
Segmentation reveals how procurement patterns diverge across infrastructure maturity levels and regulatory exposure. Upgrade cycles vary dramatically between cloud-native entrants and legacy-bound incumbents, creating distinct competitive battlegrounds within each dimension.
Deployment:
Replacement cycles accelerate where compliance mandates force infrastructure redesign, compressing traditional five-year hardware refresh timelines.
- Cloud-Based:Serverless architectures eliminate provisioning overhead for variable analytical workloads. Financial services firms in the United States and Germany dominate procurement as they retire on-premises server farms to satisfy GDPR data minimization requirements.
- Hybrid:Split-stack configurations partition sensitive training data on private nodes while pushing compute-intensive inference to public clouds. Energy utilities across India and Germany favor this model to balance RBI localization mandates against burst capacity needs.
- On-Premises:Sovereign data requirements in defense and classified government applications sustain demand for air-gapped installations.
- Private Cloud:Single-tenant virtualized stacks serve pharmaceutical manufacturers requiring validated environments for FDA submission workflows.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid.
Solution Type:
Margin structures invert as open-source engines commoditize mature categories while specialized tools capture pricing power in regulated verticals.
- Predictive Analytics:Machine learning pipelines integrated with generative AI backends enable automated decision systems for credit scoring and insurance underwriting. Investment banks in the United States and France accelerate procurement to comply with EU AI Act risk-tier documentation requirements.
- Data Mining:Multi-tier supplier traceability algorithms command premium pricing in pharmaceutical supply chains where batch recall visibility is mandatory. Swiss and German manufacturers drive demand for validated provenance tracking.
- Business Intelligence:Compressed margins characterize this mature segment as Apache Spark-based alternatives displace proprietary warehouse appliances.
- Data Visualization:Embedded dashboard components serve SaaS companies seeking white-label analytical interfaces without backend development.
- Reporting Tools:Scheduled distribution systems remain entrenched in government agencies with rigid procurement protocols.
Revenue concentrates in Business Intelligence; predictive capabilities are gaining share fastest.
End User Industry:
Application complexity determines deployment velocity, with sectors possessing legacy data architectures moving slowest despite analytical ambition.
- Manufacturing:Apache Kafka stream processing integrated with serverless query engines enables real-time defect detection and predictive maintenance. German automotive suppliers and Indian electronics contract manufacturers lead adoption of edge-to-cloud convergence architectures.
- Telecommunications:Network optimization algorithms processing subscriber behavior datasets at petabyte scale require columnar engine performance. US and Indian carriers invest heavily to manage 5G infrastructure capital allocation decisions.
- Energy & Utilities:Smart grid analytics demand hybrid deployments balancing SCADA security requirements against cloud scalability.
- Government:Procurement friction from certification requirements slows migration from legacy reporting systems.
- Transportation:Fleet routing optimization concentrates demand among logistics platforms with high-frequency location data streams.
Procurement volume concentrates in Telecommunications; Manufacturing shows the steepest expansion trajectory.
Pricing Model:
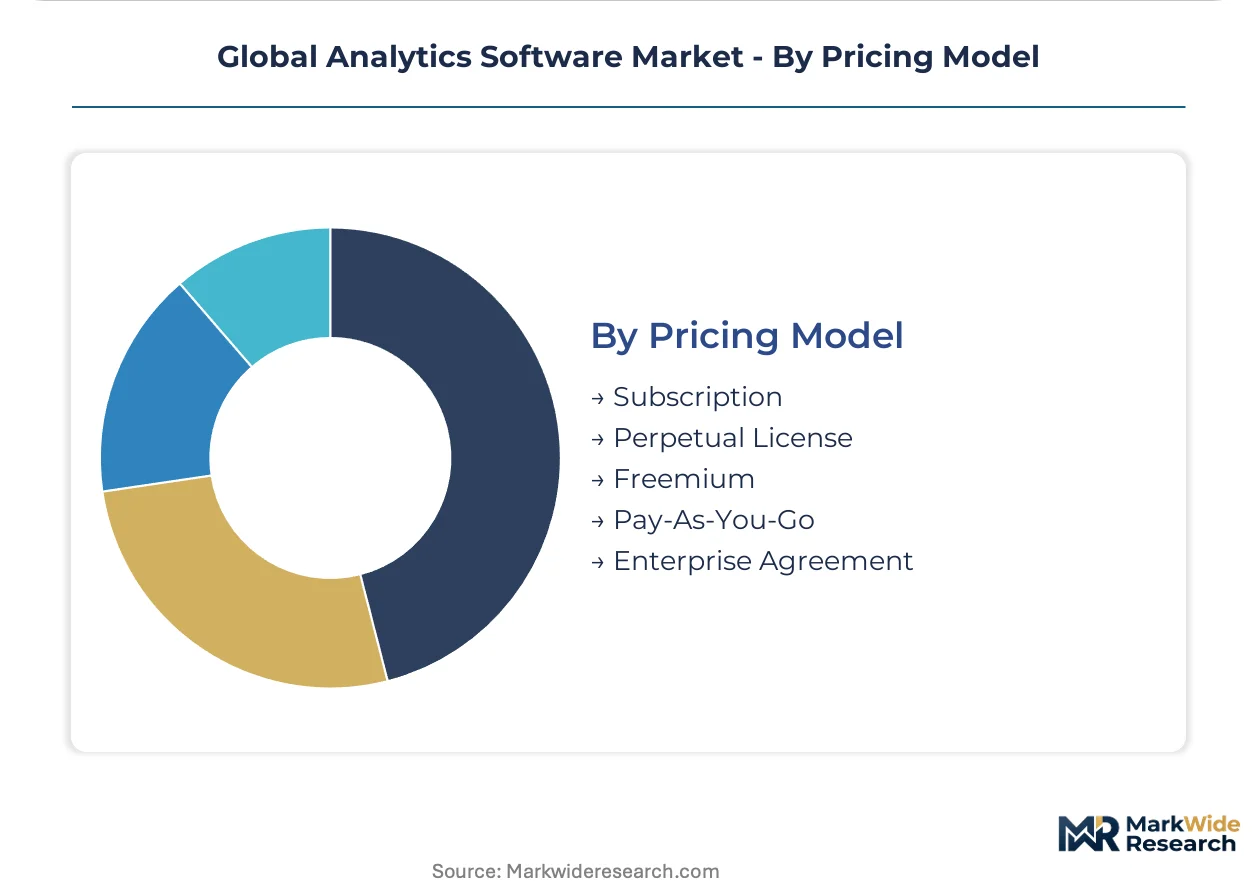
Customer scale and workload predictability determine model preference, with consumption alignment becoming the dominant negotiation lever.
- Pay-As-You-Go:Query-volume commitments align costs with actual usage patterns for SaaS companies and e-commerce platforms with spiky analytical workloads. Digital-native retailers in the United States and India negotiate this structure to avoid fixed infrastructure commitments during growth phases.
- Enterprise Agreement:Multi-year bundled contracts spanning storage, compute, and support services suit multinational corporations standardizing on single-vendor ecosystems. German and US manufacturing conglomerates favor this predictability for capital planning.
- Subscription:Seat-based recurring revenue persists in mid-market accounts with stable user populations.
- Perpetual License:Declining share reflects cloud migration trends, though government buyers retain preference for capital expenditure treatment.
- Freemium:Tiered entry points convert individual analysts and small teams to paid tiers through usage threshold triggers.
Contract value concentrates in Enterprise Agreement; Pay-As-You-Go is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in the United States, Germany, and India as enterprises modernize data architectures and navigate divergent sovereignty regimes.
United States
Financial services firms and SaaS companies drive cloud-based analytics procurement. FTC scrutiny of algorithmic discrimination under consumer protection statutes shapes vendor compliance investments. New York and San Francisco clusters host the densest concentrations of predictive analytics deployments for credit scoring and fraud detection.
Germany
Automotive suppliers and industrial manufacturers demand edge-to-cloud convergence architectures. EU AI Act risk-tier classifications compel enterprises to appoint dedicated AI governance officers. Munich and Stuttgart engineering clusters lead adoption of Apache Kafka stream processing for real-time defect detection.
India
Telecommunications carriers and electronics contract manufacturers accelerate platform procurement. The Digital Personal Data Protection Act establishes data residency requirements favoring domestic cloud infrastructure. Bangalore and Hyderabad technology corridors concentrate generative AI pipeline integrations for customer analytics.
United Kingdom
Investment banks and insurance carriers upgrade governance capabilities for automated underwriting systems. GDPR data minimization principles constrain cross-border model training datasets. London financial services clusters segregate European model training environments to satisfy documentation requirements.
France
Healthcare triage applications and hiring platforms face heightened documentation obligations under EU AI Act enforcement. ANSM and CNIL oversight shapes algorithmic impact assessment protocols. Paris pharmaceutical clusters demand validated provenance tracking for multi-tier supplier networks.
Global Analytics Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing serverless query infrastructure while open-source engines erode proprietary warehouse lock-in. The vendor base organizes around three strategic archetypes: ecosystem bundlers leveraging cloud infrastructure for pricing power, governance-heavy platforms serving regulated industries, and serverless specialists dominating petabyte-scale performance benchmarks. Competitive moves concentrate on M&A for AI governance capabilities and strategic partnerships for multi-engine query portability.
Within the ecosystem bundler tier, Microsoft Corporation and Amazon Web Services exemplify players leveraging cloud infrastructure to sustain pricing power through compute workload integration. IBM Corporation occupies a position among governance-heavy platforms anchoring competitive stance in regulated verticals. These three entities represent the dominant competitive anchors as enterprises negotiate between vendor lock-in risks and compliance requirements.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| Tableau Software |
| Amazon Web Services |
| Alteryx Inc. |
| Others |
Supply & Pricing Matrix
Performance-tier bifurcation between serverless query engines and legacy warehouse appliances manifests in divergent margin structures and sourcing strategies across enterprise procurement. Premium deployments draw from hyperscale cloud infrastructure with consumption-based metering, while commodity tiers source from open-source Apache Spark distributions and domestic cloud providers in India and Germany.
Pricing Analysis
Volume concentrates in consumption-based SaaS tiers while margins accrue to specialized data mining tools with validated provenance tracking. Price differentiation hinges on query performance benchmarks and EU AI Act compliance certification levels. Pricing pressure stems from Apache Spark commoditization displacing proprietary appliances in mid-market accounts. SaaS companies and digital-native retailers exhibit highest price sensitivity; pharmaceutical manufacturers and financial services firms show lowest.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate supplier eligibility for enterprise and government contracts, filtering vendor pools before commercial negotiation. Software development concentrates in the United States, India, and Germany, with cloud infrastructure provisioning anchored in hyperscale data centers across these jurisdictions. The supply chain draws from specialized machine learning engineering talent, GPU compute clusters, and open-source distributed computing frameworks. Single-source vulnerability persists where three hyperscale providers dominate serverless query infrastructure. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-tier documentation requirements erect compliance moats that favor incumbents with established governance infrastructure and dedicated AI ethics offices.
For Market Incumbents: Extend platform integration depth through embedded Apache Iceberg support and multi-engine query portability to neutralize vendor lock-in objections. Defensive moves should concentrate on acquiring AI governance specialists and pre-certifying automated decision system modules for high-risk deployment categories. Threat from open-source query engines commoditizing business intelligence margins demands accelerated migration of installed bases to consumption-based pricing structures. For New Entrants and Emerging Players: Domestic cloud infrastructure providers in India offer channel partnership pathways around data residency mandates under the Digital Personal Data Protection Act. White-space targets include pharmaceutical supply chain provenance tracking and edge-to-cloud convergence architectures for German automotive suppliers. Go-to-market positioning should emphasize EU AI Act readiness documentation and segregated European training environments. For Investors and Strategic Acquirers: Re-rating potential sits with governance-heavy platform specialists given enforcement acceleration of algorithmic impact assessment requirements across European jurisdictions. Long-term viability favors vendors with validated compliance frameworks and recurring revenue concentration in regulated verticals. Signal to watch is appointment velocity of dedicated AI governance officers at Fortune 500 enterprises as inflection indicator for platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Apache Iceberg adoption enables multi-engine query portability across hyperscale cloud providers. |
| Acquisition of Specialist Firm | AI governance capabilities address EU AI Act documentation requirements for automated decision systems. |
| Geographic Expansion | India data center buildouts satisfy Digital Personal Data Protection Act localization mandates. |
| Strategic Partnership | Systems integrator alliances accelerate enterprise deployment velocity for complex hybrid configurations. |
| Product Launch | Serverless query engines with consumption-based metering align pricing with spiky analytical workloads. |
Research Methodology
Document review covered SEC filings from hyperscale cloud providers, EU regulatory guidance documents, and Indian Digital Personal Data Protection Act implementation circulars, complemented by interviews with CTOs at financial services firms, IT procurement officers at pharmaceutical manufacturers, platform engineers at telecommunications carriers, and integration specialists at systems integrators. Secondary validation drew from Apache Software Foundation release documentation, hyperscaler capex disclosures, and customs data on enterprise software imports. Bottom-up deployment estimates triangulated against top-down market sizing from infrastructure spending projections.
Model outputs span value and volume across deployment mode, solution type, end-user industry, organization size, and regional adoption pattern throughout the forecast period. CAGRs derive from regression analysis against historical infrastructure replacement cycles and compliance-driven upgrade timelines. Industry-specific inputs include EU AI Act enforcement schedules, GDPR data minimization audit frequencies, and open-source engine maturation benchmarks.
Caveats apply where EU AI Act implementation delays, hyperscale pricing adjustments, or open-source engine performance breakthroughs could materially shift the outlook. Forecasts reflect assumptions on regulatory enforcement consistency and enterprise cloud migration velocity. A model refresh is warranted upon material change in EU AI Act penalty structures or major open-source query engine release milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Germany Geospatial Analytics Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Europe Crowd Analytics Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
Contact Center Analytics Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
India Big Data Analytics Market
Analytics
North America Crowd Analytics Market
Analytics
Speech Analytics Market
Analytics
Global Data Prep Market
Analytics
Mobile App Attribution Tool Market
Analytics
Business Intelligence (BI) Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Web Analytics Market
Analytics
Supply Chain Analytics Market
Analytics
Cyprus ICT Market